
 Europe RFID Market | 2026-2036
Europe RFID Market Size, Share, and Industry Trends Forecast 2026-2036
Europe RFID Market Intelligence
The emergence of asset-light, subscription-based 'RFID-as-a-Service' models is reshaping competitive positioning by lowering upfront capital expenditure for end-users. Zebra Technologies Corporation leverages its extensive hardware portfolio to offer integrated solutions within these models. NXP Semiconductors specializes in the underlying chip technology, supplying critical components to a wide array of system integrators. Datalogic S.p.A. competes by focusing on ruggedized readers and mobile computers for industrial environments in Italy and Germany.
Radio-Frequency Identification (RFID) systems use electromagnetic fields to automatically identify and track tags attached to objects. These systems operate across various frequencies, with Ultra High Frequency (UHF) systems offering long read ranges essential for commercial logistics. Passive Tags, which are powered by the reader's radio waves, dominate the market due to their low cost and simplicity for large-scale deployments. Supply Chain Management and Asset Tracking applications represent the largest segments, driven by efficiency gains in logistics and manufacturing.
Compliance with the European Union's GDPR is critical when RFID tags are associated with personal data, impacting retail and healthcare applications. All electronic reader components must adhere to CE marking requirements, while tag materials fall under the purview of the REACH regulation. Future investment decisions will hinge on the standardization of data protocols across disparate systems to enable seamless interoperability within pan-European supply chains.
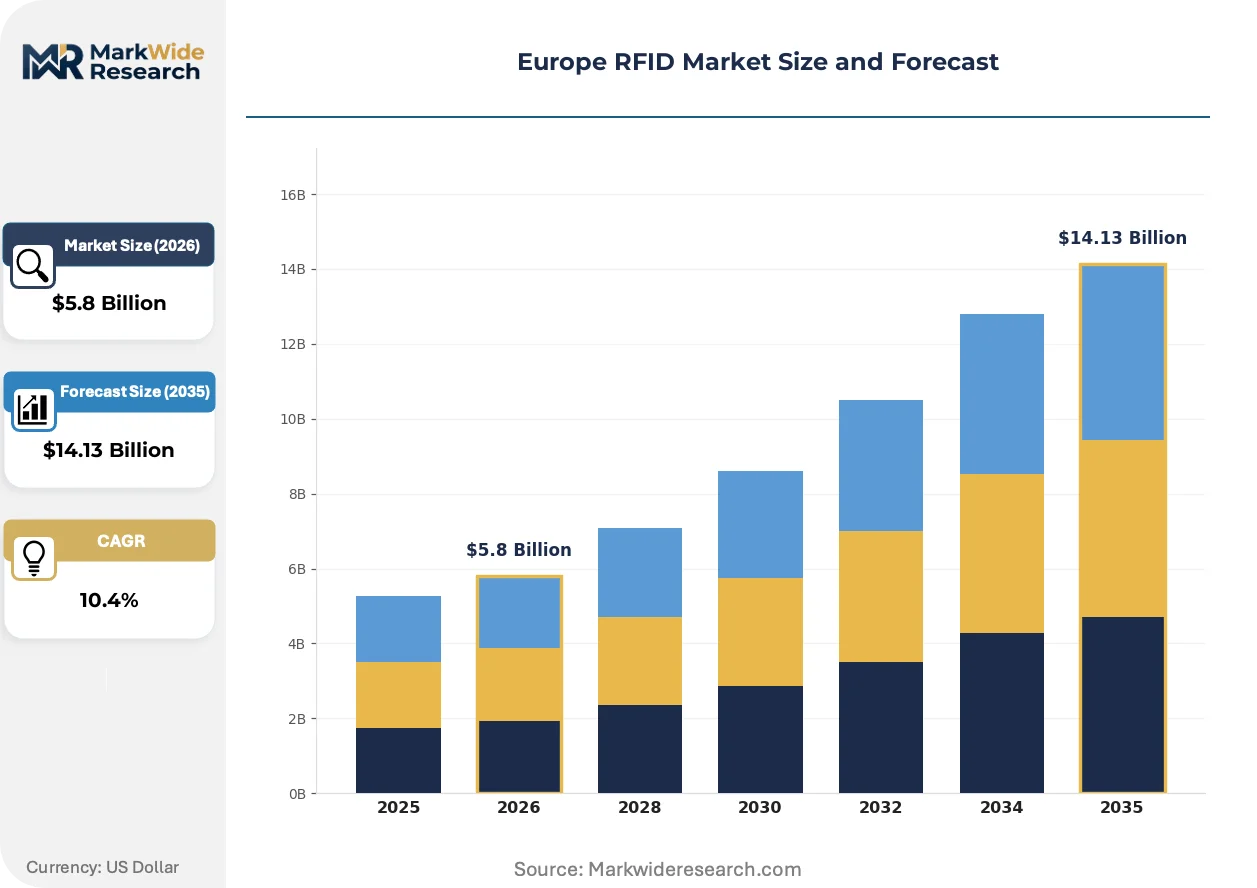
Market Dynamics
The imperative for enhanced supply chain visibility, driven by European Union regulations like the Corporate Sustainability Reporting Directive (CSRD), is the central force shaping the RFID market. This pressure moves adoption beyond retail inventory management into complex industrial and logistical ecosystems.
Growth Catalysts
- Regulatory Mandates:The EU's CSRD and proposed digital product passports compel businesses to adopt technologies like RFID for granular, verifiable traceability of goods from origin to end-of-life, particularly in textiles and electronics.
- Industrial Automation:Germany's advanced manufacturing sector leverages UHF RFID systems to automate production lines, track work-in-progress, and manage tool cribs, aligning with Industry 4.0 objectives for smart factories.
- Cost-Effective Tagging:The declining unit cost of passive RFID tags enables mass deployment in sectors like logistics and fast-moving consumer goods, making item-level tracking economically feasible for improving inventory accuracy and reducing waste.
Market Restraints
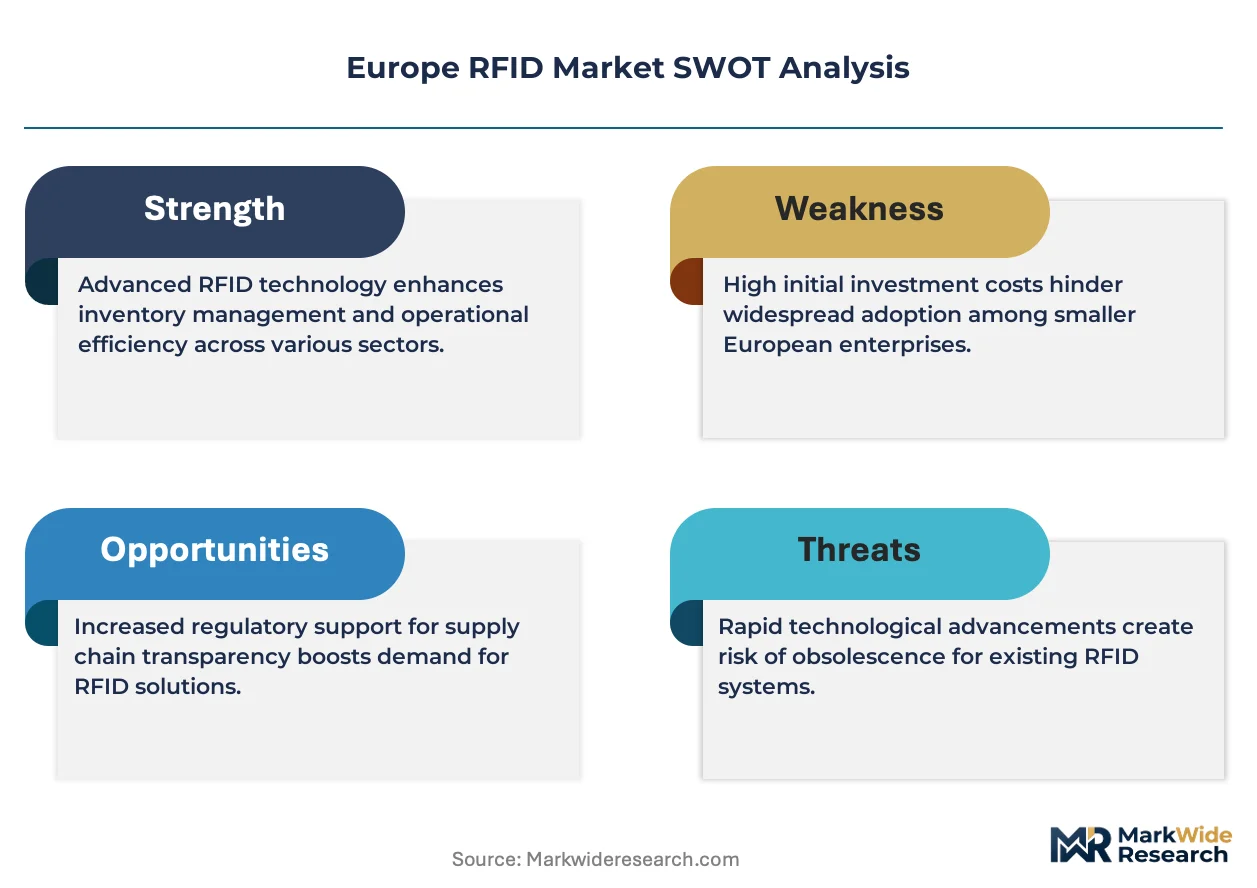
- High Implementation Costs:The substantial upfront investment required for RFID readers, antennas, middleware, and system integration presents a significant barrier for small and medium-sized enterprises (SMEs) across Europe.
- Technical Limitations:Performance of RFID systems can be compromised by signal absorption or reflection in environments with high metal or liquid content, posing a persistent challenge for applications in food and beverage processing and automotive manufacturing.
- Data Privacy Compliance:The use of RFID in consumer-facing applications must adhere to the strict requirements of the General Data Protection Regulation (GDPR), adding complexity and legal risk, especially in retail and healthcare.
Strategic Opportunities
- Emerging Applications in Circular Economy:RFID technology can enable product-as-a-service models and facilitate sorting for recycling by embedding lifecycle data in tags, aligning with the EU Green Deal objectives.
- Expansion into Eastern Europe:The modernization of logistics and warehousing infrastructure in countries like Poland and Romania creates significant opportunities for deploying RFID systems to enhance efficiency in these growing hubs.
- Integration with Blockchain:Combining RFID for physical asset identification with blockchain for an immutable digital ledger offers a powerful solution for combating counterfeiting in high-value sectors like pharmaceuticals and luxury goods.
Industry Challenges
- Interoperability Standards:A lack of universally adopted data and communication standards among different RFID hardware and software vendors complicates the creation of seamless, interoperable tracking systems across pan-European supply chains.
- Legacy System Integration:Integrating RFID data streams with existing enterprise resource planning (ERP) and warehouse management systems (WMS) is often complex and costly, requiring specialized middleware and significant IT resources.
- RF Engineering Skill Gaps:A shortage of technicians and engineers with specialized knowledge in radio frequency physics, antenna placement, and system optimization hinders the effective deployment and maintenance of robust RFID solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe RFID Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $14.13 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Tags, Active Tags, Semi-passive Tags, NFC Tags, Sensor Tags Technology: Low Frequency, High Frequency, Ultra High Frequency, Microwave Application: Supply Chain Management, Asset Tracking, Inventory Control, Product Authentication, Livestock Management End User: Retail Chains, Logistics Providers, Manufacturing Facilities, Agricultural Enterprises, Libraries |
| Companies Covered | Zebra Technologies Corporation, Honeywell International, NXP Semiconductors, Avery Dennison Corporation, Impinj, Alien Technology Corporation, Datalogic S.p.A., HID Global Corporation, Checkpoint Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe RFID Market Strategic Shifts & Innovations
A fundamental shift from component sales to integrated, data-centric services defines the market's evolution. This transition prioritizes software and analytics to unlock the value captured by RFID hardware, moving the competitive focus from simple tracking to actionable business intelligence.
Sensor-enabled RFID tags provide the ability to monitor environmental conditions such as temperature, humidity, and shock in addition to identification. Cold chain logistics and pharmaceutical distributors are rapidly adopting these active or semi-passive tags to ensure regulatory compliance and product integrity during transit. This technology is virtualizing the physical asset by creating a dynamic digital record of its journey and condition, not just its location.
The European Union's push for a circular economy is creating new use cases for RFID technology. Directives related to waste management and extended producer responsibility encourage manufacturers to embed RFID tags in products like electronics and batteries. This allows for automated sorting at recycling facilities and provides lifecycle data that supports repair and remanufacturing, directly impacting the consumer electronics and automotive sectors.
Subscription-based 'RFID-as-a-Service' (RaaS) models are altering how end-users acquire and deploy this technology. This opex-based model bundles hardware, software, and support into a single recurring fee, eliminating the large initial capital investment that has historically been a barrier. The model is gaining significant traction in the retail and logistics sectors in Western Europe, especially among businesses seeking scalability and predictable costs.
Europe RFID Market Segmentation
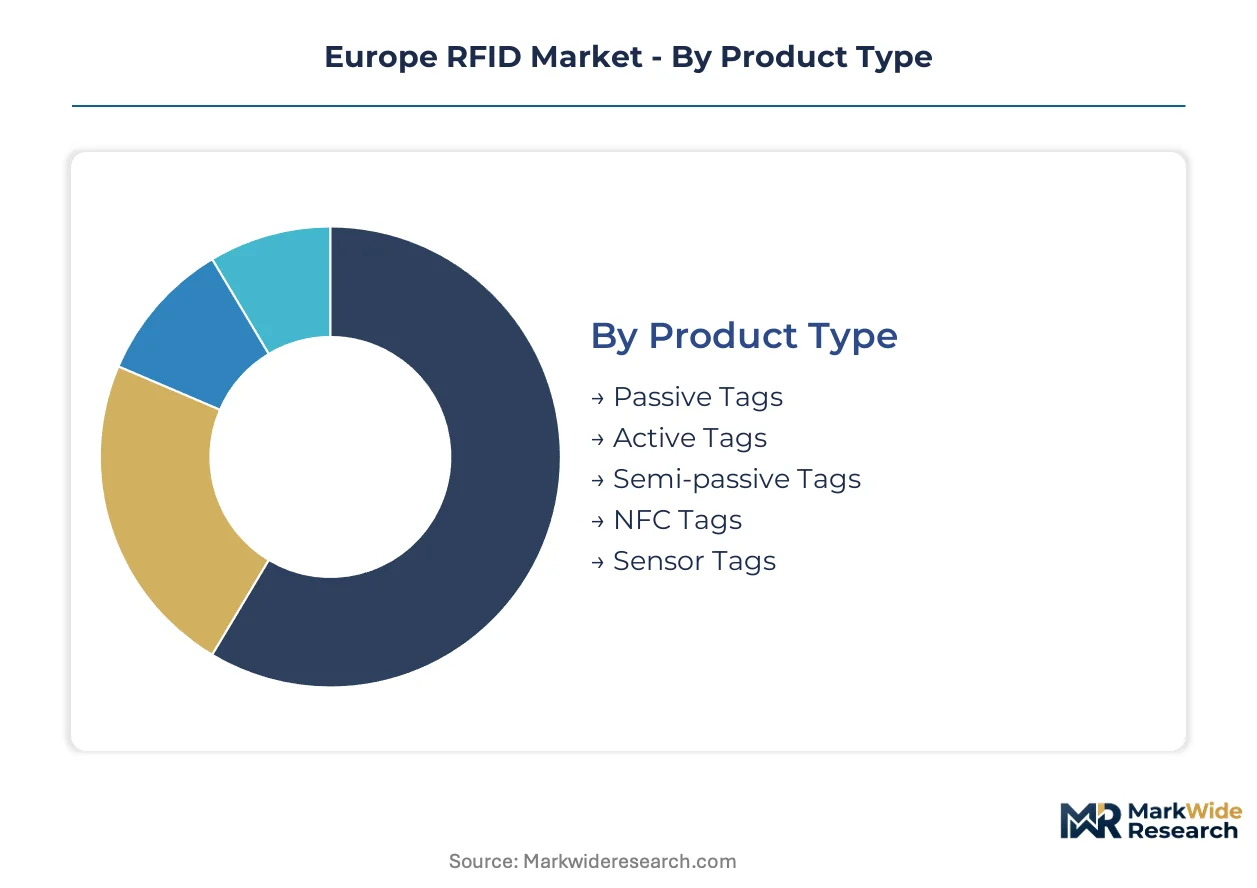
The Europe RFID market exhibits diverse needs across its industrial and commercial landscapes, necessitating a granular understanding of specific product types, underlying technologies, varied applications, and distinct end-user requirements. This segmentation illuminates the critical areas of investment and innovation driving market expansion across European economies.
Product Type:
The after-sales service intensity for RFID products varies significantly, reflecting the complexity and operational demands of different tag types.
- Passive Tags:These tags draw power from the reader's radio waves, offering a cost-effective and simple solution for large-scale deployments. Demand concentrates in European logistics and retail sectors for item-level inventory accuracy and supply chain visibility.
- Sensor Tags:Integrating environmental sensing capabilities, these advanced tags monitor conditions like temperature, humidity, or shock in addition to identification. European cold chain logistics and pharmaceutical distributors are rapidly adopting them for regulatory compliance and product integrity during transit.
- Active Tags:Equipped with their own power source, active tags provide longer read ranges and enhanced data transmission capabilities. These are typically deployed for high-value asset tracking in industrial environments across Germany.
- Semi-passive Tags:Combining battery power for enhanced performance with reader-powered communication, these tags offer a balance of range and cost-efficiency. They find use in specialized applications requiring more robust data capture than passive tags.
- NFC Tags:Near Field Communication tags enable short-range, secure data exchange, primarily interacting with mobile devices. European retail and smart packaging initiatives leverage NFC for consumer engagement and product information access.
Passive Tags holds the largest share; momentum sits with Sensor Tags.
Technology:
RFID technologies are differentiated by their operational frequencies, which dictate their suitability for distinct application environments.
- Ultra High Frequency:UHF systems offer long read ranges and high data transfer rates, essential for efficiently tracking large volumes of goods across wide areas. Commercial logistics and manufacturing facilities in Europe heavily rely on UHF for comprehensive supply chain visibility.
- High Frequency:HF systems operate at shorter ranges but perform robustly in environments with metal or liquid content, often supporting secure data transactions. European access control systems, payment solutions, and library management extensively utilize HF technology.
- Low Frequency:LF systems provide very short read ranges and are less susceptible to interference from metal or liquid, making them suitable for specific identification tasks. Livestock management and access control for harsh industrial settings in Europe frequently employ LF RFID.
- Microwave:Operating at even higher frequencies than UHF, microwave RFID offers specialized long-range identification capabilities, often in niche industrial applications. These systems are used for specific vehicle tracking and toll collection in certain European regions.
Ultra High Frequency systems drive market growth, while High Frequency maintains a steady presence in specialized applications.
Application:
The deployment of RFID technology across various applications directly correlates with the efficiency gains and operational visibility it provides.
- Supply Chain Management:This application enhances end-to-end visibility of goods, optimizing logistics and reducing operational inefficiencies across pan-European networks. The EU's Corporate Sustainability Reporting Directive (CSRD) specifically drives adoption for verifiable traceability.
- Asset Tracking:RFID enables precise monitoring and location of high-value equipment, tools, and returnable transport items within manufacturing facilities and large enterprises. Germany's advanced manufacturing sector extensively leverages asset tracking for Industry 4.0 objectives.
- Inventory Control:RFID automates stock counts and improves inventory accuracy, significantly reducing manual labor and errors in retail and warehousing. European retail chains use RFID to optimize stock levels and enhance omnichannel fulfillment.
- Product Authentication:RFID tags embedded in products help combat counterfeiting by providing unique, verifiable identities for items. This application is particularly crucial for high-value sectors like pharmaceuticals and luxury goods across Europe.
- Livestock Management:RFID provides individual animal identification and tracking, supporting health monitoring, breeding programs, and regulatory compliance in agricultural enterprises. This ensures traceability of animal products within the European food supply chain.
Supply Chain Management and Asset Tracking collectively represent the largest segments, with Product Authentication gaining share fastest.
End User:
Different end-user segments adopt RFID technology based on their unique operational imperatives and regulatory compliance needs.
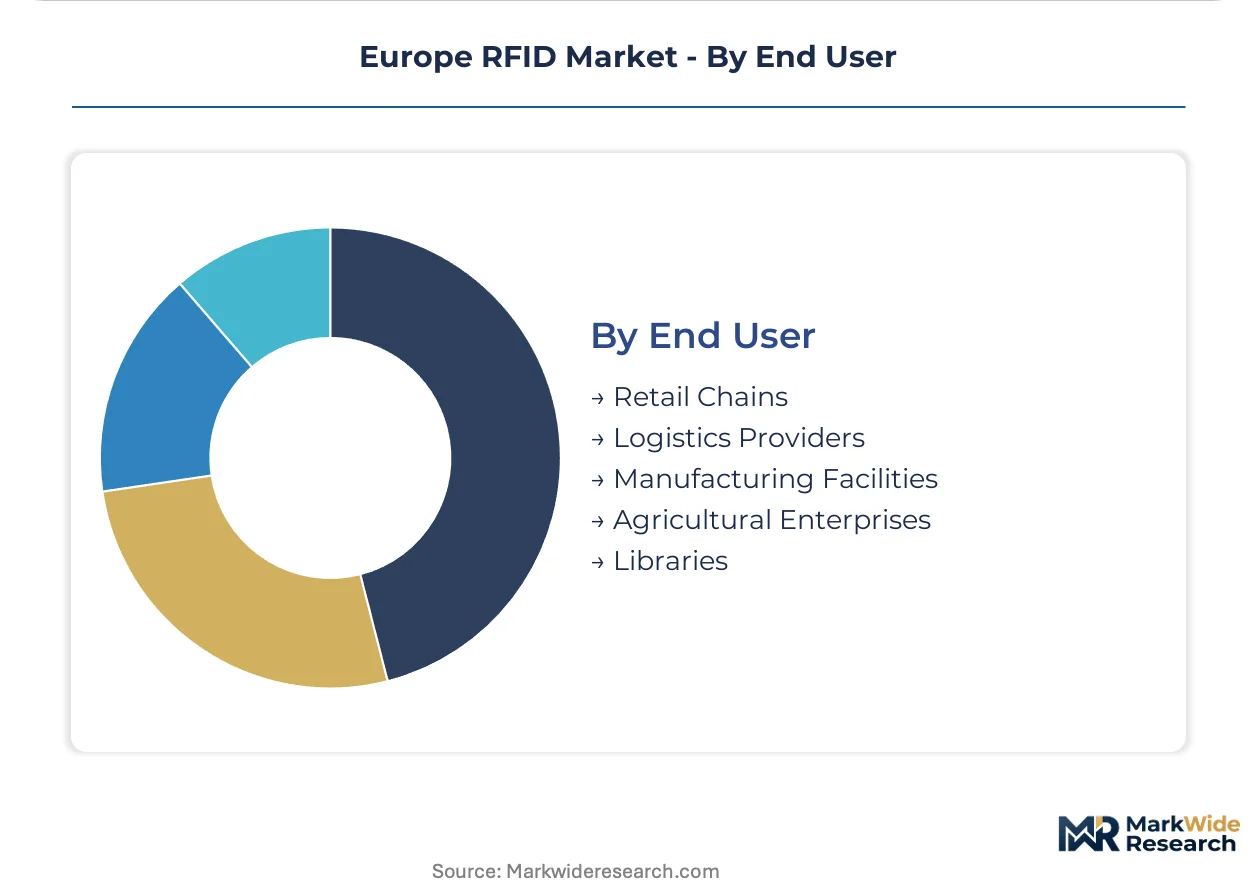
- Retail Chains:European retail chains deploy RFID to achieve near-perfect inventory accuracy, reduce stockouts, and streamline omnichannel operations. This enhances customer experience and operational efficiency across stores in Western Europe.
- Logistics Providers:These entities utilize RFID to optimize warehouse management, track shipments, and improve the efficiency of their distribution networks across Europe. Expansion into Eastern European logistics hubs creates significant deployment opportunities.
- Manufacturing Facilities:RFID systems automate production lines, track work-in-progress, and manage tool cribs within advanced manufacturing environments. Germany's industrial sector is a key adopter for its smart factory initiatives.
- Agricultural Enterprises:Farmers and agricultural businesses use RFID for livestock identification, crop traceability, and equipment management. This supports compliance with EU agricultural regulations and enhances operational oversight.
- Libraries:RFID technology streamlines book check-out, returns, and inventory management, significantly improving operational efficiency and user experience. European public and academic libraries have widely adopted these systems.
Retail Chains and Manufacturing Facilities are the primary adopters, while Logistics Providers exhibit significant expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Europe RFID market sees demand concentrating among large industrial enterprises and retail chains. These entities prioritize scalable solutions for inventory accuracy and supply chain visibility. Regulatory drivers like the CSRD further compel investment across diverse European economies.
Germany
Germany's robust advanced manufacturing and logistics sectors drive substantial RFID demand for industrial automation. The EU's CSRD mandates enhanced supply chain traceability across German enterprises. Industrial hubs in Bavaria are leveraging UHF RFID systems to optimize work-in-progress tracking and tool management.
United Kingdom
The United Kingdom's dynamic retail and e-commerce sectors increasingly adopt RFID for efficient inventory control and omnichannel fulfillment. Compliance with GDPR remains critical for consumer-facing RFID applications in the UK. London's numerous retail innovation centers are pioneering RFID solutions to enhance customer experience and operational efficiency.
France
France exhibits strong RFID adoption in luxury goods and pharmaceutical sectors, seeking enhanced product authentication and supply chain integrity. The EU Green Deal objectives encourage RFID integration for circular economy initiatives across French industries. Paris-based luxury fashion houses are increasingly embedding RFID tags to combat counterfeiting and track high-value items.
Poland
Poland's rapidly modernizing logistics and warehousing infrastructure presents significant opportunities for RFID system deployment. All electronic reader components must adhere to CE marking requirements for market entry in Poland. Warsaw's expanding logistics parks are actively implementing RFID solutions to enhance efficiency in cross-border distribution networks.
Italy
Italy's fashion, automotive, and specialized industrial manufacturing sectors drive RFID demand for asset tracking and inventory control. The REACH regulation is crucial for compliance regarding tag materials used by Italian producers. Milan's renowned fashion and design industry employs RFID technology to manage inventory and protect brand authenticity.
Europe RFID Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic market structure across Europe. The RFID market features a mix of established hardware manufacturers offering comprehensive systems and agile software-centric solution providers. Strategic archetypes include integrated solution providers, component specialists, and niche application developers. Companies are pursuing strategic partnerships and portfolio diversification to capture market share and enhance their competitive positioning.
Integrated solution providers like Zebra Technologies Corporation exemplify the trend towards comprehensive hardware and software offerings, leveraging extensive portfolios to deliver complete systems. NXP Semiconductors anchors the market's component specialization, supplying critical chip technology to a wide array of system integrators across the value chain. Datalogic S.p.A. occupies a position among specialized hardware manufacturers, focusing on ruggedized readers and mobile computers tailored for demanding industrial environments, particularly in key markets such as Italy and Germany. These players collectively shape the competitive landscape by addressing different facets of RFID deployment.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International |
| NXP Semiconductors |
| Avery Dennison Corporation |
| Impinj |
| Alien Technology Corporation |
| Datalogic S.p.A. |
| HID Global Corporation |
| Checkpoint Systems |
Cost & Logistics Intelligence
Single-source dependency on specialized chip manufacturers creates distinct pricing tiers and influences regional supply chain configurations in the Europe RFID market. This structural dynamic affects both the cost of advanced RFID solutions and the availability of critical components for system integrators.
Pricing Analysis
Cost-plus contract patterns with named indexation to semiconductor raw materials define a significant portion of RFID system pricing. The dominant pricing structure is evolving towards a hybrid model, combining project-based implementations for large enterprises with subscription-based 'RFID-as-a-Service' (RaaS) offerings. Price differentiation stems from customization levels for specific industrial applications and the extent of bundled after-sales support. Pricing softness emerges from the increasing availability of low-cost passive tags, driven by mass production. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity, while large industrial enterprises prioritize performance and integration over initial cost.
Supply Chain Analysis
Export-control regimes impacting advanced semiconductor components limit the free flow of critical RFID technology across certain geographies. Geographic supply concentration for core RFID components centers on East Asia for chip fabrication and the Netherlands for specialized design (NXP Semiconductors). Raw material dependencies include silicon wafers for integrated circuits, specialized polymers for tag substrates, and various metals for antenna construction. Single-source vulnerability for specific high-performance chip designs represents a significant supply chain risk. Downstream distribution primarily occurs through a network of system integrators, value-added resellers, and direct sales channels to large end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe RFID market is undergoing a high-growth disruption, driven by the EU's Corporate Sustainability Reporting Directive compelling enhanced traceability across supply chains.
For Market Incumbents:Pre-empt fragmentation by acquiring niche software analytics firms that specialize in RFID data interpretation and integration with existing enterprise systems. This strategy mitigates the threat from agile, software-centric solution providers entering the market with RaaS models. Invest heavily in research and development for AI-powered analytics platforms that derive actionable business intelligence from RFID data streams. Focus on building comprehensive, end-to-end solutions that offer seamless interoperability across diverse European supply chains.
For New Entrants and Emerging Players:Pursue underpenetrated segments like Eastern European logistics providers and small-to-medium enterprises (SMEs) with flexible, subscription-based RFID-as-a-Service models. This approach lowers upfront capital expenditure barriers for end-users, making advanced RFID technology accessible. Target specific vertical applications such as product authentication in high-value goods or circular economy initiatives where regulatory mandates create immediate demand. A go-to-market angle emphasizing rapid deployment, scalability, and predictable operational costs will resonate strongly with these segments.
For Investors and Strategic Acquirers:The Corporate Sustainability Reporting Directive (CSRD) reshapes the acquisition landscape, favoring companies that enable verifiable, end-to-end supply chain traceability. Long-term viability for RFID technology is robust, supported by ongoing regulatory tailwinds and the imperative for industrial automation over the next 5-10 years. Target acquisition archetypes include specialized sensor tag manufacturers, middleware developers, and software firms proficient in integrating RFID data with blockchain solutions. The signal to watch is the increasing corporate reporting on Scope 3 emissions, which will directly drive demand for granular asset tracking.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand RFID-as-a-Service (RaaS) Offerings | Lowers entry barriers for SMEs, accelerating market adoption across Europe. |
| Invest in Sensor Tag R&D | Enables real-time condition monitoring for cold chain logistics and pharmaceuticals. |
| Form Blockchain Partnerships | Enhances data immutability and combats counterfeiting in high-value sectors. |
| Acquire Middleware Specialists | Simplifies integration of RFID data with legacy ERP and WMS systems. |
| Target Eastern European Logistics | Captures growth from modernizing infrastructure and expanding distribution networks. |
Research Approach
Desk research of EU regulatory documents, industry association reports, and technology journals preceded structured interviews with RFID system integrators, supply chain managers, retail operations directors, and manufacturing automation engineers. This primary and secondary research provided qualitative insights into market dynamics and quantitative validation of market sizing. Bottom-up and top-down triangulation methods were applied to ensure data consistency and accuracy across various market segments.
Assumptions regarding consistent regulatory enforcement and stable geopolitical conditions were held fixed across the analysis window, while technological adoption rates and component cost trends were varied. The analytical framework modeled market growth based on segmentation dimensions including product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates (CAGRs) were derived from historical growth patterns and projected drivers such as the declining unit cost of passive tags and CSRD compliance deadlines.
Sensitivities concentrate around geopolitical disruptions impacting semiconductor supply chains and unforeseen changes in EU regulatory enforcement timelines. Forecasts reflect these underlying assumptions, acknowledging their potential to influence market trajectory. Material shifts in these macro-environmental factors would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Lidar in Construction Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Fixed RFID Readers Market
Sensors
Personal Navigation Devices Market
Sensors
Digital Direction Finder Market
Sensors
Facial Tracking Solution Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Vision Positioning System Market
Sensors
Body Area Network Market
Sensors
Smart Mat Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Vibration Monitoring Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Ultrasonic Technologies Market