
 Barley Grass Market | 2026-2036
Barley Grass Market Size, Share, and Industry Trends Forecast 2026-2036
Barley Grass Market Analysis
USDA Organic certification is collapsing the window for uncredentialed suppliers, forcing smaller cultivators toward third-party validation or contract manufacturing. Green Foods Corporation leverages its long-standing organic supply chain to sustain bulk powder leadership across North American health food stores. NOW Foods competes on manufacturing scale, operating multiple GMP-certified facilities that anchor its private-label and branded capsule lines. NZ Nutritionals differentiates through geographic dominance, controlling premium New Zealand-sourced raw material that commands shelf space in specialty retail.
Barley grass comprises the young leaf blades of Hordeum vulgare, harvested before jointing when chlorophyll concentration peaks at approximately 3-5% dry weight and the plant retains bioactive enzymes, vitamins, and minerals. The primary commercial purpose centers on delivering concentrated phytonutrient inputs for human consumption and topical formulations. Powder formats lead volume due to lower processing overhead and extended shelf stability, while juice extracts capture premium positioning among wellness centers seeking rapid bioavailability claims. Capsule demand concentrates among fitness enthusiasts and traveling professionals prioritizing portability over per-serving cost.
FDA Current Good Manufacturing Practice regulations and USDA National Organic Program standards govern labeling, contaminant thresholds, and facility audits across domestic supply chains. The EPA oversees pesticide residue limits on imported raw material, directly shaping sourcing decisions for non-domestic cultivators. Stakeholders must monitor evolving state-level hemp-adjacent labeling laws that occasionally sweep barley grass into broader botanical enforcement actions, creating compliance ambiguity for cross-category marketers.
Market Dynamics
USDA National Organic Program enforcement is compressing margins for uncertified cultivators while consolidating procurement power among validated supply chains across North American health food distribution.
Growth Catalysts
- Preventive nutrition pivot:Wellness centers in the United States are expanding barley grass juice protocols as chlorophyll-based detoxification gains clinical traction among functional medicine practitioners.
- Clean-label processing mandates:FDA Current Good Manufacturing Practice standards are accelerating facility upgrades that reduce microbial contamination risk in powder production.
- Direct-to-consumer channel maturation:Subscription-based powder delivery is capturing repeat purchase loyalty through personalized dosing algorithms and automated replenishment.
Market Restraints
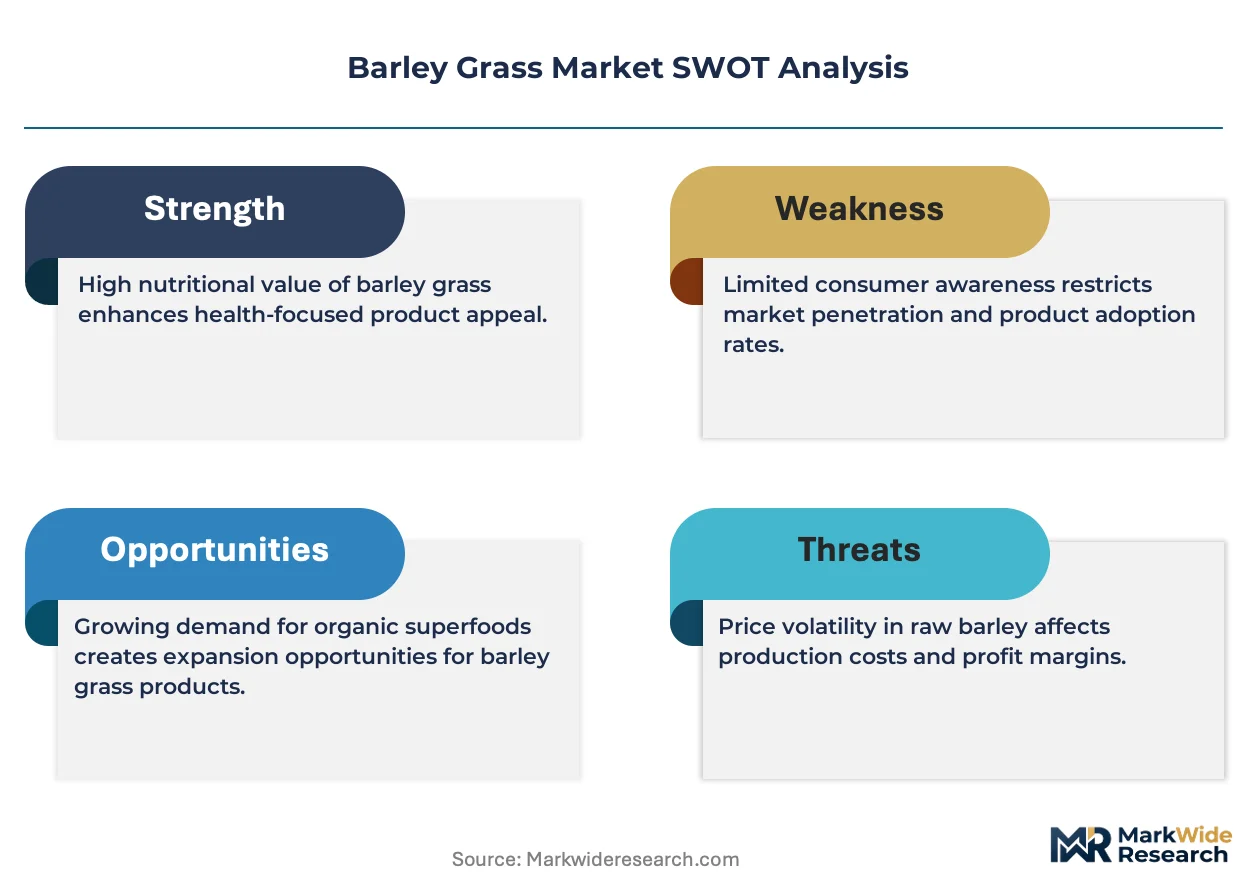
- Input cost volatility:Organic barley seed premiums fluctuate with climate-induced yield variability in the Great Plains, compressing cultivator margins during drought cycles.
- Supply concentration risk:Premium juice-grade raw material dependence on New Zealand's Canterbury Plains creates single-source vulnerability for extract manufacturers.
- Substitution threat:Spirulina and chlorella powders compete for identical shelf space in supplement retail, often at lower per-serving price points.
Strategic Opportunities
- Underpenetrated clinical nutrition:Hospital foodservice departments in Germany are piloting barley grass fortification for post-surgical recovery protocols, creating institutional volume potential.
- Regulatory tailwind:India's FSSAI functional food category expansion is lowering registration barriers for imported phytonutrient concentrates.
- Technology convergence:Cold-press extraction combined with nitrogen-flush packaging is extending juice shelf life without thermal degradation, unlocking ambient distribution.
Industry Challenges
- Certification timeline compression:USDA organic transition periods demand three-year field history documentation, straining working capital for conventional-to-organic converters.
- Enzyme stability protocols:Maintaining superoxide dismutase activity through drying and storage requires precision humidity control that many mid-scale processors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barley Grass Market |
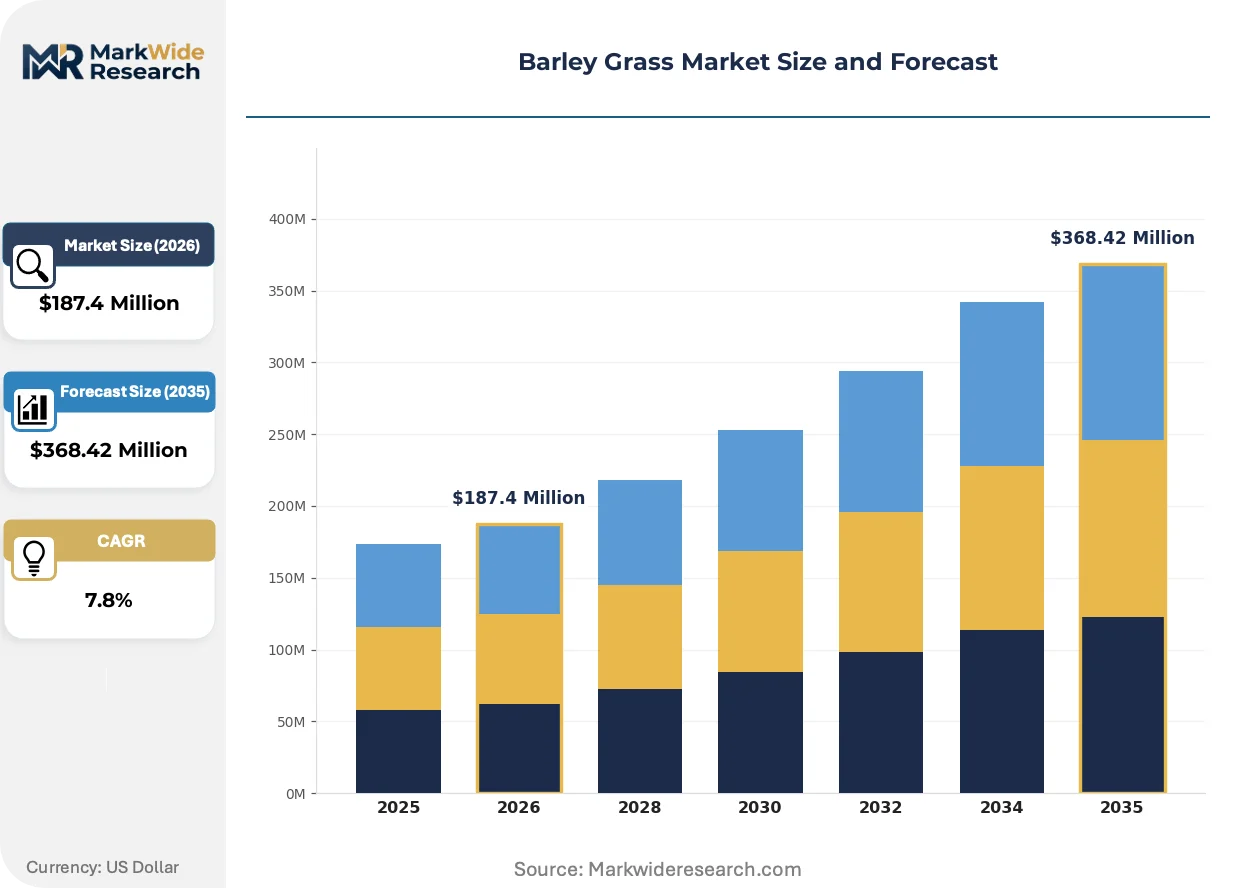
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $368.42 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Juice, Capsules, Extracts Application: Nutri-aceuticals, Food & Beverage, Personal Care, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores End User: Households, Fitness Enthusiasts, Athletes, Wellness Centers |
| Companies Covered | Green Foods Corporation, Swanson Health Products, The Synergy Company, NOW Foods, Vimergy, Morlife, Terrasoul Superfoods, NZ Nutritionals, YT Biochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barley Grass Market Emerging Trajectories
Processing technology and certification standards are restructuring competitive advantage away from commodity cultivation toward validated bioactive preservation and supply chain transparency.
Spray-drying with inlet temperatures below 80°C is supplanting conventional drum-drying for premium powder grades, preserving heat-labile vitamins and enzyme activity. Wellness centers and high-end supplement brands are specifying low-temperature processed material at 40% price premiums. This thermal gentleness is compressing market share for legacy high-heat processors unable to retrofit capital equipment.
EU REACH registration requirements for novel extraction solvents are forcing reformulation of juice concentrate production methods across European contract manufacturers. The industrial consequence is accelerated adoption of supercritical CO2 systems that bypass solvent classification entirely. Organic-certified juice extracts destined for German and French retail are most affected, with suppliers front-loading compliance documentation to maintain shelf placement.
Clean-label verification is shifting procurement authority from brokers to end-brand quality teams conducting unannounced field audits. Direct relationships with single-origin farms are replacing aggregated commodity purchases for premium positioning. This disintermediation is most visible in United States direct-to-consumer brands, which now publish cultivator profiles and harvest dates on packaging to differentiate against opaque supply chains.
Barley Grass Market Segmentation
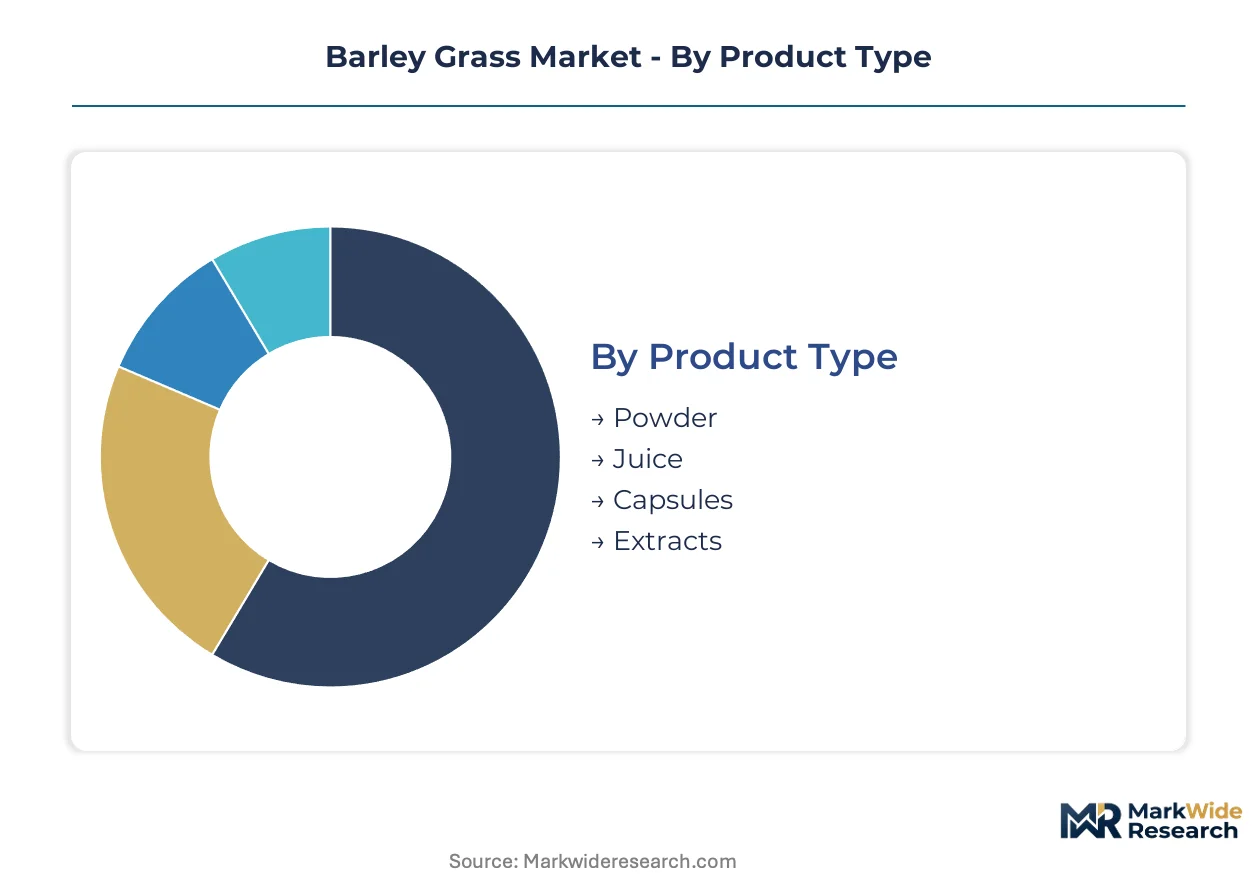
Barley grass segmentation reflects divergent processing intensities and channel economics. Powder and juice formats command fundamentally different margin structures, while wellness centers and direct-to-consumer households operate on separate procurement cycles.
Product Type:
Powder formats dominate domestic United States supply chains with established co-packing infrastructure. Juice concentrates depend heavily on Canterbury Plains imports and cold-chain distribution networks.
- Powder:Dehydrated leaf material milled to 80-200 mesh particle size with chlorophyll retention specifications. United States health food stores and bulk supplement manufacturers anchor procurement volumes, though drought cycles in the Great Plains periodically constrain organic seed availability.
- Juice:Cold-pressed liquid extracts standardized for chlorophyll and superoxide dismutase activity. Wellness centers in California and New York drive premium positioning, with nitrogen-flush packaging extending ambient shelf life for expanded distribution reach.
- Capsules:Encapsulated powder delivering standardized dosing for portability-focused segments.
- Extracts:Concentrated bioactive fractions targeting cosmetic and pharmaceutical formulation inputs.
Powder commands the established base. The steepest expansion runs through juice as functional medicine protocols gain clinical traction.
Application:
Application segments stratify by regulatory scrutiny and formulation complexity. Dietary supplements face the most intensive FDA Current Good Manufacturing Practice compliance, while food and beverage integration demands flavor masking expertise.
- Dietary Supplements:Capsule, tablet, and bulk powder formats positioned for daily micronutrient supplementation. United States direct-to-consumer subscription models are capturing repeat purchase loyalty through personalized dosing platforms and automated replenishment systems.
- Nutri-ceuticals:Functional food additives and clinical nutrition formulations with bioactive standardization. German hospital foodservice departments are piloting post-surgical recovery fortification protocols, creating institutional volume potential.
- Food & Beverage:Smoothie bases, energy bars, and fortified beverages requiring palatability engineering.
- Personal Care:Topical formulations leveraging antioxidant and anti-inflammatory properties for cosmetic applications.
Dietary supplements anchor current revenue. Nutri-ceuticals are climbing the fastest as clinical validation expands reimbursement-adjacent positioning.
Distribution Channel:
Channel economics favor divergent working capital profiles. Online retail minimizes inventory carrying costs through drop-ship fulfillment, while specialty stores demand extended payment terms and promotional support.
- Online Retail:Direct-to-consumer platforms and marketplace listings with subscription automation. United States wellness-focused brands leverage cultivator transparency and harvest dating to differentiate against opaque supply chains.
- Health Food Stores:Independent and chain retailers with trained staff and bulk bin operations. Green Foods Corporation maintains shelf presence through long-standing organic supply chain relationships.
- Supermarkets:Mass-market placement requiring price competitiveness and conventional packaging formats.
- Specialty Stores:High-service environments with premium positioning and educational staff.
Health food stores retain the core customer base. Online retail is gaining share fastest through algorithm-driven personalization and loyalty program lock-in.
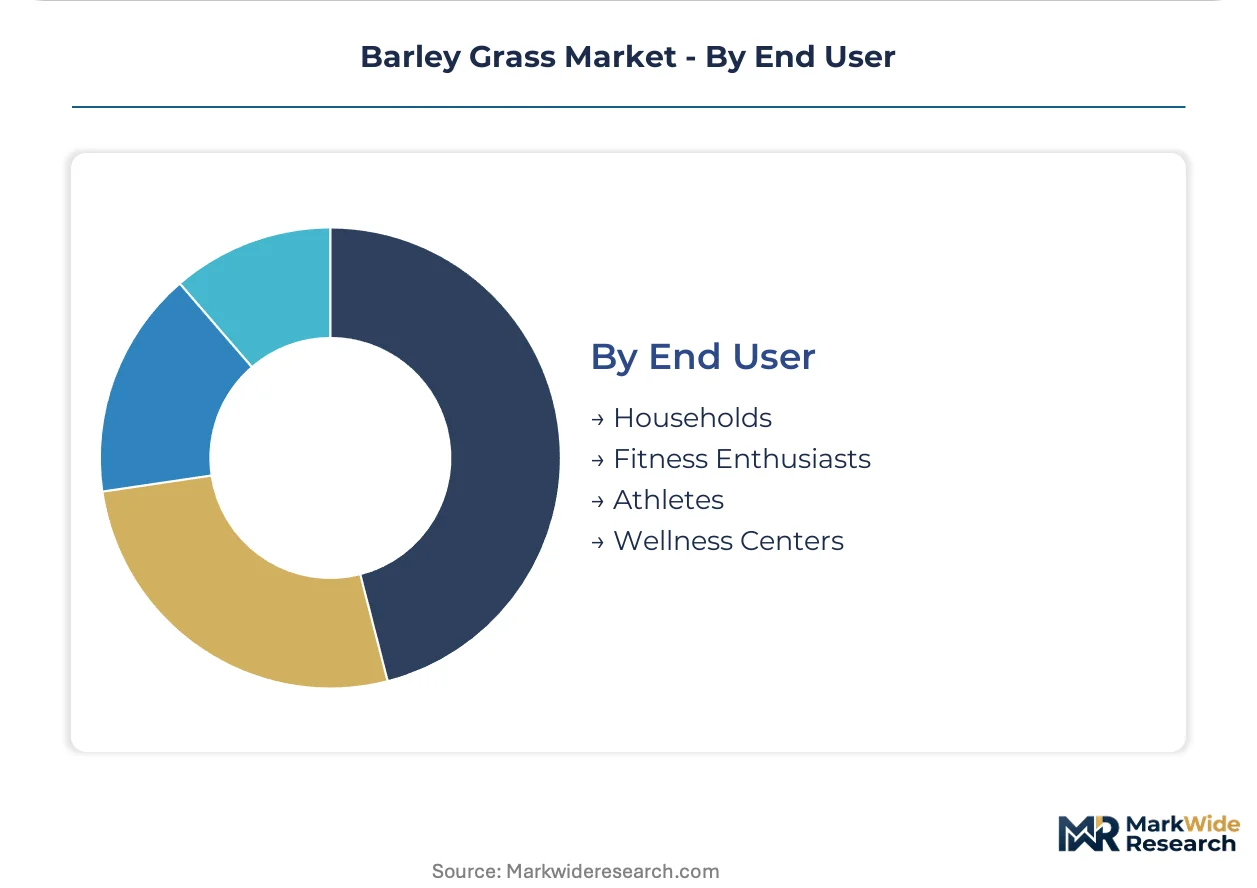
End User:
End user segments separate by consumption occasion and price sensitivity. Wellness centers operate on professional-grade procurement with volume discounts, while fitness enthusiasts prioritize convenience premiums.
- Wellness Centers:Clinical and spa environments integrating barley grass into detoxification and recovery protocols. Functional medicine practitioners in the United States are expanding juice-based chlorophyll therapies, driving premium extract demand with documented bioavailability claims.
- Households:Daily consumers purchasing through retail and subscription channels for general wellness maintenance.
- Fitness Enthusiasts:Gym-adjacent consumers seeking portable nutrition for pre and post-workout consumption.
- Athletes:Competitive performers with performance-linked supplementation protocols and brand sponsorship exposure.
Households represent the volume foundation. Wellness centers are expanding most quickly as clinical credibility separates professional-grade from commodity positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellness centers and direct-to-consumer households concentrate purchasing power in mature economies with established organic certification infrastructure. Procurement patterns diverge sharply between clinical-grade juice protocols and commodity powder formats.
United States
Functional medicine practitioners in California and New York drive premium juice extract demand through chlorophyll-based detoxification protocols. FDA Current Good Manufacturing Practice standards govern facility audits and labeling requirements for dietary supplement manufacturers. The Great Plains organic cultivation belt anchors domestic powder supply, though drought cycles periodically constrain seed availability.
Germany
Hospital foodservice departments pilot post-surgical recovery fortification protocols, creating institutional volume potential for clinical nutrition applications. EU REACH registration requirements for novel extraction solvents force reformulation of juice concentrate production methods. The Bavarian organic processing cluster advances supercritical CO2 extraction systems to bypass solvent classification entirely.
New Zealand
Canterbury Plains cultivation commands premium positioning for juice-grade raw material with documented chlorophyll standardization. The country's national food safety regulator enforces strict contaminant thresholds on exported phytonutrient concentrates. Christchurch-based extraction facilities supply nitrogen-flush packaging that extends ambient shelf life for European and North American wellness centers.
India
FSSAI functional food category expansion lowers registration barriers for imported phytonutrient concentrates, accelerating market entry for foreign suppliers. Maharashtra and Gujarat processing hubs contract with Punjab and Haryana cultivators for organic barley grass sourcing. Mumbai direct-to-consumer brands leverage subscription automation to capture repeat purchase loyalty among urban wellness households.
Japan
Metropolitan wellness centers in Tokyo and Osaka integrate barley grass into preventive nutrition protocols alongside traditional botanical therapies. METI standards for functional food claims require substantiation documentation that filters out uncredentialed suppliers. The Kanto region's health food retail chains specify low-temperature processed material at substantial price premiums over conventional powder grades.
Barley Grass Market Vendor Landscape
Player mix skews toward integrated cultivator-processors with certified organic supply chains and contract manufacturers serving private-label demand. Three structural tiers separate long-standing organic validators from mid-scale regional processors and emerging direct-to-consumer brands. Strategic moves concentrate on backward integration into cultivation to secure raw material traceability, and on cold-chain infrastructure investment to preserve enzyme activity through distribution.
Among North American organic specialists, Green Foods Corporation and NOW Foods occupy positions at opposite ends of the manufacturing spectrum. Green Foods exemplifies the cultivator-integrated archetype with established bulk powder leadership across health food store channels. NOW Foods represents the scale-driven contract manufacturing model, anchoring private-label and branded capsule production through GMP-certified facility networks. NZ Nutritionals sits within the geographic-specialist tier, leveraging Canterbury Plains sourcing to command premium shelf placement in specialty retail.
| Leading Market Players |
|---|
| Green Foods Corporation |
| Swanson Health Products |
| The Synergy Company |
| NOW Foods |
| Vimergy |
| Morlife |
| Terrasoul Superfoods |
| NZ Nutritionals |
| YT Biochem |
| Others |
Supply Flow & Price Mechanics
Cold-press extraction equipment replacing legacy drum-dryers is simultaneously relocating processing capacity toward Canterbury Plains proximity and compressing price premiums for heat-degraded powder grades. This equipment substitution dynamic concentrates procurement power among wellness centers and direct-to-consumer brands capable of certifying low-temperature protocols.
Pricing Analysis
Cost-plus contracts indexed to organic barley seed futures dominate procurement between Great Plains cultivators and North American powder processors. Three-tier pricing structure across premium, standard, and economy levels separates nitrogen-flush juice extracts from spray-dried powders and conventional drum-dried grades. Pricing pressure stems from spirulina and chlorella substitution at lower per-serving price points in mass-market retail. Fitness enthusiasts and traveling professionals purchasing capsules exhibit highest price sensitivity, while wellness centers sourcing clinical-grade juice extracts prioritize bioactivity documentation over per-unit cost.
Supply Chain Analysis
Inventory carrying costs for cold-pressed juice concentrates extend lead times for European and North American wellness centers dependent on Canterbury Plains raw material. Geographic supply concentration centers on New Zealand for juice-grade chlorophyll standardization, the United States Great Plains for organic powder cultivation, and India for contract processing of FSSAI-registered concentrates. Raw material dependencies include organic barley seed, nitrogen-flush packaging films, and supercritical CO2 extraction solvents. Single-source vulnerability for premium juice-grade raw material creates supply chain risk. Distribution runs through health food store networks for powder volumes and direct-to-consumer subscription platforms for premium extracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment automation represents a service-attach opportunity expanding faster than commodity powder hardware, as algorithm-driven dosing platforms capture repeat purchase loyalty with minimal marginal cost.
For Market Incumbents: Fortify organic certification moats through accelerated three-year field history documentation ahead of USDA enforcement tightening. Secure captive supply of Canterbury Plains juice-grade raw material through cultivation partnerships or processing joint ventures to defend against New Zealand supply concentration risk. Channel control through wellness center protocol development locks in professional-grade procurement at 40% price premiums over retail powder. For New Entrants and Emerging Players: Cold-chain logistics under-service by established processors creates entry space for regional juice extract specialists with nitrogen-flush packaging capabilities. Target German hospital foodservice departments piloting post-surgical recovery fortification as the most penetrable institutional segment. Go-to-market through functional medicine practitioner education programs builds clinical credibility before retail shelf placement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated cultivator-processors with validated organic supply chains. Long-term viability hinges on backward integration into single-origin farm relationships and cold-chain infrastructure ownership. Acquisition target archetype: mid-scale processors with USDA organic certification and retrofit-capable low-temperature drying equipment. Watch FSSAI functional food category enforcement consistency as inflection indicator for Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | USDA organic certification secures raw material traceability for wellness center procurement. |
| Cold-Chain Infrastructure Investment | Nitrogen-flush packaging extends juice shelf life for ambient distribution reach. |
| Subscription Platform Development | Algorithm-driven dosing automation captures repeat purchase loyalty with minimal marginal cost. |
| Clinical Protocol Partnerships | Functional medicine practitioner education builds professional-grade demand at premium pricing. |
| Supercritical CO2 Extraction Adoption | EU REACH solvent compliance bypass maintains German and French retail shelf placement. |
Methodological Framework
The analysis maps powder processing tiers, juice extraction methods, capsule formulation standards, and extract concentration grades, each validated through cultivation managers, supplement manufacturing executives, wellness center procurement directors, and organic certification auditors. Primary interviews with these stakeholders combined trade data from USDA National Organic Program filings, FDA facility inspection records, FSSAI functional food registrations, and EU REACH solvent documentation. Secondary sources included customs records for Canterbury Plains export volumes, health food store distribution databases, and direct-to-consumer subscription platform metrics. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and distribution channel dimensions.
Consistency checks validated volume and value outputs against organic barley seed futures pricing trends, wellness center protocol adoption surveys, and nitrogen-flush packaging equipment installation records across the projection horizon. Segmentation modeling incorporated product format, bioactivity standardization level, certification tier, and regional regulatory cluster. CAGRs derived from historical growth trajectory analysis adjusted for input cost volatility and substitution threat intensity. Industry-specific forecast inputs included drought cycle frequency in the Great Plains and FSSAI registration approval velocity.
Forecasts assume regulatory continuity in USDA National Organic Program enforcement, EU REACH solvent classification, and FSSAI functional food category definitions; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Wheat Flour Market
Grains
Pea Grits Market
Grains
Argentina Maize Market
Grains
Red Rice Market
Grains
Global Wheat Market
Grains
South Africa Grain Market
Grains
China Wheat Protein Market
Grains
Mexico Rice Market
Grains
Wheat Bran Market
Grains
Global Flour Market
Grains
Millets Market
Grains
Non-Basmati Rice Market
Grains
Grain Dryers Market
Grains
Sorghum Flour Market
Grains
Oat Bran Market
Grains
Ghana Grain Market