
 Red Rice Market | 2026-2036
Red Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Red Rice Market Analytics
Buyer concentration in the red rice trade is pivoting from fragmented local mandis toward organized health-food retail chains and direct-to-consumer platforms. LT Foods Limited leverages its established basmati infrastructure to extend into heritage red rice sourcing across Himalayan foothill cooperatives. Lundberg Family Farms sustains premium positioning through certified organic cultivation in California's Sacramento Valley. Lotus Foods, Inc. differentiates via heirloom varietal preservation and climate-resilient growing partnerships in Madagascar and Bhutan.
Red rice denotes pigmented Oryza sativa cultivars retaining anthocyanin-rich bran layers, with pericarp coloration ranging from maroon to deep purple and protein content typically exceeding conventional white milled rice by 15-20 percent. Its primary commercial purpose centers on functional food formulations, specialty retail, and heritage cuisine applications where nutritional density commands price premiums. Whole grain red rice occupies the dominant volume position due to minimal processing requirements and maximal antioxidant retention, while parboiled rice variants capture institutional foodservice demand through extended shelf stability and reduced cooking loss. Distribution through specialty stores and online retail channels concentrates margin pools, as these segments bypass commodity auction pricing and capture direct consumer willingness-to-pay for provenance documentation.
The Food Safety and Standards Authority of India mandates pesticide residue limits and organic claim verification for export-bound red rice consignments, directly conditioning market access for Dehradun Basmati and Matta varietal producers. The USDA's National Organic Program and California's CCOF certification create dual compliance thresholds for North American suppliers seeking premium shelf placement. Stakeholders must monitor evolving varietal registration requirements and geographic indication disputes that could redraw competitive boundaries between heritage producers and commercial scale operators.
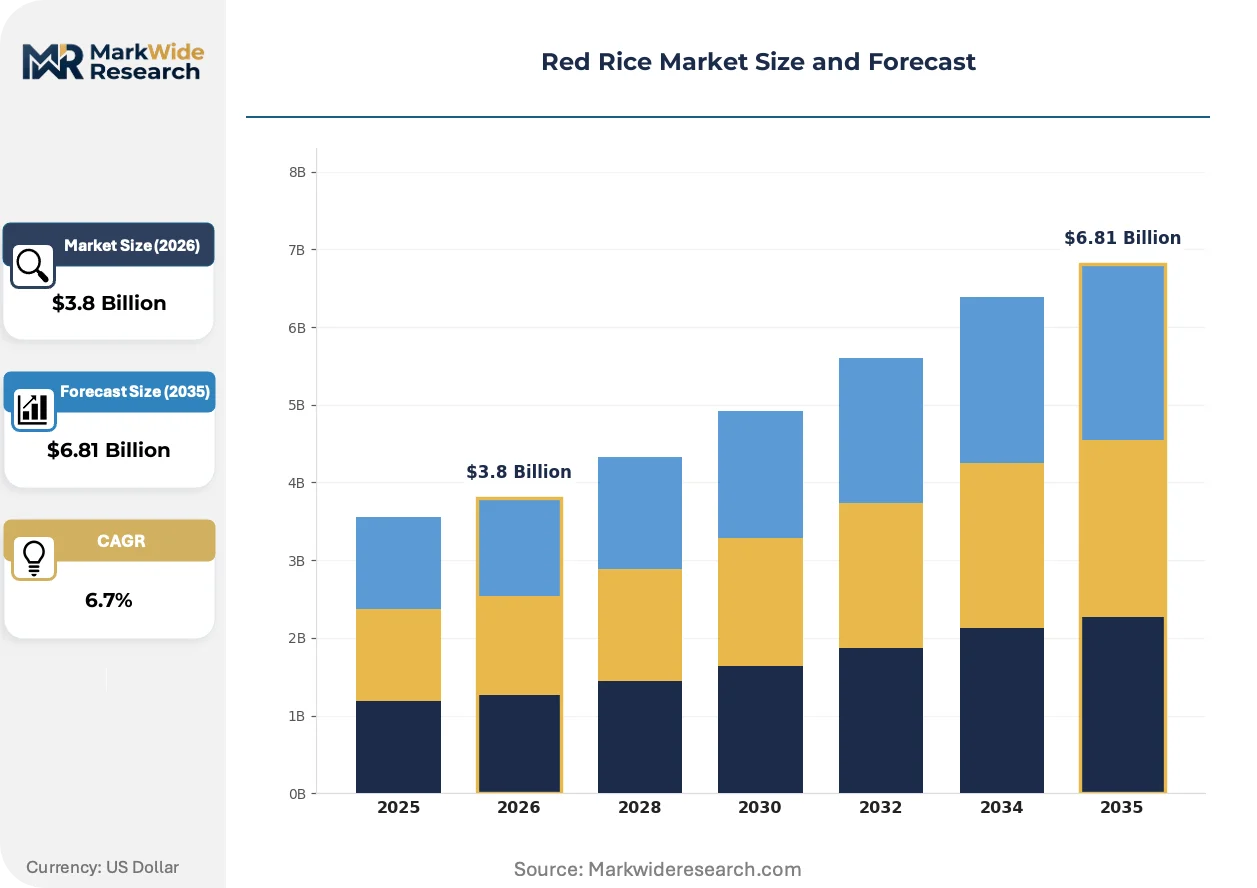
Market Dynamics
The red rice market pivots on FSSAI fortification mandates and organic certification protocols that are restructuring export compliance costs and procurement relationships across South Asian supply chains.
Growth Catalysts
- Wellness tourism integration:Kerala and Tamil Nadu heritage cuisine programs are embedding red rice into curated nutritional experiences. Ayurvedic retreat operators now specify heirloom varietals in procurement contracts.
- FSSAI export protocols:India's mandatory pesticide residue limits and organic claim verification are standardizing quality thresholds. Matta and Dehradun Basmati producers gain preferential channel access through compliant certification.
- Anthocyanin extraction:Functional food manufacturers are deploying bran-layer processing to isolate antioxidant compounds. Nutraceutical formulators source concentrated extracts for supplement applications.
Market Restraints
- Input cost volatility:Himalayan foothill irrigation water access fluctuates with monsoon variability. Smallholder cooperatives face yield uncertainty that compresses margin stability.
- Supply concentration risk:Heritage seed stock maintenance depends on limited geographic pockets in Bhutan and Madagascar. Climate stress in either region disrupts varietal preservation programs.
- Substitution pressure:Black rice and purple corn deliver comparable anthocyanin profiles at lower procurement complexity. CPG formulators rotate inputs based on spot pricing.
Strategic Opportunities
- Direct-to-consumer platforms:E-commerce channels bypass commodity auction pricing and capture provenance premiums. Specialty retailers deploy blockchain traceability to document cooperative sourcing.
- Parboiled institutional supply:Extended shelf stability variants address foodservice batch-cooking requirements. Hospital and corporate cafeteria contracts specify reduced cooking loss metrics.
- EU organic recognition:India's APEDA equivalence agreements with EFSA accelerate export clearance. Certified operators access premium shelf placement in German and Dutch retail chains.
Industry Challenges
- Heritage seed banking expertise:In-situ conservation requires agronomists trained in traditional cultivation cycles. Knowledge transfer gaps between aging farmers and extension services threaten varietal continuity.
- Dual certification timelines:USDA National Organic Program and California CCOF compliance runs 18-24 months for new entrants. Documentation burdens delay North American market entry.
- Geographic indication disputes:Matta rice origin claims face contested registration between Kerala and Tamil Nadu producer associations. Legal uncertainty deters brand investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Red Rice Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Brown Rice, Parboiled Rice, White Rice End Use: Food Industry, Health Food Stores, Restaurants, Organic Markets Packaging Type: Bags, Bulk, Boxes, Retail Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers Markets |
| Companies Covered | Hangzhou Twin-Horse Group, Shandong Zhonghui Biotechnology, Lundberg Family Farms, Organic Tattva, URMATT Ltd., LT Foods Limited, Keerthi Nirmal, Veetee Rice Limited, Lotus Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Red Rice Market Evolving Landscape
Processing technology and certification infrastructure are compressing traditional supply chain tiers while redirecting margin pools toward traceability-verified channels.
Optical sorting technology is automating bran-layer integrity assessment during milling operations. Medium-scale processors in Andhra Pradesh and Karnataka are retrofitting equipment to reduce manual grading labor. This automation is compressing quality variation and enabling consistent anthocyanin retention across export batches.
REACH chemical safety protocols in the European Union now govern imported food contact materials and processing aids. Exporters to Germany and France must demonstrate compliance with SVHC substance restrictions in packaging and handling equipment. Organic-certified operators are responding by segregating EU-bound production lines to prevent cross-contamination.
Specialty retail buyers are consolidating procurement through vertically integrated cooperatives that control seed-to-shelf documentation. Direct sourcing agreements displace traditional mandi intermediaries in Kerala and Tamil Nadu distribution. This channel restructuring concentrates most visibly in urban health-food chains across Bangalore, Chennai, and Hyderabad.
Red Rice Market Segmentation
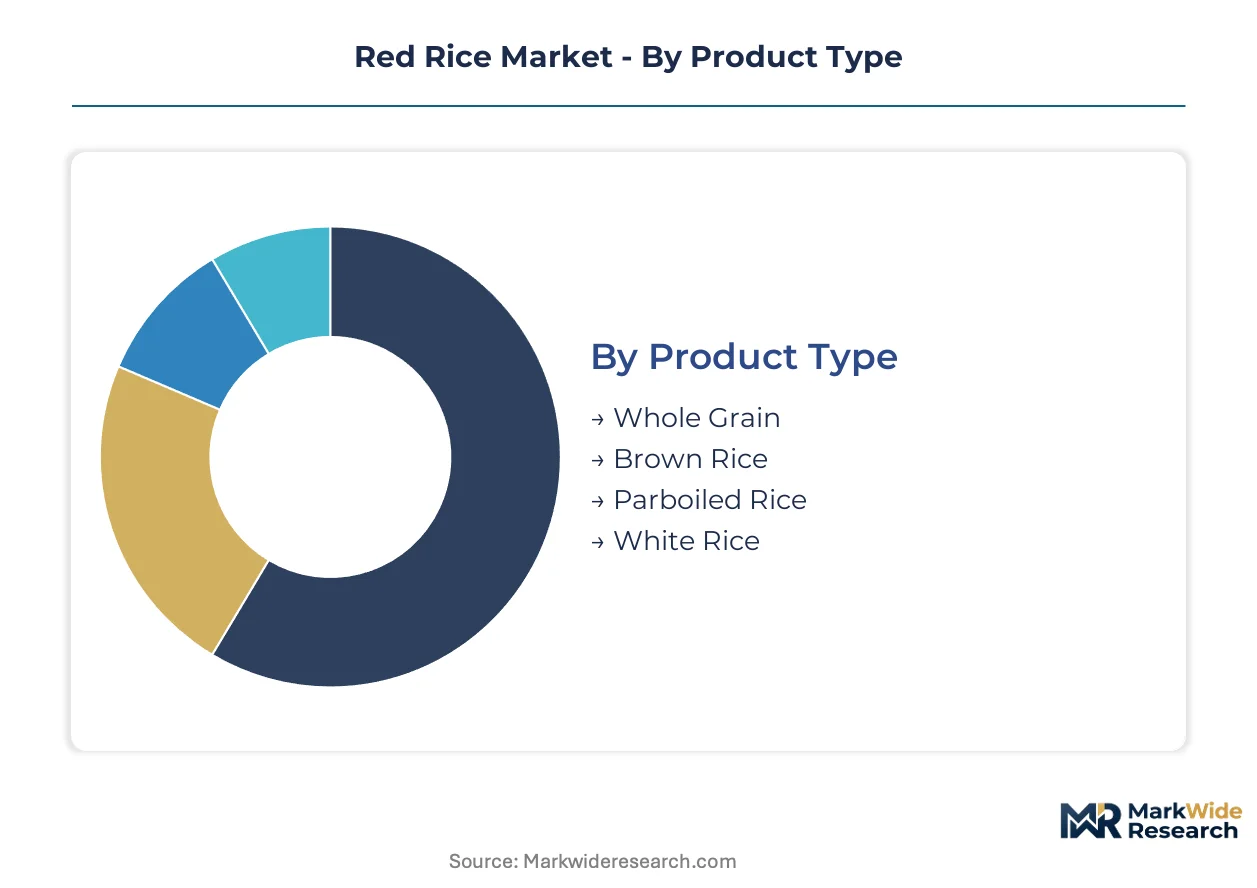
Red rice segmentation tracks divergent processing philosophies between heritage preservation and convenience optimization. Volume concentration in minimally processed formats contrasts sharply with premium capture in certified organic channels. Each category reveals distinct margin architectures shaped by certification burden and channel access.
Product Type:
Volume concentration sits in unpolished formats retaining bran-layer integrity, while premium extraction targets parboiled variants with extended stability profiles.
- Whole Grain:Unmilled kernels preserve complete pericarp anthocyanin content and 15-20% protein elevation over polished alternatives. Kerala Ayurvedic retreat operators and Tamil Nadu wellness tourism programs specify this format in procurement contracts for heritage cuisine applications.
- Parboiled Rice:Hydrothermal processing gelatinizes starch prior to milling, yielding extended shelf stability and 40% reduced cooking loss. Hospital cafeteria contracts and corporate foodservice batch operations in Bangalore and Hyderabad drive institutional demand for this segment.
- Brown Rice:Partial bran retention delivers intermediate antioxidant density with reduced cooking time versus whole grain. Health-food retail chains in Chennai and Hyderabad stock this as entry-level heritage format.
- White Rice:Complete bran and germ removal eliminates characteristic pigmentation and anthocyanin payload. Minimal commercial traction outside commodity blending applications.
Today's leader: Whole Grain. Tomorrow's challenger: Parboiled Rice.
End Use:
Channel restructuring concentrates margin capture in direct-to-consumer platforms while foodservice contracts standardize on parboiled specifications.
- Food Industry:CPG formulators and nutraceutical extractors source bran-layer concentrates for antioxidant isolation. FSSAI-mandated pesticide residue documentation governs procurement from Dehradun Basmati and Matta varietal suppliers.
- Health Food Stores:Specialty retail chains across Bangalore, Chennai, and Hyderabad deploy blockchain traceability to document Himalayan foothill cooperative sourcing. Provenance premiums bypass commodity auction pricing.
- Restaurants:Kerala and Tamil Nadu heritage cuisine programs embed heirloom red rice into curated nutritional experiences. Ayurvedic retreat operators now specify varietal provenance in supply agreements.
- Organic Markets:Dual-certified operators meeting USDA National Organic Program and California CCOF thresholds access premium shelf placement. Documentation burdens delay new entrant participation.
Health Food Stores extract the steepest expansion trajectory from wellness tourism integration and e-commerce channel growth.
Packaging Type:
Format selection tracks supply chain tier compression, with bulk formats dominating cooperative-to-processor movement and retail packs capturing final-channel margin.
- Bulk:Loose grain movement from Himalayan foothill cooperatives to regional millers minimizes handling cost. FSSAI export protocol compliance concentrates in this tier for institutional redistribution.
- Retail Packs:Consumer-facing formats with origin documentation and organic certification marks. Urban health-food chains in Bangalore and Chennai specify 1-5kg SKUs with blockchain traceability.
- Bags:Intermediate packaging for specialty store distribution. REACH-compliant materials required for EU-bound consignments through German and Dutch retail channels.
- Boxes:Premium gift formats targeting wellness tourism souvenir segments. Minimal volume share outside Kerala Ayurvedic retreat retail operations.
Bulk commands current volume leadership. Retail Packs gain share fastest from direct-to-consumer platform expansion.
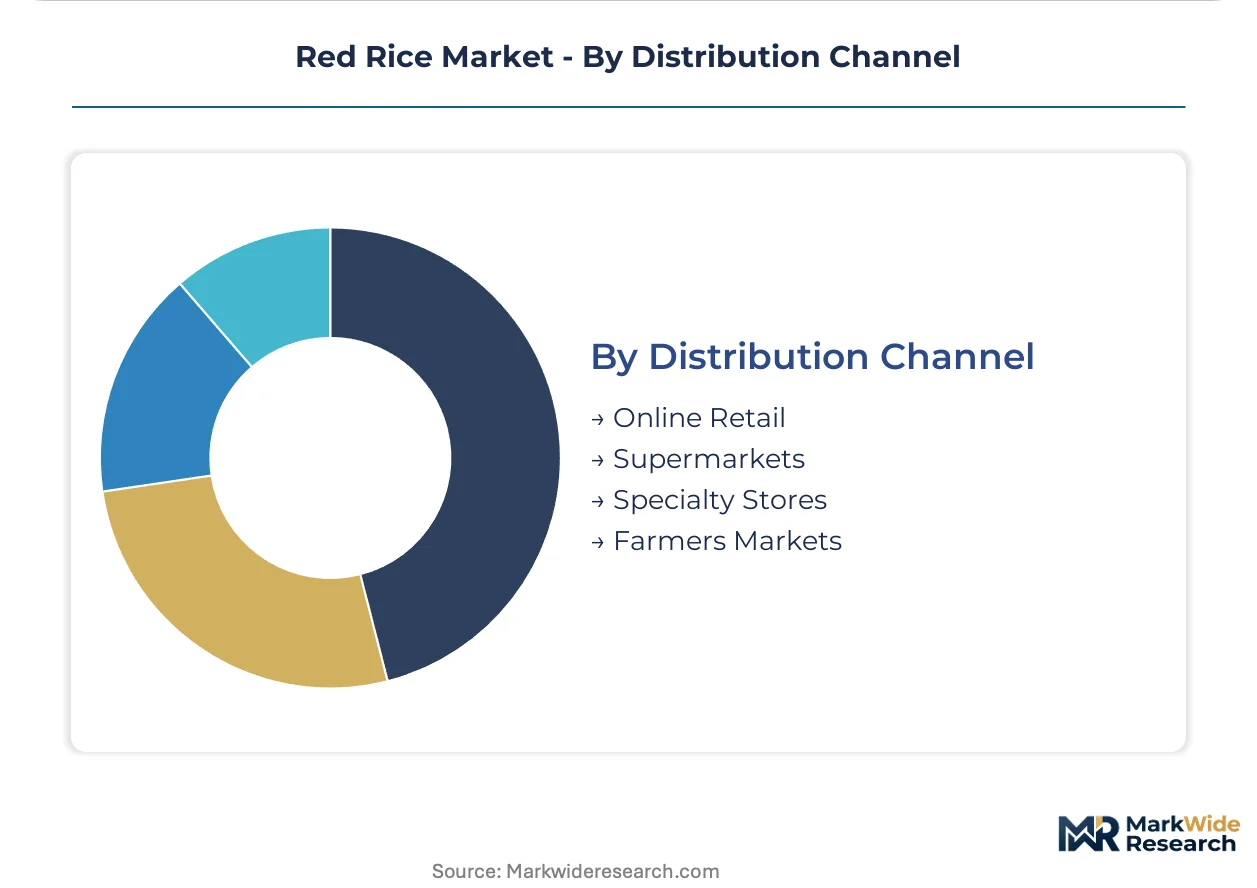
Distribution Channel:
Channel selection determines margin pool access, with specialty formats bypassing commodity pricing and capturing provenance premiums.
- Specialty Stores:Vertically integrated cooperatives control seed-to-shelf documentation. Direct sourcing agreements displace traditional mandi intermediaries in Kerala and Tamil Nadu distribution.
- Online Retail:E-commerce platforms bypass geographic constraints and capture urban consumer willingness-to-pay for heritage varietal documentation. Amazon India and BigBasket list certified organic SKUs with cooperative provenance.
- Supermarkets:Organized retail chains in Chennai and Hyderabad stock parboiled variants for mass-market accessibility. Price compression limits margin extraction versus specialty channels.
- Farmers Markets:Direct producer-to-consumer contact preserves heritage seed stock narratives. Limited scale outside Madurai and Kochi urban periphery clusters.
Specialty Stores anchor present premium capture. Online Retail projects the most aggressive expansion trajectory from platform infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomists trained in traditional cultivation cycles anchor production networks across distinct geographic pockets where heritage seed stock preservation intersects with export compliance infrastructure.
India
Kerala Ayurvedic retreat operators and Tamil Nadu wellness tourism programs drive procurement specifications for Matta and Dehradun Basmati varietals. FSSAI pesticide residue limits and organic claim verification govern export-bound consignments through APEDA. Himalayan foothill cooperatives in Uttarakhand supply heritage seed stock to Bangalore and Chennai distribution clusters.
United States
California health-food retail chains and Sacramento Valley organic cultivation operations sustain premium positioning for domestic specialty grain consumption. USDA National Organic Program and California CCOF certification create dual compliance thresholds for shelf placement. Lundberg Family Farms anchors production concentration in the Sacramento Valley with certified organic operations.
China
Functional food manufacturers in Yangtze River Delta provinces source anthocyanin concentrates for nutraceutical formulations. GB standards and SAMR oversight govern food contact materials and processing safety protocols. Zhejiang and Jiangsu processing clusters retrofit optical sorting equipment for bran-layer integrity assessment.
Madagascar
Climate-resilient growing partnerships with international buyers preserve heirloom varietals for European export channels. Madagascar's national agricultural extension services coordinate varietal registration with EU organic equivalence requirements. Antananarivo-based cooperatives manage seed banking programs for heritage red rice preservation.
Germany
REACH chemical safety protocols and EFSA organic recognition standards govern import clearance for specialty grain consignments. German retail chains in Berlin and Hamburg specify provenance documentation and blockchain traceability for premium shelf placement. Bavarian foodservice distributors channel parboiled variants to hospital and corporate cafeteria contracts.
Red Rice Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures concentrate around certification infrastructure and direct-to-consumer platform access. Three archetypes dominate: vertically integrated cooperatives controlling seed-to-shelf documentation, heritage varietal preservation specialists, and scale-driven processors leveraging existing grain infrastructure. Competitive moves center on strategic partnerships with wellness tourism operators and capacity expansion in optical sorting technology.
Among Asia-based heritage specialists, Hangzhou Twin-Horse Group and Shandong Zhonghui Biotechnology occupy positions within the functional food ingredient supply tier. LT Foods Limited exemplifies the diversified processor archetype, leveraging established infrastructure into heritage sourcing networks. Lotus Foods, Inc. represents the preservation-focused specialist model through climate-resilient partnership structures.
| Leading Market Players |
|---|
| Hangzhou Twin-Horse Group |
| Shandong Zhonghui Biotechnology |
| Lundberg Family Farms |
| Organic Tattva |
| URMATT Ltd. |
| LT Foods Limited |
| Keerthi Nirmal |
| Veetee Rice Limited |
| Lotus Foods, Inc. |
| Others |
Value Network & Pricing Analysis
Optical sorting technology retrofits across Andhra Pradesh and Karnataka milling operations are compressing quality variation while simultaneously reducing manual labor dependence and concentrating procurement power among medium-scale processors capable of capital investment.
Pricing Analysis
Certification-bundled versus unbundled grain sales split the market into distinct transaction structures. Three-tier pricing separates certified organic from conventional from commodity auction grades, with FSSAI compliance and USDA National Organic Program dual certification commanding the widest premiums. Price differentiation hinges on provenance documentation completeness and anthocyanin retention certification. Pricing pressure stems from black rice and purple corn substitution in CPG formulations. Mass-market supermarket buyers exhibit highest price sensitivity, while Ayurvedic retreat operators show lowest.
Supply Chain Analysis
Certification gating through FSSAI, USDA National Organic Program, and California CCOF creates 18-24 month compliance timelines that filter supplier participation. Geographic supply concentration centers on India, Madagascar, and California, with Himalayan foothill cooperatives and Sacramento Valley operations anchoring heritage seed stock. Raw material dependencies include irrigation water access, heritage seed banking capacity, and optical sorting equipment. Single-source vulnerability threatens varietal continuity where aging farmer knowledge gaps persist. Distribution runs through vertically integrated cooperatives displacing traditional mandi intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The red rice market functions as a stable compounder where wellness tourism integration and functional food ingredient demand generate predictable expansion without cyclical volatility.
For Market Incumbents: Cement channel control through exclusive supply agreements with Kerala and Tamil Nadu Ayurvedic retreat operators. Deepen backward integration into Himalayan foothill cooperative sourcing to lock heritage seed stock access. Invest in dual USDA and California CCOF certification infrastructure to defend against emerging organic specialists. Optical sorting capacity expansion in Karnataka preserves quality consistency advantages.
For New Entrants and Emerging Players: Begin with parboiled institutional supply contracts in Bangalore and Hyderabad foodservice corridors where specification standards are codified but supplier fragmentation persists. Target hospital and corporate cafeteria segments with extended shelf stability variants. Leverage e-commerce platform infrastructure to bypass established mandi networks and capture direct-to-consumer provenance premiums.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors lacking certification infrastructure but possessing established cooperative relationships. Five-to-ten year viability hinges on climate-resilient varietal preservation programs and EU organic equivalence access. Acquisition candidates with APEDA-registered export clearance and blockchain traceability deployment offer defensive positioning. The signal to monitor is EFSA equivalence agreement expansion accelerating German and Dutch retail channel penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Seed Banking Partnership | Madagascar cooperatives preserve climate-resilient varietals for European export channels. |
| Optical Sorting Technology Deployment | Andhra Pradesh millers reduce manual grading labor while standardizing anthocyanin retention. |
| Dual Certification Investment | USDA and California CCOF compliance unlocks premium shelf placement in Sacramento Valley retail. |
| Direct-to-Consumer Platform Launch | Amazon India and BigBasket bypass commodity auction pricing for cooperative-provenance SKUs. |
| EU Organic Equivalence Pursuit | APEDA-EFSA agreements accelerate export clearance for German and Dutch retail chains. |
Research Methodology
Direct dialogue with Ayurvedic retreat procurement officers, FSSAI compliance consultants, Himalayan cooperative agronomists, and optical sorting equipment suppliers grounded qualitative insights in operational reality. Secondary validation drew from APEDA export registration databases, FSSAI pesticide residue monitoring reports, California CCOF certification records, and EU organic equivalence agreement documentation. Bottom-up cooperative production estimates and top-down retail channel value capture were triangulated to constrain variance.
Bottom-up volume modeling tracked heritage seed stock availability, irrigation water access variability, and optical sorting capacity expansion across Karnataka and Andhra Pradesh processing clusters. Top-down value estimation calibrated wellness tourism procurement growth and functional food ingredient demand trajectories. Segmentation dimensions spanned product type, end-use channel, certification tier, and geographic production origin. CAGRs were derived from anchored base-year observations projected through assumption-weighted scenario analysis incorporating monsoon variability and EU regulatory recognition timelines.
Caveats apply where FSSAI fortification mandate revisions, EU REACH protocol expansions, or Himalayan irrigation water access disruptions could materially shift the outlook. Forecasts reflect documented assumptions about heritage seed banking continuity and cooperative knowledge transfer effectiveness. A model refresh is warranted upon material change in EFSA organic equivalence recognition or Matta rice geographic indication dispute resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Cassava Flour Market
Grains
South America Wheat Market
Grains
Grain Augers Market
Grains
United States Gluten-Free Oats Market
Grains
Organic Wheat Flour Market
Grains
United States Rice Market
Grains
Oatmeal Market
Grains
Rice Flour Market
Grains
North America Wheat Protein Market
Grains
Grain-Based Flours Market
Grains
Colombia Grains Market
Grains
Barley Grass Market
Grains
Asia-Pacific Wheat Market
Grains
Quinoa Flour Market
Grains
Asia-Pacific Rice Market
Grains
Brazil Maize Market