
 Sorghum Flour Market | 2026-2036
Sorghum Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Sorghum Flour Market Analytics
India is fragmenting its sorghum flour processing base as domestic millers expand capacity to serve both local consumption and export channels. Ardent Mills leverages its integrated grain handling network to secure consistent supply across North American bakery customers. Bob's Red Mill Natural Foods differentiates through stone-ground heritage milling techniques that command premium positioning in specialty retail. Cargill Inc. anchors industrial-scale sorghum sourcing for food manufacturers seeking gluten-free formulation alternatives.
Sorghum flour consists of finely milled endosperm and germ from Sorghum bicolor, typically yielding 8-12% protein content with neutral flavor profiles suitable for wheat substitution in baked goods. Its primary commercial purpose centers on gluten-free food manufacturing, where the flour's low glycemic index and non-allergenic properties address dietary restriction markets. Organic sorghum flour occupies the fastest-expanding product tier as clean-label mandates from European and North American retailers tighten ingredient provenance requirements. Among end users, food manufacturers represent the dominant volume channel, while bakers represent the margin-rich segment where technical support and consistent granulation specifications command pricing premiums.
The FDA enforces gluten-free labeling standards that mandate sub-20 ppm gluten thresholds, directly shaping sorghum flour certification protocols and testing expenditures for domestic suppliers. USDA organic certification and EU REACH chemical compliance frameworks further segment export-accessible production from commodity-grade output. Stakeholders must monitor evolving allergen disclosure requirements across multiple jurisdictions while evaluating backward integration into sorghum cultivation to secure supply chain transparency.
Market Dynamics
The FDA's sub-20 ppm gluten-free labeling mandate is compressing certification timelines and forcing sorghum flour processors to integrate in-house testing capabilities rather than rely on third-party laboratories.
Growth Catalysts
- Clean-label retail mandates:European and North American supermarket chains now require organic provenance documentation for shelf placement, pulling organic sorghum flour into accelerated production cycles.
- Low glycemic index properties:Diabetic and metabolic health segments are specifying sorghum flour in clinical nutrition formulations, expanding beyond traditional bakery substitution.
- Great Plains cultivation concentration:Kansas, Texas, and Nebraska sorghum belt farmers are contracting directly with millers, shortening supply chains for domestic food manufacturers.
Market Restraints
- Input cost volatility:Sorghum grain prices fluctuate with drought cycles across the US Central Plains, compressing processor margins during poor harvest years.
- Technical limitation:Sorghum flour lacks gluten's elastic network, requiring xanthan gum or guar gum additions that increase formulation complexity and raw material costs.
- Substitution threat:Rice flour and tapioca starch offer lower-cost gluten-free alternatives for price-sensitive industrial bakers, capping sorghum flour's volume expansion.
Strategic Opportunities
- Underpenetrated geography:Sub-Saharan African markets consume sorghum as whole grain; flour processing infrastructure remains nascent, offering first-mover positioning for industrial millers.
- Regulatory tailwind:USDA organic certification premiums are widening as conventional grain prices stagnate, rewarding backward integration into certified organic cultivation.
- Technology convergence:Near-infrared spectroscopy paired with blockchain traceability is enabling real-time quality verification for export shipments to EU REACH-compliant buyers.
Industry Challenges
- Certification timeline compression:FSSAI in India and FDA in the United States run parallel but non-harmonized testing protocols, forcing exporters to duplicate laboratory expenditures.
- Capex intensity:Stone-ground heritage milling equipment requires specialized maintenance expertise that is scarce outside traditional milling regions of the US Pacific Northwest.
- Skill gap:Gluten-free formulation chemistry expertise remains concentrated among a limited cohort of food technologists trained in wheat-alternative rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorghum Flour Market |
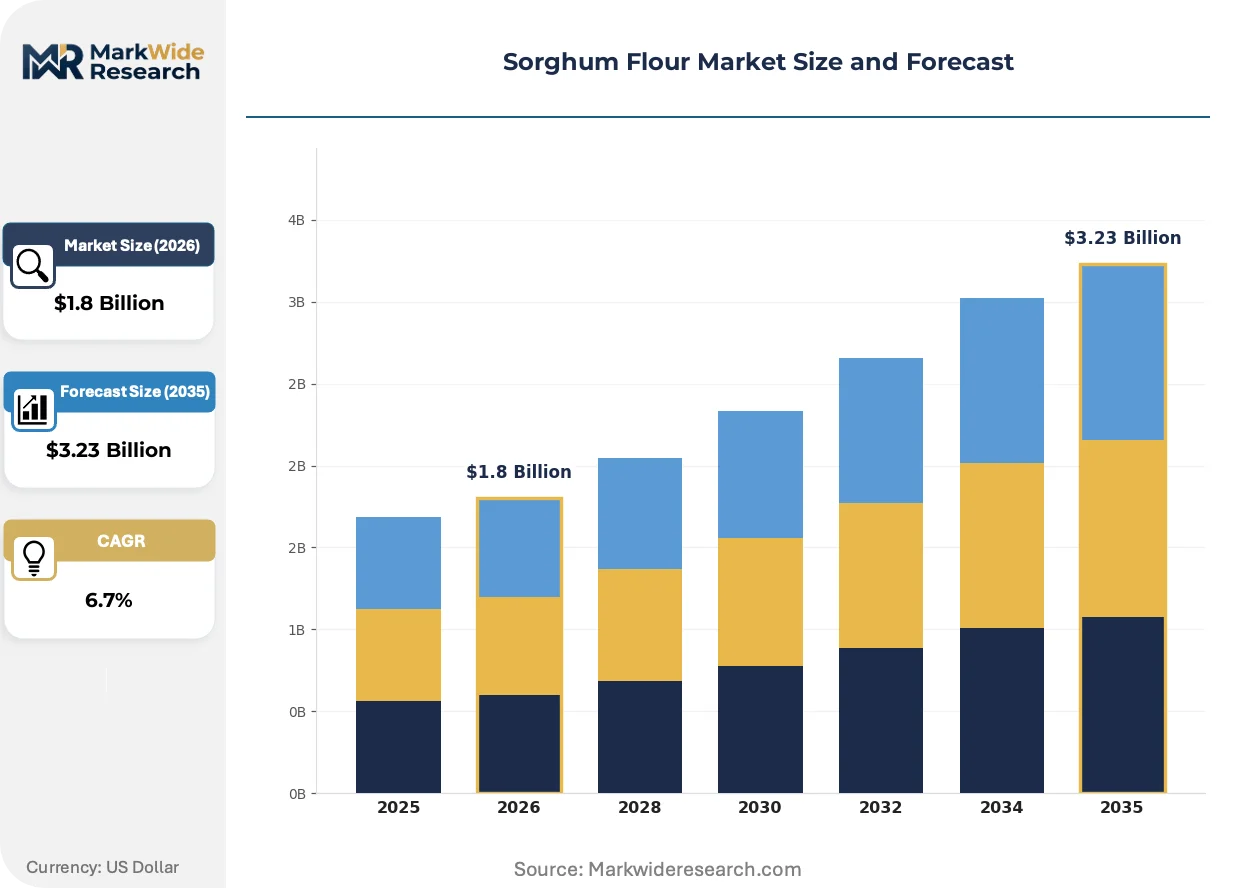
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Sorghum Flour, Conventional Sorghum Flour, Instant Sorghum Flour, Gluten-Free Sorghum Flour End User: Food Manufacturers, Bakers, Restaurants, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Application: Baking, Cooking, Snacks, Nutritional Products |
| Companies Covered | Ardent Mills, The Hain Celestial Group, Archer Daniels Midland Company, Grain Millers Inc., Bob's Red Mill Natural Foods, Cargill Inc., Firebird Artisan Mills, Agspring, Great River Organic Milling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorghum Flour Market Evolving Landscape
Extrusion and micronization technologies are redefining particle size distribution standards, while regulatory convergence around allergen disclosure is reshaping cross-border trade documentation requirements.
Extrusion pre-treatment of sorghum flour is rendering obsolete conventional hammer-milling for infant nutrition applications, where sub-100 micron particle specifications are mandatory. European pediatric formula manufacturers are adopting this technology ahead of North American counterparts. The capital barrier is consolidating processing capacity among industrial-scale operators capable of justifying equipment expenditure.
EU REACH chemical compliance frameworks are extending substance disclosure requirements to food-contact materials, compelling sorghum flour exporters to document pesticide residue thresholds across the entire supply chain. This regulatory layer adds 60-90 days to export certification timelines. Organic-certified suppliers are capturing preferential sourcing agreements as conventional processors struggle with documentation burdens.
Direct-procurement contracts between food manufacturers and sorghum belt cooperatives are displacing spot-market purchasing for gluten-free bakery operations. Ardent Mills and similar integrated handlers are offering technical support services as contract sweeteners. This channel shift concentrates volume among buyers with sufficient scale to commit to annual offtake agreements.
Sorghum Flour Market Segmentation
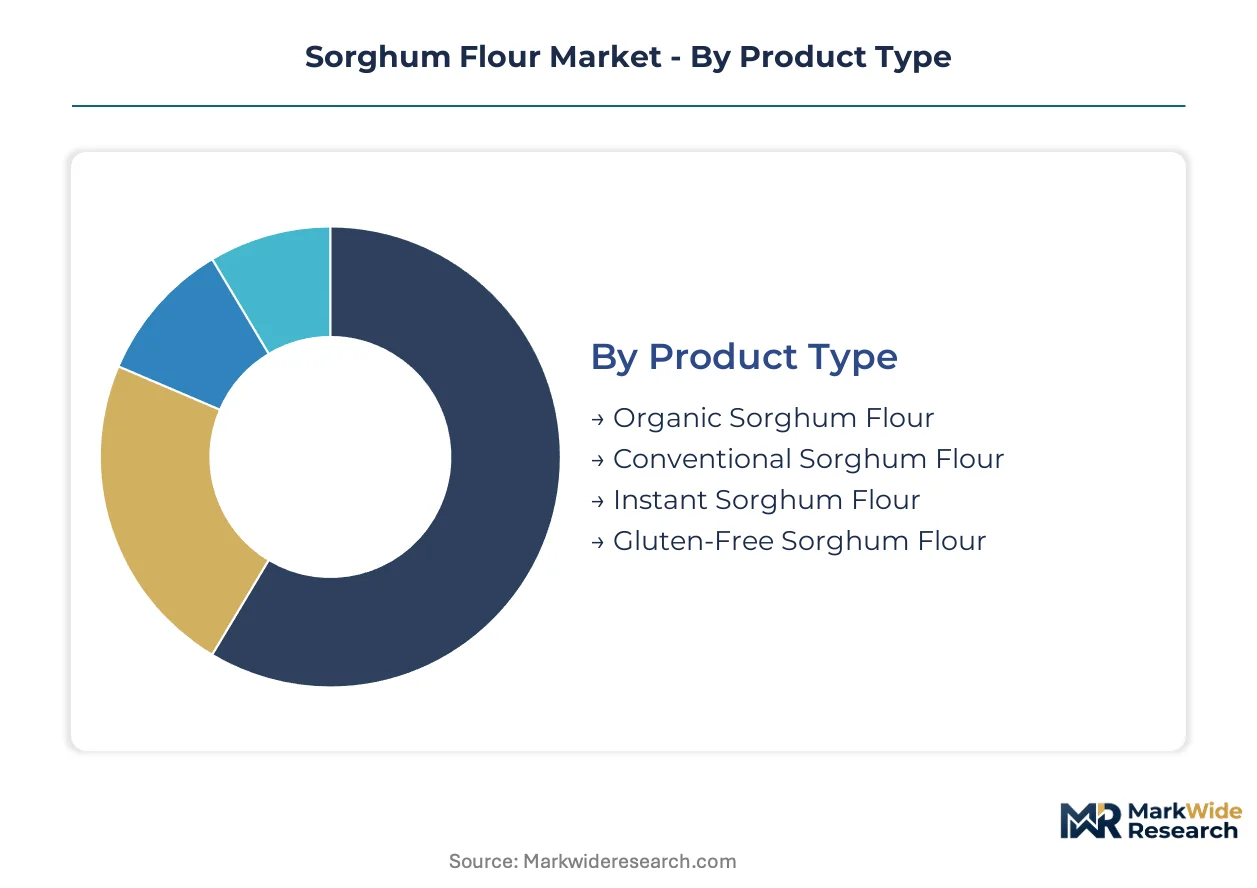
Sorghum flour segmentation reveals divergent margin structures across certification tiers and end-use channels. Product type differentiation separates premium-positioned organic supply from commodity-grade volume, while application-based demand concentrates in gluten-free bakery formulations where technical specifications command pricing power.
Product Type:
Certification tier drives cost structure and market access, with organic provenance and gluten-free verification creating distinct pricing bands across the supply base.
- Organic Sorghum Flour:Milled from USDA-certified or EU organic-compliant grain with full traceability documentation. Clean-label mandates from European and North American retailers are accelerating procurement of certified-organic supply, particularly for infant nutrition and premium bakery applications.
- Conventional Sorghum Flour:Standard-milled grain without organic certification, serving price-sensitive industrial bakers and commodity food manufacturing. Kansas, Texas, and Nebraska sorghum belt cooperatives supply this tier through direct-procurement contracts that displace spot-market purchasing.
- Instant Sorghum Flour:Pre-gelatinized flour processed through extrusion or drum-drying for instant beverage and porridge applications. African and South Asian markets consume this format for traditional food preparations.
- Gluten-Free Sorghum Flour:Segregated-milled and tested to FDA sub-20 ppm thresholds for celiac-safe labeling. Food manufacturers seeking wheat-alternative formulations specify this grade for cross-contamination-controlled supply chains.
Conventional sorghum flour holds installed capacity. Organic sorghum flour is rotating up the share rankings.
End User:
Customer type determines volume scale versus margin capture, with industrial processors demanding technical support while artisan bakers pay premiums for consistent granulation.
- Food Manufacturers:Industrial-scale buyers integrating sorghum flour into packaged gluten-free products, clinical nutrition formulations, and mass-market bakery lines. These customers require batch-to-batch consistency and documentation for FDA gluten-free labeling compliance.
- Bakers:Artisan and commercial bakery operations substituting sorghum flour for wheat in specialty bread, pastry, and dessert applications. This segment commands the highest per-unit margins where technical support and custom granulation specifications justify pricing premiums.
- Restaurants:Food service operations offering gluten-free menu items to accommodate dietary-restricted diners. Procurement concentrates through broadline distributors rather than direct miller relationships.
- Households:Consumer-packaged retail purchasers baking at home for celiac disease management or low-glycemic dietary preferences. This channel exhibits high brand loyalty to heritage stone-ground suppliers.
Food manufacturers hold installed capacity. Bakers are rotating up the share rankings.
Distribution Channel:
Channel selection reflects customer scale and service requirements, with digital platforms capturing convenience-oriented households while food service demands just-in-time replenishment.
- Online Retail:Direct-to-consumer and marketplace platforms serving geographically dispersed households and small-scale bakers. Subscription models for organic-certified flour are gaining traction among repeat purchasers.
- Supermarkets:Mass-market retail placement requiring slotting fees and promotional support, with gluten-free flour positioned in specialty diet aisles. Clean-label documentation requirements from European and North American chains are tightening supplier qualification.
- Specialty Stores:Health food retailers and co-ops emphasizing organic provenance and heritage milling credentials. Bob's Red Mill and comparable stone-ground brands dominate this channel through premium positioning.
- Food Service:Broadline distributors and cash-and-carry operators supplying restaurants and institutional kitchens. This channel demands pallet-scale minimums and compressed lead times that favor integrated grain handlers.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
Application:
Use case determines functional specifications, with baking applications requiring precise rheological properties while nutritional products prioritize protein content and glycemic response.
- Baking:Primary application encompassing bread, cake, cookie, and pastry formulations where sorghum flour substitutes for wheat. Xanthan gum or guar gum additions compensate for gluten absence, increasing formulation complexity.
- Cooking:Traditional porridge, flatbread, and sauce thickening applications in African, South Asian, and Latin American cuisines. Sub-Saharan African markets consume sorghum as whole grain; flour processing infrastructure remains nascent.
- Snacks:Extruded and baked snack formulations including crackers, chips, and puffed products. Micronization technologies enabling sub-100 micron particle specifications are expanding this segment.
- Nutritional Products:Clinical nutrition, infant formula, and metabolic health formulations leveraging sorghum flour's low glycemic index and non-allergenic properties. Diabetic and metabolic health segments are specifying sorghum flour ahead of traditional bakery substitution.
Baking holds installed capacity. Nutritional products are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Union Pacific rail network connecting Kansas grain elevators to West Coast export terminals underwrites North American sorghum flour's international reach. Port infrastructure at Houston and Los Angeles handles containerized flour shipments to Asia-Pacific and European buyers. This logistics backbone shapes regional production concentration and trade flows.
United States
Kansas, Texas, and Nebraska farmers contract directly with millers for gluten-free bakery supply chains. FDA sub-20 ppm labeling mandates compress certification timelines and force processors to integrate in-house testing. The Great Plains sorghum belt concentrates cultivation within 200 miles of Wichita-based milling infrastructure.
India
Domestic millers expand capacity to serve both local consumption and export channels as FSSAI testing protocols run parallel to FDA requirements. The Deccan Plateau sustains traditional jowar consumption while Maharashtra and Karnataka processors invest in flour-grade infrastructure. Fragmentation across small-scale millers is consolidating around export-oriented facilities in Gujarat.
Germany
EU REACH chemical compliance frameworks extend substance disclosure to food-contact materials, compelling exporters to document pesticide residues across supply chains. The country's organic food retail sector demands full traceability documentation. Hamburg port infrastructure serves as the primary European entry point for imported sorghum flour.
Brazil
The country's national agricultural regulator enforces phytosanitary standards that shape import protocols for processed grain products. Sorghum cultivation concentrates in Mato Grosso and Goiás states for animal feed, with human-grade flour processing emerging near São Paulo food manufacturing clusters. Domestic gluten-free product formulation lags North American adoption curves.
Australia
Queensland and New South Wales sorghum production supplies Asian export markets through Brisbane and Sydney port infrastructure. The country's national food standards code mandates allergen disclosure requirements that align with Codex Alimentarius frameworks. Organic certification premiums are widening as conventional grain prices stagnate across the Murray-Darling Basin.
Sorghum Flour Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The sorghum flour market exhibits tiered consolidation, with integrated grain handlers controlling volume flows and heritage millers capturing premium positioning. Three archetypes dominate: backward-integrated agricultural conglomerates, stone-ground heritage specialists, and extrusion-technology industrial processors. Competitive moves concentrate on direct-procurement contracting and certification-premium capture rather than price-based rivalry.
Within the integrated handler tier, Ardent Mills anchors North American supply chain coordination through its grain elevator network. Bob's Red Mill Natural Foods and Firebird Artisan Mills exemplify the heritage-milling archetype, commanding retail premium positioning through stone-ground credentials. Cargill Inc. occupies the industrial-scale sourcing position for food manufacturers seeking gluten-free formulation alternatives. These three entities represent divergent strategic paths: volume consolidation, artisan premiumization, and commodity-scale supply security.
| Leading Market Players |
|---|
| Ardent Mills |
| The Hain Celestial Group |
| Archer Daniels Midland Company |
| Grain Millers Inc. |
| Bob's Red Mill Natural Foods |
| Cargill Inc. |
| Firebird Artisan Mills |
| Agspring |
| Great River Organic Milling |
| Others |
Value Network & Pricing Analysis
The Union Pacific rail corridor connecting Kansas grain elevators to West Coast export terminals anchors freight cost dynamics that cascade through supply concentration and downstream price stratification. Contracting patterns between Great Plains cooperatives and integrated millers compress spot-market volatility for volume buyers while organic-certified supply commands widening premiums through documentation-intensive EU REACH compliance.
Pricing Analysis
Volume-discount tiering separates annual offtake contracts from spot purchases, with food manufacturers securing sub-market rates through direct-procurement commitments while artisan bakers absorb higher per-unit costs for custom granulation. Certification grade and geographic delivery cost drive price differentiation, with USDA organic and FDA gluten-free verification adding testing and traceability overhead. Pricing pressure stems from rice flour and tapioca starch substitution in price-sensitive industrial formulations. Food manufacturers exhibit highest price sensitivity due to formulation cost targets, while specialty retailers show lowest sensitivity where heritage credentials justify premiums.
Supply Chain Analysis
Contract-manufacturing concentration rests with Ardent Mills, Cargill Inc., and integrated grain handlers controlling elevator-to-mill infrastructure across the US Great Plains. Geographic supply concentrates in the United States, India, and Australia, with Kansas-Texas-Nebraska sorghum belt farms feeding North American processing capacity. Raw material dependencies center on drought-vulnerable sorghum grain, xanthan gum for gluten-free formulation, and certified organic seed stock. Single-source vulnerability runs through concentrated Great Plains cultivation exposed to climate volatility. Distribution runs through direct-procurement contracts displacing spot markets, with broadline distributors serving food service and online platforms capturing household demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sorghum flour incumbents face substitution defense against rice flour and tapioca starch undercutting in industrial bakery channels, requiring strategic repositioning around certification premiums and technical service differentiation.
For Market Incumbents: Pre-empt rice flour substitution by embedding formulation chemists within food manufacturer R&D teams, converting technical support into switching costs. Anchor backward integration into certified organic cultivation to capture widening USDA premium spreads and secure supply chain transparency for EU REACH documentation requirements. Defend against margin compression through exclusive annual contracting that locks volume before harvest volatility materializes.
For New Entrants and Emerging Players: Pursue Sub-Saharan African flour processing infrastructure where whole-grain consumption patterns create first-mover positioning for industrial millers. Target instant sorghum flour formats in South Asian and African traditional food markets ahead of extrusion technology consolidation. Enter through equipment-light toll milling arrangements with existing grain cooperatives rather than greenfield capacity builds.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural conglomerates with underutilized sorghum milling assets and dormant organic certification pathways. Long-term viability hinges on clean-label mandate durability across European and North American retail channels. Watch FSSAI-FDA harmonization progress as inflection signal for Indian export-oriented facility valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures widening USDA certification premiums and secures EU REACH traceability documentation. |
| In-House Gluten Testing Capabilities | Compresses FDA sub-20 ppm certification timelines and reduces third-party laboratory expenditure duplication. |
| Extrusion Technology Deployment | Enables sub-100 micron particle specifications for infant nutrition and clinical formulation contracts. |
| Direct-Procurement Contracting | Displaces spot-market purchasing and concentrates volume among scale-capable annual offtake committers. |
| Blockchain Traceability Implementation | Supports real-time quality verification for export shipments to EU REACH-compliant buyers. |
Research Methodology
A spread of perspectives from grain elevator operators, food manufacturer procurement leads, gluten-free bakery technologists, and organic certification auditors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through USDA organic certification databases, FDA gluten-free labeling guidance documents, EU REACH substance disclosure frameworks, and Kansas-Texas-Nebraska cooperative contracting records. Bottom-up volume estimates from milling capacity utilization triangulated against top-down demand projections from end-use consumption patterns.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning certification tier, end-user channel, distribution format, and application use case. CAGRs derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Industry-specific forecast inputs included sorghum belt planting intentions, drought cycle frequency patterns, and clean-label retail mandate adoption curves.
Macroeconomic conditions sit as an overlay; deviation in grain commodity price volatility, freight rate fluctuations, or organic certification cost inflation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and substitution elasticity in industrial bakery formulations. Quarterly review of FDA certification backlog data, EU REACH substance list updates, and Great Plains precipitation indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Low Fat Rice Market
Grains
Wild Rice Market
Grains
White Beans Market
Grains
Ghana Grain Market
Grains
Triticale Market
Grains
China Wheat Protein Market
Grains
Global Wheat Market
Grains
Asia Pacific Maize Market
Grains
North America Wheat Flour Market
Grains
Green Pea Grits Market
Grains
Argentina Grains Market
Grains
South America Rice Market
Grains
Bangladesh Rice Market
Grains
Asia Pacific Wheat Protein Market
Grains
Egypt Rice Market
Grains
North America Oats Market