
 Millets Market | 2026-2036
Millets Market Size, Share, and Industry Trends Forecast 2026-2036
Millets Market Analysis
End-use demand is shifting from traditional household consumption toward packaged food and nutraceutical applications. Cargill, Incorporated leverages its grain handling infrastructure to secure supply from African and South Asian origins. Archer Daniels Midland Company sustains ingredient innovation through its specialty milling operations for gluten-free formulations. Nestlé S.A. competes in the breakfast cereal segment with millet-based product lines targeting European health-conscious consumers.
Millets comprise a group of small-seeded cereal crops including foxtail, pearl, finger, and barnyard varieties, typically containing higher protein, fiber, and mineral content than refined wheat or rice, with primary commercial purpose as human food, animal feed, and functional ingredients. Pearl millet occupies the largest volume share due to its drought tolerance and established cultivation across the Sahel and Rajasthan. Foxtail millet leads in East Asian processing for brewing and snack applications. The flour production application anchors margin pools as bakeries reformulate for clean-label and allergen-free positioning.
The USDA and India's FSSAI regulate millet grading, pesticide residue limits, and organic certification pathways that determine export eligibility and retail placement. The EU's REACH and EFSA novel food assessments shape which processed millet ingredients enter European supply chains. Stakeholders must monitor how carbon accounting rules and water-stress indices redirect procurement toward low-input millet varieties.
Market Dynamics
India's PLI scheme for nutri-cereals and the EU's Farm to Fork Strategy are redirecting procurement flows toward formalized smallholder networks, compressing the informal trading layer that historically dominated millet commerce.
Growth Catalysts
- India's Shree Anna integration:Government procurement for school feeding programs and public distribution systems is creating guaranteed offtake volumes that stabilize farmer planting decisions.
- Clean-label reformulation:European bakeries and gluten-free manufacturers are substituting refined wheat with foxtail and pearl millet flours to meet allergen-free positioning requirements.
- Drought tolerance premiums:Rajasthan and Sahel-region pearl millet commands preferential sourcing from ingredient buyers facing water-stress disclosure mandates under emerging carbon accounting frameworks.
Market Restraints
- Input cost volatility:Fertilizer and irrigation equipment prices fluctuate with energy markets, squeezing margins for rain-fed smallholders who lack storage infrastructure.
- Supply concentration risk:Over half of traded pearl millet volume originates from Rajasthan and Maharashtra, exposing processors to monsoon-dependent yield variability.
- Substitution threat:Quinoa and amaranth occupy similar nutritional positioning in North American and European health-food channels, competing for shelf space and formulation slots.
Strategic Opportunities
- Nutraceutical extraction:Polyphenol and dietary fiber concentrates from finger millet offer high-margin ingredient pathways for functional food manufacturers targeting metabolic health positioning.
- EU Green Deal procurement:Carbon-sequestering crop status under the Farm to Fork Strategy unlocks premium contract structures for African-origin millet meeting organic certification pathways.
- E-commerce direct channels:Specialty flour and ready-to-cook formats bypass traditional commodity auctions, capturing value-add margins previously absorbed by layered intermediaries.
Industry Challenges
- Post-harvest processing skill gaps:Dehulling and milling operations require specialized equipment calibration that rural cooperatives struggle to maintain without technical extension support.
- FSSAI-EU regulatory misalignment:Divergent pesticide residue limits and organic certification timelines create compliance friction for exporters serving both destination markets simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Millets Market |
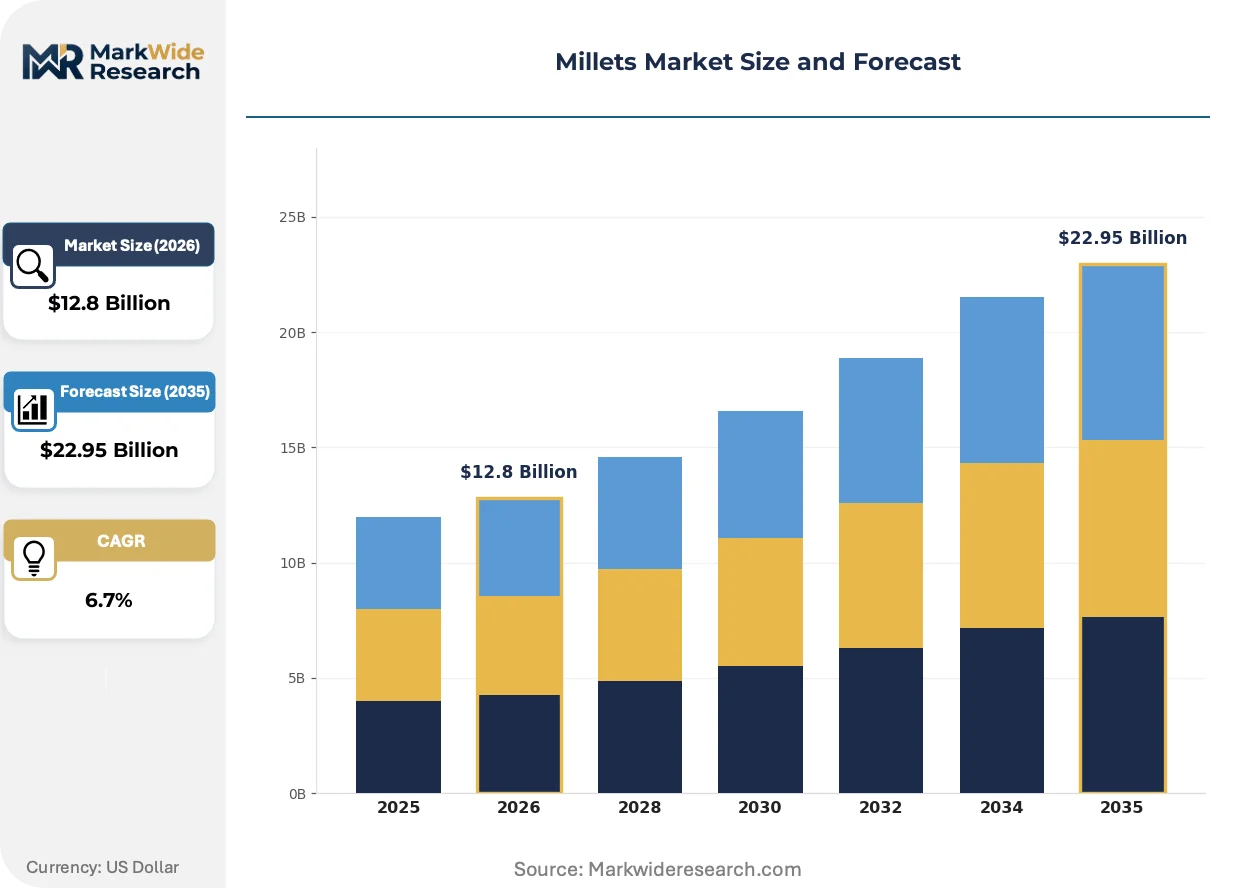
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foxtail Millet, Pearl Millet, Finger Millet, Barnyard Millet End Use: Food & Beverage, Animal Feed, Nutraceuticals, Food Ingredients Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Baking, Breakfast Cereals, Snack Foods, Flour Production |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Nestlé S.A., Bunge Limited, Olam International Limited, General Mills, Inc., ITC Limited, Tata Consumer Products Limited, Bob’s Red Mill Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Millets Market Emerging Trajectories
Processing technology and procurement transparency are converging to transform millet from a subsistence crop into a traceable, specification-grade ingredient for packaged food manufacturers.
Extrusion technology is unifying texturization and nutrient retention in single-pass processing, enabling snack and breakfast cereal manufacturers to incorporate whole millet without sacrificing shelf stability or mouthfeel. European contract manufacturers are retrofitting lines originally designed for corn and rice. This convergence is compressing the capital barrier that previously restricted millet processing to traditional stone-milling operations.
REACH and EFSA novel food assessments are tightening entry requirements for processed millet ingredients entering European supply chains, forcing African and South Asian exporters to upgrade laboratory testing capabilities and documentation systems. The flour and concentrate segment faces the steepest compliance burden. Indian processors are responding by consolidating testing partnerships with EU-accredited laboratories in Mumbai and Hyderabad.
Buyer concentration among multinational food manufacturers is shortening contract cycles and demanding real-time traceability from farm gate to finished product. Direct sourcing agreements are displacing auction-based procurement in Rajasthan and Maharashtra. This shift is most visible in the organic and baby food verticals, where Nestlé and Danone subsidiaries specify village-level provenance requirements.
Millets Market Segmentation
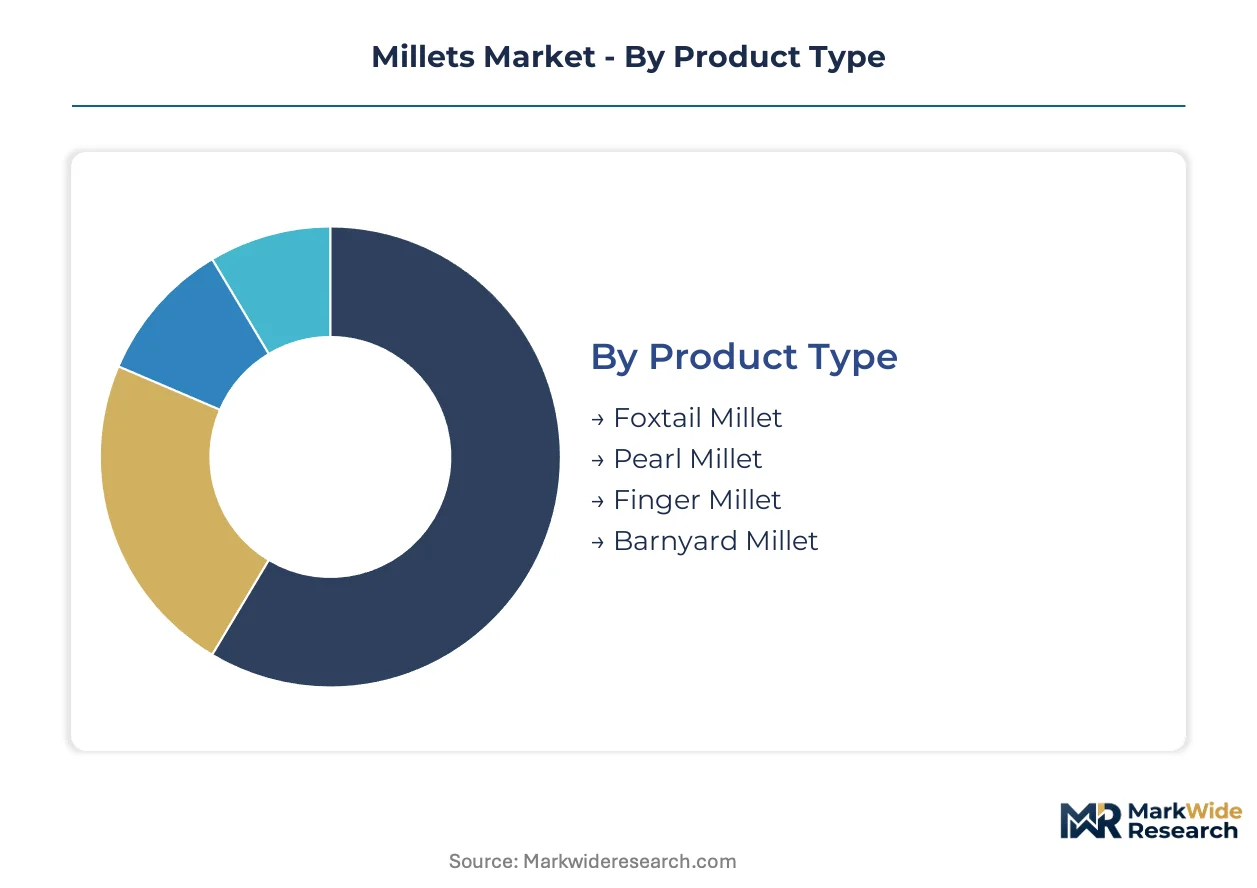
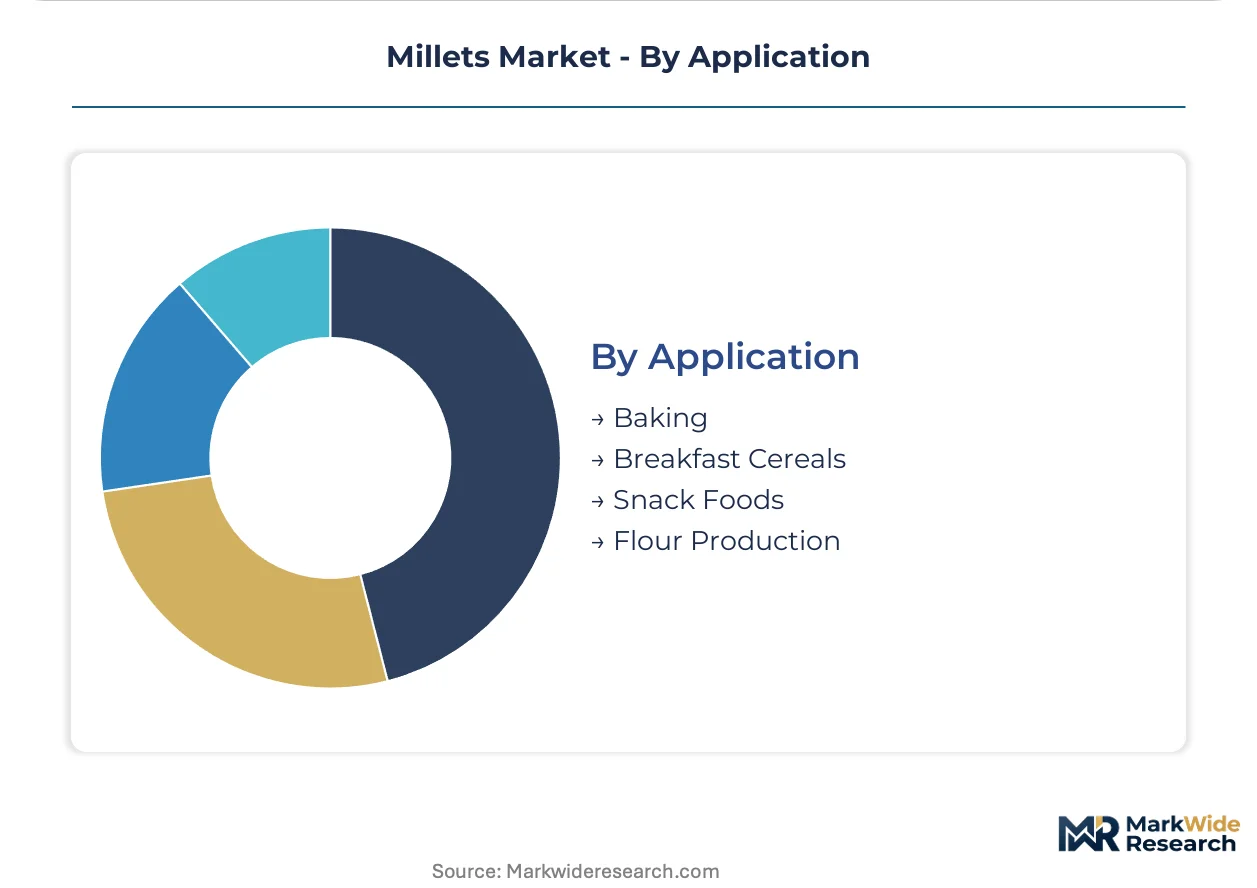
Segmentation in the millets market determines which value pools attract capital investment and which remain trapped in commodity trading. Certification requirements, processing intensity, and channel margin structures vary sharply across product types and end-use applications.
Product Type:
FSSAI organic certification and EU REACH compliance create divergent approval burdens across varieties, with drought-tolerant landraces facing lighter documentation loads than novel processed forms.
- Pearl Millet:Drought-hardy C4 grain with 11-12% protein content and established dehulling infrastructure across Rajasthan and the Sahel. Demand concentrates in gluten-free flour applications for European bakeries reformulating under allergen disclosure mandates, though monsoon dependency in Maharashtra and Rajasthan creates supply volatility that processors hedge through forward contracts.
- Foxtail Millet:Small-seeded variety with superior amylopectin structure suited to extrusion and brewing applications. East Asian processors in Japan and South Korea command premium positioning for foxtail-derived ingredients in functional snack formulations, with METI and MFDS food additive approvals governing import eligibility.
- Finger Millet:High-calcium grain (344mg/100g) traditional to East African and South Indian cultivation systems, requiring specialized milling equipment for ragi flour production.
- Barnyard Millet:Fastest-maturing variety (45-60 days) with lowest water footprint, cultivated primarily in Uttarakhand and Nepal for domestic consumption and limited export.
Pearl Millet sits at the top of the volume ranking, with Foxtail Millet climbing the fastest.
End Use:
Margin structures stratify sharply between bulk animal feed contracting and specification-grade nutraceutical extraction, with the latter demanding laboratory partnerships that few African or South Asian processors have assembled.
- Food & Beverage:Packaged goods manufacturers including breakfast cereal and gluten-free bakery verticals specify whole-grain or flour forms with defined particle size distributions. Nestlé and Danone subsidiaries enforce village-level traceability requirements that compress traditional intermediary layers in Rajasthan procurement networks.
- Nutraceuticals:Polyphenol and dietary fiber concentrates from finger millet command ingredient premiums for metabolic health positioning, though EFSA novel food assessments and FDA GRAS self-determination create dual compliance burdens that filter out smaller extractors.
- Animal Feed:Compound feed manufacturers in Gujarat and Haryana blend pearl millet with oilseed meals for poultry rations, purchasing through auction markets without organic or traceability premiums.
- Food Ingredients:Specialty millers supply specification-grade flours to contract manufacturers, with BIS and FSSAI grading determining eligibility for institutional catering and export channels.
Food & Beverage captures the dominant revenue share, while Nutraceuticals expands most quickly.
Distribution Channel:
Channel selection dictates working capital intensity and margin retention, with direct-to-consumer formats requiring inventory systems that rural cooperatives rarely maintain.
- Wholesale:Auction-based procurement through Agricultural Produce Market Committees in Maharashtra and Rajasthan dominates pearl millet volume, with price discovery transparent but quality specification loose and traceability minimal.
- Online Retail:Direct channels for specialty flour and ready-to-cook formats bypass layered intermediaries, though logistics partnerships with Delhivery and Blue Dart determine reach into Tier-2 and Tier-3 Indian cities.
- Supermarkets:Modern trade placement in Reliance Fresh and BigBasket requires FSSAI-licensed packaging and barcode compliance that informal millers cannot satisfy.
- Specialty Stores:Organic and health-food retailers in Bangalore and Mumbai stock heritage millet varieties with story-driven provenance claims, sourcing through curated aggregator platforms.
Wholesale retains the volume lead, with Online Retail gaining share fastest.
Application:
Processing technology requirements fragment the application landscape, with extrusion-capable manufacturers capturing value that stone-millers cannot access.
- Flour Production:Bakeries across Germany and France substitute refined wheat with foxtail and pearl millet flours for clean-label positioning, with particle size specifications (typically 250-400 micron) enforced through contract terms that favor integrated millers over traditional chakki operations.
- Breakfast Cereals:Extrusion technology unifies texturization and nutrient retention in single-pass processing, enabling whole millet incorporation without shelf stability sacrifice; European contract manufacturers retrofit corn and rice lines to accommodate smaller batch sizes.
- Snack Foods:Puffed and baked formats target Indian urban consumers with heritage positioning, with flavor innovation (millet-based namkeen, energy bars) driving trial in Mumbai and Delhi metropolitan markets.
- Baking:Artisan bakeries in Pune and Bengaluru experiment with millet sourdough formulations, though gluten-free structure challenges limit industrial scale-up without hydrocolloid additives.
Flour Production anchors current volume, with Breakfast Cereals showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting millet processing capacity toward jurisdictions with lighter organic certification burdens, as African and South Asian exporters face divergent pesticide residue limits across destination markets.
India
The FSSAI's Shree Anna integration drives procurement volumes through school feeding programs and public distribution systems. Rajasthan and Maharashtra anchor pearl millet cultivation, with Nagpur-based millers retrofitting lines for specification-grade flour exports. The PLI scheme for nutri-cereals compresses informal trading layers into formal smallholder networks.
United States
Gluten-free bakery reformulation and ancient grain positioning in natural food channels sustain import demand for foxtail and pearl millet. The USDA's organic certification pathways determine retail placement eligibility, with Minneapolis-St. Paul distributors consolidating procurement from Indian and African origins. Clean-label mandates accelerate specification-grade contracting over commodity auction sourcing.
Germany
REACH compliance and EFSA novel food assessments filter processed millet ingredients entering European supply chains. Bavarian contract manufacturers retrofit extrusion lines for whole-millet breakfast cereals, while Hamburg-based traders navigate carbon accounting disclosures under the EU Green Deal. The Farm to Fork Strategy unlocks premium contract structures for certified organic imports.
China
Foxtail millet processing for brewing and snack applications concentrates in Shandong and Henan provinces. GB standards for grain quality and SAMR food additive approvals govern domestic circulation and export eligibility. Zhengzhou millers supply specification-grade flour to Japanese and South Korean contract manufacturers facing METI and MFDS import requirements.
Nigeria
Pearl millet cultivation across the Sahel supplies regional food security programs and informal cross-border trade. The drought-hardy crop commands preferential sourcing from European buyers facing water-stress disclosure mandates. Kano-based aggregators struggle with post-harvest processing skill gaps that limit entry into formal export channels.
Millets Market Vendor Landscape
Backward integration into grain handling infrastructure dominates the current landscape, as processors secure supply from drought-prone origins to hedge yield variability. The vendor base stratifies between multinational agribusiness conglomerates with integrated origination networks and regional millers with specialty certification capabilities. Three archetypes prevail: scale-driven grain traders with pan-origination logistics, specialty food manufacturers with clean-label positioning, and cooperative-backed processors with government contract access. M&A activity and capacity expansion in extrusion technology represent the dominant competitive vectors, compressing capital barriers that previously restricted millet processing to traditional stone-milling operations.
Within the multinational agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven origination archetypes with grain handling infrastructure spanning African and South Asian supply bases. Nestlé S.A. occupies a position representing the specialty food manufacturer archetype, competing in breakfast cereal and baby food verticals with traceability requirements that compress traditional intermediary layers. These three entities anchor the competitive structure without exhausting the vendor landscape, as regional cooperatives and contract manufacturers retain significant share in specification-grade flour and nutraceutical extraction segments.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Nestlé S.A. |
| Bunge Limited |
| Olam International Limited |
| General Mills, Inc. |
| ITC Limited |
| Tata Consumer Products Limited |
| Bob's Red Mill Natural Foods |
| Others |
Supply Flow & Price Mechanics
Extrusion technology adoption across European contract manufacturers is compressing processing cost curves while simultaneously concentrating procurement power among multinationals with capital to retrofit legacy lines. This dual effect reshapes margin distribution between Rajasthan smallholders and specification-grade flour exporters.
Pricing Analysis
Retailer markup compression in Indian modern trade channels is forcing three-tier pricing structure across organic certified, FSSAI-graded, and unbranded commodity tiers. Price differentiation hinges on EU REACH compliance status and volume scale in forward contracting. Cost compression in the unbranded tier is intensifying because monsoon yield variability drives spot market volatility. Compound feed manufacturers in Gujarat exhibit highest price sensitivity, while Nestlé and Danone subsidiaries accept premium positioning for traceability guarantees.
Supply Chain Analysis
Skilled equipment calibration specialists in Maharashtra and Karnataka remain scarce relative to extrusion capacity expansion timelines. Pearl millet supply concentrates in Rajasthan, Maharashtra, and the Nigerian Sahel belt. Raw material flows draw from monsoon-dependent smallholder networks, phosphate fertilizer inputs, and irrigation equipment spare parts. Single-source vulnerability runs through Nagpur-based millers controlling specification-grade flour exports. Distribution runs through Agricultural Produce Market Committee auction markets layered with aggregator platforms for organic verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The millets market functions as a geographic-arbitrage play where EU Green Deal carbon-accounting premiums for African-origin organic millet exceed Indian FSSAI compliance costs by meaningful margins.
For Market Incumbents: Anticipate quinoa and amaranth substitution threats in North American health-food channels by accelerating backward integration into drought-tolerant landrace seed programs. Prioritize certification investment in EU REACH and EFSA novel food pathways to lock out regional millers lacking laboratory partnerships. Channel control through direct sourcing agreements with Rajasthan cooperatives defends margin position against auction-based price volatility.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian e-commerce direct channels offers white-space capture for ready-to-cook formats bypassing layered intermediaries. Target barnyard millet from Uttarakhand for fastest-maturity positioning in specialty organic verticals. Deploy curated aggregator platform partnerships with Bangalore and Mumbai health-food retailers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among cooperative-backed processors with government contract access but lacking extrusion technology. Long-term viability hinges on carbon-sequestering crop status formalization under emerging water-stress disclosure mandates. Watch for FSSAI-EU regulatory alignment progress as the inflection signal indicating export channel expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Line Retrofit | European contract manufacturers capture whole-millet breakfast cereal margins previously restricted to corn and rice processors. |
| Direct Sourcing Agreement | Nestlé and Danone subsidiaries enforce village-level provenance requirements that compress traditional Rajasthan intermediary layers. |
| EU-Accredited Laboratory Partnership | Indian processors in Mumbai and Hyderabad overcome EFSA novel food assessment barriers blocking African and South Asian exporters. |
| Organic Certification Pathway Investment | Farm to Fork Strategy premium contract structures reward African-origin millet meeting REACH compliance timelines. |
| E-commerce Logistics Integration | Specialty flour and ready-to-cook formats leverage Delhivery and Blue Dart partnerships to reach Tier-2 and Tier-3 Indian cities. |
Methodological Framework
Bottom-up food and beverage end-use modeling reconciled against top-down grain origination tracking forms the analytical core of this study. Primary interviews with Rajasthan cooperative managers, Nagpur miller technical directors, European bakery procurement leads, and FSSAI regulatory officers combined with secondary validation from USDA grading standards, EU REACH substance databases, Agricultural Produce Market Committee auction records, and Indian customs export filings. Triangulation across stakeholder inputs and documentary sources ensures cross-verified volume and value estimates.
Historical trendline analysis of pearl and foxtail millet trade flows anchored projection frameworks across the modeling period. Segmentation dimensions modeled include product variety, end-use application, distribution channel format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline consumption estimates, with drought tolerance premiums and clean-label reformulation rates serving as industry-specific forecast inputs.
Caveats apply where FSSAI-EU regulatory misalignment, monsoon yield variability, or quinoa substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions about PLI scheme continuity and carbon accounting rule finalization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Asia Pacific Wheat Protein Market
Grains
China Maize Market
Grains
Bangladesh Rice Market
Grains
Quinoa Flour Market
Grains
Grain-Based Flours Market
Grains
Paraguay Grains Market
Grains
Corn Market
Grains
Barley Grass Market
Grains
South Africa Grain Market
Grains
Cameroon Grains Market
Grains
Brazil Maize Market
Grains
Asia-Pacific Rice Market
Grains
Green Pea Grits Market
Grains
Pulses Market
Grains
White Rice Flour Market
Grains
Wheat Protein Market