
 Pea Grits Market | 2026-2036
Pea Grits Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Grits Market Analytics
Canada is rewriting competitive dynamics in pea grits through expanded pulse processing infrastructure across Saskatchewan and Manitoba. Roquette Frères leverages its European extrusion expertise to sustain premium positioning in specialty milling. AGT Food and Ingredients anchors North American supply with integrated farm-to-ingredient operations. Puris Foods differentiates through domestic U.S. organic pea cultivation networks.
Pea grits consist of coarsely milled yellow or green pea fragments, typically retaining 20-25% protein content and processed through dry fractionation or air-classification milling systems. The ingredient functions primarily as a texturizing agent and protein fortifier in gluten-free and plant-based food formulations. Organic pea grits command the strongest margin pool as certification barriers limit supplier entry, while gluten-free variants show the fastest volume trajectory amid celiac-safe formulation trends. Conventional pea grits still dominate total tonnage through cost-sensitive baking and soup applications.
Health Canada and the Canadian Food Inspection Agency enforce strict allergen labeling and novel food approval pathways that determine which pea-derived ingredients reach commercial formulations. The USDA National Organic Program and FDA Food Safety Modernization Act shape U.S. market access through organic certification mandates and preventive control requirements for milling facilities. Stakeholders must monitor evolving protein content threshold definitions across North American and European regulatory frameworks to anticipate reformulation cycles and qualification barriers.
Market Dynamics
Clean-label regulatory frameworks in the European Union are forcing food manufacturers to reformulate wheat-based products with certified gluten-free alternatives, compressing supplier qualification timelines and reshaping procurement criteria across bakery and soup applications.
Growth Catalysts
- EFSA Novel Food approvals:Streamlined pathways for pea-derived ingredients accelerate commercial entry into European gluten-free formulations.
- Saskatchewan-Mantoba pulse clusters:Expanded fractionation infrastructure reduces raw material transit costs for North American processors.
- Air-classification milling:Precision particle size control enables protein content standardization demanded by contract manufacturers.
Market Restraints
- Yellow pea input volatility:Prairie drought cycles in Canada create 12-18 month price swings that compress processor margins.
- Novel food dossier costs:EFSA safety assessments require EUR 150K-400K investment, excluding smaller ingredient suppliers from EU market access.
- Fava bean substitution:Higher lysine content in fava grits displaces pea protein in select plant-based meat applications.
Strategic Opportunities
- German bakery reformulation wave:Traditional wheat-heavy product lines face mandatory allergen labeling expansions, opening volume slots for pea-fortified alternatives.
- Organic certification arbitrage:USDA National Organic Program and EU organic equivalence create dual-market pricing premiums for certified growers.
- Extrusion-texturization convergence:Twin-screw extrusion paired with high-moisture processing generates fibrous structures mimicking whole-muscle meat in plant-based cuts.
Industry Challenges
- Protein assay standardization:Divergent Kjeldahl versus Dumas methodologies across ISO, AOAC, and EU reference labs create batch rejection disputes between suppliers and buyers.
- Legacy wheat mill retrofitting:Cross-contamination protocols for gluten-free pea grits require dedicated air-handling and line-segregation investments that strain mid-cap facility budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Grits Market |
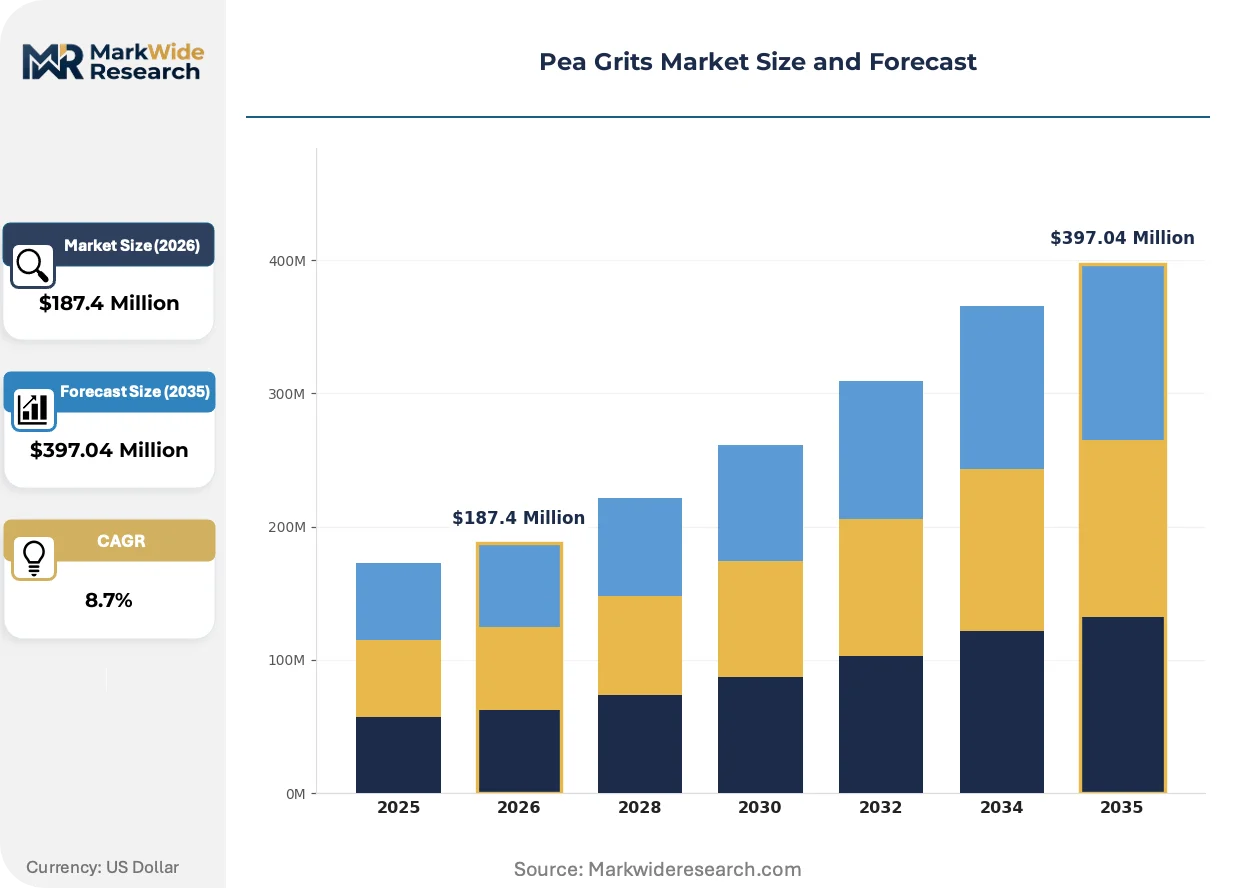
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pea Grits, Conventional Pea Grits, Gluten-Free Pea Grits, Flavored Pea Grits End Use: Baking, Soups, Snacks, Side Dishes Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Bags, Boxes, Bulk Containers, Pouches |
| Companies Covered | Roquette Frères, Ingredion Incorporated, AGT Food and Ingredients, The Scoular Company, Puris Foods, ADM, Avena Foods Limited, Best Cooking Pulses Inc., Martino Rossi SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Grits Market Evolving Landscape
Near-infrared spectroscopy deployment across milling operations is digitizing quality assurance workflows, compressing protein and moisture verification from hours to minutes and enabling real-time batch release decisions.
Sensor arrays integrated into air-classification systems track particle distribution continuously. Major European extrusion houses now demand certificate-of-analysis data streams before truck unloading. This infrastructure investment is digitizing supplier-buyer information exchange, reducing dispute resolution cycles and locking in preferred vendor status for early adopters.
REACH registration requirements for novel protein isolates are tightening purity thresholds for heavy metals and mycotoxins. German food manufacturers now require third-party laboratory verification beyond standard HACCP documentation. The bakery segment bears the highest compliance burden, with reformulation timelines extending 18-24 months to secure qualified ingredient status.
Ingredient procurement teams are consolidating supplier rosters from 12-15 vendors to 3-4 strategic partners with integrated farm-to-milling traceability. Large contract manufacturers in France and the Netherlands now mandate blockchain-tracked lot records. This concentration pattern favors vertically integrated processors with captive organic acreage and in-house extrusion capability.
Pea Grits Market Segmentation
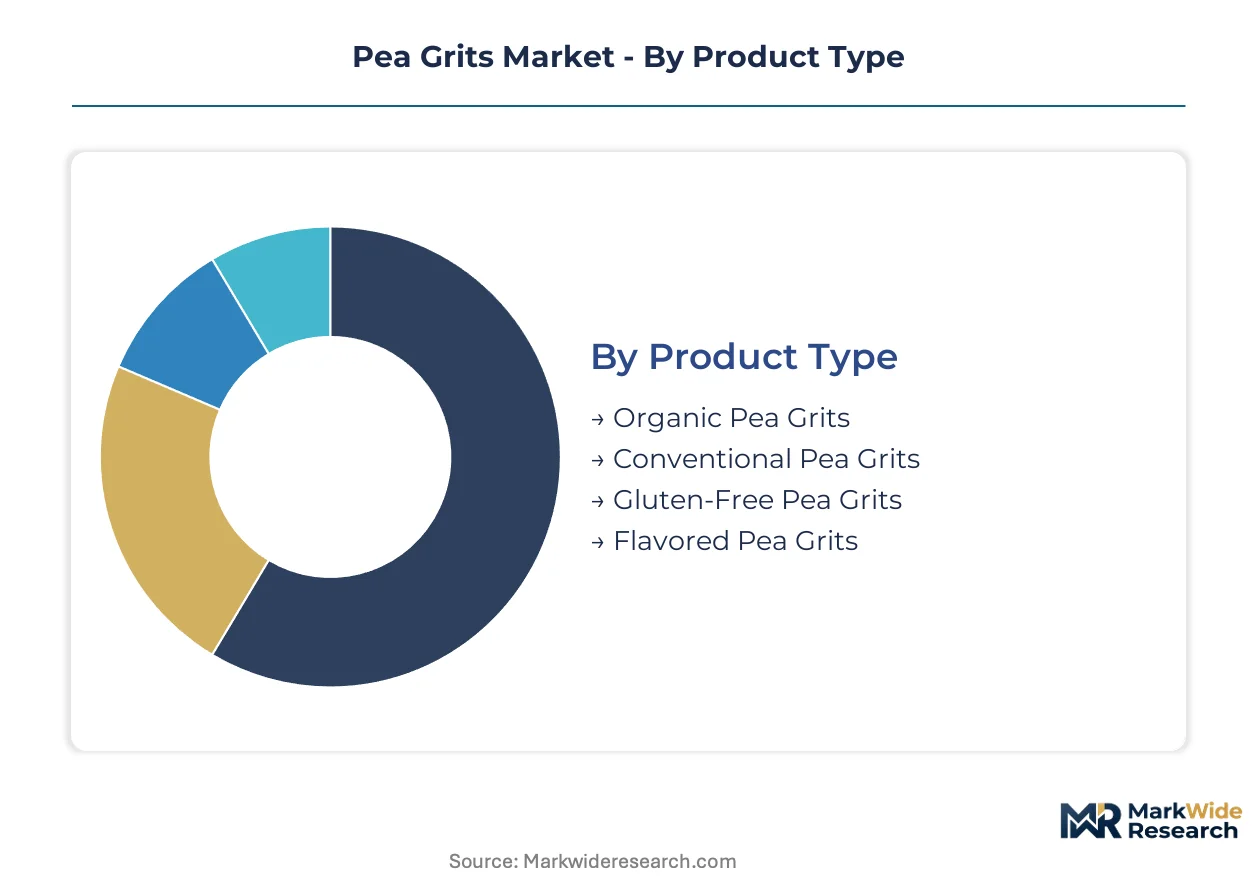
Pea grits segmentation reveals how certification tiers, application requirements, and channel economics partition value capture across the supply chain. Manufacturers configure milling specifications and packaging formats to match the technical and compliance demands of distinct buyer clusters.
Product Type:
Cost tier structures the competitive landscape, with certification barriers and protein standardization requirements creating sharp margin differentiation across grades.
- Organic Pea Grits:Derived from certified organic yellow or green peas with full traceability from farm to mill. German and French bakery manufacturers absorb premium pricing to meet EU organic labeling requirements and secure shelf placement in health-focused retail channels.
- Gluten-Free Pea Grits:Processed in dedicated facilities with validated allergen control protocols and batch testing below 20 ppm gluten threshold. Celiac-safe formulation demand in European bakery applications is climbing the fastest as mandatory allergen labeling expansions force wheat product reformulation.
- Conventional Pea Grits:Standard milling of non-certified peas for cost-sensitive soup and baking applications where protein fortification takes priority over certification status.
- Flavored Pea Grits:Pre-seasoned variants incorporating herb or spice blends targeting convenience-oriented side dish preparation in North American retail.
Organic pea grits hold installed capacity. Gluten-free pea grits is rotating up the share rankings.
End Use:
Application-specific protein content and particle size requirements drive milling configuration decisions and contract pricing structures.
- Baking:Requires precise air-classified particle distribution for uniform hydration and crumb structure in gluten-free bread and pastry formulations. German industrial bakeries specify 20-25% protein content with tight moisture control for automated dough handling systems.
- Snacks:Extrusion-texturized pea grits generate expanded or sheeted structures in savory cracker and puff applications. Snack manufacturers in the Netherlands and Belgium prioritize protein fortification claims for plant-based product lines.
- Soups:Coarser grit fractions provide thickening and mouthfeel in ready-to-serve and dry soup mixes where cost minimization dominates procurement.
- Side Dishes:Whole or cracked pea grits substitute for rice or couscous in prepared meal components targeting flexitarian dietary patterns.
Baking commands the deepest technical qualification. Snacks is expanding most quickly as extrusion technology converges with protein fortification trends.
Distribution Channel:
Customer type and purchase frequency determine packaging formats, margin structures, and supplier relationship intensity.
- Supermarkets:High-volume retail placement demands branded consumer packaging with nutritional callouts and recipe integration. French and German supermarket chains now dedicate shelf space to certified gluten-free and organic pea grits in the alternative flour aisle.
- Health Food Stores:Specialty retail channels emphasize organic certification, local sourcing narratives, and dietitian endorsement for celiac and allergen-sensitive consumers.
- Online Retail:Direct-to-consumer and marketplace platforms enable subscription models and bulk purchasing for home bakers and small foodservice operators.
- Specialty Stores:Ethnic grocery and gourmet food retailers stock imported or artisan-milled pea grits for Eastern European and Mediterranean culinary traditions.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
Packaging Type:
Volume scale and handling requirements separate industrial procurement from retail-ready configurations.
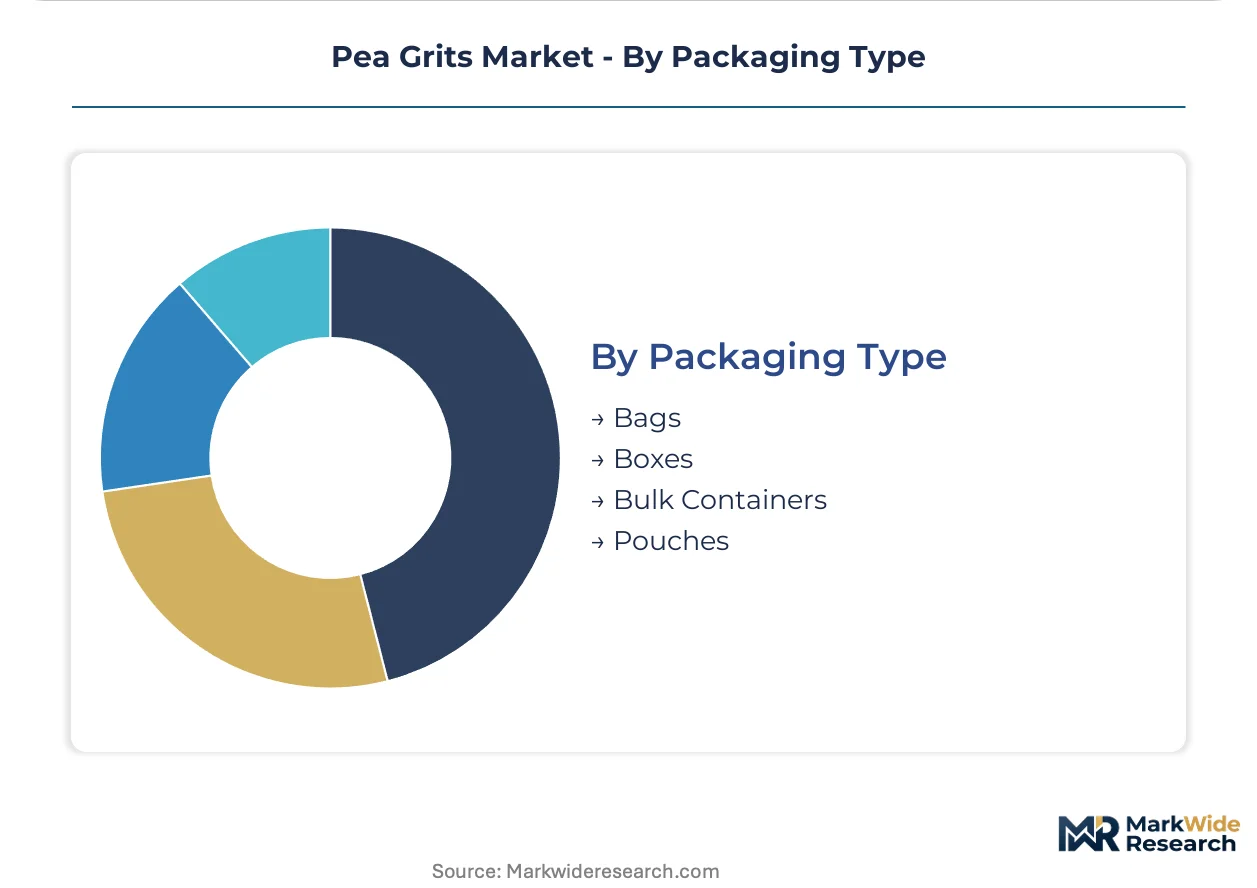
- Bulk Containers:1,000 kg totes and supersacks for industrial bakery and extrusion facilities with pneumatic conveying systems. Canadian and U.S. contract manufacturers specify food-grade liners with nitrogen flush for extended shelf stability.
- Bags:Multi-wall paper or plastic retail bags in 500g to 2kg formats for supermarket and health food store placement with reseal features.
- Pouches:Stand-up flexible packaging with high-barrier films for flavored variants and single-serve convenience positioning.
- Boxes:Carton-overwrap formats for premium organic lines with window panels and recipe card inserts.
Bulk containers hold installed capacity. Pouches is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial bakeries consume pea grits as certified gluten-free wheat substitutes, while Canadian processors prioritize organic certification arbitrage between USDA and EU equivalency agreements. This consumption-mix differential fragments procurement specifications across Atlantic supply chains.
Germany
Mandatory allergen labeling expansions under the EU Food Information to Consumers Regulation force wheat-heavy bakery reformulation. EFSA novel food dossier requirements compress supplier qualification timelines to 18-24 months. The Baden-Württemberg and Bavaria industrial baking clusters absorb premium-priced organic pea grits to secure health-focused retail shelf placement.
Canada
Saskatchewan and Manitoba pulse processing infrastructure expansion reduces raw material transit costs for North American contract manufacturers. Health Canada and the Canadian Food Inspection Agency enforce strict allergen labeling and novel food approval pathways. Prairie drought cycles create 12-18 month yellow pea input price volatility that compresses processor margins.
United States
Domestic organic pea cultivation networks in the upper Midwest supply certified ingredients for dual USDA-EU organic market access. The FDA Food Safety Modernization Act mandates preventive control requirements for milling facilities. Twin-screw extrusion houses in the Pacific Northwest demand real-time certificate-of-analysis data streams before truck unloading.
France
Industrial bakeries in the Île-de-France and Hauts-de-France regions reformulate traditional product lines under expanded EU allergen labeling frameworks. REACH registration requirements tighten purity thresholds for heavy metals and mycotoxins in novel protein isolates. Large contract manufacturers now mandate blockchain-tracked lot records, consolidating supplier rosters to 3-4 strategic partners.
Netherlands
Snack manufacturers in the Randstad prioritize protein fortification claims for plant-based product lines utilizing extrusion-texturized pea grits. EFSA streamlined novel food approval pathways accelerate commercial entry into European gluten-free formulations. Belgian and Dutch extrusion facilities specify air-classified particle distribution for uniform expanded structure generation.
Pea Grits Market Competitive Landscape
Capability concentration sits with European extrusion specialists; scale advantage sits with North American integrated processors. The vendor base organizes into three tiers: multinational ingredient conglomerates with captive pulse sourcing, regional millers with dedicated gluten-free facilities, and organic-certified specialists with farm-level traceability. Dominant competitive moves include backward integration into prairie pulse production and strategic partnerships with contract manufacturing networks.
Among the named players, Roquette Frères exemplifies European extrusion capability concentration, while AGT Food and Ingredients anchors North American supply with integrated farm-to-ingredient operations. Puris Foods occupies a position within the organic-certified specialist tier through domestic U.S. cultivation networks.
| Leading Market Players |
|---|
| Roquette Frères |
| Ingredion Incorporated |
| AGT Food and Ingredients |
| The Scoular Company |
| Puris Foods |
| ADM |
| Avena Foods Limited |
| Best Cooking Pulses Inc. |
| Martino Rossi SpA |
| Others |
Value Network & Pricing Analysis
Undercapacity in Saskatchewan-Mantoba fractionation facilities is compressing processor margins and forcing buyers toward longer-term contract structures to secure volume commitments.
Pricing Analysis
Long-term offtake agreements dominate procurement between Canadian processors and European extrusion houses, insulating buyers from prairie drought-driven input volatility. Price differentiation rests on certification tier—organic EU-equivalent commands substantial premiums over conventional grades—and volume scale, with industrial bakeries locking in multi-year supply. Cost compression in conventional pea grits is intensifying as fava bean substitutes gain traction in plant-based meat formulations. Small health food retailers show highest price sensitivity, while German industrial bakeries absorb premiums for qualified gluten-free supply.
Supply Chain Analysis
EU REACH registration requirements for novel protein isolates restrict market entry for non-compliant suppliers, channeling flow toward established processors with dossier completion. Geographic supply concentrates in Canada, France, and the Netherlands, with prairie yellow pea cultivation feeding North American fractionation and Roquette's European extrusion network serving bakery demand. Raw material dependencies include prairie-grown yellow peas, specialized air-classification milling equipment, and nitrogen-flush food-grade liners. Single-source vulnerability runs through Saskatchewan-Mantoba pulse clusters exposed to drought cycles. Distribution runs through bulk totes for industrial extrusion houses and multi-wall retail bags for supermarket placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
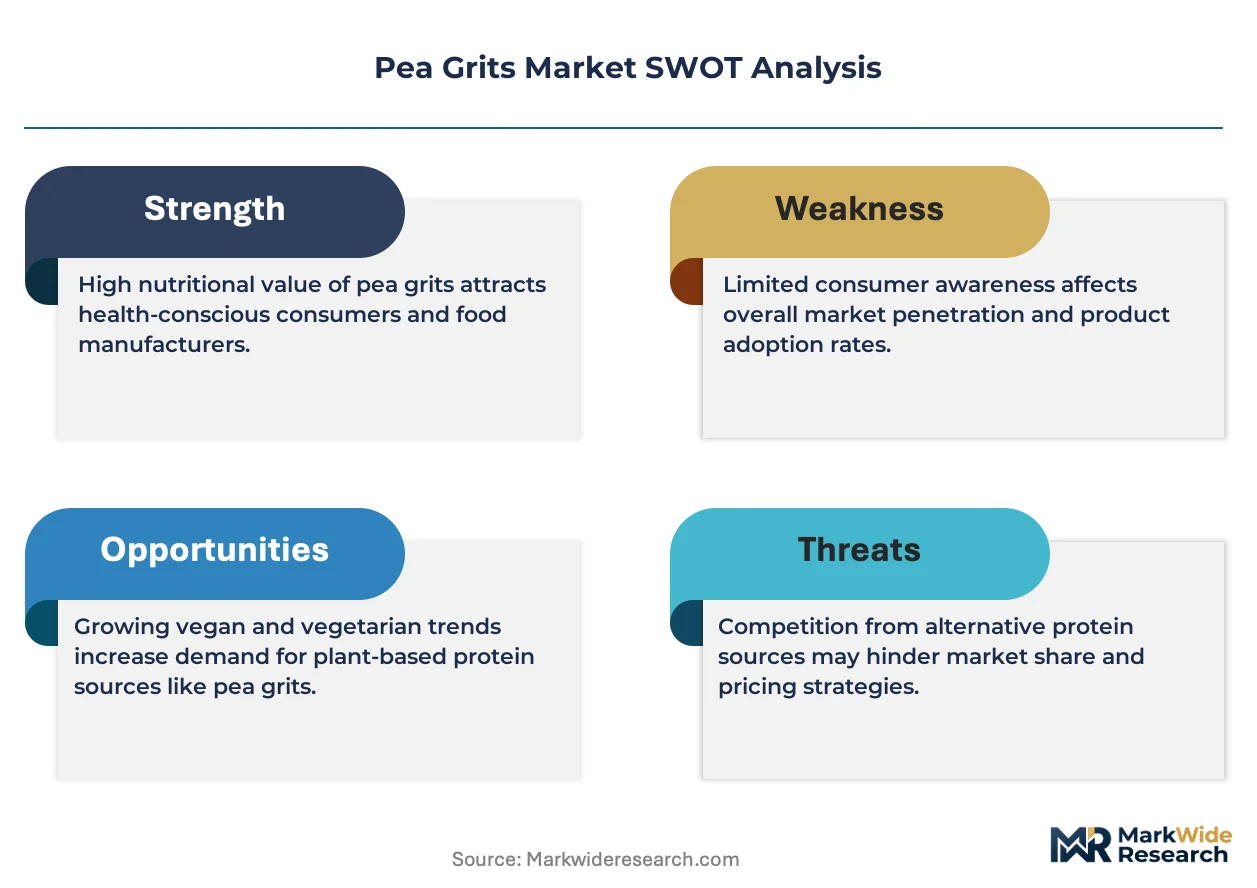
Fava bean protein substitution threatens volume retention in plant-based meat applications, forcing pea grits incumbents to defend position through certification moats and extrusion-texturization convergence.
For Market Incumbents: Harden supply security through backward integration into prairie organic acreage and captive air-classification milling capacity. Lock in preferred vendor status with German bakery reformulation programs by pre-qualifying gluten-free protocols ahead of mandatory allergen labeling expansions. Fava bean displacement in high-lysine applications demands accelerated extrusion-texturization R&D to replicate whole-muscle structures. For New Entrants and Emerging Players: Pursue organic certification arbitrage between USDA National Organic Program and EU equivalency agreements to capture dual-market pricing premiums. White-space exists in blockchain-tracked lot records for French contract manufacturers consolidating supplier rosters. Target online retail subscription models for home bakers seeking certified gluten-free ingredients with recipe integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated processors with captive organic cultivation and in-house extrusion capability. Long-term viability hinges on qualification speed for EFSA novel food pathways and air-classification precision. Watch for prairie infrastructure expansion announcements as inflection signals for margin compression or recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive prairie acreage secures supply and captures USDA-EU organic arbitrage premiums. |
| EFSA Novel Food Dossier Completion | Regulatory qualification unlocks German bakery reformulation volume slots ahead of competitors. |
| Air-Classification Milling Scale-Up | Precision particle control meets Roquette and AGT contract specifications for protein standardization. |
| Blockchain Traceability Implementation | Lot-level transparency satisfies French manufacturer mandates for consolidated supplier rosters. |
| Extrusion-Texturization Partnership | Twin-screw capability convergence generates fibrous structures defending against fava substitution. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in documented compliance pathways. Conversations with pulse processing plant managers, bakery procurement leads at German industrial clusters, extrusion technology directors, and health food retail category buyers combined with Health Canada novel food approvals, EFSA safety assessments, USDA organic certification databases, and Saskatchewan agricultural statistics. Bottom-up volume modeling from milling capacity utilization and top-down demand triangulation from bakery reformulation timelines validate segment trajectories.
Calibration against historical protein ingredient substitution patterns and prairie drought impact cycles shapes the analytical framework across the projection horizon. Segmentation dimensions include certification tier, end-use application, particle size specification, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for EFSA approval velocity and extrusion capacity expansion schedules. Forecast inputs incorporate yellow pea yield volatility coefficients and gluten-free labeling enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity indices and EU regulatory enforcement budgets would shift the trajectory. Forecasts reflect assumptions on EFSA streamlining continuity and prairie infrastructure completion timelines. Material shifts in fava bean protein cost-positioning or REACH purity threshold tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain Storage Silos Market
Grains
Rolled Oats Market
Grains
Corn Market
Grains
Grain Dryers Market
Grains
Uganda Grains Market
Grains
North America Rice Market
Grains
Wheat Flour Market
Grains
Europe Wheat Protein Market
Grains
Asia Pacific Maize Market
Grains
Dried Spent Grain Market
Grains
GCC Basmati Rice Market
Grains
Corn Flour Market
Grains
Canada Pulses Market
Grains
Basmati Rice Market
Grains
Global Rice Market
Grains
Global Grain Mill Products Market