
 Ghana Grain Market | 2026-2036
Ghana Grain Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Grain Market Foresight
Post-harvest storage and logistics services is restructuring how grain value gets captured in Ghana. Olam Ghana Ltd. leverages its inland warehousing network to reduce post-harvest losses across the northern belt. Farmerline anchors its competitive position through digital extension services that link smallholders to certified seed and credit. Tamanaa Company Limited specializes in local rice processing, competing against imports with shorter supply chains.
Grain comprises the harvested seed of cultivated cereals and legumes, typically dried to moisture content below 14 percent to prevent fungal degradation and preserve caloric density for human and animal nutrition. In Ghana, grain serves as the foundational input for flour milling, animal feed compounding, and brewing operations. Maize dominates production volumes and anchors the animal feed segment, while rice imports still satisfy a structural deficit in domestic milling capacity. Sorghum and millet retain strong positions in food processing for traditional fermented products, though these categories carry thinner margin pools than packaged rice or feed-grade maize.
Ghana's national food regulator, the Food and Drugs Authority, enforces mycotoxin limits that shape storage technology investments and quality premiums at wholesale markets. The Ministry of Food and Agriculture administers the Planting for Food and Jobs program, which conditions input subsidies on registered farmer participation and designated crop targets. Stakeholders must monitor how warehouse receipt system expansion alters price discovery and credit access for smallholders without formal land titles.
Market Dynamics
The Planting for Food and Jobs program is restructuring input access for smallholder farmers while warehouse receipt systems alter price discovery and credit access across Ghana's grain value chain.
Growth Catalysts
- Input Subsidy Restructuring:The Ministry of Food and Agriculture conditions fertilizer and seed subsidies on registered farmer participation, expanding certified seed adoption rates among smallholders in the northern belt.
- Urban Food Processing Demand:Flour milling and animal feed compounding operations around Kumasi absorb larger grain volumes as Ghana's urban population concentrates in the Ashanti Region.
- Post-Harvest Infrastructure:Inland warehousing networks reduce post-harvest losses below 14 percent moisture thresholds, preserving caloric density for human and animal nutrition markets.
Market Restraints
- Import Dependency in Rice Milling:Structural deficits in domestic rice processing capacity force reliance on Asian imports, compressing margins for local processors competing against subsidized foreign supply.
- Mycotoxin Compliance Costs:Food and Drugs Authority enforcement of aflatoxin limits requires capital-intensive storage technology investments that smallholders without formal land titles struggle to finance.
- Climate Volatility in Production Zones:Erratic rainfall patterns across the northern grain belt increase yield uncertainty and input cost volatility for rain-fed maize and sorghum cultivation.
Strategic Opportunities
- Digital Extension Services:Mobile-based platforms link smallholders to certified seed and credit, bypassing traditional agricultural development bank bottlenecks in rural districts.
- Traditional Fermentation Processing:Sorghum and millet value chains for fermented products remain underdeveloped relative to packaged rice, offering white space for specialty processing investments.
- Warehouse Receipt Financing:Expansion of collateralized grain storage creates new credit instruments for farmers lacking conventional collateral, deepening financial inclusion in the northern regions.
Industry Challenges
- Certified Seed Distribution Gaps:Limited extension officer density in remote districts delays farmer access to improved varieties, slowing yield convergence with research station potential.
- Storage Technology Integration:Smallholders face capital constraints when adopting hermetic storage bags and solar dryers that satisfy Food and Drugs Authority quality thresholds for formal market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Grain Market |
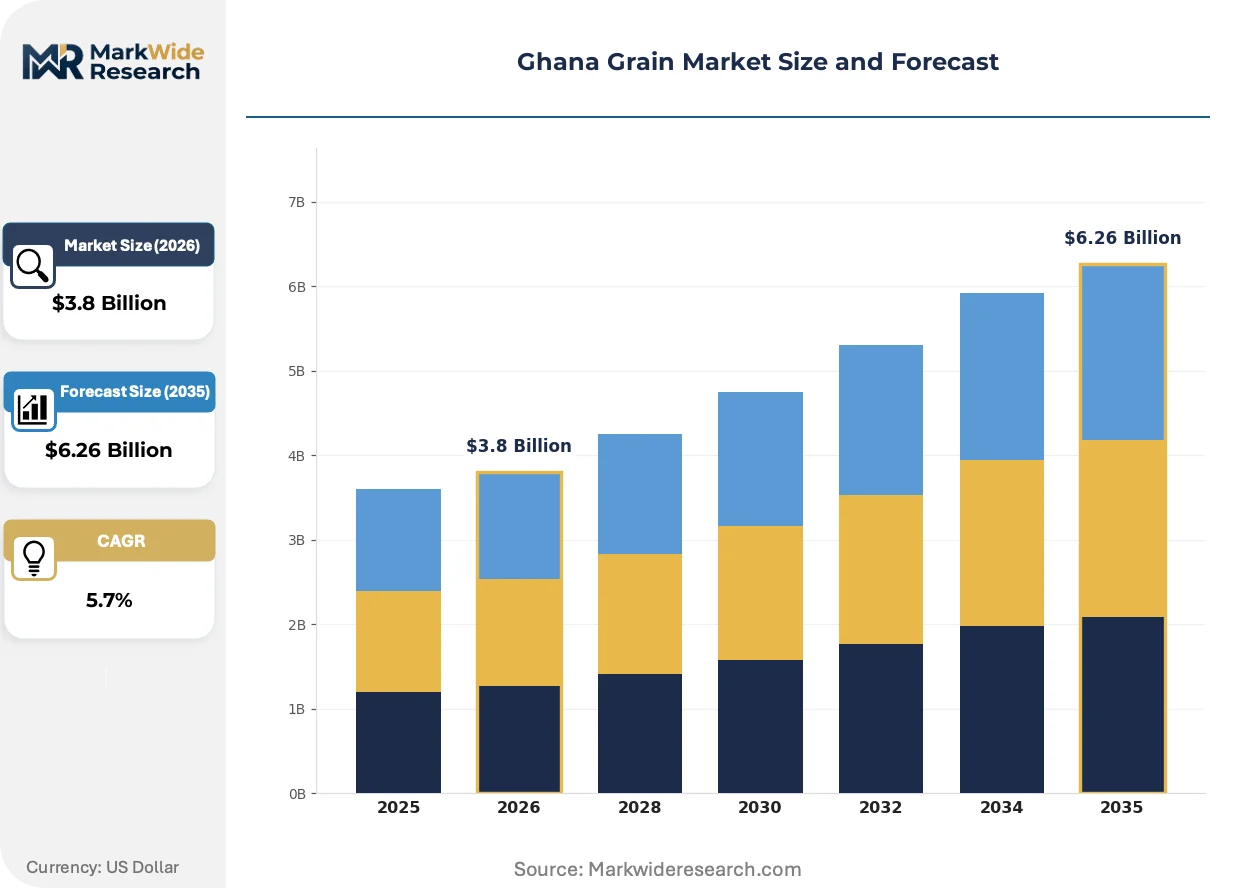
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Grain Type: Maize, Sorghum, Millet, Rice, Soybean, Wheat End Use: Animal Feed, Food Processing, Biofuel Production, Brewing, Industrial Use, Seed Packaging Type: Sacks, Bulk Bags, Jute Bags, Plastic Bags, Paper Bags, Bins Distribution Channel: Wholesale Markets, Retail Shops, Cooperatives, Online Platforms, Exporters, Local Traders |
| Companies Covered | Cereal Investments Company (C.I.C.) Ghana Ltd., Farmerline, Olam Ghana Ltd., Nestle, ETG, Grain West Africa Company Limited, Tamanaa Company Limited, Maxigate Group of Companies Ghana Ltd, Premium Foods Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Grain Market Shifts & Advancements
Digital platforms and mechanized processing are compressing traditional supply chain layers while regulatory enforcement tightens quality standards across Ghana's grain economy.
Mechanized drying and sorting equipment is automating post-harvest handling previously performed through sun-drying and manual winnowing. Medium-scale aggregators in Techiman and Tamale markets deploy mobile solar dryers to achieve uniform moisture content below 14 percent. This technology is automating quality standardization that previously required multiple handling stages, reducing labor intensity while enabling warehouse receipt system participation.
The Food and Drugs Authority has tightened mycotoxin surveillance protocols for maize and groundnut entering formal wholesale channels. Enforcement actions at border markets and urban terminals now require documented storage conditions and laboratory certificates. Large millers in Kumasi and Accra have responded by contracting directly with certified warehouses, bypassing traditional open-air market aggregators.
Urban consumers exhibit preference shifts toward packaged rice with origin labeling and moisture guarantees. Supermarket chains in Accra and Tema now stock branded local rice varieties that compete on shelf-life consistency rather than price alone. This behavioral rotation pressures informal market traders to upgrade handling practices or lose share to structured retail channels.
Ghana Grain Market Segmentation
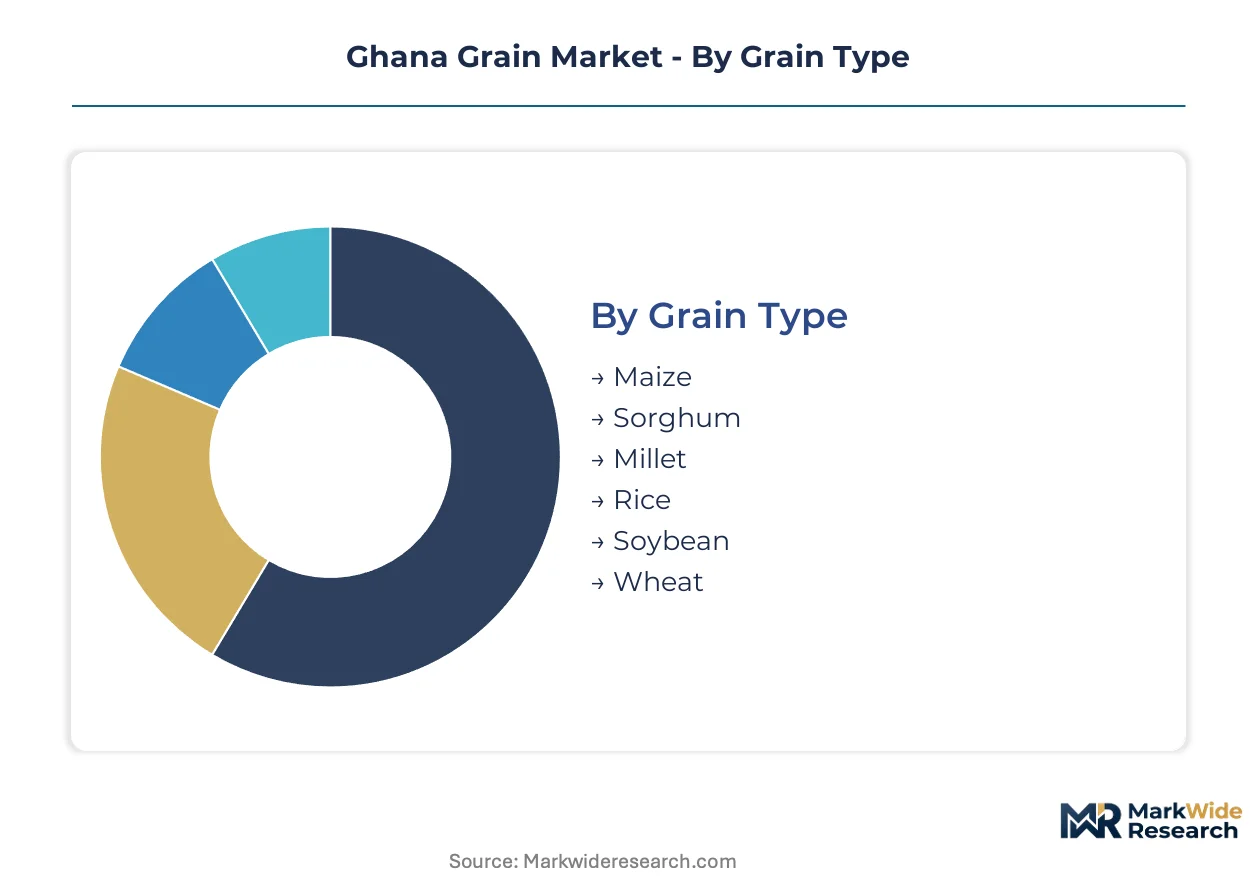
Grain segmentation in Ghana reveals how capital requirements and infrastructure shape competitive access across distinct value chain layers. Farmers, processors, and traders make positioning decisions based on moisture thresholds, storage specifications, and channel control.
Grain Type:
Capital intensity varies sharply across grain categories, with irrigation-dependent rice and mechanized wheat demanding the heaviest upfront investment while traditional cereals operate on thinner asset bases.
- Maize:Dried to moisture content below 14 percent, maize anchors Ghana's animal feed compounding and flour milling sectors. Kumasi's industrial corridor absorbs the largest volumes as poultry operations expand around the Ashanti Region's processing infrastructure.
- Rice:Paddy rice requires substantial irrigation capital and milling equipment that domestic processors struggle to finance against subsidized Asian imports. Tamale and Bolgatanga production zones remain underdeveloped relative to milling demand concentrated in Accra and Tema.
- Sorghum:Drought-tolerant grain serving traditional fermentation processing with minimal input requirements.
- Millet:Small-seeded cereal maintaining stronghold in northern Ghana's rain-fed production systems.
- Soybean:Leguminous oilseed gaining traction in feed formulations around Techiman aggregation hubs.
- Wheat:Import-dependent grain processed by industrial bakeries and millers in coastal urban centers.
Maize absorbs the bulk of installed capacity; rice is expanding most quickly as import substitution policies reshape investment incentives.
End Use:
Application requirements determine equipment specifications and regulatory exposure across Ghana's grain economy.
- Animal Feed:Feed-grade maize and soybean meal undergo mycotoxin screening enforced by the Food and Drugs Authority. Kumasi's poultry belt drives formulation demand as integrated farms scale production.
- Food Processing:Flour milling and traditional fermentation require distinct moisture protocols and storage certification. Tamale sorghum processors compete on supply chain length against imported alternatives.
- Biofuel Production:Emerging demand channel for starch-rich grains with limited current infrastructure.
- Brewing:Sorghum and maize inputs for traditional and industrial beverage production.
- Industrial Use:Starch extraction and non-food applications requiring specialized handling equipment.
- Seed:Certified seed multiplication governed by Ministry of Food and Agriculture variety registration.
Food processing commands the deepest value pools; animal feed is climbing the fastest as poultry integration accelerates.
Packaging Type:
Handling specifications cascade from moisture targets through material selection and unit economics.
- Sacks:Woven polypropylene dominates medium-volume trade through Techiman and Tamale wholesale markets, balancing durability against unit cost for aggregators serving Kumasi millers.
- Bulk Bags:One-ton flexible intermediate bulk containers enable warehouse receipt system participation with standardized weighing and reduced handling labor.
- Jute Bags:Traditional breathable packaging for moisture-sensitive sorghum and millet.
- Plastic Bags:Retail-scale packaging for supermarket distribution in Accra and Tema.
- Paper Bags:Branded retail formats for premium local rice positioning.
- Bins:Rigid containers for large-scale miller procurement and port handling.
Sacks retain the widest installed base; bulk bags are gaining share fastest as warehouse receipt financing expands.
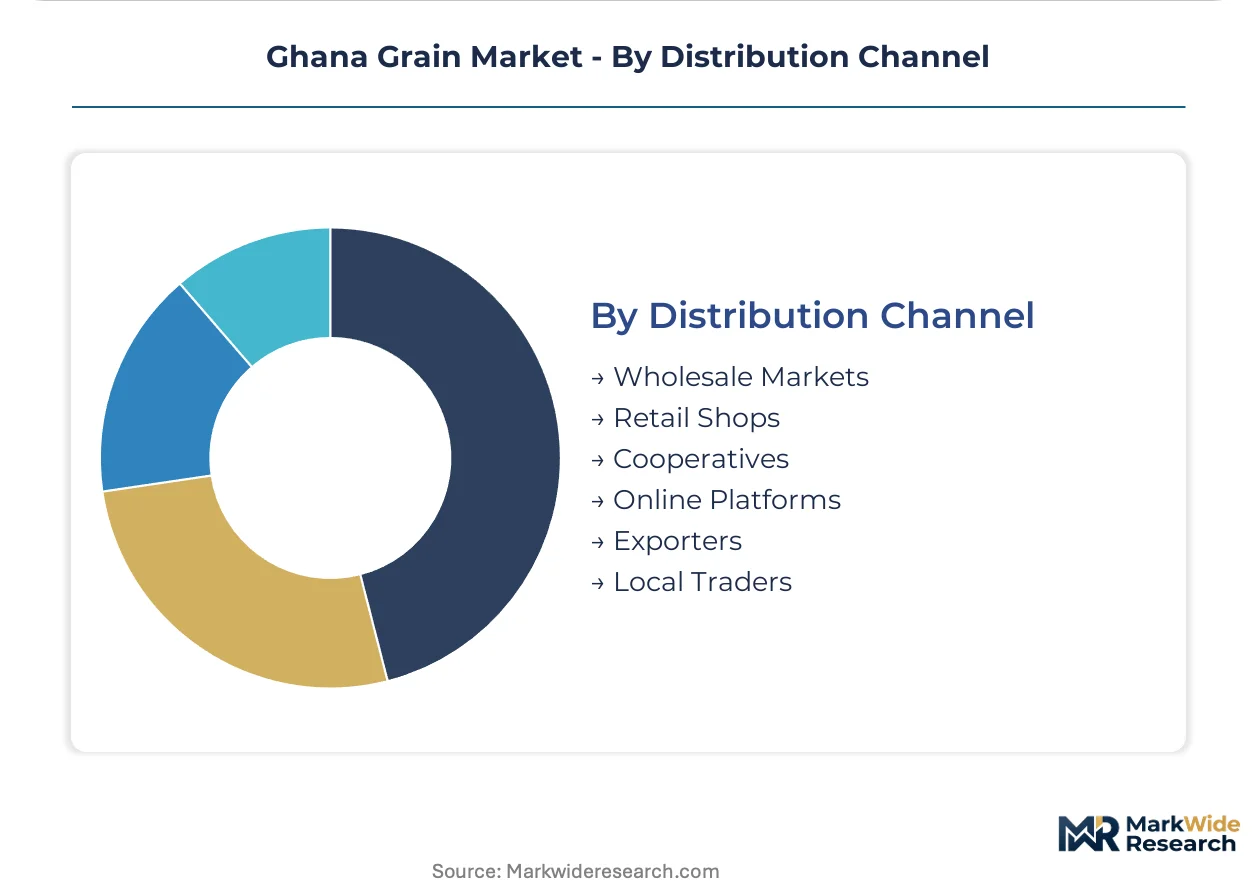
Distribution Channel:
Channel selection determines price discovery transparency and working capital requirements for market participants.
- Wholesale Markets:Techiman Central Market and Tamale Aboabo Market aggregate northern belt production for southern millers, with quality grading determining price tiers and credit terms.
- Cooperatives:Farmer groups bypass trader margins through collective bargaining and warehouse receipt collateralization, deepening financial inclusion in districts with limited banking penetration.
- Retail Shops:Urban neighborhood distribution for household consumption in Kumasi and Accra.
- Online Platforms:Digital marketplaces linking aggregators to processors with logistics coordination.
- Exporters:Formal shipments to regional ECOWAS markets and beyond.
- Local Traders:Informal intermediaries with lowest capital barriers and highest price volatility exposure.
Wholesale markets absorb the bulk of volume throughput; cooperatives are expanding most quickly as the Planting for Food and Jobs program strengthens collective marketing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ghana's grain production concentrates in the northern savanna zones while consumption and processing gravity pulls toward southern urban centers. This spatial divide shapes infrastructure investment patterns and price formation across the value chain.
Ashanti Region
Kumasi's poultry integration and flour milling operations absorb the largest grain volumes outside Accra. The Ministry of Food and Agriculture channels Planting for Food and Jobs subsidies toward registered farmer groups supplying this corridor. Techiman Central Market serves as the primary aggregation node linking northern production to Ashanti processors.
Northern Region
Tamale anchors sorghum and millet cultivation systems with minimal input requirements relative to irrigated rice. The Food and Drugs Authority's mycotoxin surveillance protocols shape storage technology adoption among aggregators in Tamale Aboabo Market. Farmerline's digital extension services concentrate subscriber density in this zone.
Upper East Region
Bolgatanga's rice production zones remain underdeveloped against milling demand concentrated in coastal cities. Rain-fed cultivation faces yield uncertainty from erratic rainfall patterns across the northern grain belt. Warehouse receipt system pilots target this region for collateralized storage expansion.
Greater Accra Region
Tema's port infrastructure handles wheat imports for industrial bakeries while local rice processors compete for supermarket shelf space. Urban consumers exhibit preference shifts toward packaged rice with origin labeling and moisture guarantees. Olam Ghana Ltd. leverages its warehousing network to supply formal retail channels.
Ghana Grain Market Competitive Landscape
Top-tier vendors anchor integrated trading and processing operations, while mid-tier aggregators compete on supply chain length and regional sourcing relationships. The competitive structure splits between multinational traders with warehouse infrastructure and domestic processors specializing in import substitution. Strategic archetypes include: vertically integrated traders controlling storage and logistics; digital platform operators linking smallholders to credit and certified inputs; and local rice processors competing against subsidized Asian supply. Dominant competitive moves encompass warehouse network expansion and direct contracting with certified storage facilities.
Among Ghana-based operators, Cereal Investments Company (C.I.C.) Ghana Ltd. and Tamanaa Company Limited occupy positions within the domestic processing tier, while Olam Ghana Ltd. represents the integrated multinational archetype with inland warehousing networks.
| Leading Market Players |
|---|
| Cereal Investments Company (C.I.C.) Ghana Ltd. |
| Farmerline |
| Olam Ghana Ltd. |
| Nestle |
| ETG |
| Grain West Africa Company Limited |
| Tamanaa Company Limited |
| Maxigate Group of Companies Ghana Ltd |
| Premium Foods Limited |
| Others |
Supply & Pricing Matrix
Manual threshing labor concentrated in Ghana's Upper East Region creates cost differentials that widen spreads between warehouse-certified and open-air market grain. The Food and Drugs Authority's mycotoxin enforcement feeds these tier separations by forcing capital investment that smallholders without formal land titles cannot finance.
Pricing Analysis
Price erosion across informal market tiers traces to subsidized Asian rice imports that compress domestic milling margins. Three-tier pricing structure across premium certified-warehouse, standard cooperative-aggregated, and economy open-air levels stratifies by moisture documentation and aflatoxin testing. Cost-down pressure on local rice processors accelerates because port-handled wheat and Asian paddy enjoy tariff advantages. Poultry feed compounders in Kumasi exhibit highest price sensitivity due to thin formulation margins, while branded retail rice buyers in Accra show lowest sensitivity to origin-premium spreads.
Supply Chain Analysis
Single-source vulnerability sits with the Techiman-Tamale corridor that channels northern belt production toward Ashanti processors. Geographic supply concentration centers on Ghana's northern savanna zones for sorghum and millet, with rice paddy drawing from Bolgatanga and irrigated valleys near Tamale. Raw material dependencies rest on rain-fed maize cultivation, imported wheat for industrial bakeries, and fertilizer subsidies administered through the Ministry of Food and Agriculture. Supply chain risk hinges on single-source vulnerability to erratic rainfall patterns across rain-fed production zones. Distribution runs through wholesale markets at Techiman Central and Tamale Aboabo, with cooperatives and warehouse receipt systems gaining share as alternative channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's grain market functions as a vertical-integration race where warehouse infrastructure and certified storage capacity determine who captures value from smallholder aggregation to formal retail. Players are pursuing downstream control over Tema and Accra supermarket channels as the decisive lever.
For Market Incumbents: Anticipate margin compression from Asian rice import competition by locking in multi-year warehouse receipt contracts with Planting for Food and Jobs registered farmer groups. Prioritize backward integration into solar drying and hermetic storage equipment deployment to satisfy Food and Drugs Authority quality thresholds that informal aggregators cannot meet.
For New Entrants and Emerging Players: The price-point gap between premium certified-warehouse rice and economy open-air market grain offers white-space entry for mid-tier branded positioning. Target sorghum and millet fermentation processing in Tamale where supply chains remain underdeveloped against packaged rice. Pursue digital extension services linking smallholders to certified seed and credit as the go-to-market angle, bypassing agricultural development bank bottlenecks.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic rice processors possessing irrigation access and milling capacity given import substitution policy momentum. Long-term viability favors operators with warehouse infrastructure in the northern belt and direct retail relationships in Greater Accra. Monitor warehouse receipt system expansion rates across the Upper East Region as the signal to watch for financial inclusion depth and collateralized lending inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Network Expansion | Inland storage capacity in Techiman and Tamale reduces post-harvest losses below Food and Drugs Authority moisture thresholds. |
| Digital Extension Platform Launch | Mobile-based services link smallholders to certified seed and credit, bypassing traditional agricultural development bank bottlenecks. |
| Import Substitution Milling Capacity | Domestic rice processing investments compete against subsidized Asian supply through shorter supply chains to Accra supermarkets. |
| Cooperative Marketing Infrastructure | Collective bargaining and warehouse receipt collateralization deepen financial inclusion in districts with limited banking penetration. |
| Hermetic Storage Technology Deployment | Capital-intensive equipment satisfies mycotoxin surveillance protocols that informal open-air market aggregators cannot meet. |
Research Methodology
Multi-period observation of Planting for Food and Jobs subsidy disbursement patterns, warehouse receipt system participation rates, and Food and Drugs Authority enforcement actions anchored the trend analysis, supplemented by interviews with grain aggregators at Techiman Central Market, poultry feed compounders in Kumasi, and supermarket category buyers in Accra. Secondary validation drew from Ministry of Food and Agriculture program documentation, Ghana Statistical Service agricultural production data, and Food and Drugs Authority regulatory filings. Bottom-up triangulation across farmer group registration databases and top-down reconciliation against national grain balance sheets ensured consistency.
Segment-weighting by grain type, end-use application, and distribution channel shaped the analytical framework across the projection horizon. Modeled dimensions included moisture certification tiers, packaging specifications from woven polypropylene sacks to bulk bags, and regional production clusters spanning the northern savanna to Ashanti processing corridors. CAGRs were derived from trend extrapolation of input subsidy expansion, urbanization-driven food processing demand, and post-harvest infrastructure investment flows. Industry-specific forecast inputs incorporated poultry integration rates around Kumasi and supermarket penetration of packaged local rice in Greater Accra.
Inputs from warehouse receipt system operators and cooperative marketing groups were available through the study window; gaps in smallholder storage technology adoption data introduce uncertainty bands around loss-reduction estimates. Forecasts reflect assumptions about Ministry of Food and Agriculture program continuity, rainfall pattern stability, and import tariff policy. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain Storage Silos Market
Grains
Global Wheat Market
Grains
Asia Pacific Maize Market
Grains
Wheat Protein Market
Grains
Cultured Wheat Market
Grains
Wheat Flour Market
Grains
Soya Flour Market
Grains
Organic Wheat Flour Market
Grains
Wild Rice Market
Grains
Grain Bins Market
Grains
United States Rice Market
Grains
United States Maize Market
Grains
Wheat Bran Market
Grains
Asia-Pacific Guar Market
Grains
Grain Silos and Storage System Market
Grains
Quinoa Flour Market