
 Rotary Drum Dryers Market | 2026-2036
Rotary Drum Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Drum Dryers Market Insights
Chinese heavy equipment manufacturing is consolidating around rotary drum dryer production for mining and metallurgy applications. FLSmidth Inc leverages its mineral processing heritage to dominate large-scale installations across Africa and Latin America. Buhler AG sustains technology leadership in food-grade thermal processing through precision moisture control systems. ANDRITZ AG anchors European demand with biomass drying solutions tied to renewable energy feedstock preparation.
A rotary drum dryer is a cylindrical vessel that rotates on a slight incline while hot gas or steam passes through the drum to reduce moisture content in bulk solids, typically operating at temperatures between 150°C and 800°C depending on material sensitivity and thermal efficiency requirements. Direct heated configurations remain the volume backbone due to lower capital outlay and simpler maintenance protocols, though indirect heated designs are capturing margin pools in pharmaceutical and specialty chemical applications where product contamination risks command premium pricing. Food processing end users increasingly specify modular installation types to accommodate seasonal crop intake fluctuations without permanent infrastructure commitments.
EPA emissions guidelines for industrial dryers in the United States and REACH chemical safety protocols in Europe are tightening permissible volatile organic compound thresholds, forcing retrofit cycles and new equipment specifications. China's MEE enforces parallel efficiency standards that favor domestic manufacturers with localized certification pathways. Stakeholders must weigh regulatory compliance timelines against equipment lifecycle economics when committing to thermal processing investments.
Market Dynamics
EU F-Gas Regulation enforcement is accelerating replacement cycles across chemical processing facilities, while China's MEE efficiency mandates redirect procurement toward domestic certification pathways. Equipment buyers now weigh compliance timelines against thermal processing lifecycle economics.
Growth Catalysts
- Biomass feedstock preparation:Renewable energy mandates in Germany and Austria drive ANDRITZ AG installations for pellet production. Agricultural residue processing volumes climb as district heating networks expand.
- REACH chemical safety protocols:Pharmaceutical manufacturers in Switzerland and France specify indirect heated configurations to eliminate product contamination risks. Premium pricing pools emerge for certified thermal processing equipment.
- Inner Mongolia mining corridor:Mineral processing capacity scaling concentrates demand for large-scale direct heated systems. Domestic Chinese manufacturers capture volume through localized MEE certification advantages.
Market Restraints
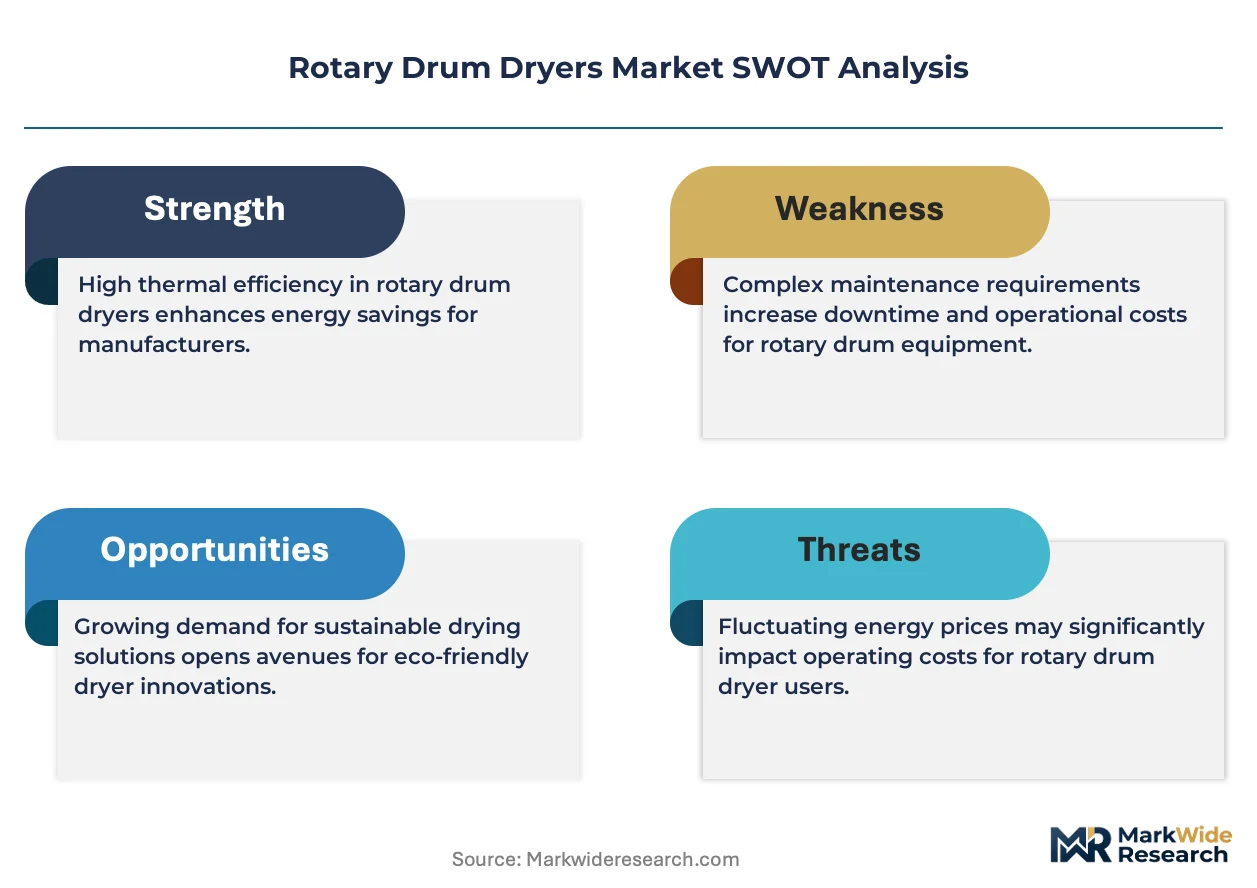
- Specialty steel input volatility:Drum shell fabrication depends on nickel alloy and stainless steel price swings. Foundry capacity concentration in China creates supply bottleneck exposure.
- Technical limitation in heat recovery:Exhaust gas temperature differentials constrain thermal efficiency gains below theoretical maximums. Retrofit economics deteriorate for installations older than fifteen years.
- Substitution threat from belt dryers:Food processing applications with fragile particle structures increasingly specify conveyor-based alternatives. Modular belt systems offer lower infrastructure commitment for seasonal operations.
Strategic Opportunities
- Pharmaceutical API manufacturing:Sterile drying requirements in India and South Korea create specification gaps for validated thermal processing. cGMP-compliant indirect heated drum systems address unmet demand.
- Technology convergence with IoT sensors:Real-time moisture profiling and predictive maintenance algorithms differentiate equipment offerings. Precision control systems command margin premiums in specialty chemical applications.
- EU Green Deal industrial decarbonization incentives:Heat pump integration and waste heat recovery retrofits qualify for member-state subsidy programs. Equipment financing structures evolve to capture grant-backed procurement cycles.
Industry Challenges
- Commissioning engineer scarcity:Thermal process optimization expertise concentrates among aging specialists in Germany and Japan. Knowledge transfer gaps delay installation timelines for complex indirect heated configurations.
- Legacy control system integration:Existing SCADA architectures in US chemical plants require protocol bridging for modern dryer automation. Custom engineering extends project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Drum Dryers Market |
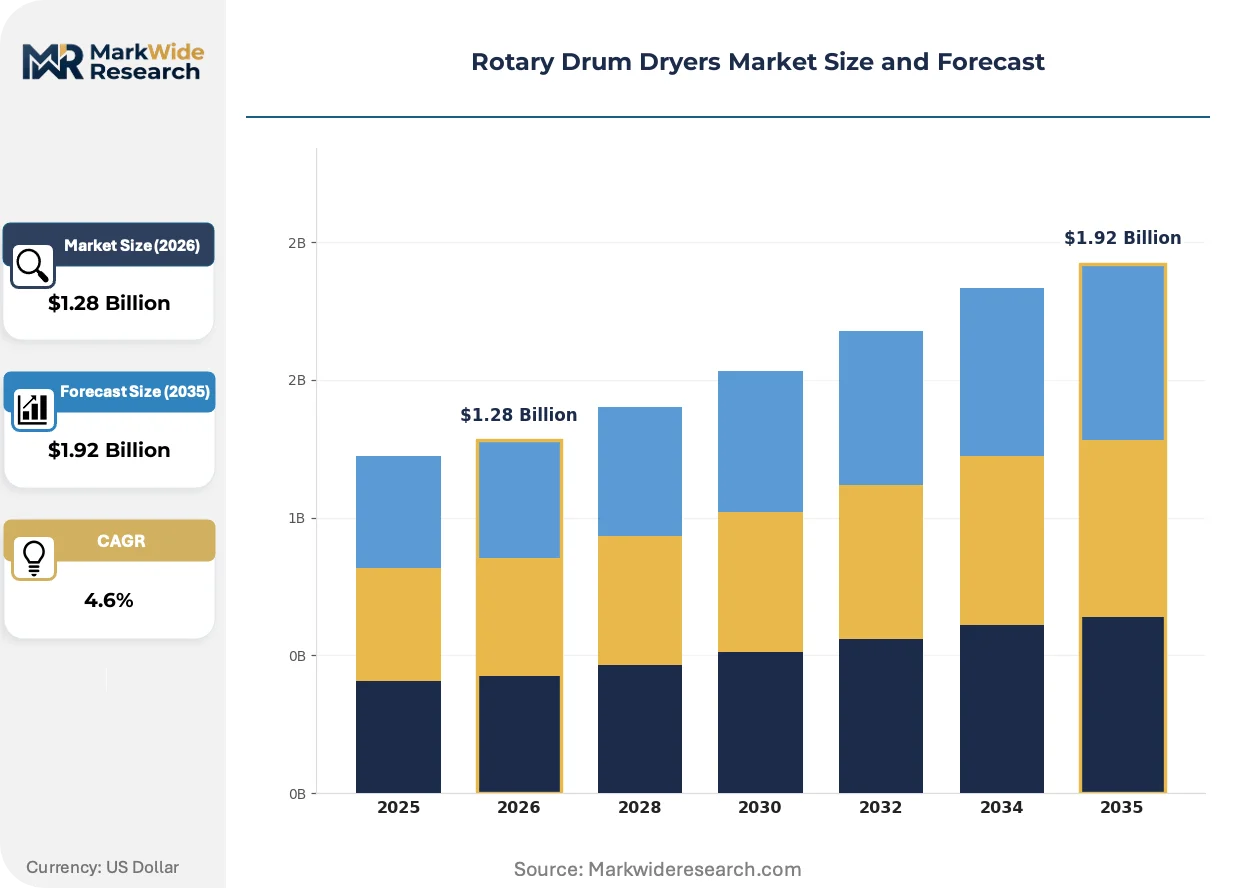
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Direct Heated, Indirect Heated, Steam Heated, Electric Heated, Hot Air Material Processed: Biomass, Minerals, Chemicals, Food Products, Pharmaceuticals End User Industry: Energy Production, Mining & Metallurgy, Food Processing, Chemical Manufacturing Installation Type: Fixed, Mobile, Modular, Stationary |
| Companies Covered | FLSmidth Inc, Buhler AG, FEECO International, Louisville Dryer Company, ThyssenKrupp AG, ANDRITZ AG, Metso Outotec Corporation, Schenck Process Holding GmbH, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Drum Dryers Market Trends and Innovations
Electrification of thermal sources and digitalization of process control are compressing equipment differentiation cycles. Buyers now prioritize energy recovery architectures and predictive maintenance capabilities alongside core drying performance specifications.
Heat pump-assisted rotary drum dryers are electrifying thermal input methods for temperature-sensitive applications. Food-grade processors in the Netherlands and Denmark adopt these systems to eliminate on-site combustion emissions. The technology is electrifying what had been fossil-fuel-dependent process heat, enabling carbon footprint claims that command retail channel preference.
EPA emissions guidelines for industrial dryers tighten volatile organic compound thresholds in US chemical manufacturing corridors. Facility operators face retrofit deadlines that compress equipment replacement windows. Pharmaceutical and specialty chemical plants in New Jersey and Texas accelerate indirect heated system procurement to preempt enforcement actions.
Modular installation contracts now displace permanent infrastructure commitments among agricultural commodity processors. Seasonal crop intake patterns in Argentina and Ukraine drive demand for relocatable drying capacity. Grain trading houses specify containerized drum systems that relocate between harvest regions, collapsing the traditional fixed-asset model for thermal processing investments.
Rotary Drum Dryers Market Segmentation
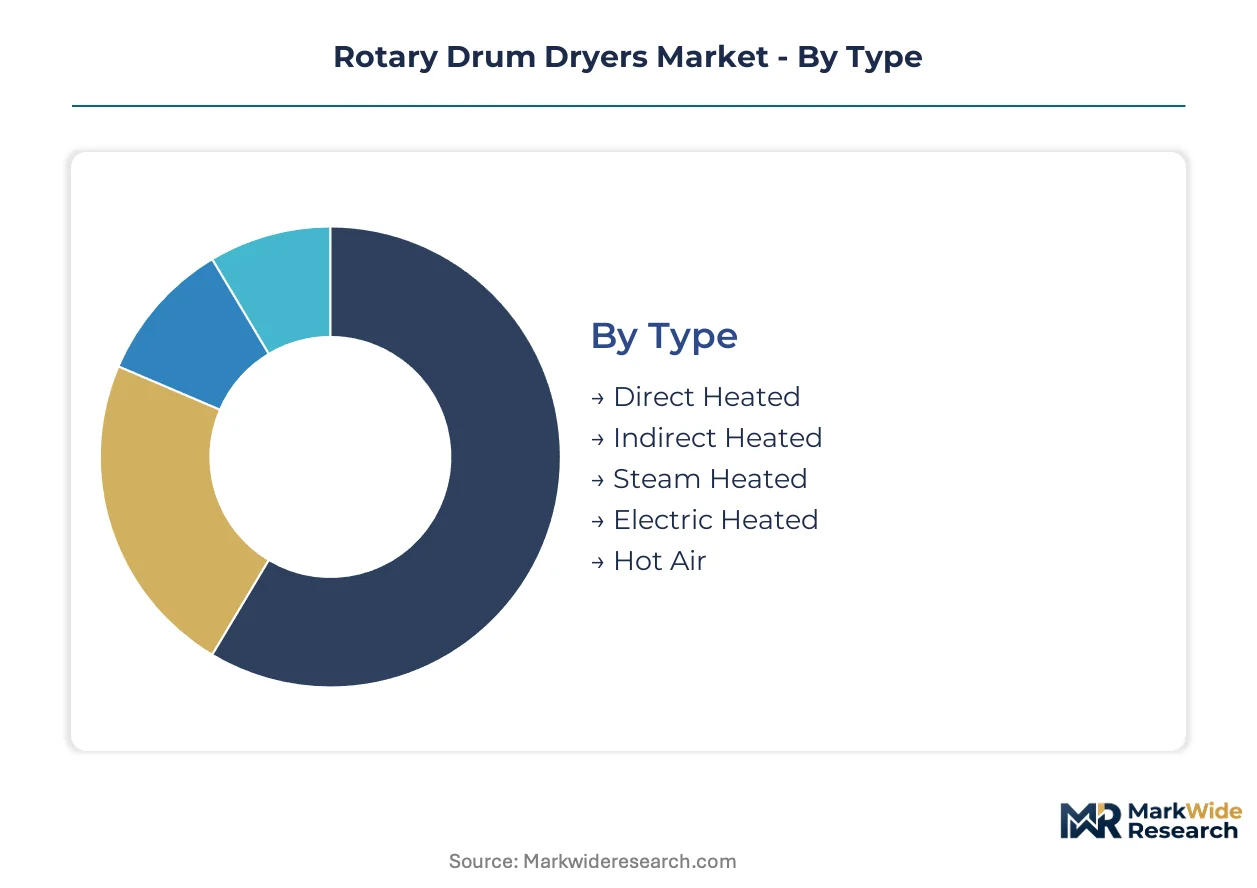
Rotary drum dryer procurement decisions diverge sharply across thermal configurations and material sensitivity requirements. Equipment specification cascades through heat transfer method, processed material characteristics, and installation permanence obligations.
Type:
Capital outlay thresholds and contamination risk tolerance separate buyers across thermal delivery architectures.
- Direct Heated:Combustion gases contact material directly, delivering thermal efficiency above 85% for moisture-tolerant bulk solids. Mining operations in China's Inner Mongolia corridor specify these systems for iron ore concentrate processing where product purity standards permit gas-to-solid contact.
- Indirect Heated:Heat transfers through drum shell walls, isolating material from combustion contaminants. Pharmaceutical manufacturers in Switzerland and France mandate this configuration for API drying under REACH protocols, accepting 40% higher capital costs to eliminate cross-contamination pathways.
- Steam Heated:Saturated steam jackets enable precise temperature control for heat-sensitive organics.
- Electric Heated:Resistance elements electrify thermal input for sites with renewable electricity access.
- Hot Air:Recirculated process air suits applications with moderate temperature requirements and existing heat recovery infrastructure.
Volume sits with Direct Heated systems; growth tilts toward Indirect Heated configurations.
Material Processed:
Moisture binding mechanisms and thermal degradation thresholds dictate equipment specification intensity.
- Minerals:Crystalline structures tolerate aggressive thermal profiles above 600°C. Mining concentrators in Chile and Australia deploy large-diameter drums for copper concentrate drying where throughput volume dominates equipment selection criteria.
- Biomass:Fibrous cellulosic materials require controlled temperature ramps to preserve calorific value. Austrian district heating feedstock processors specify ANDRITZ AG systems with staged moisture removal for wood pellet production.
- Chemicals:Synthetic compounds demand atmosphere-controlled environments.
- Food Products:Hygienic design standards govern surface finish and cleanability.
- Pharmaceuticals:cGMP validation requirements extend procurement timelines.
Minerals processing commands installed base dominance; biomass applications are climbing the fastest.
End User Industry:
Regulatory exposure profiles and capacity utilization patterns shape replacement cycle timing.
- Mining & Metallurgy:Continuous operation regimes prioritize mechanical reliability and parts availability. Large-scale installations across Brazil and South Africa run 8,000+ annual hours, driving maintenance-contract procurement alongside original equipment.
- Chemical Manufacturing:Batch flexibility requirements and emissions compliance deadlines accelerate replacement decisions. German facilities under EU F-Gas Regulation enforcement are retiring systems older than fifteen years ahead of mechanical failure.
- Energy Production:Renewable feedstock preparation creates seasonal demand spikes.
- Food Processing:Modular specifications accommodate harvest timing variability.
Mining & Metallurgy anchors current revenue; Chemical Manufacturing shows the steepest replacement trajectory.
Installation Type:
Asset permanence commitments versus operational flexibility requirements define procurement structure.
- Modular:Containerized subsystems relocate between seasonal processing sites without civil works. Argentine grain traders deploy these systems across soybean and wheat harvest regions, collapsing fixed-asset depreciation schedules into variable throughput costs.
- Fixed:Permanent foundations support highest-capacity continuous operations.
- Mobile:Skid-mounted configurations serve remote mining camps.
- Stationary:Integrated plant architectures minimize interface complexity.
Fixed installations retain volume concentration; modular configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inner Mongolia's iron ore corridor anchors procurement intensity for direct heated systems. German chemical clusters drive indirect heated replacement cycles under EU F-Gas enforcement. Brazilian mining expansion and Indian pharmaceutical capacity additions round out regional demand distribution.
China
Inner Mongolia's mineral processing belt concentrates demand for large-scale direct heated installations. MEE efficiency mandates favor domestic manufacturers with localized certification pathways. Zhengzhou and Shanghai equipment fabricators capture volume through state-backed procurement preferences.
Germany
Chemical manufacturing facilities in North Rhine-Westphalia and Bavaria accelerate indirect heated system procurement. EU F-Gas Regulation enforcement compresses replacement windows for aging thermal processing assets. Ludwigshafen and Leverkusen industrial clusters drive premium-tier equipment specifications.
United States
EPA emissions guidelines tighten volatile organic compound thresholds across Texas and New Jersey chemical corridors. Pharmaceutical API manufacturers specify cGMP-compliant indirect heated configurations. Houston and Philadelphia metropolitan areas anchor retrofit procurement timelines.
Brazil
Iron ore concentrators in Minas Gerais deploy large-diameter drums for copper concentrate drying. ANVISA pharmaceutical regulations create specification gaps for validated thermal processing equipment. São Paulo state industrial parks attract modular installation contracts for seasonal flexibility.
India
Pharmaceutical API manufacturing expansion in Maharashtra and Gujarat creates demand for cGMP-compliant indirect heated systems. CDSCO regulatory pathways extend procurement timelines for validated equipment. Hyderabad and Ahmedabad industrial clusters drive technology upgrade cycles.
Rotary Drum Dryers Market Competitive Landscape
Global majors compete with regional champions across thermal configuration expertise and certification depth. Market structure tilts toward consolidated premium tiers alongside fragmented volume segments. Three archetypes dominate: mineral processing heritage players, food-grade precision specialists, and diversified industrial conglomerates. Capacity expansion and technology licensing represent the primary competitive vectors.
Within the mineral processing heritage tier, FLSmidth Inc and Metso Outotec Corporation exemplify scale-driven positioning for large-diameter mining installations. Buhler AG occupies a distinct niche representing food-grade precision thermal control capabilities. ANDRITZ AG anchors the biomass and renewable feedstock preparation segment. ThyssenKrupp AG and GEA Group sit within diversified industrial conglomerate archetypes spanning multiple thermal processing applications.
| Leading Market Players |
|---|
| FLSmidth Inc |
| Buhler AG |
| FEECO International |
| Louisville Dryer Company |
| ThyssenKrupp AG |
| ANDRITZ AG |
| Metso Outotec Corporation |
| Schenck Process Holding GmbH |
| GEA Group |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation enforcement gates qualified supply and premium-tier pricing access for rotary drum dryer manufacturers serving European chemical processing facilities. Compliance certification under REACH protocols separates certified thermal processing equipment from commodity alternatives, creating pricing power for validated indirect heated system producers.
Pricing Analysis
Warranty and aftermarket service bundling separates premium-tier equipment from unbundled commodity offerings. Project-based pricing dominates large-scale mining installations, while modular contracts accommodate seasonal agricultural processors with lower infrastructure commitment. Price differentiation hinges on cGMP validation status and thermal efficiency guarantees, with pharmaceutical buyers showing lowest price sensitivity due to contamination risk exposure. Cost compression in standard direct heated configurations intensifies as Chinese domestic manufacturers leverage MEE certification advantages.
Supply Chain Analysis
Welding specialist and thermal engineer scarcity in Germany and Japan constrains fabrication capacity for complex indirect heated drum systems. Drum shell production draws from specialty steel foundries concentrated in China, with nickel alloy and stainless steel inputs feeding from Chinese and South Korean metallurgical suppliers. Single-source vulnerability in high-temperature alloy supply creates bottleneck exposure during commodity price spikes. Distribution runs through OEM-direct channels for large mining contracts and regional equipment distributors for modular agricultural systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary drum dryer procurement operates as a cost-of-compliance story where EU F-Gas Regulation enforcement creates a barrier-to-entry moat for certified equipment manufacturers.
For Market Incumbents: Lock in long-term service contracts with mining operators in Chile and Australia to defend against modular belt dryer substitution in fragile particle applications. Deepen backward integration into specialty steel supply through captive foundry partnerships in China, securing drum shell fabrication capacity against nickel alloy price volatility. Prioritize commissioning engineer knowledge transfer programs to address aging specialist retirement timelines. For New Entrants and Emerging Players: Argentine and Ukrainian grain trading houses represent an underserved buyer archetype seeking relocatable drying capacity without permanent infrastructure commitment. Target containerized modular installations for seasonal crop intake patterns, bypassing fixed-asset competition from established OEMs. Pursue technology licensing partnerships with European biomass feedstock processors to accelerate market entry without full R&D burden. For Investors and Strategic Acquirers: CDSCO regulatory pathway acceleration in India is the leading indicator that pharmaceutical API manufacturing capacity expansion will sustain premium-tier equipment demand. Position acquisition screening around cGMP-validated indirect heated system specialists with established commissioning expertise. Monitor MEE efficiency mandate tightening in China as signal for domestic manufacturer consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Supply | Captive nickel alloy sourcing insulates drum shell fabrication from Chinese foundry concentration risk. |
| cGMP Validation Investment | REACH-compliant certification unlocks pharmaceutical API manufacturing procurement in Switzerland and France. |
| Modular Installation Platform Development | Containerized systems address Argentine grain trader demand for seasonal relocatable drying capacity. |
| Heat Pump Electrification Partnership | EU Green Deal subsidy eligibility positions equipment for Netherlands and Denmark food-grade carbon footprint claims. |
| Commissioning Engineer Training Consortium | German-Japanese knowledge transfer programs address thermal process optimization specialist scarcity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this rotary drum dryer market analysis. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at mining and chemical processing facilities combined with bottom-up and top-down triangulation. Secondary validation drew from MEE efficiency standard publications, EU F-Gas Regulation enforcement notices, EPA emissions guideline updates, and equipment import-export documentation.
Segmentation granularity modeled thermal configuration type, processed material characteristics, end-use industry vertical, and installation permanence requirements across the projection horizon. CAGRs derived from installed base replacement cycle analysis, capacity expansion announcements, and regulatory compliance timeline compression. Industry-specific forecast inputs included mining throughput volume projections, pharmaceutical API manufacturing capacity buildouts, and biomass pellet production mandates.
Revisions become necessary when EU F-Gas Regulation enforcement timelines accelerate, Chinese MEE efficiency mandates expand certification requirements, or specialty steel commodity prices trigger equipment specification downgrades. Material deviation in named regulatory triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Shelling Machine Market