
 Male Artificial Urinary Sphincter Market | 2026-2036
Male Artificial Urinary Sphincter Market Size, Share, and Industry Trends Forecast 2026-2036
Male Artificial Urinary Sphincter Market Analytics
Leasing arrangements for high-cost surgical implants are reconfiguring competitive dynamics in the male artificial urinary sphincter space. Boston Scientific Corporation leverages its established urology portfolio to sustain hospital contracting relationships across North American markets. Coloplast anchors European distribution through specialized continence care channels. Affluent Medical competes with differentiated hydraulic designs targeting reduced revision rates.
A male artificial urinary sphincter is an implantable prosthetic device comprising a cuff, pressure-regulating balloon, and control pump, typically constructed from silicone elastomer with radiopaque markers for postoperative imaging assessment; its primary function is to restore voluntary urinary continence in men with severe stress urinary incontinence by occluding the bulbar urethra until manual deactivation. Inflatable sphincter systems dominate value generation due to their established clinical track record and premium pricing relative to semi-rigid alternatives. Minimally invasive surgical technique adoption is accelerating fastest among technology segments as urologists seek reduced operative morbidity and shorter catheterization periods. Post-prostate surgery application anchors volume demand, reflecting the substantial iatrogenic incontinence burden following radical prostatectomy.
FDA premarket notification and CE marking under the EU MDR govern device approval pathways, with both frameworks intensifying requirements for long-term implant survival data and biocompatibility documentation. HIPAA and GDPR compliance obligations shape how manufacturers collect and transmit patient-reported outcome data from implanted devices. Stakeholders must monitor evolving reimbursement thresholds for revision surgeries and emerging robotic surgical platforms that could alter device placement economics.
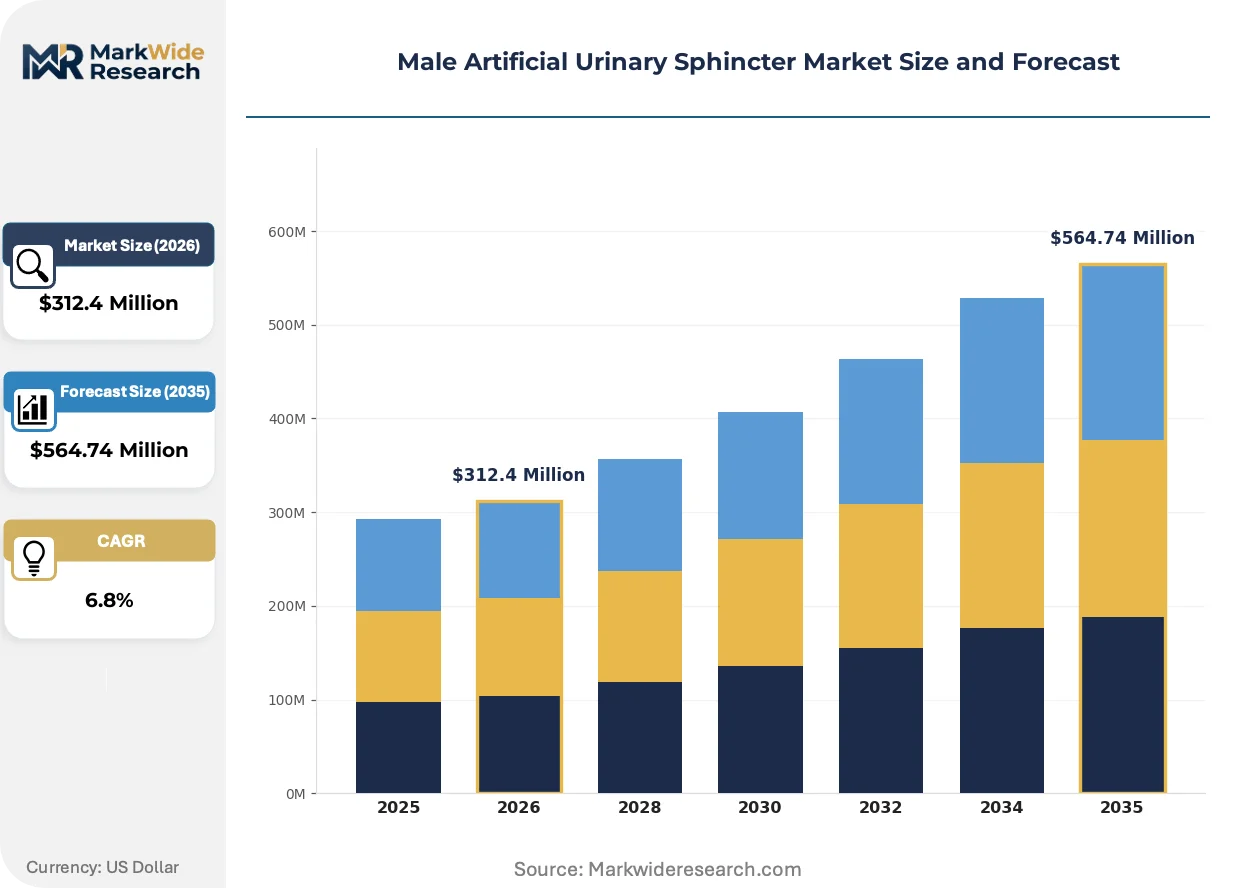
Market Dynamics
The male artificial urinary sphincter market is compressing around revision burden reduction as urologists prioritize implant longevity over upfront device cost in purchasing decisions. This clinical preference shift is restructuring supplier competition toward durability engineering and post-implant surveillance services.
Growth Catalysts
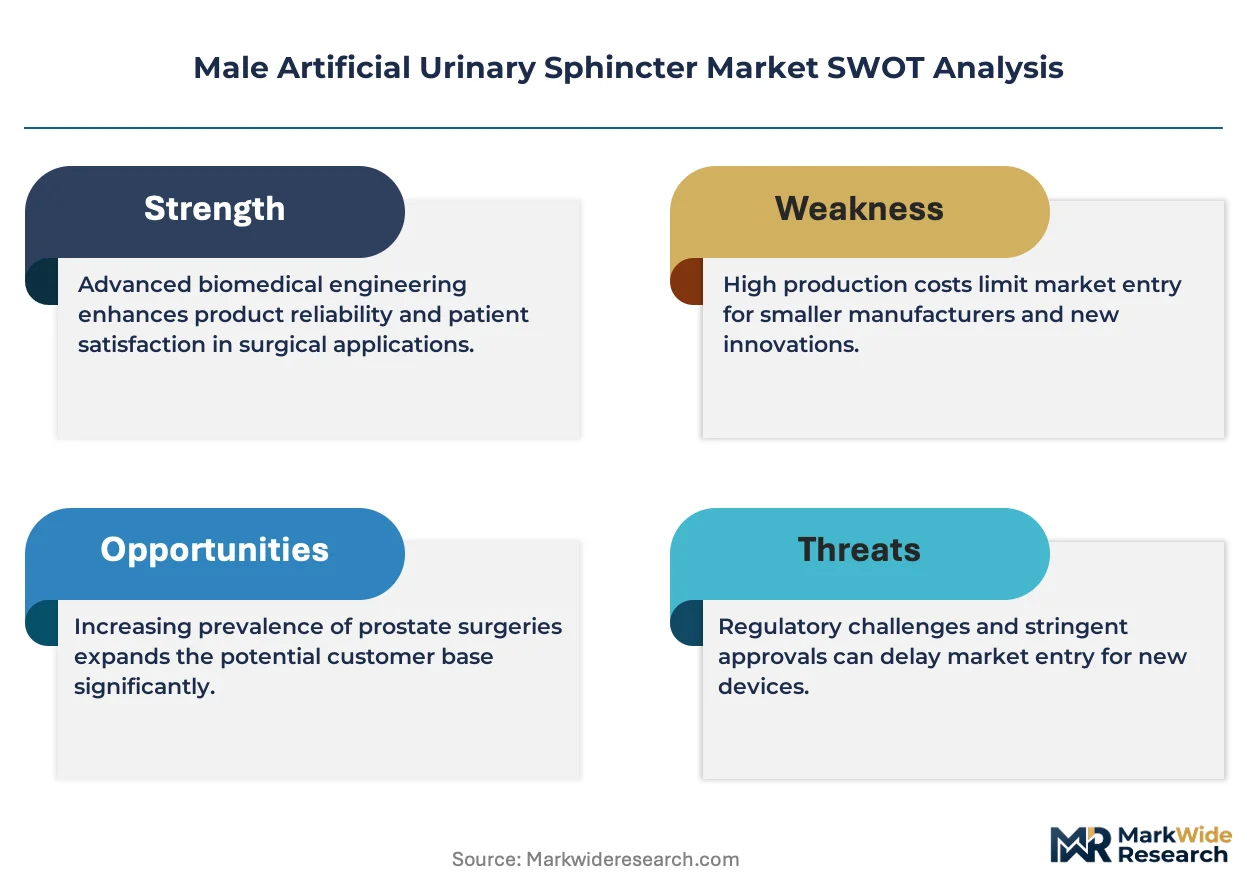
- Post-prostatectomy patient volume expansion:Radical prostatectomy rates in the United States continue generating iatrogenic stress urinary incontinence cases requiring surgical intervention, sustaining procedural demand for implantable sphincter systems.
- Medicare reimbursement stability:Center for Medicare and Medicaid Services coverage determinations for artificial urinary sphincter implantation and revision procedures reduce financial barriers for eligible beneficiaries in American healthcare markets.
- Silicone elastomer biocompatibility advances:Improved material formulations with reduced encrustation and tissue erosion profiles extend functional implant survival, reinforcing physician confidence in long-term patient outcomes.
Market Restraints
- Single-supplier silicone medical-grade dependency:Concentrated sourcing of implant-grade silicone elastomer from specialized chemical manufacturers creates input vulnerability and price inelasticity for device producers.
- EU MDR clinical data requirements:Intensified post-market surveillance obligations and extended notified body review timelines under European Medical Device Regulation delay product modifications and new market entries.
- Conservative management alternatives:External penile compression devices and absorbent products retain patient preference among mild-to-moderate incontinence cases, capping addressable surgical candidacy.
Strategic Opportunities
- Robotic surgical platform integration:Da Vinci and competing robotic systems enable precision cuff placement with reduced operative morbidity, opening procedural access to high-volume academic medical centers.
- Patient-reported outcome data monetization:HIPAA-compliant registries capturing long-term continence scores create service revenue streams and differentiation tools for manufacturers with established implant populations.
- India private urology network expansion:Rising medical tourism infrastructure and domestic prostate cancer screening penetration in Indian metropolitan markets present first-mover positioning for premium implant suppliers.
Industry Challenges
- Explant analysis expertise scarcity:Specialized biomedical engineering capabilities for failed device retrieval and failure mode identification concentrate in limited academic pathology departments, constraining rapid design iteration feedback loops.
- CE marking transition backlog:European notified body capacity constraints under MDR implementation create certification queue delays, forcing inventory allocation decisions across regional distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Male Artificial Urinary Sphincter Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Sphincter, Magnetic Sphincter, Semi-Rigid Sphincter, Others End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Surgical Technique, Minimally Invasive Procedure, Open Surgery, Robotic Surgery Application: Post-Prostate Surgery, Neurogenic Bladder, Stress Urinary Incontinence, Others |
| Companies Covered | Affluent Medical, Rigicon, Inc., Boston Scientific Corporation, GT Urological, Promedon GmbH, Zephyr Surgical Implants, UroMems Inc., RBM-Med, Coloplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Male Artificial Urinary Sphincter Market Evolving Landscape
Active compression mechanism redesign is collapsing historical trade-offs between occlusion pressure and urethral perfusion that previously forced compromise in device engineering. These technical advances are enabling new competitive positioning around reduced revision rates.
Magnetic resonance imaging-conditional sphincter construction is collapsing compatibility barriers that previously excluded implanted patients from diagnostic oncology surveillance protocols. Academic medical centers with integrated prostate cancer follow-up programs are prioritizing these configurations in purchasing decisions. The technology is compressing device selection criteria toward multimodal imaging compatibility as a standard specification.
FDA intensification of long-term implant survival data requirements is extending premarket submission preparation timelines and expanding clinical trial cost structures for new device entrants. The agency's renewed focus on mechanical failure mode documentation is forcing manufacturers to maintain explant retrieval programs. Small and mid-sized developers without established post-market surveillance infrastructure face disproportionate compliance burden relative to established competitors with legacy implant populations.
Hospital value analysis committees are consolidating purchasing authority for high-cost urological implants, displacing individual surgeon preference as the dominant selection criterion. Integrated delivery networks in the United States are negotiating system-wide contracts with performance guarantees tied to revision-free survival metrics. This concentration is most visible in Medicare Advantage–dominated markets where capitated reimbursement intensifies cost accountability across the care continuum.
Male Artificial Urinary Sphincter Market Segmentation
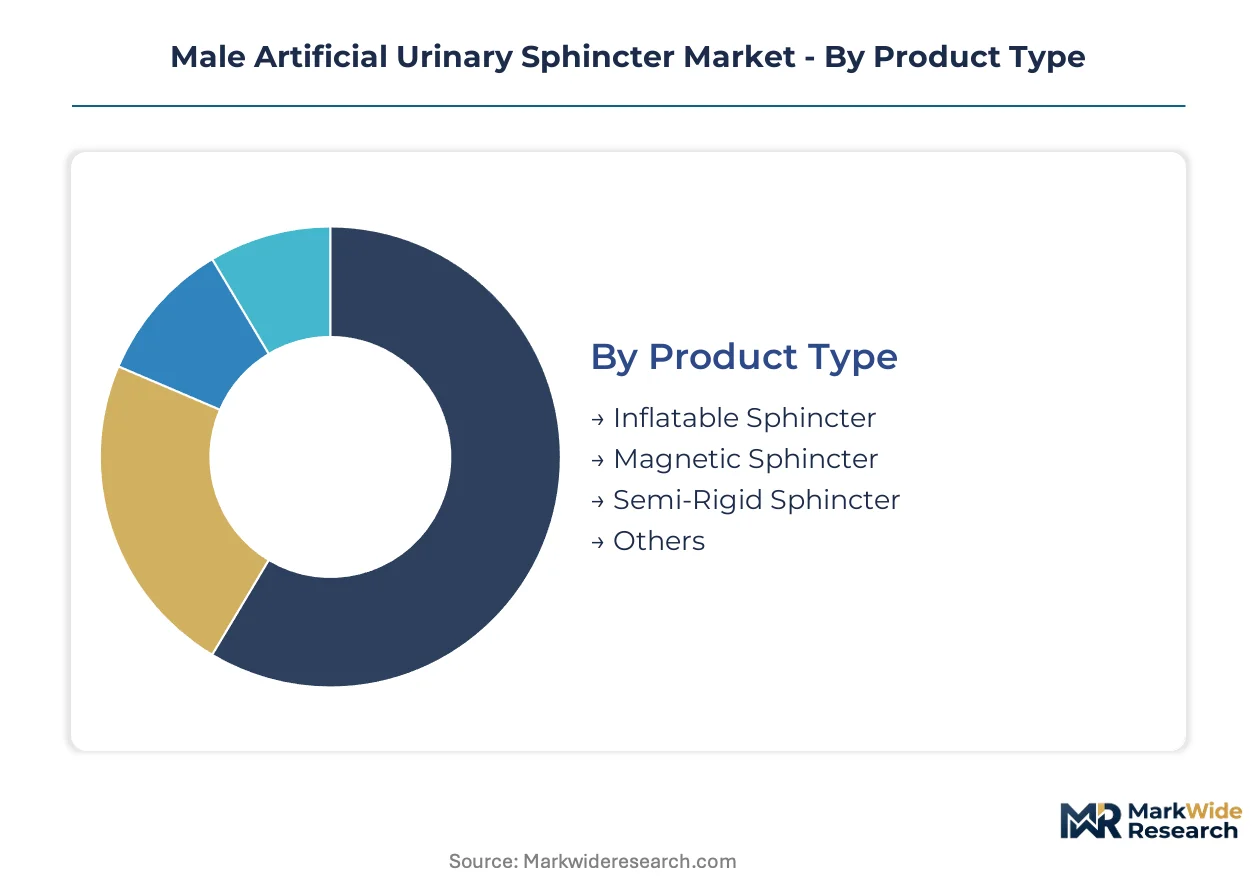
Segmentation in the male artificial urinary sphincter market reveals distinct procurement rhythms and clinical decision hierarchies. Product type stratification separates premium hydraulic systems from entry-level mechanical alternatives, while technology segmentation tracks the migration toward reduced operative morbidity across hospital settings.
Product Type:
Replacement cycles vary dramatically across this category, with inflatable systems requiring revision every 7-10 years while semi-rigid alternatives demand earlier intervention due to mechanical fatigue.
- Inflatable Sphincter:Three-component hydraulic systems employing silicone elastomer cuffs, pressure-regulating balloons, and scrotal pumps dominate procedural volume. Medicare reimbursement stability in the United States sustains hospital investment in these premium devices despite higher upfront acquisition costs relative to mechanical alternatives.
- Magnetic Sphincter:Magnetic resonance-conditional constructions eliminate imaging compatibility barriers for prostate cancer surveillance protocols. Academic medical centers with integrated oncology follow-up programs in Germany and the United States prioritize these configurations to preserve diagnostic access.
- Semi-Rigid Sphincter:Simpler mechanical designs offer reduced surgical complexity for resource-constrained settings.
- Others:Experimental and hybrid mechanisms remain in limited clinical evaluation.
Inflatable Sphincter dominates installed base. Magnetic Sphincter is where expansion concentrates.
End User:
Procurement authority concentrates differently across this category, with integrated delivery networks consolidating high-value implant purchasing while independent urology clinics retain discretion for conservative management devices.
- Hospitals:Academic medical centers and community hospital systems perform the majority of primary implantations and revision procedures. Value analysis committees in United States Medicare Advantage markets negotiate system-wide contracts with revision-free survival guarantees.
- Clinics:Specialized urology clinics handle patient evaluation, device activation training, and long-term surveillance. Outpatient procedure migration toward ambulatory surgical centers in metropolitan United States markets compresses length-of-stay economics.
- Home Care:Post-activation patient education and pump manipulation training occur in home settings.
- Rehabilitation Centers:Pelvic floor rehabilitation integration supports surgical candidacy assessment.
Hospitals capture procedural revenue concentration. Clinics are gaining share fastest in patient acquisition and longitudinal management.
Technology:
Learning curve duration and capital equipment requirements create tiered adoption barriers across surgical approaches, with robotic platforms demanding substantial institutional investment.
- Minimally Invasive Procedure:Laparoscopic and perineal approaches with reduced catheterization periods and operative morbidity expand patient eligibility. Da Vinci system integration at high-volume United States academic centers enables precision cuff placement with shorter recovery trajectories.
- Robotic Surgery:Robotic platforms command premium positioning through enhanced visualization and suturing precision. Hospital capital allocation committees in Germany and the United States prioritize these configurations for competitive differentiation in prostate cancer care continuums.
- Surgical Technique:Broad category encompassing established open and minimally invasive methodologies.
- Open Surgery:Perineal and transabdominal approaches retain indication for complex revision cases.
Surgical Technique holds legacy volume concentration. Minimally Invasive Procedure shows the steepest expansion trajectory.
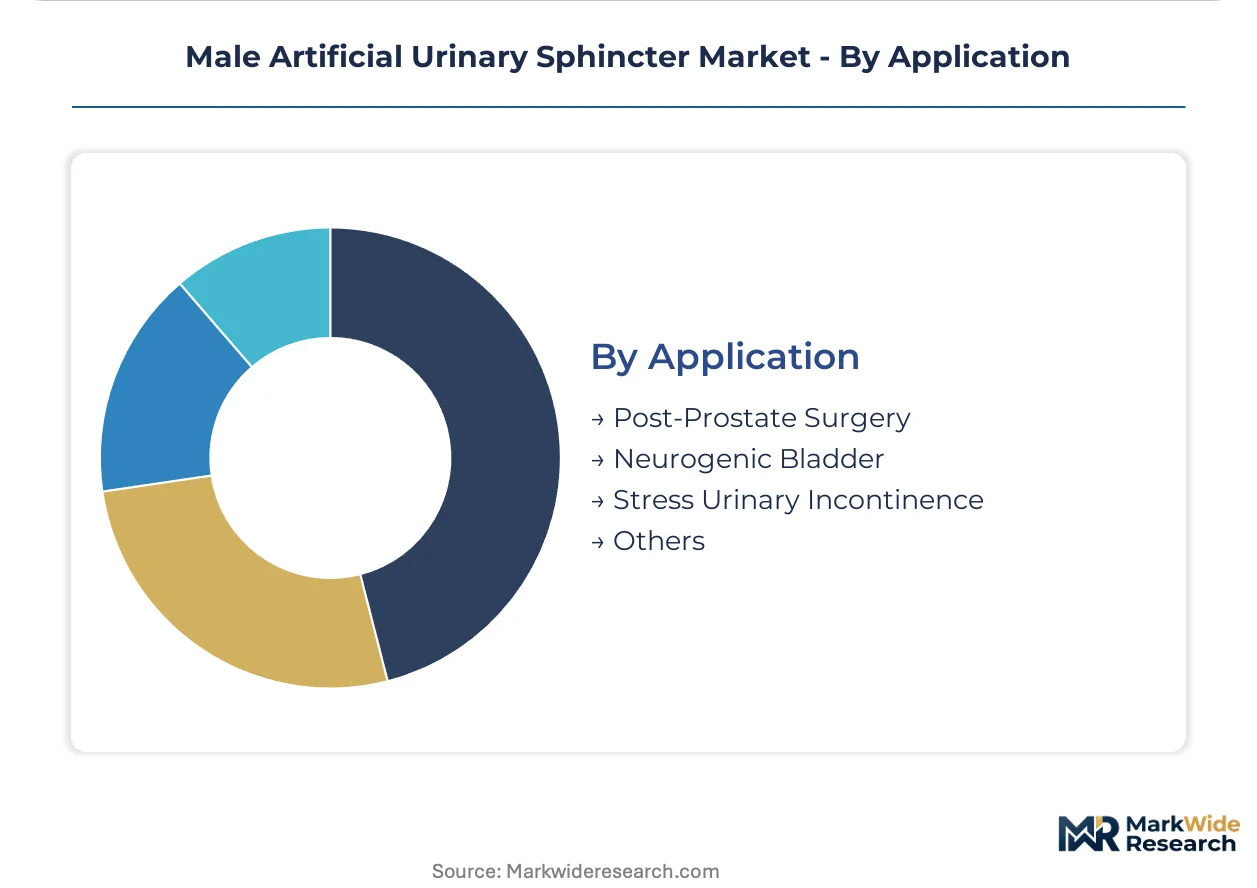
Application:
Disease etiology determines reimbursement pathway complexity and patient candidacy screening intensity across this category.
- Post-Prostate Surgery:Iatrogenic stress urinary incontinence following radical prostatectomy generates the dominant procedural demand. Rising prostate cancer screening penetration in Indian metropolitan markets and stable radical prostatectomy rates in the United States sustain addressable case volume.
- Stress Urinary Incontinence:Idiopathic and mixed etiology cases represent secondary demand concentration. Conservative management failure documentation requirements under CMS coverage determinations in the United States extend evaluation timelines.
- Neurogenic Bladder:Spinal cord injury and multiple sclerosis populations require specialized multidisciplinary assessment.
- Others:Congenital anomalies and trauma-related indications comprise residual volume.
Post-Prostate Surgery anchors revenue concentration. Stress Urinary Incontinence is climbing the fastest as diagnostic awareness expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement stability in the United States sustains procedural volume for implantable urological devices, while the European Union Medical Device Regulation intensifies documentation requirements across member states. National health technology assessment programs in Germany and France increasingly weigh long-term implant survival data in coverage determinations.
United States
Radical prostatectomy rates generate substantial iatrogenic stress urinary incontinence caseloads requiring surgical intervention. FDA premarket notification pathways for implantable urological devices mandate comprehensive biocompatibility documentation and mechanical failure mode analysis. Academic medical centers in Boston and Baltimore anchor clinical trial activity and post-market surveillance program enrollment.
Germany
Prostate cancer screening penetration and specialized urology center density support device utilization across statutory and private insurance pools. CE marking under EU MDR and BfArM post-market surveillance obligations extend notified body review timelines for product modifications. The Baden-Württemberg and Bavaria regions concentrate explant analysis expertise and biomedical engineering research partnerships.
France
HAS evaluation of medical devices incorporates patient-reported outcome thresholds for continence restoration procedures. ANSM vigilance reporting requirements shape manufacturer post-market surveillance infrastructure investments. The Île-de-France region hosts specialized continence care networks and academic urology departments with integrated prostate cancer follow-up programs.
India
Rising prostate cancer screening penetration in metropolitan markets expands addressable surgical candidacy among middle-class populations. CDSCO medical device registration requirements for implantable urological products intensify quality system documentation obligations. Private urology networks in Maharashtra and Karnataka develop medical tourism infrastructure for premium implant procedures.
United Kingdom
NICE technology appraisal processes evaluate cost-effectiveness thresholds for artificial urinary sphincter implantation against conservative management alternatives. MHRA vigilance reporting and UKCA marking transition requirements create regulatory adaptation costs for device suppliers. The Greater London and Manchester metropolitan areas concentrate specialized pelvic floor surgery capacity and multidisciplinary incontinence assessment clinics.
Male Artificial Urinary Sphincter Market Competitive Landscape
On the supply side, the industry is consolidating around established urology portfolios and specialized continence care distribution channels. Three-component hydraulic systems dominate value generation through premium pricing and revision procedure economics. Strategic archetypes include diversified medical technology conglomerates, specialized urological device manufacturers, and emerging competitors with differentiated mechanical designs. Competitive dynamics center on hospital contracting relationships and post-implant surveillance service capabilities.
Among diversified medical technology suppliers, Boston Scientific Corporation anchors North American hospital contracting networks through established urology portfolio breadth. Coloplast exemplifies specialized continence care channel dominance in European markets. Affluent Medical occupies a position within the emerging competitor tier, representing differentiated hydraulic design approaches targeting reduced revision rates.
| Leading Market Players |
|---|
| Affluent Medical |
| Rigicon, Inc. |
| Boston Scientific Corporation |
| GT Urological |
| Promedon GmbH |
| Zephyr Surgical Implants |
| UroMems Inc. |
| RBM-Med |
| Coloplast |
| Others |
Value Network & Pricing Analysis
Transatlantic air freight corridors from Frankfurt to Chicago carry implant-grade silicone elastomer shipments where fuel surcharge volatility amplifies cost differentials between FDA-grade and CE-grade device tiers, concentrating pricing power among manufacturers with backward-integrated polymer sourcing while forcing smaller competitors toward standard-grade material substitutions that compress margins in Medicare-reimbursed segments.
Pricing Analysis
Certification level creates the primary spread between premium and standard device tiers, with FDA 510(k)-cleared systems commanding substantial premiums over CE-marked alternatives due to enhanced biocompatibility documentation and explant retrieval program investments. Three-tier pricing structure across premium, standard, and economy levels reflects silicone purity grades, radiopaque marker density, and pressure-regulating balloon durability specifications. Cost compression in the economy tier is intensifying because Indian private urology networks negotiate volume-based procurement contracts that force manufacturers to absorb logistics expenses. Hospital value analysis committees in United States Medicare Advantage markets demonstrate lowest price sensitivity due to capitated reimbursement structures, while independent European clinics exhibit highest sensitivity amid EU MDR compliance cost pass-through disputes.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk calculus for specialized silicone medical-grade manufacturers, with cross-border component transfers facing escalating customs scrutiny under evolving trade enforcement protocols. Implant-grade silicone elastomer production concentrates in Germany, the United States, and Japan, with specialized polymerization capabilities tethered to pharmaceutical-grade cleanroom infrastructure. Device assembly draws from radiopaque marker suppliers in Switzerland, pressure-regulating balloon membrane specialists in Ireland, and scrotal pump valve mechanism producers in the United States. Single-source vulnerability pervades medical-grade silicone precursor sourcing, where two specialized chemical manufacturers control global supply. Distribution runs through hospital system contracting networks in North America and specialized continence care distributors in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power in the male artificial urinary sphincter market is consolidating around integrated delivery networks and hospital value analysis committees, with individual surgeon preference displaced by system-wide procurement authority that extracts performance guarantees and revision-free survival commitments from device suppliers.
For Market Incumbents: Insulate market position through captive supply arrangements for implant-grade silicone elastomer that neutralize raw material cost volatility, while expanding post-implant surveillance service capabilities to deepen hospital contracting relationships against emerging competitors with differentiated hydraulic designs. Prioritize explant retrieval program investments that satisfy FDA intensified mechanical failure mode documentation requirements, converting regulatory compliance burden into competitive moat against smaller developers lacking legacy implant populations. For New Entrants and Emerging Players: Indian metropolitan private urology networks present the most penetrable geographic expansion opportunity, where rising prostate cancer screening penetration and medical tourism infrastructure development outpace established supplier distribution coverage. Target Maharashtra and Karnataka state markets through CDSCO registration pathway investments and local clinical partnership structures that bypass incumbent hospital system contracting lock-in. Pursue robotic surgical platform integration as primary go-to-market angle, positioning precision cuff placement capabilities for academic medical center capital allocation committees prioritizing Da Vinci system compatibility. For Investors and Strategic Acquirers: EU MDR notified body capacity constraints and extended review timelines reshape the acquisition landscape toward targets with existing CE marking certificates and established post-market surveillance infrastructure that circumvent certification queue delays. Frame long-term viability around implant longevity engineering capabilities and patient-reported outcome data monetization potential across five-to-ten year holding horizons. Monitor FDA premarket notification submission volumes for artificial urinary sphincter modifications as inflection indicator for competitive intensity and pricing pressure direction.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates market access for MRI-conditional device configurations in German academic centers. |
| Hospital System Partnership | Integrated delivery network contracts in United States Medicare Advantage markets secure revision procedure revenue streams. |
| Backward Integration | Captive silicone elastomer supply neutralizes price inelasticity from specialized chemical manufacturers. |
| Software Companion Development | HIPAA-compliant patient-reported outcome registries create differentiated service revenue and clinical evidence bases. |
| Reimbursement Strategy | CMS coverage determination alignment ensures procedural access for eligible Medicare beneficiaries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Primary interviews engaged urologists, hospital purchasing committee members, biomedical engineers specializing in explant analysis, GPO contracts managers, and regulatory affairs leads at device manufacturers. Bottom-up triangulation across implant procedure volumes, revision rates, and device ASPs validates top-down market sizing derived from manufacturer revenue disclosures and trade data.
Forecast inputs include radical prostatectomy incidence trajectories, Medicare reimbursement stability assessments, and EU MDR implementation pace across member states. The analytical framework segments by product type, end user, technology, and application dimensions, with CAGRs derived from regression analysis against prostate cancer screening penetration and specialized urology center density metrics. Silicone elastomer supply constraints and robotic surgical platform adoption curves inform industry-specific forecast adjustments across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by diversified medical technology conglomerates would shift competitive dynamics and pricing outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Self-Injections Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Enteral Stents Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Urine Flow Meters Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Gel Implants Market
Medical Devices
Medical Device Cros Market
Medical Devices
Rigid Laparoscope Market