
 India Respiratory Devices Market | 2026-2036
India Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Respiratory Devices Market Foresight
Multi-source procurement for critical components is recalibrating how domestic manufacturers secure sensors and flow-control assemblies. Philips Healthcare leverages its Bengaluru R&D base to sustain localization of CPAP circuit designs. Cipla anchors the mid-tier inhaler segment through extensive pulmonary therapy distribution. ResMed competes on connected-care platforms that integrate cloud-based adherence monitoring for sleep apnea patients.
India respiratory devices comprise therapeutic and diagnostic equipment engineered to deliver controlled gas flow, aerosolized medication, or positive airway pressure with precision tolerances typically within two liters per minute for oxygen delivery systems. These instruments serve acute hospital ventilation, chronic disease management, and ambulatory respiratory support across clinical and domestic environments. Inhalers and nebulizers command substantial volume due to India's high asthma and COPD burden, while oxygen concentrators emerged as a high-growth category following supply chain stress during the pandemic period. CPAP devices occupy a premium niche where patient compliance data increasingly determines reimbursement eligibility and brand stickiness.
CDSCO's Medical Device Rules govern product registration, clinical evaluation, and post-market surveillance for all respiratory equipment sold in India. BIS certification for electrical safety and electromagnetic compatibility creates additional compliance layers for imported and locally manufactured devices. The PLI scheme for medical electronics offers production-linked incentives that encourage domestic assembly of ventilators and oxygen concentrators. Stakeholders must monitor how CDSCO's risk-based classification updates and state-level tender standardization reshape competitive access across public hospital networks.
Market Dynamics
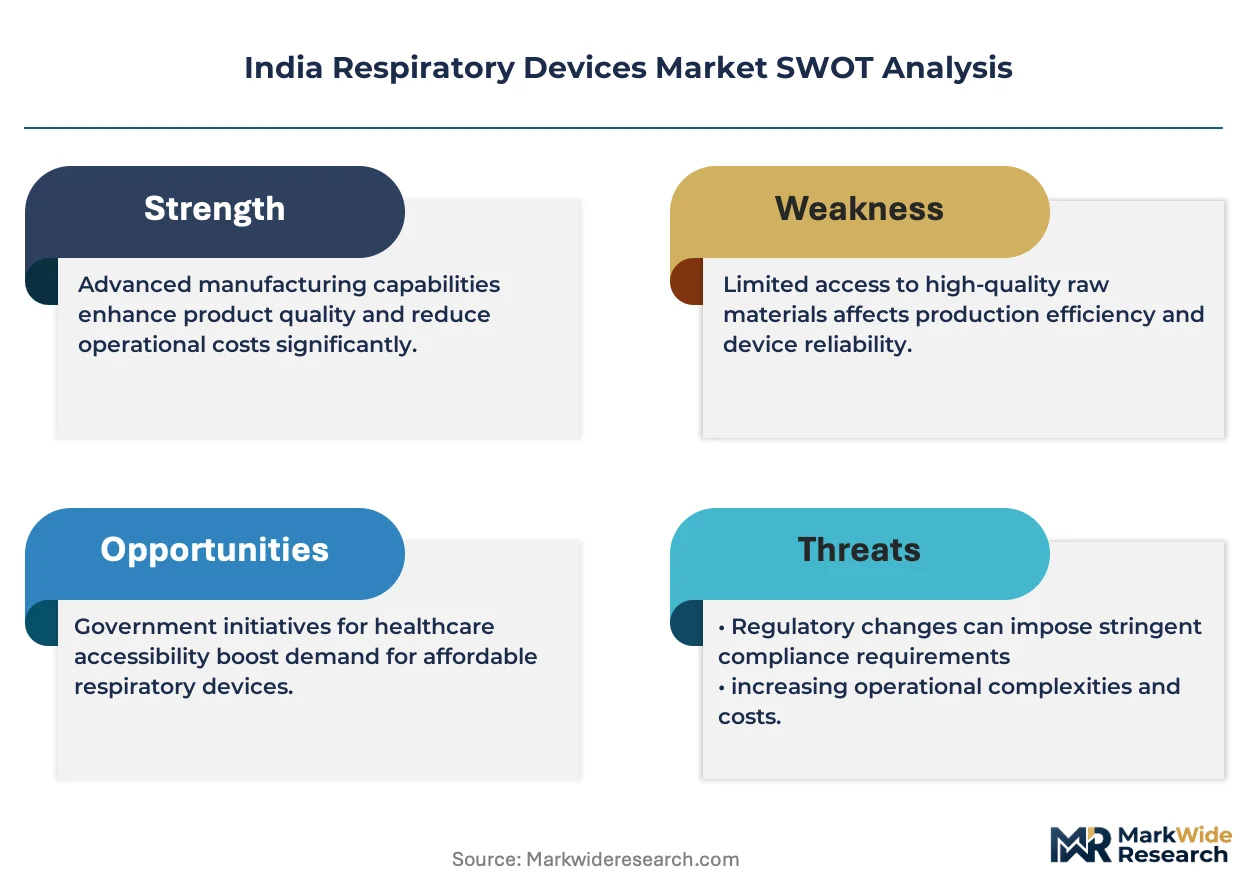
Mesh nebulizer technology and CDSCO's tightened quality surveillance are compressing margins for legacy compressor-based devices while rewarding precision-engineered alternatives that meet Class C device standards.
Growth Catalysts
- CDSCO's 2022 Medical Device Rules:Risk-based classification elevates respiratory equipment to Class C, creating entry barriers that favor established manufacturers with clinical evaluation capabilities.
- Homecare oxygen therapy:Maharashtra and Karnataka urban corridors are expanding portable concentrator deployment through hospital-at-home programs and pulmonologist-led chronic care networks.
- PLI scheme for medical electronics:Production-linked incentives covering ventilators and oxygen concentrators are attracting component localization investments into Bengaluru and Pune manufacturing clusters.
Market Restraints
- Sensor import dependency:Flow-control assemblies and pressure transducers concentrate in East Asian supply chains, exposing domestic assemblers to currency volatility and extended lead times.
- BIS electromagnetic compatibility testing:Mandatory certification for electrical safety creates 4-6 month approval bottlenecks that delay product launches and tie up working capital.
- Refurbished CPAP penetration:Gray-market recertified devices from Gulf return channels undercut authorized distribution in price-sensitive tier-2 cities.
Strategic Opportunities
- Tier-3 city diagnostic penetration:Kerala and Tamil Nadu district hospital networks lack spirometry infrastructure, creating whitespace for handheld diagnostic devices with simplified operator interfaces.
- Cloud-connected adherence platforms:Integration of cellular-enabled CPAP machines with pulmonologist dashboards enables remote titration and recurring revenue service models.
- DGFT export promotion schemes:Duty drawback benefits and EPCG licenses incentivize respiratory device manufacturers to target SAARC and African markets with India-origin certification.
Industry Challenges
- Biomedical engineering talent scarcity:Ventilator calibration and sleep therapy device programming require specialized skills that outpace Indian technical institute output.
- State tender standardization fragmentation:Each public health department maintains distinct technical specifications, forcing manufacturers to maintain multiple product variants and documentation sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Respiratory Devices Market |
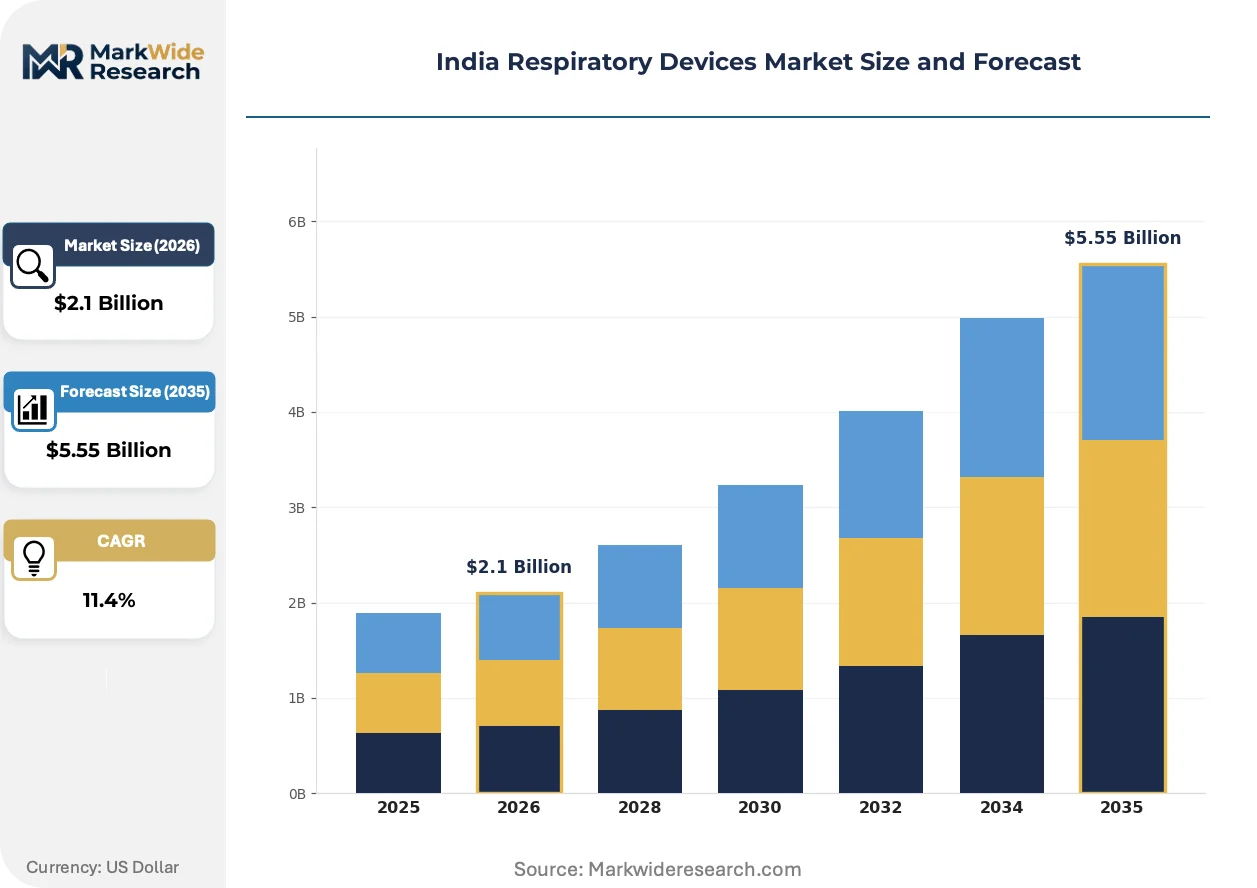
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Devices, Oxygen Concentrators End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Technology: Electronic, Manual, Portable, Hybrid Application: Asthma, COPD, Sleep Apnea, Respiratory Infections |
| Companies Covered | Fisher & Paykel Healthcare, Drägerwerk AG & Co. KGaA, Philips Healthcare, Masimo Corporation, Hamilton Medical, ResMed, GE Healthcare, Cipla, Medtronic plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Respiratory Devices Market Shifts & Advancements
Digital health integration and miniaturization are redefining device architecture, with manufacturers racing to embed connectivity and reduce power consumption for ambulatory use cases.
Mesh nebulizer piezoelectric technology is consolidating the acute and chronic aerosol therapy segments by replacing compressor-driven systems in pediatric and geriatric applications. Pulmonology clinics in Delhi-NCR and Mumbai are adopting these silent, portable units for office-based administration. The technology is consolidating procurement decisions around single-platform vendors who can supply both clinical and home-use variants under unified service contracts.
CDSCO's strengthened post-market surveillance mandates now require adverse event reporting and periodic safety update reports for all Class C respiratory devices. This regulatory burden disproportionately affects imported equipment, pushing multinational registrants to establish local pharmacovigilance capabilities or partner with Indian authorized representatives. The compliance cost gradient is accelerating registration withdrawals for low-volume legacy ventilator models.
Hospital procurement committees are unbundling device acquisition from consumables and service contracts, forcing manufacturers to compete on transparent lifecycle cost rather than upfront capital expenditure. This purchasing model shift compresses margins on oxygen concentrators and CPAP machines in Tamil Nadu and Karnataka corporate hospital chains. Western India municipal corporation tenders are piloting similar total-cost-of-ownership evaluation frameworks for public health infrastructure upgrades.
India Respiratory Devices Market Segmentation
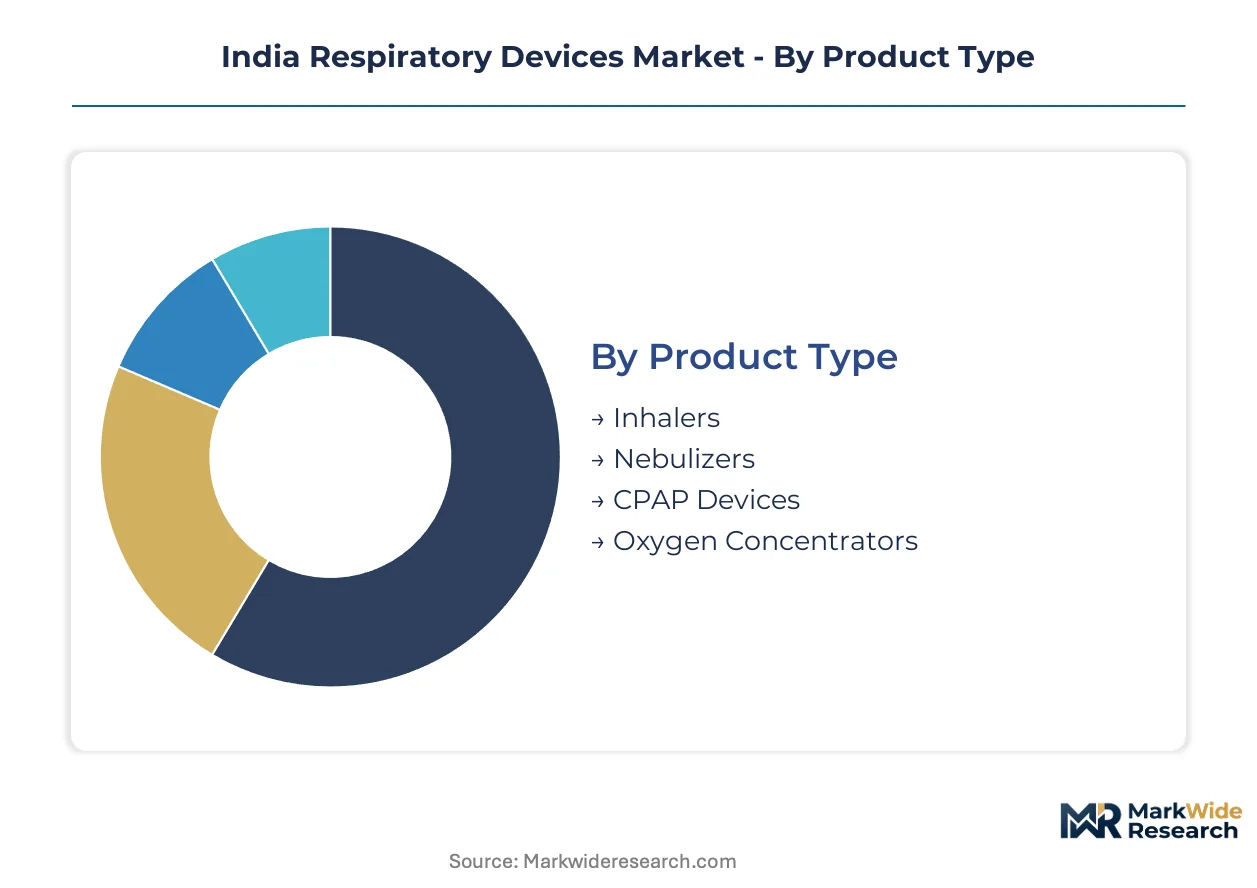
Segmentation in India's respiratory devices market reveals how clinical requirements, reimbursement pathways, and infrastructure availability fragment procurement decisions across public and private channels. Understanding these divides helps manufacturers align product specifications with the precise settings where volume concentrates.
Product Type:
Hospital procurement committees weight upfront capital against lifetime service costs when selecting between therapeutic modalities.
- Inhalers:Metered-dose and dry-powder inhalers deliver bronchodilators and corticosteroids through propellant or breath-actuated mechanisms with particle size optimization for distal lung deposition. Maharashtra and Karnataka pulmonology clinics drive volume for combination-therapy devices as CDSCO's Class C rules tighten quality documentation requirements.
- Nebulizers:Compressor and mesh nebulizers convert liquid medication into respirable aerosol for patients unable to coordinate inhaler technique. Mesh piezoelectric systems are displacing compressor units in Delhi-NCR pediatric practices where silent operation and portability command premium positioning.
- CPAP Devices:Continuous positive airway pressure machines maintain patent airways through calibrated pressure delivery with humidification and data logging for sleep apnea management.
- Oxygen Concentrators:Pressure-swing adsorption systems extract medical-grade oxygen from ambient air, with portable variants gaining traction in Bengaluru and Pune homecare networks.
Volume sits with inhalers; growth tilts toward oxygen concentrators.
End User:
Facility infrastructure determines device complexity tolerance and service contract expectations.
- Hospitals:Acute care settings demand ventilators, high-flow oxygen systems, and ICU-grade monitoring with centralized alarm management and biomedical engineering support. Tamil Nadu and Kerala corporate hospital chains unbundle device acquisition from consumables, compressing vendor margins through transparent lifecycle costing.
- Homecare:Ambulatory patients and caregivers operate portable concentrators, CPAP machines, and mesh nebulizers with simplified interfaces and cellular connectivity for remote monitoring. Western India municipal corporation tenders are piloting hospital-at-home programs that expand concentrator deployment through pulmonologist-led chronic care networks.
- Clinics:Outpatient pulmonary practices require handheld diagnostic and therapeutic devices for office-based administration with rapid patient turnover.
- Rehabilitation Centers:Post-acute facilities focus on weaning protocols and respiratory muscle training with ventilator-compatible exercise equipment.
Hospitals dominate installed base; homecare represents the steepest expansion trajectory.
Technology:
Power reliability and operator training availability shape technology selection across India's uneven electricity grid.
- Electronic:Microprocessor-controlled devices with sensor feedback, data logging, and algorithm-driven pressure or flow modulation require stable power and technical support infrastructure concentrated in tier-1 cities.
- Manual:Mechanical inhalers and simple oxygen delivery systems operate without electrical power, serving rural Maharashtra and Karnataka districts with intermittent grid access.
- Portable:Battery-powered concentrators and travel CPAP units with DC-AC conversion prioritize weight reduction and power efficiency for ambulatory and travel use cases.
- Hybrid:Devices combining manual backup with electronic primary operation bridge infrastructure gaps in tier-2 and tier-3 facility networks.
Electronic systems anchor revenue; portable configurations gain share fastest.
Application:
Disease prevalence patterns and reimbursement eligibility create distinct demand profiles across therapeutic indications.
- Asthma:Chronic airway inflammation requiring rescue bronchodilation and maintenance anti-inflammatory therapy drives inhaler volume across all age groups with seasonal exacerbation patterns.
- COPD:Progressive airflow limitation necessitating long-oxygen therapy, nebulized bronchodilators, and eventually non-invasive ventilation in advanced stages.
- Sleep Apnea:Obstructive and central sleep disordered breathing treated with CPAP, BiPAP, or adaptive servo-ventilation where adherence data increasingly determines insurance reimbursement eligibility.
- Respiratory Infections:Acute viral and bacterial pneumonias requiring short-term oxygen supplementation, nebulized antibiotics, or mechanical ventilation in severe presentations.
COPD commands the largest patient base; sleep apnea shows the fastest premium-device adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's pharmaceutical feedstock concentration anchors India's respiratory device manufacturing, with Mumbai-Pune corridor suppliers feeding active pharmaceutical ingredients into inhaler production while Bengaluru electronics clusters source sensors for oxygen concentrator assembly.
Maharashtra
Mumbai and Pune hospital networks drive demand for ICU ventilators and high-flow oxygen systems through corporate hospital chains expanding bed capacity. CDSCO's Class C device registration requirements compel manufacturers to establish local pharmacovigilance units in the state. The Mumbai-Pune pharmaceutical belt concentrates inhaler API production, with Cipla and domestic generics feeding metered-dose device assembly lines.
Karnataka
Bengaluru's pulmonology clinics and hospital-at-home programs are expanding portable oxygen concentrator deployment for COPD management. The state's PLI scheme incentives attract medical electronics assembly for ventilator pressure transducers and flow sensors. Electronics City and Whitefield manufacturing zones host Philips Healthcare's R&D localization and domestic oxygen concentrator final assembly operations.
Tamil Nadu
Chennai corporate hospital chains unbundle device acquisition from service contracts, compressing vendor margins through transparent lifecycle costing for CPAP and oxygen concentrator procurement. BIS electromagnetic compatibility testing bottlenecks delay product launches for manufacturers serving this market. The Sriperumbudur-Oragadam industrial corridor hosts contract manufacturers assembling nebulizer components for export to SAARC markets.
Delhi-NCR
Specialty pulmonology practices in Delhi and Gurugram adopt mesh nebulizer technology for pediatric and geriatric aerosol therapy, displacing compressor-based systems. CDSCO headquarters proximity accelerates regulatory consultation for Class C device registrants seeking risk-based classification clarity. The Okhla industrial area concentrates refurbished medical device trading, with gray-market CPAP units from Gulf return channels undercutting authorized distribution.
Gujarat
Ahmedabad and Surat district hospital networks lack spirometry infrastructure, creating whitespace for handheld diagnostic device penetration with simplified operator interfaces. DGFT export promotion schemes incentivize respiratory device manufacturers in the state to target African markets with India-origin certification. The Sanand-Vadodara pharmaceutical zone supplies excipients and packaging materials for inhaler device assembly across western India.
India Respiratory Devices Market Competitive Landscape
Localization of R&D and manufacturing dominates the current landscape as multinational registrants establish Indian authorized representatives and domestic assemblers expand component sourcing. The market structures around three tiers: multinational device manufacturers with CDSCO Class C registration capabilities, mid-tier domestic assemblers leveraging PLI incentives, and regional distributors of refurbished or economy-grade equipment. Strategic archetypes include technology licensors transferring mesh nebulizer piezoelectric designs, integrated hospital solution providers bundling devices with service contracts, and export-focused assemblers targeting SAARC duty drawback benefits. Competitive moves concentrate on backward integration into sensor sourcing and geographic expansion through state-level tender participation.
Among multinational device manufacturers, Philips Healthcare exemplifies the R&D localization archetype through its Bengaluru engineering base, while ResMed occupies a position within the connected-care platform tier emphasizing cloud-based adherence monitoring. Cipla represents the domestic pharmaceutical-integrated model, anchoring mid-tier inhaler distribution through established pulmonary therapy networks. These three companies illustrate how regulatory compliance capabilities, manufacturing scale, and distribution reach stratify competitive positioning across India's respiratory device procurement channels.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| Drägerwerk AG & Co. KGaA |
| Philips Healthcare |
| Masimo Corporation |
| Hamilton Medical |
| ResMed |
| GE Healthcare |
| Cipla |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Backward integration into sensor sourcing anchors competitive positioning for domestic oxygen concentrator assemblers while compressing margins for import-dependent competitors. CDSCO's Class C device registration requirements and BIS electromagnetic compatibility certification create compliance cost gradients that separate premium-tier multinationals from mid-tier local manufacturers.
Pricing Analysis
Warranty and service contract unbundling is reshaping procurement negotiations across Tamil Nadu and Karnataka corporate hospital chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales support depth. Cost compression in the standard tier is intensifying because state tender committees now evaluate total lifecycle expenditure rather than capital outlay alone. Tier-2 municipal hospitals exhibit the sharpest price sensitivity; premium sleep therapy clinics show the least.
Supply Chain Analysis
Reverse-logistics flows for refurbished CPAP units from Gulf return channels are undercutting authorized distribution in Delhi-NCR and tier-2 cities. Flow-control assemblies and pressure transducers draw from East Asian manufacturing clusters, while pharmaceutical excipients for inhaler production rest on Mumbai-Pune suppliers. Single-source vulnerability concentrates in piezoelectric mesh components for nebulizer assembly. Distribution runs through state-level tender networks and pulmonologist-led chronic care programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CDSCO's risk-based classification under the 2022 Medical Device Rules constructs a compliance moat that rewards established registrants with clinical evaluation capabilities and authorized representative infrastructure.
For Market Incumbents: Anchor market position through captive supply of pressure transducers and flow sensors to offset East Asian import dependency. Deepen backward integration into Bengaluru electronics clusters while defending against gray-market refurbished CPAP penetration through extended warranty bundling. For New Entrants and Emerging Players: District hospital networks in Kerala and Tamil Nadu represent the most penetrable buyer archetype for handheld spirometry devices with simplified operator interfaces. Pursue white-label manufacturing partnerships with existing CDSCO registrants to bypass 4-6 month BIS certification bottlenecks while targeting export promotion schemes for SAARC markets. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational device manufacturers seeking authorized representative capabilities and local pharmacovigilance infrastructure. Long-term viability favors targets with demonstrated CDSCO Class C registration success and component localization under PLI scheme incentives. Monitor state tender standardization pilots for early signals of procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C Registration Investment | Establishes regulatory barrier-to-entry moat against unregistered competitors in hospital procurement. |
| Mesh Nebulizer Technology Licensing | Captures pediatric and geriatric aerosol therapy segments displacing legacy compressor systems. |
| Cloud-Connected Adherence Platform Development | Enables recurring revenue service models integrated with pulmonologist dashboard remote monitoring. |
| Component Localization Under PLI Scheme | Reduces currency exposure on East Asian sensor imports while qualifying for production-linked incentives. |
| State Tender Standardization Participation | Secures volume commitments through Maharashtra and Karnataka municipal corporation hospital-at-home programs. |
Research Methodology
Independent corroboration across hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and CDSCO regulatory consultants underwrites the qualitative findings. Primary fieldwork combined with secondary validation from CDSCO registration databases, BIS certification records, state tender documentation, and PLI scheme beneficiary disclosures anchors the analysis. Bottom-up and top-down triangulation cross-checks manufacturer shipment data against hospital procurement records and distributor inventory positions.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user facility tier, technology power dependency, and therapeutic application. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and adjusted for regulatory inflection points. Forecast inputs incorporate PLI scheme disbursement schedules and state-level chronic disease prevalence projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CDSCO risk-classification updates and East Asian supply chain disruptions. Practitioners should monitor state tender unbundling pilots and mesh nebulizer patent expiration schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Nebulizer Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Global Medical Dynamometer Market
Medical Devices
US Medical Device Manufacturers Market