
 Banana Bread Market | 2026-2036
Banana Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Banana Bread Market Intelligence
Southeast Asia is narrowing its gap in banana flour processing capacity as regional mills upgrade drying and milling infrastructure to supply gluten-free banana bread formulations. King Arthur Baking Company leverages its direct-to-consumer recipe ecosystem to anchor premium mix sales. Grupo Bimbo sustains retail shelf dominance through refrigerated distribution networks spanning Latin America and select US corridors. Yamazaki Baking competes in Asian convenience channels with individually wrapped mini-loaf formats engineered for vending and grab-and-go retail.
Banana bread denotes a chemically leavened quick bread whose crumb structure derives from mashed ripe bananas, wheat or alternative flours, and a fat source, with moisture content typically ranging from 35% to 45% to achieve shelf-stable softness without preservatives. Its primary commercial purpose spans retail bakery, foodservice breakfast programs, and at-home preparation via prepared mixes. Fresh banana bread commands the largest revenue pool in North American supermarkets, while gluten-free variants capture expanding margin premiums as cassava and banana-flour blends displace traditional wheat formulations. Online retail channels for banana bread mixes are accelerating fastest, though bakeries retain higher per-unit profitability through impulse-driven slice sales and seasonal flavor rotations.
FDA nutrition-labeling rules on added sugars and serving-size definitions directly reshape banana bread formulation targets and front-of-package claims in the United States. USDA organic certification and Non-GMO Project verification create tiered market access thresholds that specialty brands must navigate for premium positioning. Stakeholders should monitor evolving FDA guidance on refined-grain reduction targets and state-level sugar-tax proposals that could recalibrate product architecture across retail and foodservice segments.
Market Dynamics
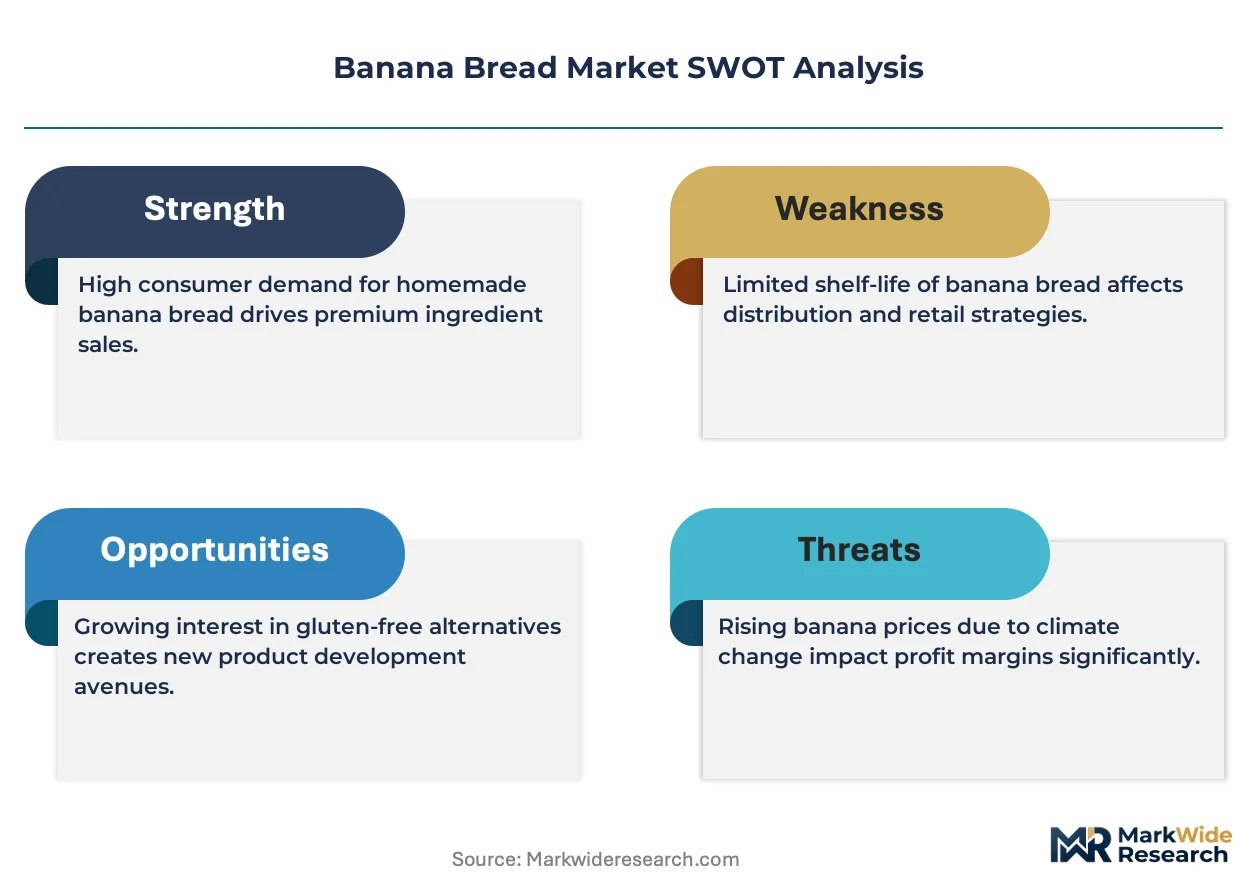
Banana bread formulation is pivoting around FDA added-sugar disclosure mandates, forcing reformulation of legacy recipes and recalibration of front-of-package claims across US retail channels.
Growth Catalysts
- Clean-label reformulation:Reduced-sugar recipes align with FDA nutrition-labeling requirements for added sugars disclosure, unlocking shelf space in health-focused retail sets.
- Breakfast convenience culture:US household penetration sustains demand for grab-and-go formats, with supermarket bakeries expanding private-label offerings to capture impulse purchases.
- Gluten-free flour innovation:Cassava and banana-flour blends displace wheat formulations, capturing margin premiums in specialty diet segments.
Market Restraints
- Input cost volatility:Ripe banana supply fluctuates with tropical weather patterns, compressing margins for processors dependent on spot-market procurement.
- Supply concentration risk:Southeast Asian milling infrastructure upgrades lag demand growth, creating bottlenecks for gluten-free flour supply chains.
- Regulatory friction:State-level sugar-tax proposals in the US threaten to recalibrate product architecture and pricing thresholds.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer mix sales accelerate fastest, bypassing traditional bakery distribution constraints.
- USDA organic certification tier:Premium positioning through organic and Non-GMO Project verification creates defensible margin pools.
- Vending format engineering:Individually wrapped mini-loaf formats unlock Asian convenience channels and grab-and-go retail.
Industry Challenges
- Refrigerated distribution complexity:Fresh banana bread shelf-life requirements demand cold-chain integrity that fragments logistics networks.
- Clean-label certification timelines:USDA organic and Non-GMO Project verification create multi-month approval bottlenecks for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banana Bread Market |
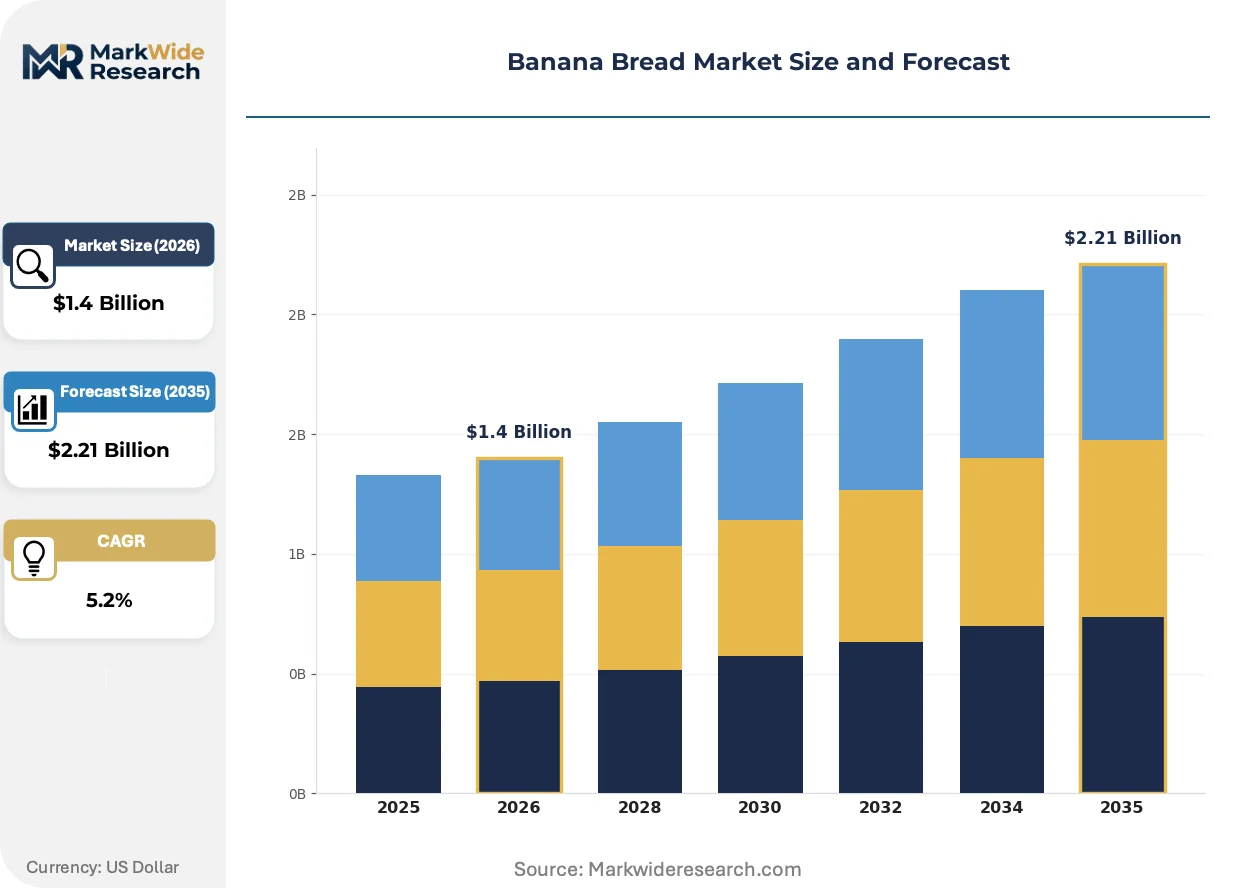
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Banana Bread, Frozen Banana Bread, Mixes, Gluten-Free Distribution Channel: Online Retail, Supermarkets, Bakeries, Specialty Stores Consumer Type: Health-Conscious Consumers, Families, Students, Foodies Serving Size: Individual Loaves, Slices, Bulk Packages, Mini Loaves |
| Companies Covered | King Arthur Baking Company, Aryzta, Grupo Bimbo, Papa Joe's Bakehouse, Yamazaki Baking, General Mills, Simple Mills, Banana Bread Company, Flowers Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banana Bread Market Strategic Shifts & Innovations
Formulation science and channel engineering are converging to reshape how banana bread reaches consumers, with regulatory pressure and convenience demand pulling in parallel directions.
Alternative flour technology is migrating from niche gluten-free applications toward mainstream shelf-stable formulations. Cassava-banana flour blends now anchor premium mix lines for home bakers seeking wheat alternatives. King Arthur Baking Company anchors this shift through recipe ecosystems that normalize unfamiliar ingredients.
FDA serving-size definitions and added-sugar disclosure rules are compressing allowable sweetness levels in commercial formulations. Front-of-package claims must now reconcile with backend nutrition panels. US supermarket bakeries respond with reduced-sugar private-label lines that maintain moisture through fat-source reformulation.
Foodservice procurement is unbundling traditional bakery supply relationships in favor of seasonal flavor-rotation contracts. Slice-based impulse sales now dominate breakfast programs and café channels. This pattern concentrates in US urban corridors where grab-and-go occasions outpace sit-down consumption.
Banana Bread Market Segmentation
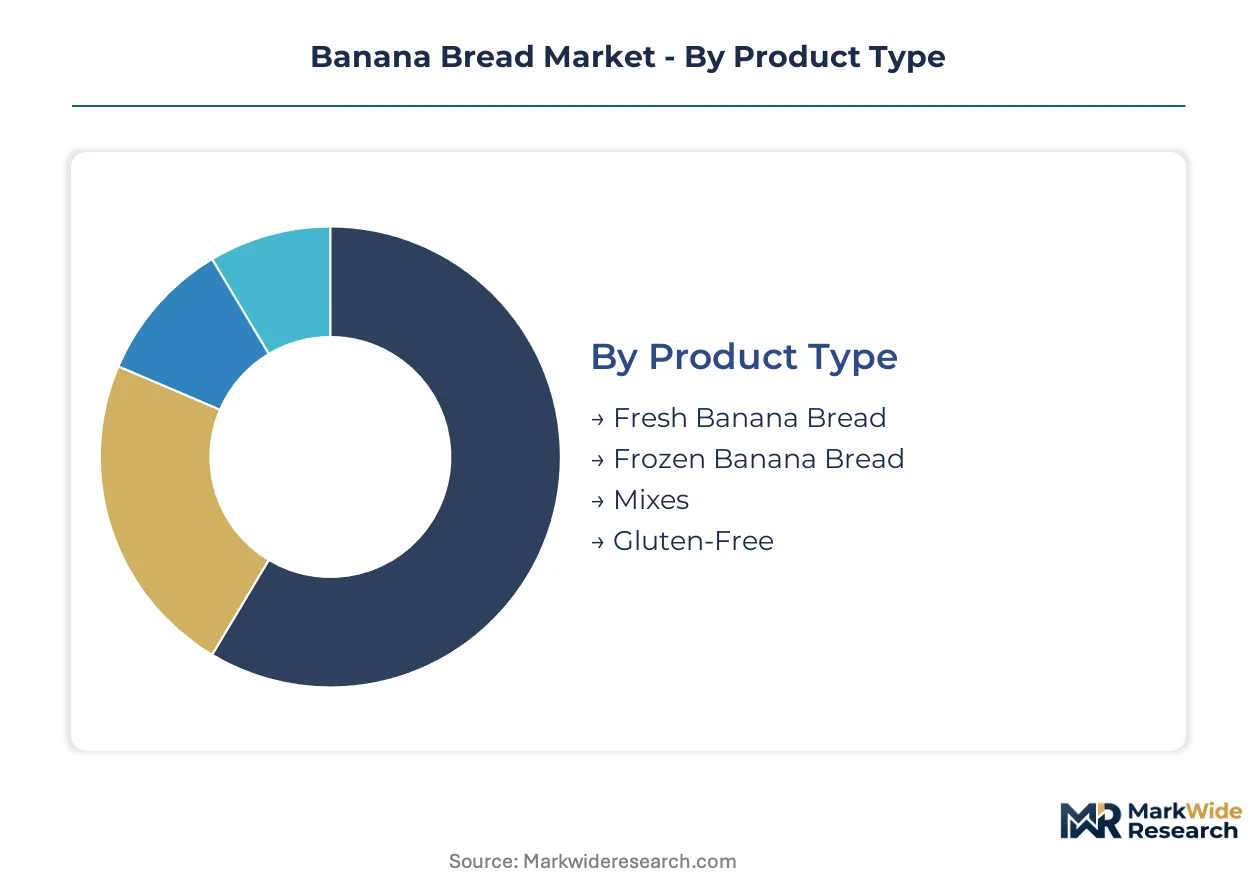
Banana bread segmentation reveals how formulation, format, and channel choices fragment purchasing behavior across convenience-driven and occasion-based demand. Product architecture decisions directly determine margin capture and shelf-life economics for manufacturers and retailers.
Product Type:
Cost tier stratification separates fresh production from shelf-stable and at-home preparation alternatives, with each tier carrying distinct margin profiles and logistics requirements.
- Fresh Banana Bread:Moisture content of 35-45% delivers preservative-free softness through fat-source emulsification. US supermarket bakeries anchor volume here, with private-label lines expanding to capture impulse-driven breakfast occasions. FDA added-sugar disclosure mandates are forcing reformulation of legacy recipes in this tier.
- Mixes:Dehydrated ingredient blends enable at-home preparation with controlled portion economics. King Arthur Baking Company anchors premium positioning through recipe ecosystems that normalize alternative flours. Online retail channels accelerate fastest for this segment, bypassing traditional bakery distribution constraints.
- Frozen Banana Bread:Blast-frozen loaves extend shelf-life to 6-12 months through cold-chain integrity. Foodservice procurement increasingly favors this format for seasonal flavor-rotation contracts.
- Gluten-Free:Cassava and banana-flour blends displace wheat formulations for specialty diet requirements. Southeast Asian milling infrastructure upgrades are narrowing supply bottlenecks for this expanding tier.
Fresh banana bread holds installed capacity. Gluten-free is rotating up the share rankings.
Distribution Channel:
Application context determines channel selection, with grab-and-go occasions concentrating in physical retail while planned purchases migrate online.
- Supermarkets:In-store bakeries and deli counters generate impulse purchases through sensory cues and proximity to checkout. Refrigerated distribution networks span Latin America and select US corridors, with private-label expansion capturing margin from branded alternatives.
- Online Retail:Direct-to-consumer mix sales eliminate intermediary markups and enable subscription-based replenishment. This channel climbs the fastest as home bakers seek ingredient transparency and recipe integration.
- Bakeries:Artisan producers command per-slice premiums through seasonal rotations and localized flavor profiles. Urban corridors concentrate demand here, with breakfast programs and café channels driving volume.
- Specialty Stores:Curated assortments target health-focused retail sets with organic and Non-GMO Project verified offerings. USDA certification creates tiered access thresholds that filter brand participation.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
Consumer Type:
Customer type segmentation maps purchasing motivation to product attributes, from nutritional vigilance to experiential discovery.
- Health-Conscious Consumers:Clean-label scrutiny drives demand for reduced-sugar recipes and alternative flour formulations. This segment concentrates in US coastal metropolitan areas where FDA nutrition panels influence purchase decisions.
- Families:Bulk-format purchasing and value-oriented private-label selection characterize household penetration. Breakfast convenience culture sustains repeat purchase frequency in suburban corridors.
- Students:Price-sensitive demand gravitates toward individually wrapped mini-loaf formats engineered for vending and grab-and-go retail. Asian convenience channels show particular concentration here.
- Foodies:Experiential purchasers seek limited-edition flavors and premium ingredient provenance. Recipe ecosystems and social media discovery drive engagement with specialty brands.
Families hold installed capacity. Health-conscious consumers are rotating up the share rankings.
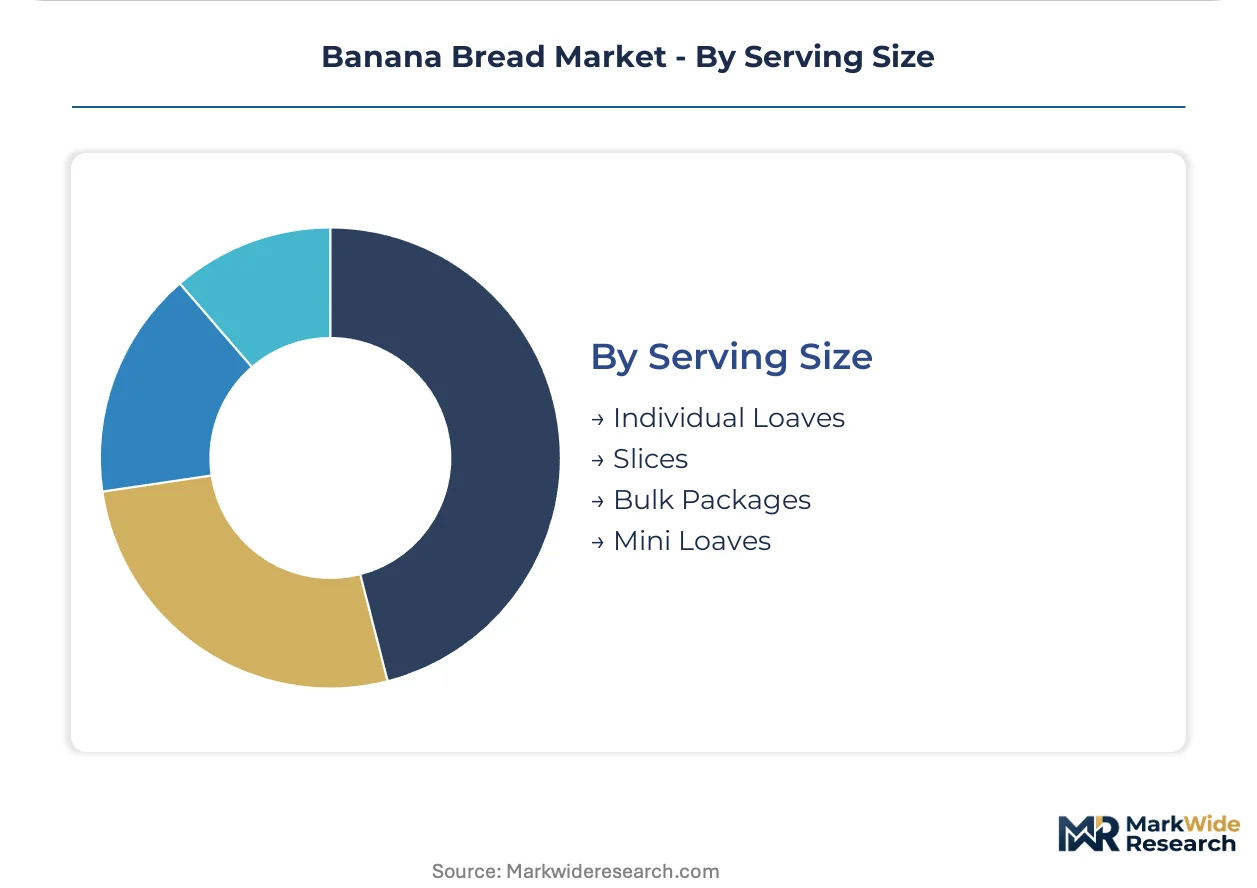
Serving Size:
Volume economics and occasion matching determine format selection, from single-serve impulse to household-scale preparation.
- Slices:Individually portioned sales dominate foodservice breakfast programs and café channels. Impulse-driven per-unit profitability exceeds whole-loaf alternatives through premium pricing acceptance.
- Mini Loaves:4-6 ounce formats unlock vending deployment and convenience-store placement. Yamazaki Baking engineers these specifications for Asian grab-and-go retail density.
- Individual Loaves:Standard 1-pound formats balance portion adequacy with shelf-life management. Retail bakery operations optimize production workflows around this specification.
- Bulk Packages:Multi-loaf configurations serve institutional procurement and family-scale consumption. Cost-per-ounce efficiency drives adoption in club-store and foodservice channels.
Individual loaves hold installed capacity. Slices are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banana bread production clusters where ripe banana supply chains intersect with refrigerated distribution infrastructure and breakfast convenience culture. Southeast Asian milling upgrades are narrowing supply gaps for gluten-free flour inputs.
United States
FDA added-sugar disclosure mandates and breakfast convenience culture drive formulation reformulation and private-label expansion in supermarket bakeries. The agency's serving-size definitions compress allowable sweetness levels in commercial recipes. California and Texas concentrate demand through urban grab-and-go corridors and in-store deli penetration.
Japan
Individually wrapped mini-loaf formats engineered for vending density sustain channel-specific demand in convenience retail. METI standards for food labeling influence portion-size specifications and front-of-package claim structures. Tokyo-Osaka corridor anchors production scale for Asian convenience channel supply.
Germany
Clean-label scrutiny and organic certification thresholds shape premium positioning in health-focused retail sets. EU Green Deal sustainability requirements and EFSA nutrition claims regulation influence ingredient sourcing transparency. Bavaria and North Rhine-Westphalia cluster artisan bakery capacity and refrigerated distribution nodes.
Brazil
Tropical banana supply proximity reduces input cost volatility for processors with integrated sourcing. ANVISA food labeling regulations govern nutritional disclosure and allergen declaration requirements. São Paulo state concentrates industrial bakery capacity serving Latin American retail corridors.
Thailand
Regional milling infrastructure upgrades for banana flour drying and processing expand gluten-free ingredient supply capacity. The country's national food and drug administration oversees food safety standards for export-oriented production. Bangkok metropolitan area anchors processing scale for Southeast Asian gluten-free formulation supply.
Banana Bread Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in flour milling and emulsification technology. The vendor base spans multinational bakery conglomerates with refrigerated distribution networks, regional artisan producers with localized flavor profiles, and specialty mix brands with direct-to-consumer recipe ecosystems. Three archetypes dominate: scale-driven mass producers, premium-tier clean-label specialists, and convenience-format engineers. Competitive moves concentrate on portfolio diversification into gluten-free variants and geographic expansion through cold-chain partnerships.
Within the scale-driven tier, Grupo Bimbo and Flowers Foods occupy positions anchored by refrigerated distribution density across multiple continents. King Arthur Baking Company exemplifies the premium-mix archetype through recipe ecosystem integration. Yamazaki Baking represents convenience-format engineering specialization for Asian vending and grab-and-go channels.
| Leading Market Players |
|---|
| King Arthur Baking Company |
| Aryzta |
| Grupo Bimbo |
| Papa Joe's Bakehouse |
| Yamazaki Baking |
| General Mills |
| Simple Mills |
| Banana Bread Company |
| Flowers Foods |
| Others |
Cost & Logistics Intelligence
Panama Canal freight corridors dictate refrigerated container economics for fresh banana bread distribution, compressing margins for processors without cold-chain redundancy while enabling premium pricing capture by operators with dual-routing flexibility. This logistics chokepoint concentrates pricing power among scale players with Latin American sourcing integration and US Gulf Coast distribution nodes.
Pricing Analysis
FDA added-sugar disclosure mandates dictate the pricing tier structure across US retail channels, separating clean-label certified organic offerings from conventional formulations through USDA verification thresholds. Price differentiation rests on Non-GMO Project verification and refrigerated distribution density as primary drivers. Pricing pressure intensifies in the standard tier as private-label supermarket bakeries compress branded alternatives through direct sourcing. Families exhibit highest price sensitivity through bulk-format purchasing, while health-conscious coastal consumers absorb premium tier markups for alternative flour formulations.
Supply Chain Analysis
Tariff exposure between Southeast Asian banana flour mills and US gluten-free formulators dominates supply chain risk assessment for specialty diet segments. Raw material sourcing concentrates in Ecuador, Costa Rica, and the Philippines for ripe banana supply, with cassava flour inputs drawing from Thailand and Vietnam. Single-source vulnerability persists in Southeast Asian drying infrastructure upgrades. Distribution runs through refrigerated logistics networks spanning Latin American production zones and US urban consumption corridors, with blast-frozen formats bypassing fresh shelf-life constraints through cold-chain integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based mix replenishment and recipe ecosystem integration expand faster than unit sales of prepared loaves, repositioning banana bread as a recurring-ingredient service rather than transactional bakery purchase. This attach-layer dynamic favors direct-to-consumer operators with content and commerce integration.
For Market Incumbents: Pre-empt gluten-free format commoditization by locking exclusive banana flour supply contracts with upgraded Southeast Asian mills before capacity constraints ease. Defend refrigerated distribution density through Latin American cold-chain partnerships that replicate Grupo Bimbo's corridor control. Certification investment in USDA organic and Non-GMO Project verification creates defensible margin pools against private-label encroachment. For New Entrants and Emerging Players: Pursue online retail channel white space through direct-to-consumer mix sales with integrated recipe content, bypassing supermarket bakery slotting fees. The most penetrable segment sits in health-conscious households seeking ingredient transparency without prepared-loaf premiums. A go-to-market angle anchored in cassava-banana flour education and home-baking tutorial content unlocks subscription economics. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational bakery conglomerates seeking to divest non-core regional brands with localized flavor portfolios but underutilized refrigerated distribution assets. Long-term viability across the analysis window hinges on format diversification into vending-compatible mini-loaves and gluten-free variant pipelines. The signal to watch is Southeast Asian milling capacity utilization rates as a leading indicator of gluten-free input cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA added-sugar compliance unlocks shelf space in health-focused retail sets. |
| Direct-to-Consumer Channel Expansion | Online retail mix sales bypass traditional bakery distribution constraints and intermediary markups. |
| Gluten-Free Flour Supply Integration | Backward control over Southeast Asian banana flour milling secures specialty diet margin premiums. |
| Vending Format Engineering | Individually wrapped mini-loaf specifications unlock Asian convenience channel density. |
| Recipe Ecosystem Development | Content-commerce integration normalizes alternative flours and drives subscription replenishment. |
Research Approach
A spread of perspectives from supermarket bakery category managers, gluten-free flour mill operators, refrigerated logistics coordinators, and foodservice procurement directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA labeling guidance documents, USDA organic certification databases, and refrigerated freight rate indices. Customs records from Ecuador and Costa Rica, alongside Southeast Asian milling capacity registries, anchored supply-side quantification. Bottom-up volume builds across product type and channel segments triangulated against top-down category expenditure estimates.
Demand-supply balance modeling across the projection horizon anchored volume forecasts, with segmentation dimensions spanning product type, distribution channel, consumer motivation, and serving size format. CAGRs derived from trend extrapolation of historical penetration rates adjusted for regulatory inflection points and channel shift dynamics. Input assumptions incorporated FDA serving-size definition revisions, Southeast Asian milling infrastructure buildout timelines, and cold-chain capacity expansion in Latin American export corridors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer mix specialists or Southeast Asian flour mill consolidators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Biscuit Mixes Market
Bakery Products
Flatbread Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Pastry Margarine Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Baked Foods Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Sourdough Market
Bakery Products
Wedding Cakes Market
Bakery Products
Bread Improver Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Pancakes Market
Bakery Products
Lentil Bread Market
Bakery Products
Dough Conveyor Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market