
 Freeze Dried Bananas Market | 2026-2036
Freeze Dried Bananas Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Bananas Market Insights
Premium-grade whole freeze dried banana specifications is reorganizing competitive dynamics across the supply base. Oregon Freeze Dry leverages its heritage in lyophilization technology to sustain leadership in bulk ingredient supply for food manufacturers. Van Drunen Farms anchors North American sourcing through vertically controlled fruit procurement networks. European Freeze Dry competes on certified organic and allergen-free production lines that command shelf space in continental retail.
Freeze dried bananas are fresh bananas stripped of moisture through sublimation at temperatures below -40°C, preserving cellular structure, natural sugars, and potassium content for shelf-stable applications in cereals, infant nutrition, and smoothie formulations. The powder segment leads ingredient-grade shipments due to its solubility and dosing precision in commercial baking operations, while slices dominate consumer snack channels where texture drives repeat purchase. Online stores represent the fastest-growing distribution channel as direct-to-consumer brands bypass traditional wholesale markups.
FDA food safety standards and USDA organic certification govern product claims and import eligibility for freeze dried fruit entering the United States, while EFSA nutrition labeling rules and EU Organic Regulation shape European market access and consumer transparency expectations. The EU Green Deal packaging directives are pressing suppliers toward recyclable pouch formats. Stakeholders must monitor evolving low-moisture food safety protocols and channel-specific certification requirements to secure positioning in premium ingredient procurement programs.
Market Dynamics
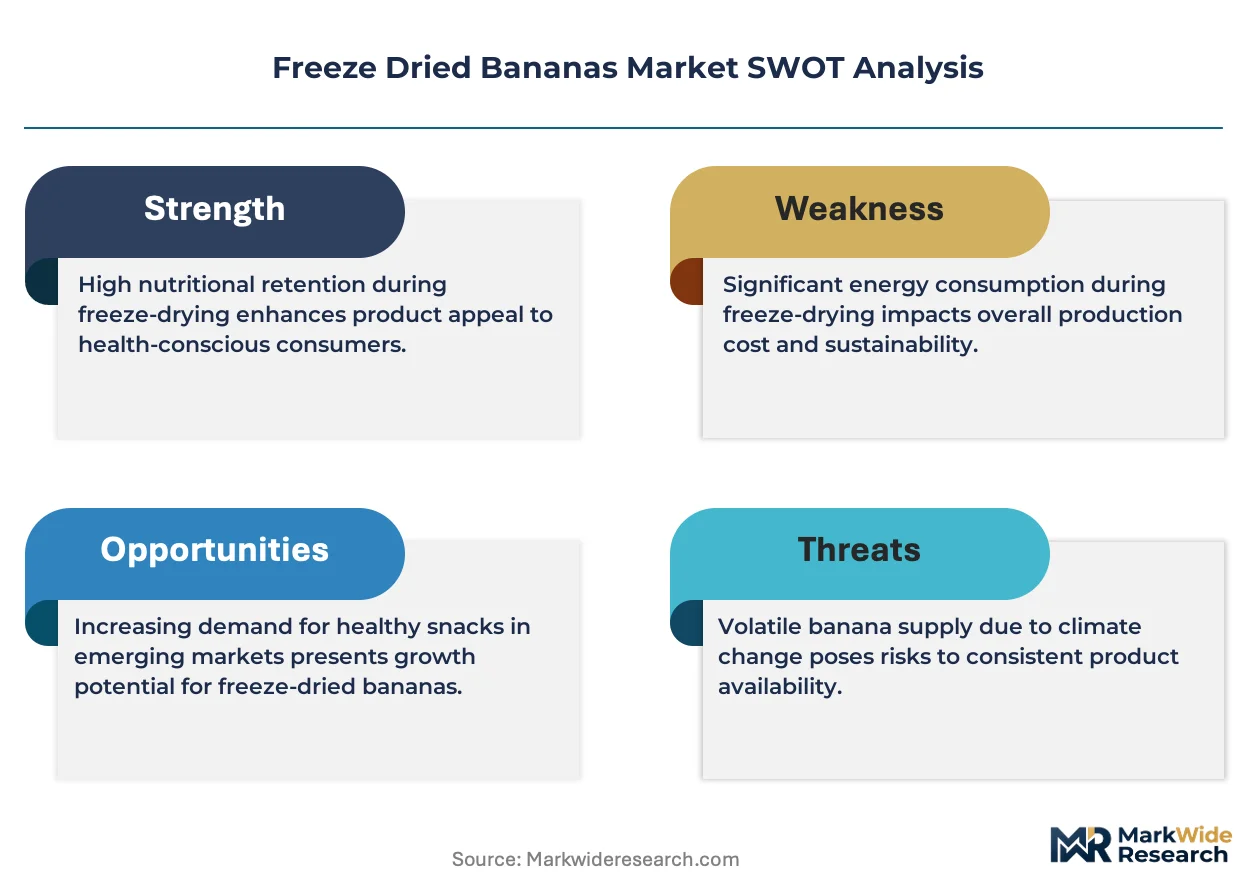
Clean-label certification requirements and low-moisture processing technology upgrades are compressing margins for commodity-grade suppliers while rewarding vertically integrated producers with organic and allergen-free credentials. The structural force reshaping competitive positioning centers on shelf-stable fruit procurement programs tightening their quality benchmarks.
Growth Catalysts
- USDA Organic certification:Retailers in the United States are mandating certified organic freeze dried fruit for private-label lines, pulling capacity toward controlled-environment agriculture partnerships.
- Infant nutrition formulation:Powder-grade freeze dried banana demand is accelerating as baby food manufacturers seek clean-label potassium sources with precise dosing control.
- Germany:German retailers are expanding functional snack aisles, creating dedicated shelf space for whole and sliced formats targeting health-conscious commuter segments.
Market Restraints
- Energy-intensive sublimation:Lyophilization requires sustained temperatures below -40°C, tying operating costs to volatile electricity pricing in European manufacturing zones.
- Raw fruit concentration:Cavendish banana sourcing clusters in Ecuador and Costa Rica, exposing processors to port congestion and climate-induced harvest volatility.
- Moisture specification limits:FDA low-moisture food safety protocols impose strict water activity thresholds that legacy drying equipment cannot consistently achieve.
Strategic Opportunities
- Japan:Underpenetrated convenience store channels in Japanese urban centers present white space for single-serve snack pouches targeting office workers.
- EU Green Deal packaging directives:Recyclable pouch mandates are creating first-mover advantage for suppliers with compostable film partnerships and closed-loop logistics.
- Smoothie subscription services:Direct-to-consumer ingredient bundles are bypassing traditional wholesale markups, enabling margin capture previously lost to retail intermediaries.
Industry Challenges
- Lyophilization technician scarcity:Specialized equipment operation and maintenance skills are concentrated among aging workforces in legacy freeze dry facilities.
- Multi-certification timelines:Simultaneous pursuit of USDA Organic, EU Organic Regulation, and FSSC 22000 approvals extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Bananas Market |
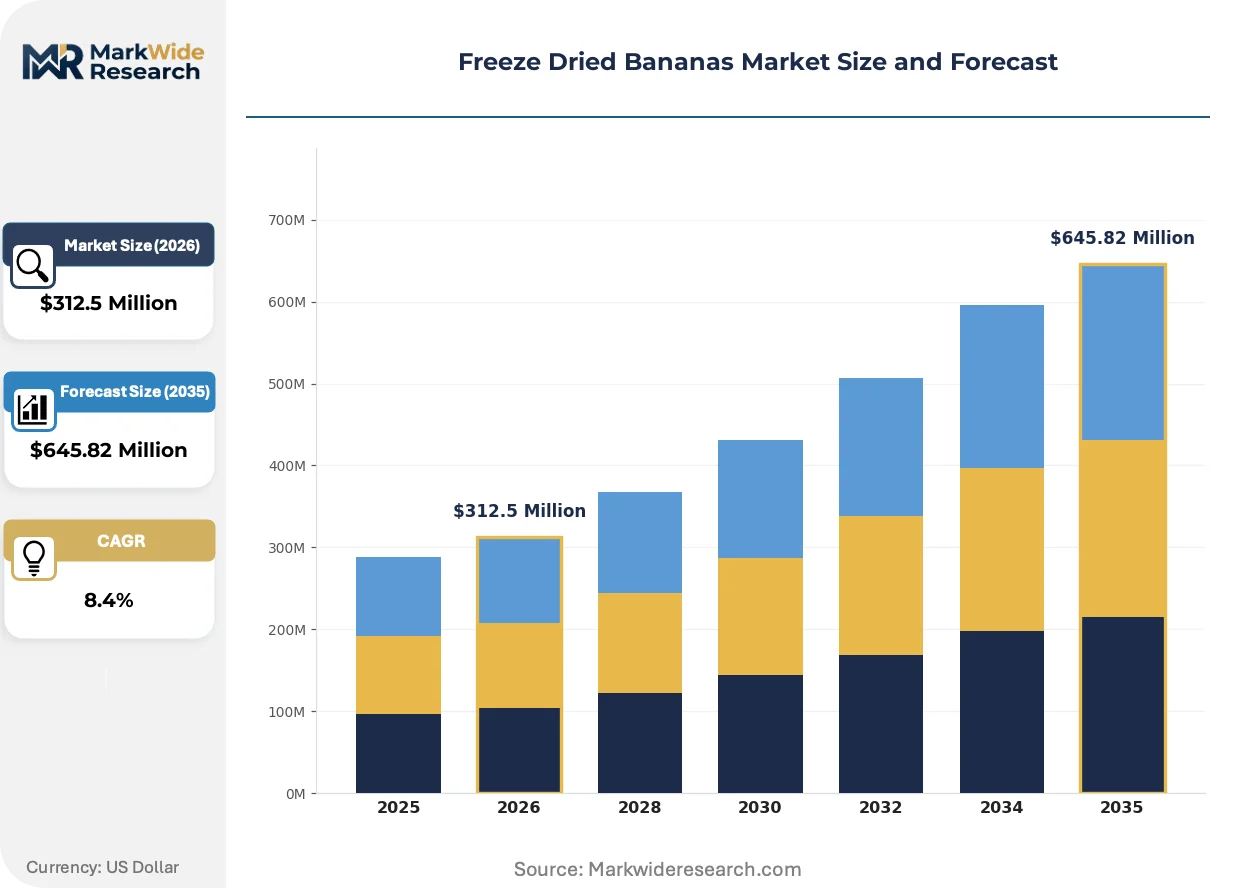
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole, Slices, Powder, Granules End Use: Food Industry, Snack Foods, Baking, Smoothies Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Direct Sales Packaging Type: Bags, Pouches, Jars, Bulk Packaging |
| Companies Covered | Natierra, Crispy Green, Mercer Foods, Paradise Fruits, Oregon Freeze Dry, European Freeze Dry, Van Drunen Farms, Chaucer Foods, DMH Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Bananas Market Trends and Innovations
Processing technology convergence and distribution channel restructuring are fragmenting traditional supply relationships. Three developments are compressing legacy business models while opening entry points for specialized operators.
Advanced microwave-assisted freeze drying is fragmenting equipment supplier hierarchies by reducing cycle times and energy consumption. Mid-scale snack brands in the United States are adopting these systems to bypass bulk ingredient brokers and establish captive powder production. The technology is compressing the minimum efficient scale for vertical entry, enabling regional players to challenge established bulk suppliers.
EFSA nutrition labeling rules and EU Organic Regulation are tightening transparency requirements for shelf-stable fruit claims. European retailers are now demanding batch-level traceability documentation that legacy paper-based systems cannot generate. Continental organic lines are responding by investing in blockchain-enabled supply chain verification to maintain retail access.
Direct-to-consumer subscription models are displacing traditional foodservice distribution for ingredient-grade powder. Commercial bakeries and smoothie manufacturers in Germany are sourcing through specialized online portals that aggregate small-batch producers. This channel rotation is most visible in North Rhine-Westphalia, where regional procurement cooperatives are forming to secure consistent supply outside conventional wholesale networks.
Freeze Dried Bananas Market Segmentation
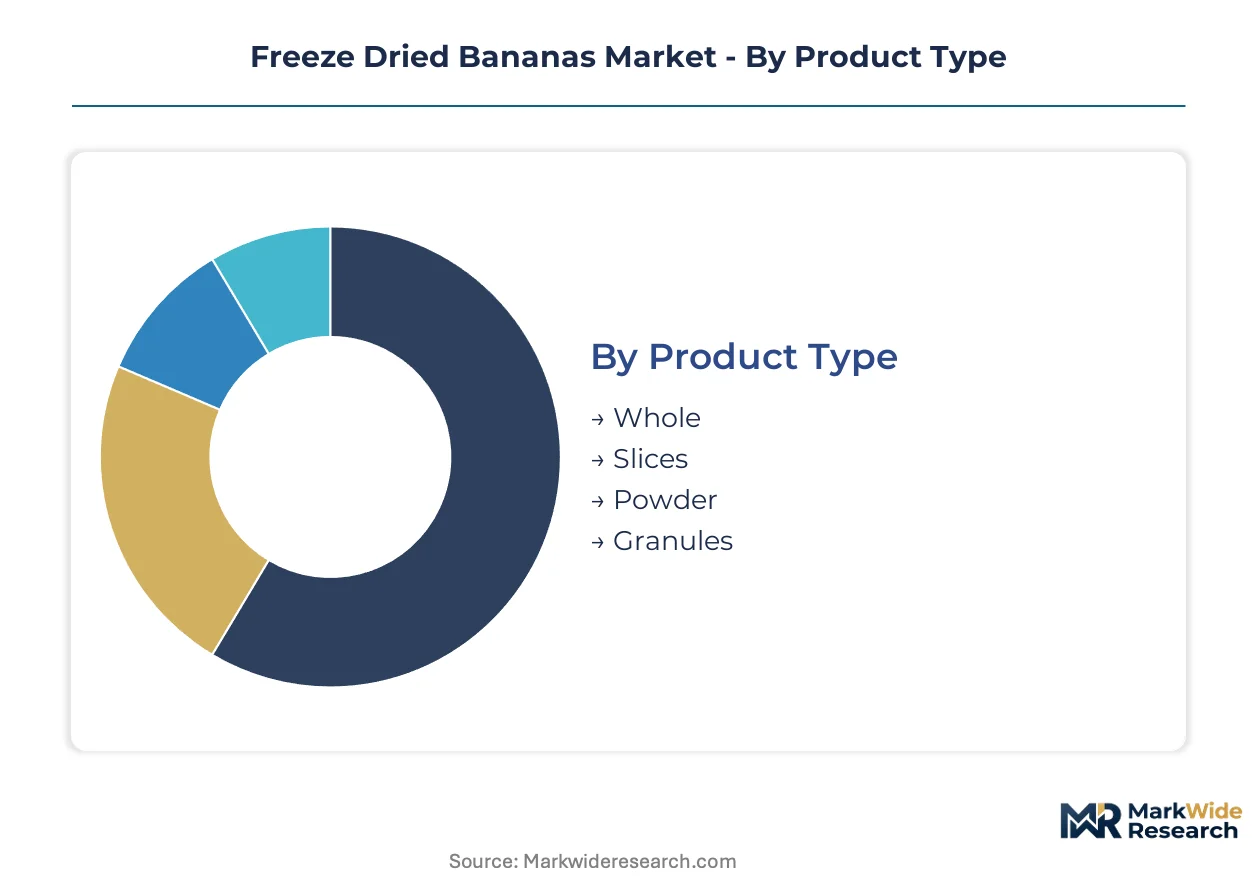
Freeze dried banana procurement patterns diverge sharply across product formats and channel structures. Manufacturers must align production specifications with end-use technical requirements while navigating distinct margin profiles in retail versus ingredient supply.
Product Type:
Powder and granule formats face intensifying substitution pressure from spray-dried banana alternatives and maltodextrin carriers in cost-sensitive baking applications. Whole and slice segments defend position through texture differentiation that alternative drying technologies cannot replicate.
- Whole:Intact cellular structure preserves visual appeal and rehydration properties for premium cereal inclusions and foodservice garnishes. Demand concentrates in German organic retail where whole format commands shelf-space premiums for clean-label positioning.
- Slices:Standardized thickness (3-5mm) delivers consistent texture in snack pouches and trail mixes. United States health food stores are expanding facings for sliced formats targeting commuter snacking occasions with portable potassium delivery.
- Powder:Soluble particle size (80-200 mesh) enables precise dosing in infant nutrition and commercial smoothie bases.
- Granules:Intermediate particle size bridges powder flowability and slice texture for energy bar binding applications.
Powder retains volume leadership in ingredient-grade procurement; slices hold the steepest expansion curve in direct-to-consumer channels.
End Use:
Application-specific moisture specifications and certification requirements fragment supplier relationships across end-use tiers. Food industry procurement demands batch-level documentation that snack channels rarely require.
- Food Industry:Bulk ingredient supply to cereal manufacturers and bakery chains demands FSSC 22000 certification and water activity below 0.3 for shelf-stable inclusions. Japanese food manufacturers are tightening specifications for banana powder in retort-pouch desserts.
- Snack Foods:Consumer-ready positioning emphasizes texture retention and single-serve convenience. United States direct-to-consumer brands are bypassing wholesale markups through subscription models for whole and sliced formats.
- Baking:Powder-grade solubility requirements favor fine particle distribution for uniform moisture absorption in commercial dough systems.
- Smoothies:Rapid-dissolve specifications prioritize powder and fine granule formats for blender-free reconstitution.
Food industry procurement dominates volume throughput; snack foods are climbing the fastest as channel restructuring captures retail margin.
Distribution Channel:
Channel selection determines certification burden and working capital intensity. Direct sales relationships demand longest payment terms but lock in volume commitments.
- Online Stores:Direct-to-consumer fulfillment enables margin capture previously lost to retail intermediaries. German specialized portals are aggregating small-batch producers for commercial bakery procurement outside conventional wholesale networks.
- Supermarkets:Private-label penetration requires USDA Organic certification and quarterly promotional funding commitments.
- Health Food Stores:Independent retail in United States and Japan demands minimum order quantities below pallet scale.
- Direct Sales:Food manufacturer contracts specify annual volume commitments with price adjustment clauses tied to Ecuadorian fresh fruit futures.
Supermarkets maintain volume leadership in whole and slice formats; online stores are gaining share fastest through subscription model expansion.
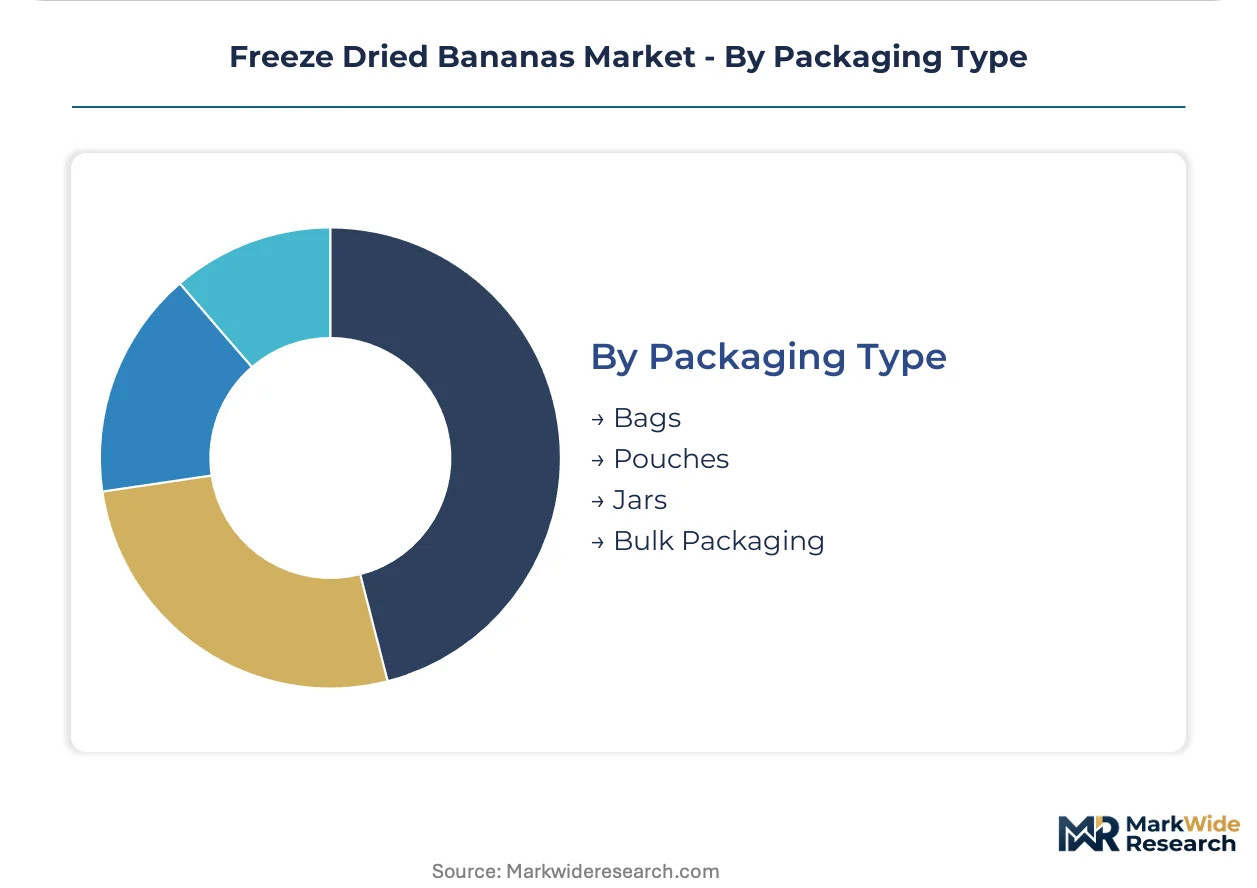
Packaging Type:
EU Green Deal packaging directives are forcing format transitions that alter cost structures and shelf-life performance. Recyclable mandates favor material innovations with unproven moisture barrier properties.
- Pouches:Stand-up formats with resealable zippers dominate snack channel placement. Compostable film partnerships in European supply chains are creating first-mover advantage under EU packaging directives.
- Bags:Multi-layer laminates with aluminum cores retain longest shelf stability for bulk ingredient shipments to food manufacturers.
- Jars:Rigid packaging commands premium positioning in gift and specialty retail segments.
- Bulk Packaging:Fiber drums with nitrogen flushing minimize oxidation for industrial-scale powder procurement.
Bags retain volume leadership in ingredient-grade supply; pouches are expanding most quickly as retail channels convert to resealable convenience formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of freeze dried banana products tilt toward import-dependent markets with limited domestic lyophilization capacity. The United States, Germany, and Japan absorb the bulk of internationally traded volume while sourcing raw Cavendish feedstock from Ecuador and Costa Rica.
United States
Private-label expansion at major retailers and infant nutrition formulation upgrades are pulling powder-grade shipments toward controlled-environment agriculture partnerships. FDA food safety standards and USDA organic certification govern import eligibility and product claims. Oregon anchors West Coast processing with heritage lyophilization facilities serving bulk ingredient procurement programs.
Germany
Functional snack aisle expansion and commuter-oriented single-serve positioning are accelerating whole and sliced format penetration. EFSA nutrition labeling rules and EU Organic Regulation shape transparency expectations and retail access conditions. North Rhine-Westphalia hosts procurement cooperatives aggregating small-batch producers outside conventional wholesale networks.
Japan
Underpenetrated convenience store channels and office worker snacking occasions present white space for portable potassium delivery formats. METI standards and national food safety protocols regulate low-moisture fruit imports. Tokyo and Osaka metropolitan clusters concentrate demand for retort-pouch dessert inclusions and premium cereal applications.
United Kingdom
Clean-label positioning in health food retail and subscription-model direct-to-consumer brands are displacing traditional wholesale markups. FSA allergen labeling requirements and post-Brexit import certification complexity add compliance overhead. London and Southeast England dominate channel restructuring for smoothie ingredient bundles and online portal aggregation.
India
Emerging demand from commercial baking and infant food manufacturers is testing import substitution feasibility for powder-grade supply. FSSAI food safety standards and BIS quality certifications govern domestic production and import eligibility. Maharashtra and Gujarat industrial corridors are piloting small-scale lyophilization units for regional fruit processing.
Freeze Dried Bananas Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base separates into three discernible layers: heritage bulk suppliers with captive lyophilization infrastructure, mid-scale regional processors pursuing organic credentials, and direct-to-consumer brands bypassing wholesale intermediaries. Strategic moves center on backward integration into Ecuadorian fresh fruit sourcing and compostable packaging partnerships under EU Green Deal directives.
Within the heritage bulk supplier tier, Oregon Freeze Dry and European Freeze Dry exemplify divergent geographic anchoring strategies. Van Drunen Farms occupies a position bridging North American sourcing networks and vertically controlled procurement. These three entities represent distinct archetypes: Pacific Northwest technology heritage, continental European certification specialization, and Midwestern agricultural supply chain integration.
| Leading Market Players |
|---|
| Natierra |
| Crispy Green |
| Mercer Foods |
| Paradise Fruits |
| Oregon Freeze Dry |
| European Freeze Dry |
| Van Drunen Farms |
| Chaucer Foods |
| DMH Ingredients |
| Others |
Pricing and Supply Chain Analysis
USDA Organic certification gates both supply qualification and price differentiation simultaneously, separating certified producers from commodity-grade competitors while retailers mandate organic credentials for private-label placement. Industrial OEM buyers anchor contract-based long-term offtake structures with annual volume commitments and price adjustment clauses tied to Ecuadorian fresh fruit futures. Pricing stratifies across premium organic, standard conventional, and economy-grade tiers based on certification level and particle size specification. Cost compression in commodity-grade supply is intensifying because spray-dried alternatives erode powder-grade margins in cost-sensitive baking applications. Snack-channel buyers exhibit highest price sensitivity, while infant nutrition manufacturers prioritize dosing precision over unit cost.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with annual volume commitments and price adjustment clauses tied to Ecuadorian fresh fruit futures. Pricing stratifies across premium organic, standard conventional, and economy-grade tiers based on certification level and particle size specification. Cost compression in commodity-grade supply is intensifying because spray-dried alternatives erode powder-grade margins in cost-sensitive baking applications. Snack-channel buyers exhibit highest price sensitivity, while infant nutrition manufacturers prioritize dosing precision over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate raw Cavendish procurement as processors buffer against Ecuadorian and Costa Rican harvest volatility and port congestion. Lyophilization equipment and nitrogen-flushed bulk packaging draw from specialized vendors in Germany, Japan, and the United States. Single-source vulnerability concentrates in Ecuadorian fresh fruit supply, where climate-induced harvest disruption propagates through processor pipelines. Distribution runs through direct sales relationships with food manufacturers and specialized online portals aggregating small-batch producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German retailers expand functional snack aisles and United States direct-to-consumer brands bypass wholesale intermediaries, consolidating procurement volume among fewer channel controllers.
For Market Incumbents: Consolidate backward integration into Ecuadorian fresh fruit sourcing partnerships to secure feedstock against climate volatility, while expanding certified organic production lines to defend against mid-scale regional processors pursuing clean-label credentials. Channel control through captive direct-to-consumer subscription platforms represents a critical lever for margin retention as retail intermediaries lose relevance. For New Entrants and Emerging Players: Anchor in Japanese convenience store channels for single-serve snack pouches, the most penetrable white space given underdeveloped office-worker snacking positioning. Compostable film partnerships for EU Green Deal compliance offer a differentiated go-to-market angle for European market entry, bypassing legacy suppliers with unproven sustainable packaging capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microwave-assisted freeze drying equipment, enabling regional players to challenge heritage bulk suppliers with smaller-scale vertical entry. Acquisition targets should prioritize mid-scale processors with organic credentials and captive lyophilization infrastructure, not commodity-grade toll processors. Watch for inflection when advanced drying technology adoption crosses threshold penetration in North American snack manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fresh Fruit Sourcing | Secures Ecuadorian and Costa Rican Cavendish supply against climate-induced harvest volatility. |
| Compostable Packaging Partnership | Creates first-mover advantage under EU Green Deal directives for recyclable pouch mandates. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale markups and captures retail margin previously lost to intermediaries. |
| USDA Organic Certification Investment | Unlocks private-label placement at United States retailers mandating certified organic lines. |
| Microwave-Assisted Freeze Drying Adoption | Reduces cycle times and energy consumption, compressing minimum efficient scale for regional entry. |
Research Methodology
The analysis maps powder-grade ingredient supply, sliced snack formats, whole premium positioning, and granule intermediate applications, each validated through procurement managers at cereal manufacturers, category buyers at German retailers, quality directors at infant nutrition companies, and operations leads at lyophilization facilities. Secondary validation draws from FDA food safety filings, USDA organic certification databases, EFSA nutrition labeling guidance, EU Organic Regulation documentation, and customs trade records for Ecuadorian and Costa Rican fresh fruit exports. Bottom-up segment sizing and top-down macro constraint checks ensure triangulated consistency.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, end-use application, distribution channel structure, packaging type, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating infant nutrition formulation upgrades, clean-label certification expansion, and channel restructuring toward direct-to-consumer models. Industry-specific inputs include lyophilization capacity utilization rates and organic certification penetration by supply base tier.
Decision-makers should treat outputs as directional under assumptions of sustained clean-label demand and stable Ecuadorian fresh fruit export flows; material deviation would warrant model refresh. Specific risk factors include energy price volatility affecting sublimation economics, moisture specification enforcement tightening under FDA protocols, and multi-certification timeline extensions delaying product launches. Revision becomes warranted when microwave-assisted drying technology adoption crosses threshold penetration or when EU packaging directive enforcement accelerates format transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Dehydrated Beets Market