
 Embedded Die Packaging Market | 2026-2036
Embedded Die Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Die Packaging Market Intelligence
The supply chain for outsourced assembly and test (OSAT) services is fragmenting as integrated device manufacturers bring more packaging processes in-house. Amkor Technology leverages its scale in advanced packaging to serve a broad base of fabless clients. Taiwan Semiconductor Manufacturing Company extends its foundry leadership by offering integrated fan-out and 3D packaging solutions. Infineon Technologies specializes in solutions for automotive and power applications, controlling its packaging technology for reliability.
Embedded die packaging is a technique where one or more semiconductor dies are placed within the layers of a printed circuit board or substrate. This approach eliminates wire bonds and solder bumps, achieving a significant reduction in package height and a shorter interconnect path for improved electrical performance. System in Package (SiP) configurations represent a dominant package type, integrating multiple functional components. Within technology segments, fan-out wafer level packaging is seeing rapid uptake, especially for mobile and consumer electronics applications.
The EU's RoHS directive dictates material composition, banning hazardous substances like lead and mercury in electronic components. In parallel, US export control regulations on advanced semiconductor technologies and China's GB standards for electronics influence technology access and supply chain strategies. Stakeholders must navigate this divergent regulatory landscape while managing thermal dissipation and manufacturing yield for increasingly complex modules.
Market Dynamics
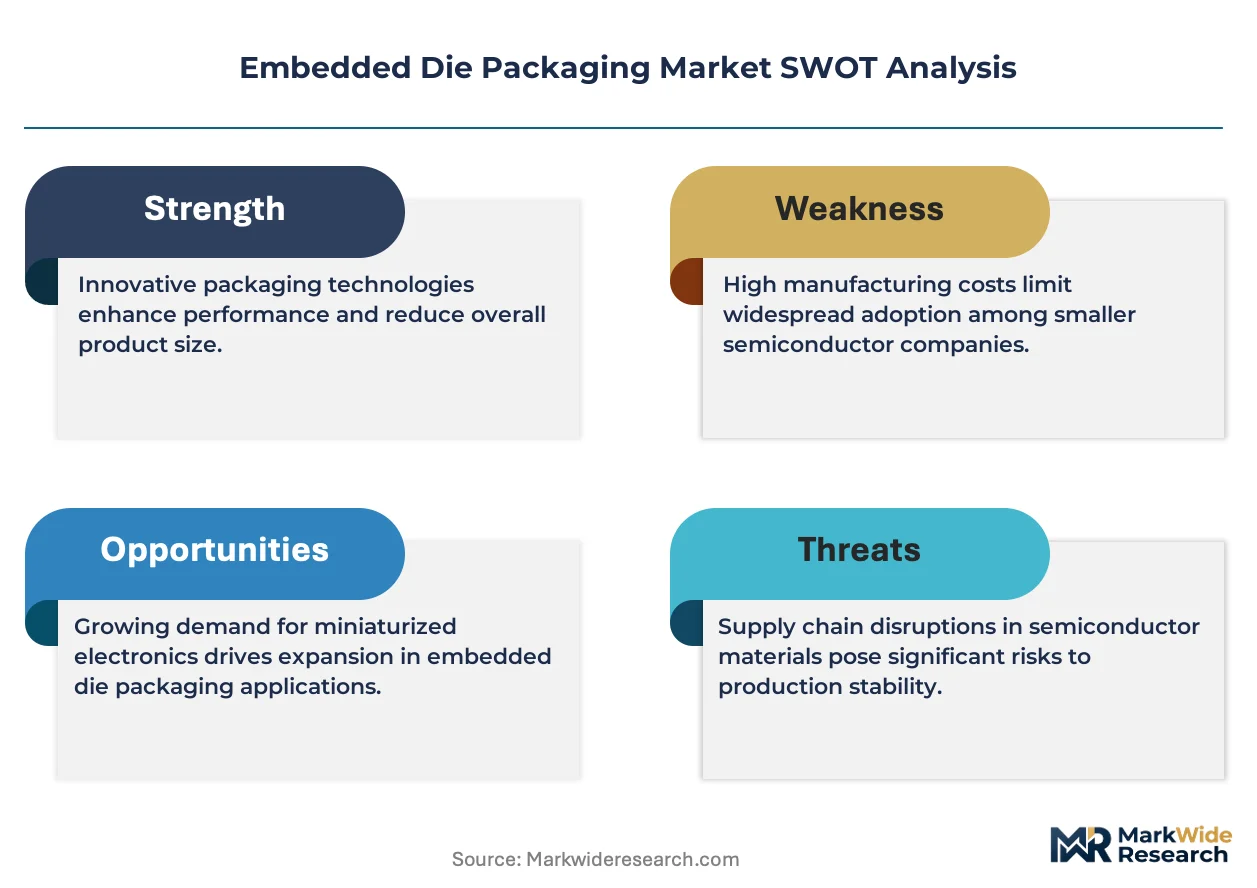
The central force shaping the embedded die packaging market is the relentless pursuit of miniaturization and functional integration, driven by performance demands in mobile, automotive, and high-performance computing applications, which traditional packaging technologies cannot satisfy.
Growth Catalysts
- 5G and Telecom Expansion:Demand from the telecommunication sector for smaller, more efficient components for 5G base stations and user equipment accelerates adoption.
- Panel Level Packaging:This technology enables higher throughput and lower cost per unit for large-scale production, improving manufacturing economics for high-volume applications.
- Geographic Concentration:Semiconductor manufacturing hubs in Taiwan and South Korea provide a dense ecosystem of expertise, materials, and equipment, fostering rapid innovation cycles.
Market Restraints
- High Capital Expenditure:Establishing advanced embedded die packaging lines requires significant upfront investment in specialized lithography, deposition, and handling equipment.
- Thermal Management Complexity:Increasing die density within a compact footprint creates significant thermal dissipation challenges, potentially limiting performance and reliability without advanced cooling solutions.
- Regulatory Divergence:Navigating conflicting material requirements between the EU's RoHS directive and varying standards in other regions complicates supply chain management and product design.
Strategic Opportunities
- Automotive Electronics:The expansion of ADAS, infotainment, and vehicle-to-everything (V2X) communication systems creates a significant opportunity for highly reliable, compact embedded modules.
- Medical Device Miniaturization:Wearable health monitors, diagnostic implants, and portable medical imaging devices represent an underpenetrated market requiring extreme miniaturization and biocompatible packaging.
- Technology Convergence:Combining fan-out packaging with 3D stacking techniques opens new possibilities for heterogeneous integration, merging logic, memory, and sensors in a single package.
Industry Challenges
- Manufacturing Yield Management:Achieving consistently high yields for complex multi-die modules is a persistent operational hurdle, as a single faulty die can render the entire package useless.
- Cross-Disciplinary Talent Scarcity:A shortage of engineers with combined expertise in semiconductor physics, substrate design, and thermal mechanics constrains product development and process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Die Packaging Market |
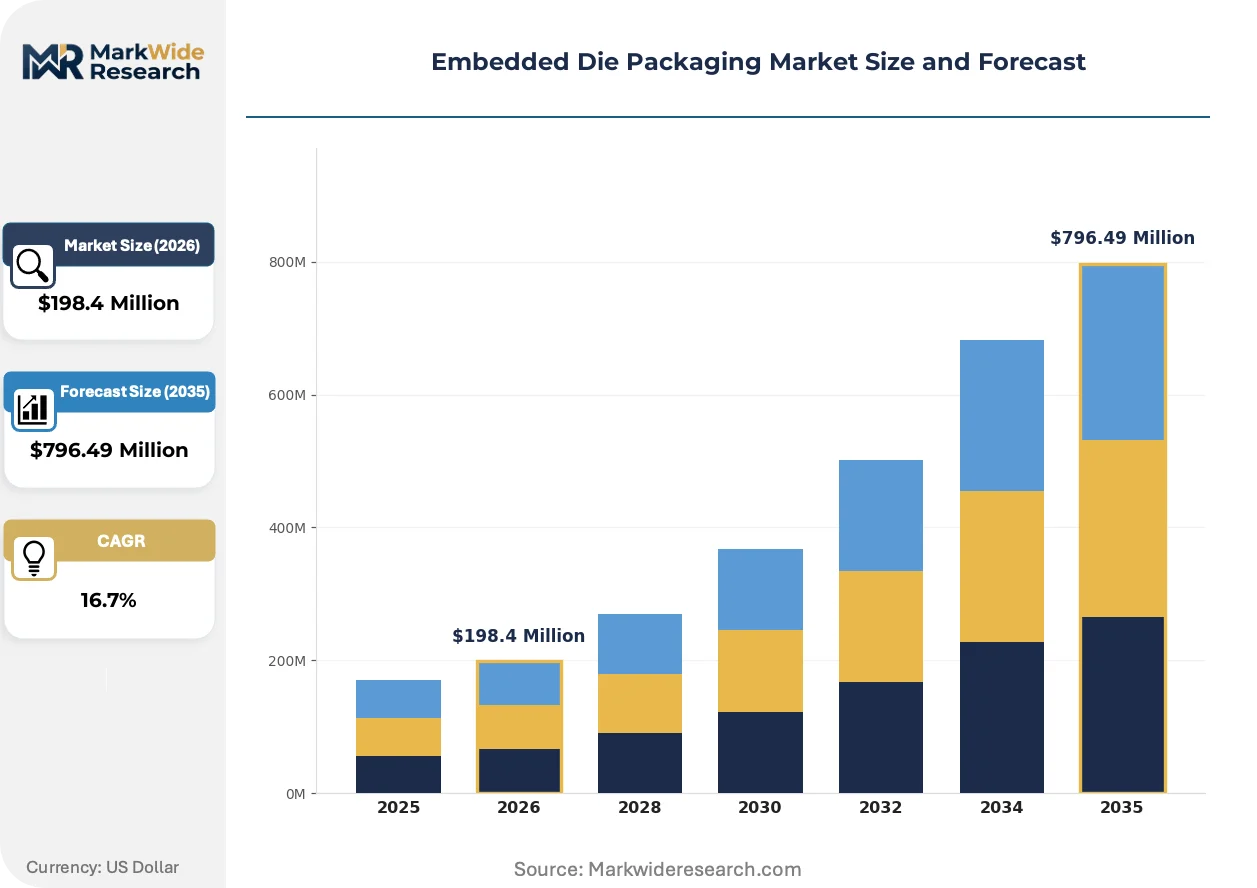
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $796.49 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Package Type: System in Package,Wafer Level Package,Flip Chip,3D Packaging,Panel Level Packaging Technology: Through Silicon Via,Fan Out,Chip on Board,Embedded Passives,Interposer Application: Consumer Electronics,Telecommunication,Automated Industrial Equipment,Military & Aerospace,Data Storage Devices End User: OEMs,Tier-1 Suppliers,Contract Manufacturers,EMS Providers,Assembly & Test Houses |
| Companies Covered | Fujikura, Microsemi, ASE Technology, TDK Corporation, Schweizer Electronic, Amkor Technology, AT&S Austria Technologie & Systemtechnik, Taiwan Semiconductor Manufacturing Company, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Die Packaging Market Strategic Shifts & Innovations
Integration is the dominant theme, as the technology moves beyond packaging single components toward creating entire electronic subsystems within a single, miniaturized module. This shift fundamentally alters design, manufacturing, and supply chain collaboration across the electronics industry.
System-in-Package Integration
Fan-out wafer level packaging (FOWLP) provides a platform for higher I/O density and improved electrical performance over conventional packaging methods. Mobile and consumer electronics manufacturers are rapidly adopting FOWLP to meet miniaturization demands. As a result, the market is migrating from discrete single-die components to complex, multi-die System-in-Package (SiP) modules that integrate diverse functionalities, compressing system-level board space.
Material and Process Compliance
The European Union's RoHS directive mandates the restriction of hazardous substances such as lead and mercury in electronic equipment. This regulation compels a shift to lead-free materials and processes, which can affect solder joint reliability and manufacturing temperatures. The automotive and industrial sectors are most impacted, investing in extensive requalification and material science research to ensure long-term component reliability.
Collaborative Co-Design Models
A significant demand-side shift sees original equipment manufacturers pursuing collaborative co-design partnerships with their semiconductor packaging providers. This model displaces the traditional transactional procurement of standard components, emphasizing system-level optimization from the project's outset. This trend is most prominent in high-performance computing and 5G infrastructure, where thermal and electrical co-simulation is critical for achieving performance targets.
Embedded Die Packaging Market Segmentation
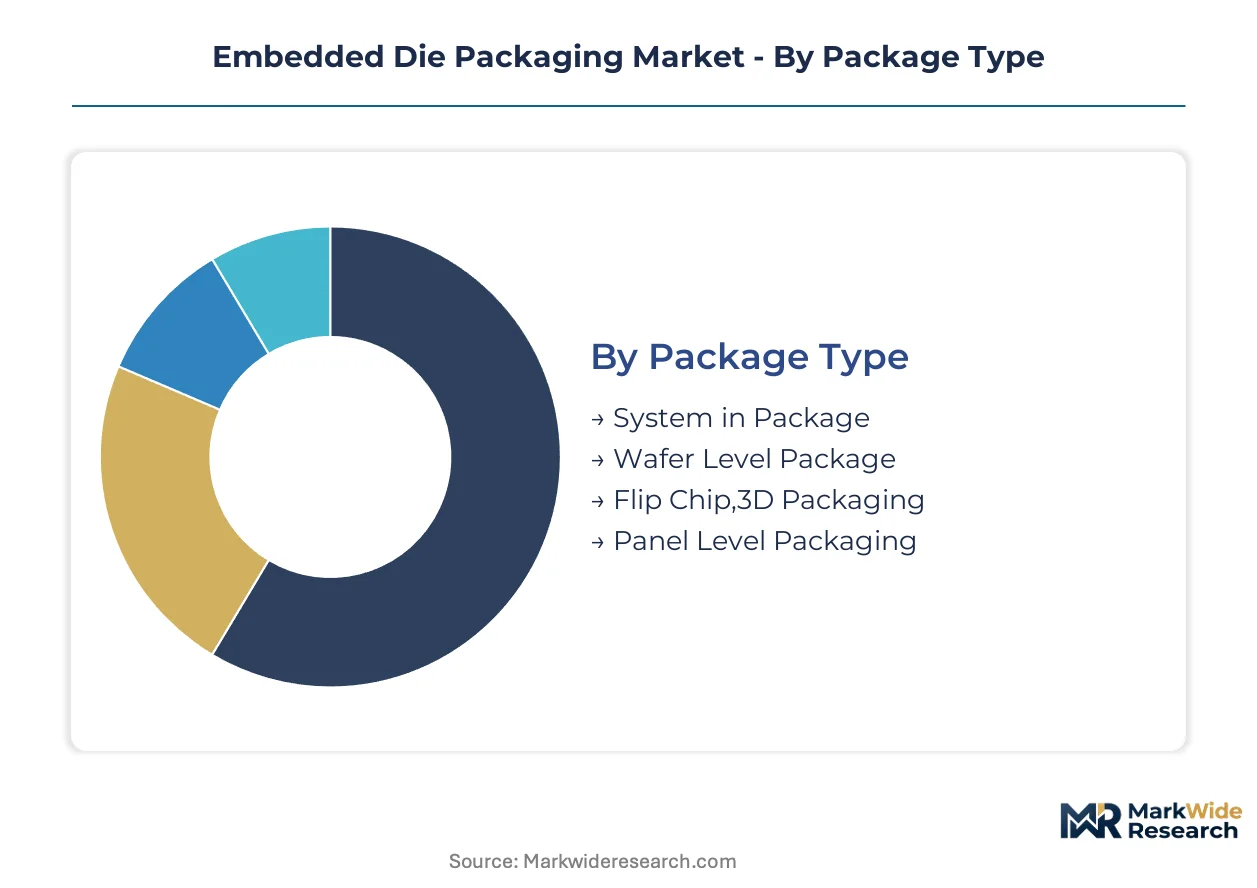
The embedded die packaging market's segmentation provides a detailed framework for understanding the diverse technical approaches and end-use applications driving its expansion. Analyzing these segments reveals critical insights into where innovation is most concentrated and which market forces dictate adoption rates.
Package Type:
The embedded die packaging market segments by package type, reflecting a spectrum from mature, established configurations to emerging, high-integration solutions.
- System in Package:This configuration integrates multiple functional components, such as processors, memory, and sensors, into a single module. Mobile and consumer electronics manufacturers in Taiwan drive demand for SiP solutions, seeking extreme miniaturization and enhanced performance within compact devices.
- Panel Level Packaging:This technology processes multiple packages on a large-area panel, significantly reducing manufacturing costs per unit. Automated industrial equipment producers and automotive electronics suppliers leverage panel level packaging for high-volume, cost-effective production in South Korea.
- Wafer Level Package:This packaging technique completes the packaging process directly on the wafer before dicing, offering a compact footprint and improved electrical performance.
- Flip Chip:This method connects dies face-down onto a substrate using solder bumps, enhancing electrical performance and I/O density for computing applications.
- 3D Packaging:This advanced approach stacks multiple dies vertically, utilizing through-silicon vias (TSVs) to achieve ultra-compact, high-performance integration for specialized computing.
System in Package handles the majority of throughput; Panel Level Packaging is the fastest mover on share.
Technology:
Technology segmentation highlights distinct approaches to achieving miniaturization and electrical efficiency within embedded die packaging.
- Fan Out:This technology expands the interconnection area beyond the chip size, allowing for more I/O connections and better thermal dissipation. Mobile phone manufacturers globally adopt fan-out wafer level packaging for its compact form factor and superior electrical characteristics.
- Through Silicon Via:TSV technology creates vertical electrical connections through the silicon wafer, enabling the stacking of multiple dies with minimal interconnect length. High-performance computing and data center applications in the US utilize TSV for dense memory and processor integration.
- Chip on Board:This method directly mounts an unpackaged semiconductor die onto a printed circuit board, reducing package size and improving thermal conductivity for LED lighting.
- Embedded Passives:This technology integrates passive components like resistors and capacitors directly into the substrate or package, reducing board space and improving signal integrity.
- Interposer:An interposer acts as an electrical interface between a microchip and a circuit board, providing fine-pitch routing and supporting heterogeneous integration for advanced modules.
Fan Out technologies dominate for high-performance mobile devices, while Through Silicon Via solutions offer advanced vertical integration for specialized applications.
Application:
Application segments delineate where embedded die packaging delivers critical performance advantages across diverse industry sectors.
- Consumer Electronics:This segment includes smartphones, wearables, and other portable devices that demand extreme miniaturization and power efficiency. Manufacturers in China increasingly integrate embedded die packaging to achieve thinner form factors and enhanced functionality for new product generations.
- Telecommunication:Embedded die packaging supports 5G infrastructure, base stations, and user equipment by providing compact, high-frequency components. European telecom equipment providers require these solutions for improved signal integrity and reduced footprint in network deployments.
- Automated Industrial Equipment:This sector utilizes embedded die packaging for robust, compact control systems and sensors in factory automation.
- Military & Aerospace:High-reliability, miniaturized components are crucial for avionics, radar systems, and defense electronics in this segment.
- Data Storage Devices:Embedded packaging enhances performance and capacity in solid-state drives (SSDs) and other memory solutions for enterprise and consumer markets.
Consumer Electronics drives the largest volume demand, with Telecommunication experiencing accelerating integration of advanced packaging solutions.
End User:
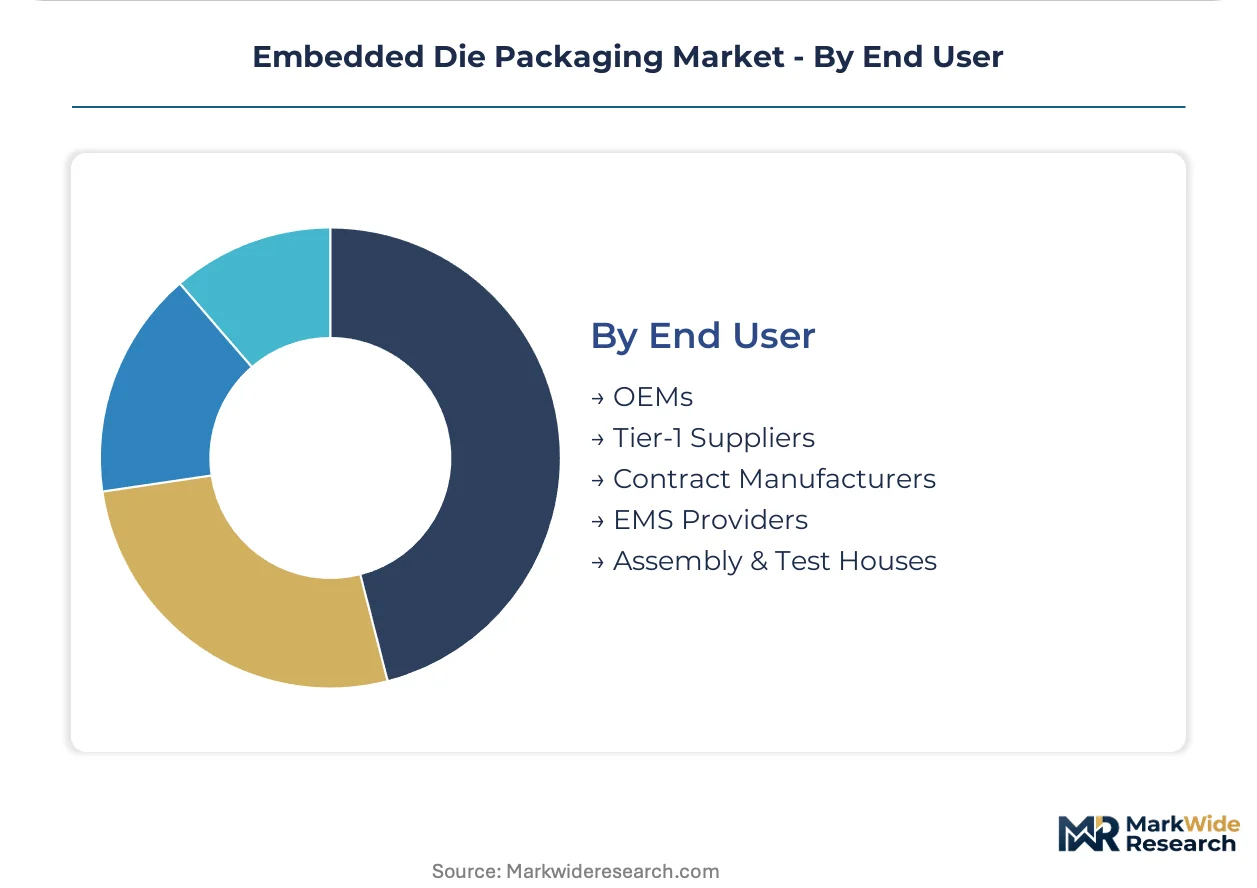
End user segmentation reflects the varied roles organizations play across the semiconductor supply chain in adopting embedded die packaging.
- OEMs:Original Equipment Manufacturers directly integrate embedded die packages into their final products, influencing design specifications. Automotive OEMs in Germany prioritize reliability and compact size for advanced driver-assistance systems.
- Contract Manufacturers:These companies provide manufacturing services for other firms, often handling the assembly and testing of complex embedded die packages. Large contract manufacturers in Mexico support diverse electronics clients seeking scalable production capabilities.
- Tier-1 Suppliers:These suppliers provide major sub-assemblies or components to OEMs, requiring advanced packaging for their integrated modules.
- EMS Providers:Electronics Manufacturing Services providers offer a broad range of design, manufacturing, and testing services for electronic components and assemblies.
- Assembly & Test Houses:Specialized firms offering outsourced assembly, packaging, and testing services for semiconductor devices.
OEMs represent the primary customer base for embedded die packaging, and Contract Manufacturers exhibit increasing strategic importance in production scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's robust semiconductor manufacturing infrastructure underpins its dominant position in advanced packaging technologies. This ecosystem supports the development and production of embedded die solutions for global electronics. The country's expertise in foundry services and advanced packaging fuels innovation across the industry.
Taiwan
Demand from mobile and consumer electronics manufacturers drives System in Package (SiP) solutions for extreme miniaturization. Taiwan's government actively supports the semiconductor industry through strategic investment programs and R&D incentives. Hsinchu Science Park remains a global hub for semiconductor research and advanced embedded die packaging innovation.
South Korea
South Korea's automated industrial equipment and automotive electronics producers leverage panel level packaging for high-volume, cost-effective production. The MFDS (Ministry of Food and Drug Safety) influences material requirements for medical device components, impacting packaging choices. Pyeongtaek and Gyeonggi Province house major advanced packaging facilities and critical R&D centers.
United States
United States' high-performance computing and data center applications demand Through Silicon Via (TSV) for dense memory and processor integration. US export control regulations on advanced semiconductor technologies shape supply chain strategies for complex modules. Silicon Valley and Austin serve as critical centers for design, advanced packaging research, and intellectual property development.
Germany
Germany's automotive OEMs prioritize reliability and compact size for advanced driver-assistance systems and infotainment. The EU's RoHS directive dictates material composition for electronic components, impacting embedded die design and manufacturing. Bavaria and Baden-Württemberg host key automotive electronics and industrial equipment manufacturers, driving specialized packaging demand.
China
China's consumer electronics manufacturers increasingly integrate embedded die packaging to achieve thinner form factors and enhanced functionality. China's GB standards for electronics influence technology access and supply chain strategies for domestic and international players. The Yangtze River Delta and Pearl River Delta regions are major production bases for consumer electronics and advanced packaging.
Embedded Die Packaging Market Key Industry Players
On the supply side, the industry is experiencing fragmentation within outsourced assembly and test (OSAT) services, alongside strategic vertical integration by integrated device manufacturers. This dynamic environment sees large OSAT providers leveraging their scale, while leading foundry services extend their capabilities into advanced packaging. Key archetypes include dedicated OSAT firms, IDMs with captive packaging facilities, and specialized technology providers. Companies actively pursue capacity expansion and strategic partnerships to navigate evolving market demands and technological shifts.
Scale-driven OSAT specialists like Amkor Technology exemplify a broad service model for fabless clients, leveraging extensive advanced packaging capabilities. Taiwan Semiconductor Manufacturing Company, a leading foundry, represents the extension of manufacturing leadership into sophisticated integrated fan-out and 3D packaging solutions. Infineon Technologies, with its focus on automotive and power applications, occupies a position as an integrated device manufacturer controlling its packaging technology for enhanced reliability. These firms collectively anchor various segments of the embedded die packaging ecosystem, from high-volume consumer electronics to mission-critical industrial applications.
| Leading Market Players |
|---|
| Fujikura |
| Microsemi |
| ASE Technology |
| TDK Corporation |
| Schweizer Electronic |
| Amkor Technology |
| AT&S Austria Technologie & Systemtechnik |
| Taiwan Semiconductor Manufacturing Company |
| Infineon Technologies |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes' cost dynamics significantly influence embedded die packaging pricing, reflecting the concentration of advanced manufacturing capabilities in Asia and shaping downstream price differentiation for global electronics brands.
Pricing Analysis
Volume-based transactional pricing structures dominate the embedded die packaging market. Price differentiation stems from the complexity of integration and the required certification level, particularly for automotive or medical applications. Pricing softness reflects intense competition among OSAT providers and integrated device manufacturers. Consumer electronics manufacturers exhibit the highest price sensitivity, while military and aerospace clients prioritize reliability over cost.
Supply Chain Analysis
US export control regulations on advanced semiconductor technologies create a structural risk within the embedded die packaging supply chain. Geographic supply concentration centers on Taiwan, South Korea, and China for manufacturing and assembly. This ecosystem draws from specialized semiconductor dies, advanced substrate materials, and high-purity chemicals. Distribution of these complex modules primarily runs through direct contracts between packaging providers and OEMs or Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded die packaging market presents a significant service-attach opportunity, with recurring revenue from design optimization and post-manufacturing testing services expanding faster than initial hardware sales.
For Market Incumbents:Insulate core market share by investing heavily in advanced R&D for next-generation 3D packaging and heterogeneous integration. This counters the threat from specialized foundries extending their packaging capabilities. Capacity addition in key hubs like Taiwan and South Korea reinforces manufacturing economies of scale. Deepening vertical integration into specialized substrate production also secures critical material supply.
For New Entrants and Emerging Players:Pursue niche applications requiring extreme miniaturization and specialized reliability, such as medical implants or specific military avionics. The most penetrable segments are those with lower volume but higher value, where established players are slower to innovate. A go-to-market angle focusing on rapid prototyping and custom design services for early-stage product development offers differentiation.
For Investors and Strategic Acquirers:Carve-out targets emerge from integrated device manufacturers seeking to divest non-core packaging operations, offering specialized capabilities. The long-term viability of this market rests on the relentless demand for smaller, more powerful electronic devices across all sectors. Acquisition targets should possess strong intellectual property in thermal management or advanced material science. The signal to watch is the increasing adoption rate of panel-level packaging beyond consumer electronics.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 3D Packaging R&D | Advances integration density for high-performance computing and AI accelerators. |
| Expand Panel Level Packaging Capacity | Reduces manufacturing costs for high-volume automotive and consumer electronics. |
| Form Collaborative Design Partnerships | Optimizes system-level performance for complex modules in 5G infrastructure. |
| Acquire Thermal Management Specialists | Addresses critical heat dissipation challenges in compact embedded die modules. |
| Secure Advanced Substrate Material Supply | Ensures access to critical components amid geopolitical supply chain pressures. |
Research Approach
Operator-level perspectives from packaging engineers, OEM procurement leads, R&D directors, and supply chain managers anchored the qualitative base of this analysis. Primary interviews were triangulated with secondary validation from patent databases, trade publications, regulatory filings, and corporate financial reports. This approach ensured a robust understanding through both bottom-up market insights and top-down industry trends.
Scenario-bracketing framing informed the quantitative model, which projected market values across the analysis window. Segmentation dimensions including package type, technology, application, end user, and regional production hubs were meticulously modeled. Compound Annual Growth Rates were derived from historical data trends, anticipated technological shifts, and projected demand from 5G rollout schedules and electric vehicle production forecasts.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or supply chain stability would shift the trajectory of embedded die packaging adoption. Forecasts reflect assumptions regarding technological maturation and sustained investment in semiconductor manufacturing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market