
 Semiconductor Solder Flux Market | 2026-2036
Semiconductor Solder Flux Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Solder Flux Market Insights
Specialty flux formulation revenue is rewriting margin distribution across the semiconductor materials stack. Indium Corporation leverages deep R&D intensity in ultra-high-purity indium-based activators to command premium positioning. Heraeus Holding GmbH anchors European supply through captive precious-metal refining and localized blending operations. Shenmao Technology Inc. competes on manufacturing scale out of Taiwan and mainland China facilities.
Semiconductor solder flux comprises chemically activated compounds—typically rosin, resin, or synthetic bases with halide or organic acid activators—designed to remove oxides from metal surfaces and promote wetting at 180–260°C during joint formation. Its primary purpose is ensuring metallurgical integrity in high-density interconnects where voiding or incomplete fusion causes field failures. No-clean flux formulations now lead product-type revenue as miniaturized packages limit post-process cleaning access; reflow soldering dominates technology adoption because surface-mount device densities render wave methods impractical for advanced semiconductor packaging. Water-soluble flux retains share in military and medical applications where ionic residue standards remain stringent.
EPA regulations in the United States restrict volatile organic compound emissions from solvent-based cleaning processes, directly elevating no-clean formulation demand. REACH registration requirements in Europe force full material disclosure across halide activator supply chains, raising compliance costs for imported formulations. China's GB standards and MIIT directives on green manufacturing push domestic flux producers toward lead-free and low-residue chemistries. Stakeholders must monitor how evolving halogen-free specifications across multiple jurisdictions reshape formulation R&D priorities and qualification timelines.
Market Dynamics
Flux formulation chemistry is pivoting around halogen-free mandates as semiconductor packaging densities eliminate post-solder cleaning access, forcing activator redesign across every major production cluster.
Growth Catalysts
- EV powertrain electronics:Electric vehicle inverter and battery management module assembly demands fluxes with thermal cycling reliability beyond traditional consumer-grade specifications.
- REACH Article 33 disclosure:European material transparency rules favor no-clean formulations that minimize downstream substance reporting burdens for OEMs.
- Flip-chip underfill compatibility:Advanced packaging architectures require flux residues that do not interfere with capillary flow of molding compounds.
Market Restraints
- Precious metal activator cost volatility:Palladium and silver salt prices swing formulation input costs unpredictably for high-reliability grades.
- Indium supply concentration:Ultra-high-purity indium refining capacity clusters in Chinese and Canadian smelters, creating single-source vulnerability for premium activator supply.
- Rosin base substitution limits:Synthetic resin alternatives fail to match natural rosin's oxide reduction kinetics in low-temperature soldering.
Strategic Opportunities
- Vietnam packaging expansion:Intel and Amkor facility investments create demand for localized flux blending and technical service presence.
- Photovoltaic ribbon interconnects:Solar cell stringing processes adopt semiconductor-grade flux specifications as module efficiency targets tighten.
- MIIT green manufacturing credits:Chinese domestic producers gain cost advantages through state subsidies for lead-free and low-residue chemistry transitions.
Industry Challenges
- Formulation chemist scarcity:Expertise in halide-free activator synthesis concentrates among retiring specialists at Japanese and German suppliers.
- Automotive qualification timelines:AEC-Q100 and AEC-Q101 testing cycles extend 18-24 months, freezing formulation iterations for EV-targeted products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Solder Flux Market |
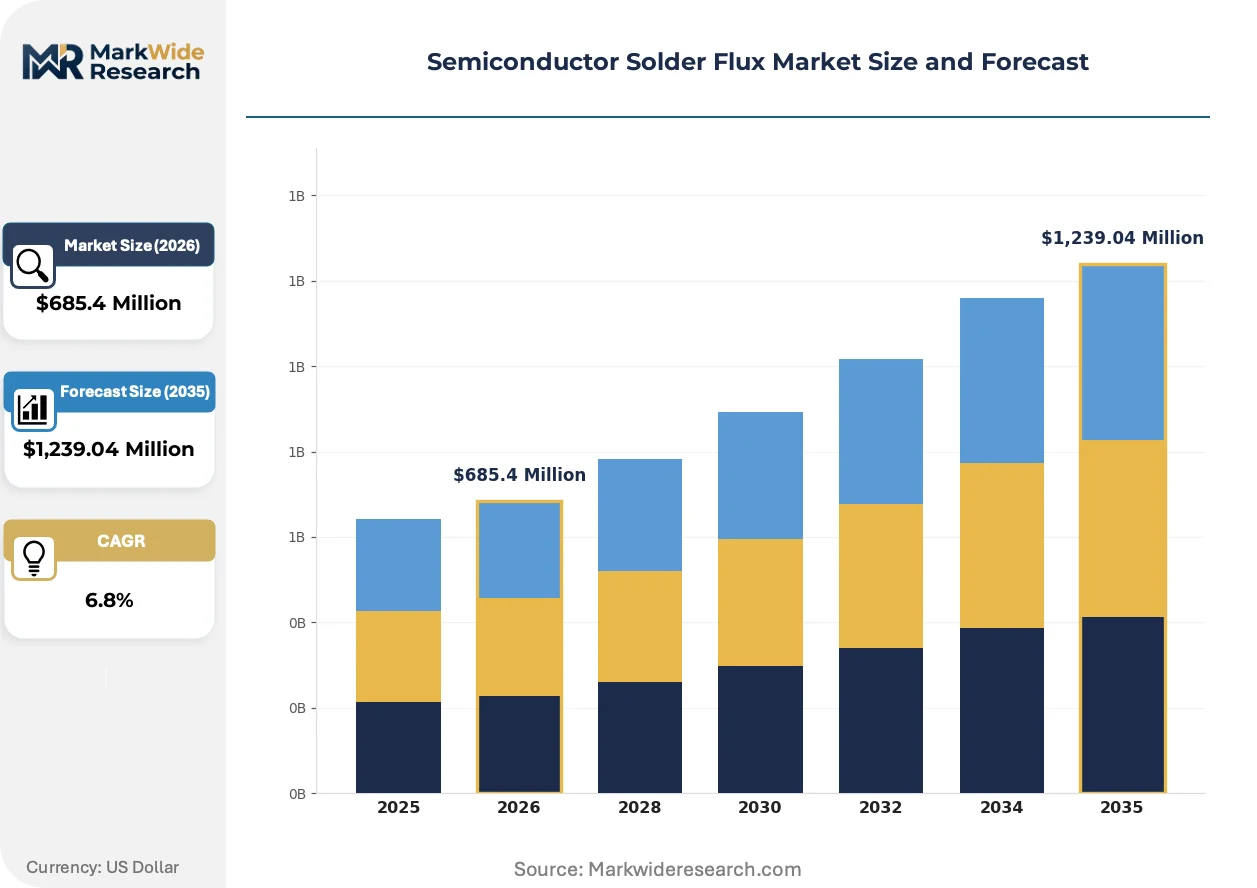
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rosin Flux, No-Clean Flux, Water-Soluble Flux, Lead-Free Flux Technology: Wave Soldering, Selective Soldering, Reflow Soldering, Manual Soldering End User: Consumer Electronics, Automotive Electronics, Industrial Electronics, Telecommunications Application: PCB Assembly, Semiconductor Packaging, Surface Mount Technology, Electronic Manufacturing Services |
| Companies Covered | Indium Corporation, Heraeus Holding GmbH, AIM Solder, Henkel AG & Co. KGaA, Alpha Assembly Solutions, Kester, Shenmao Technology Inc., Senju Metal Industry Co., Ltd., Inventec Performance Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Solder Flux Market Trends and Innovations
Activators and carrier chemistries are diverging along cleanliness-performance tradeoffs as packaging miniaturization and environmental compliance tighten simultaneously.
Micro-alloyed solder paste systems incorporating nanoparticle-enhanced flux vehicles are rendering obsolete conventional rosin-based formulations in sub-0.3mm pitch applications. Smartphone and wearable OEMs in South Korea and Taiwan have adopted these systems at production scale since 2022. The shift is compressing margin structures for mid-tier flux compounders lacking nanoparticle dispersion capabilities.
EPA Method 24 VOC testing protocols now classify low-solvent no-clean fluxes separately from traditional rosin solutions, creating regulatory preference for synthetic base chemistries. US-based electronics assemblers face emissions reporting thresholds that favor water-based and zero-VOC formulations. Military and medical device segments retain solvent-cleanable flux exemptions, fragmenting procurement specifications across end-use verticals.
Consolidated procurement by OSAT giants is displacing fragmented distributor networks across Asia-Pacific. ASE Group and JCET now specify direct technical partnerships with flux formulators, bypassing regional chemical distributors for volume supply agreements. This concentration is most pronounced in Singapore and Penang packaging corridors, where supplier qualification costs now exceed distributor margins.
Semiconductor Solder Flux Market Segmentation
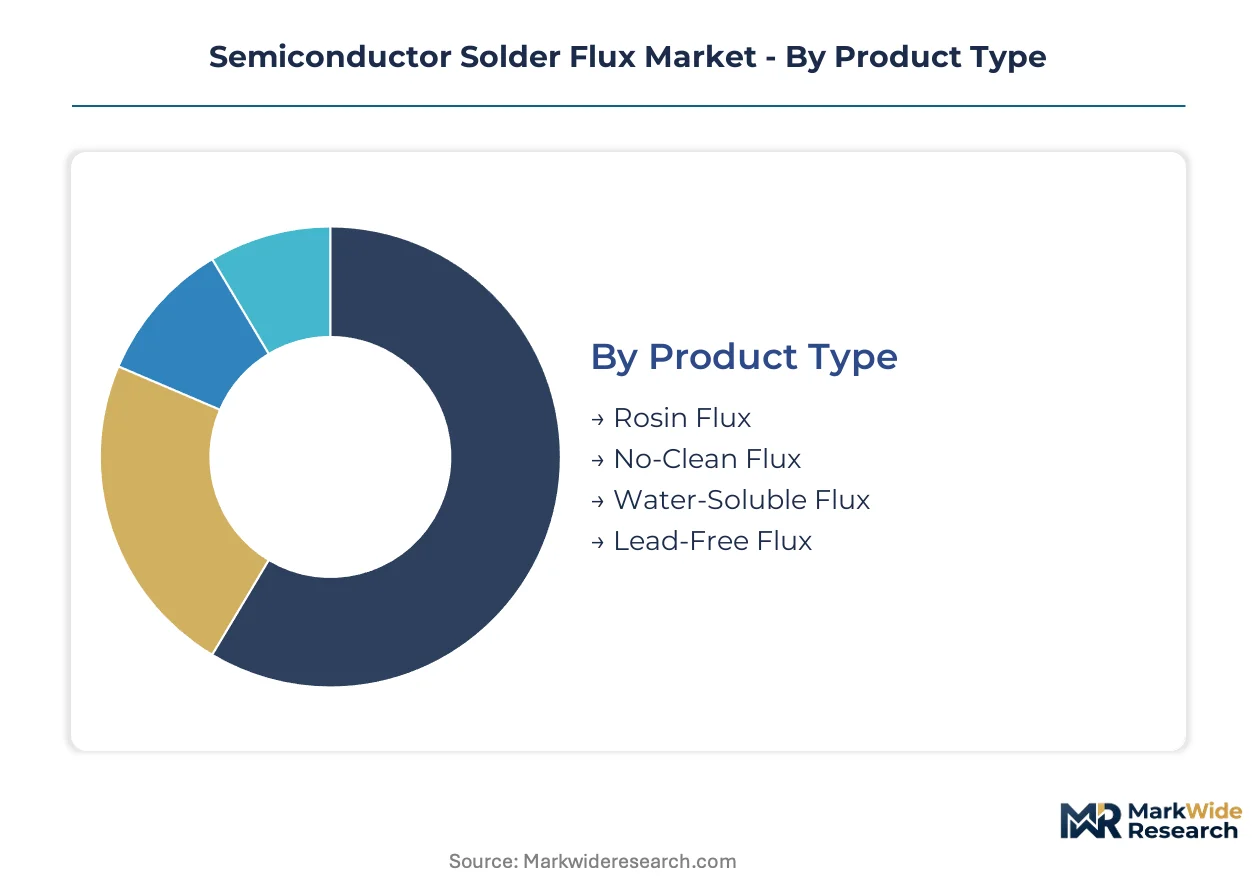
Semiconductor solder flux segmentation reveals how formulation chemistry, assembly technology, and end-use reliability requirements create distinct procurement specifications. Each dimension shapes supplier R&D priorities and customer qualification pathways differently.
Product Type:
Mature formulations dominate current revenue, while emerging chemistries reshape compliance-driven procurement across automotive and medical verticals.
- No-Clean Flux:Synthetic resin bases with low-residue activators eliminate post-process cleaning in miniaturized packages where physical access is restricted. Smartphone and wearable OEMs in Taiwan and South Korea specify these formulations for sub-0.3mm pitch assemblies where ionic contamination risks field failures.
- Rosin Flux:Natural pine-derived colophony blended with halide or organic acid activators delivers superior oxide reduction kinetics at low temperatures. Legacy consumer electronics assembly in mainland China retains this chemistry for cost-sensitive through-hole applications where cleaning infrastructure remains available.
- Water-Soluble Flux:Highly polar synthetic activators in glycol or water carriers permit complete residue removal via aqueous cleaning. Military and medical device manufacturers in the United States specify these formulations where MIL-STD-202 ionic contamination standards apply.
- Lead-Free Flux:Modified activator packages compensate for higher melting points of SAC305 and related alloys without compromising wetting performance. European automotive electronics suppliers adopt these formulations under REACH Article 33 disclosure obligations.
No-Clean Flux retains volume leadership; Lead-Free Flux holds the steepest expansion curve.
Technology:
Cost tier stratification separates high-volume automated processes from precision manual applications requiring specialized technician training.
- Reflow Soldering:Forced-convection ovens with precise thermal profiling deposit solder paste on surface-mount pads before component placement. Advanced packaging facilities in Singapore and Penang deploy this technology exclusively for flip-chip and wafer-level package assembly.
- Wave Soldering:Molten solder wave contact solders through-hole components on mixed-technology boards. Industrial electronics manufacturers in Germany retain this method for power supply modules requiring heavy copper thermal management.
- Selective Soldering:Programmable mini-wave nozzles target specific through-hole joints without masking surrounding surface-mount devices. Automotive ECU producers in Mexico adopt this hybrid approach for mixed-technology powertrain controllers.
- Manual Soldering:Hand-held iron applications with liquid or gel flux dispensing repair prototypes and low-volume specialty assemblies. Aerospace maintenance operations in France utilize certified technician workflows for flight-critical system repairs.
Reflow Soldering dominates value capture; Selective Soldering is climbing the fastest as automotive mixed-technology boards proliferate.
End User:
Application-specific reliability tiers create divergent qualification requirements from consumer-grade thermal cycling to automotive mission-profile validation.
- Automotive Electronics:Powertrain inverters, battery management systems, and ADAS modules demand flux formulations surviving AEC-Q100 thermal cycling from -40°C to 150°C. EV manufacturers in Germany and the United States specify halogen-free no-clean grades for underfill-compatible residues.
- Consumer Electronics:Smartphones, laptops, and wearables prioritize miniaturization and cost optimization over extended reliability. Assembly contractors in Vietnam serving Apple and Samsung supply chains drive volume consumption of synthetic-base no-clean formulations.
- Industrial Electronics:Factory automation controllers and power conversion equipment operate in uncontrolled environments with extended service life requirements. Japanese industrial equipment OEMs specify rosin-based formulations with enhanced humidity resistance.
- Telecommunications:Base station infrastructure and optical networking hardware demand long-term stability in outdoor installations. 5G equipment suppliers in Finland and Sweden procure low-residue fluxes compatible with conformal coating adhesion.
Consumer Electronics retains volume leadership; Automotive Electronics gains share fastest as electrification multiplies semiconductor content per vehicle.
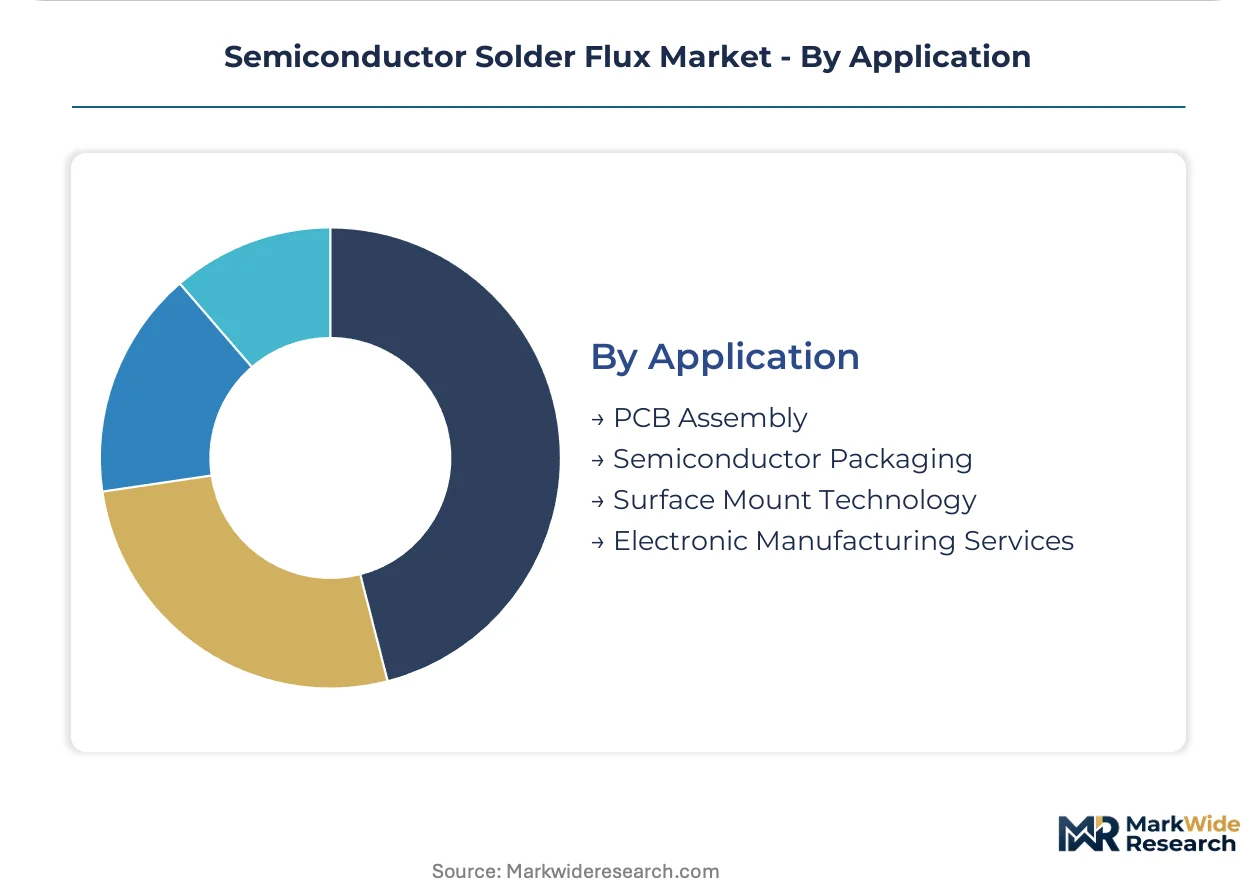
Application:
Customer type concentration separates captive semiconductor packaging from outsourced electronics manufacturing with divergent technical service requirements.
- Semiconductor Packaging:Flip-chip, wafer-level, and system-in-package assembly require flux residues compatible with subsequent underfill molding and wire bonding. OSAT giants in Taiwan and Singapore specify direct technical partnerships with formulators for process optimization support.
- PCB Assembly:Printed circuit board soldering encompasses surface-mount and through-hole attachment across diverse end products. Contract manufacturers in Malaysia serving industrial and medical verticals maintain multi-flux inventories for customer-specific qualification requirements.
- Surface Mount Technology:Component placement and reflow of chips, passives, and connectors on organic substrates. EMS providers in Mexico serving North American automotive Tier 1s invest in selective soldering capability for mixed-technology boards.
- Electronic Manufacturing Services:Full-turnkey production from design through test and fulfillment creates consolidated flux procurement at scale. Foxconn and Jabil operations in China negotiate direct volume agreements bypassing regional chemical distributors.
PCB Assembly retains volume leadership; Semiconductor Packaging shows the steepest expansion trajectory as advanced packaging architectures multiply flux consumption per wafer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Mexico prioritize cost-sensitive formulations for high-volume consumer electronics assembly, while German and Japanese automotive electronics producers absorb premium pricing for AEC-Q100-qualified no-clean grades without volume elasticity.
China
Domestic semiconductor packaging capacity expansion in Jiangsu and Shanghai provinces drives concentrated flux demand from OSAT facilities. MIIT green manufacturing credits subsidize lead-free chemistry transitions for domestic formulators. The Yangtze River Delta cluster hosts captive blending operations serving flip-chip and wafer-level packaging lines.
Germany
Automotive powertrain electrification multiplies flux consumption per vehicle for inverter and battery management module assembly. REACH Article 33 disclosure obligations favor no-clean formulations that minimize downstream substance reporting for OEMs. Bavaria's automotive electronics corridor anchors European demand for halogen-free, underfill-compatible grades.
United States
Defense and medical device manufacturers sustain water-soluble flux demand under MIL-STD-202 ionic contamination standards. EPA Method 24 VOC testing protocols elevate regulatory preference for synthetic-base no-clean formulations over rosin solutions. The Southwest packaging corridor in Arizona and New Mexico concentrates advanced flip-chip assembly requiring residue-compatible flux chemistries.
Vietnam
Intel and Amkor facility investments in Ho Chi Minh City and Bac Ninh provinces create demand for localized flux blending and technical service presence. Contract manufacturers serving Apple and Samsung supply chains drive volume consumption of synthetic-base no-clean formulations. Northern industrial zones concentrate EMS operations importing formulation expertise from Taiwanese technical partners.
Japan
Industrial automation equipment OEMs specify rosin-based formulations with enhanced humidity resistance for factory controller applications. METI directives on green manufacturing push domestic producers toward low-residue chemistry transitions. The Chubu region around Nagoya hosts precision electronics assemblers maintaining multi-flux inventories for customer-specific qualification requirements.
Semiconductor Solder Flux Market Competitive Landscape
Capability concentration sits with specialized formulators commanding premium positioning through activator chemistry expertise; scale advantage sits with integrated materials suppliers blending flux as part of broader solder paste portfolios. The market structures around three tiers: precious-metal refiners with captive activator supply, regional compounders serving geographic procurement clusters, and multinational chemical conglomerates distributing flux within broader electronics materials portfolios. Dominant competitive moves include direct technical partnerships with OSAT giants bypassing distributor networks, and backward integration into ultra-high-purity indium refining for activator supply security.
Among German-based materials specialists, Heraeus Holding GmbH anchors European supply through precious-metal refining integration. Indium Corporation exemplifies the capability-concentrated tier with deep R&D intensity in ultra-high-purity activators. Shenmao Technology Inc. occupies a scale-driven position manufacturing out of Taiwan and mainland China facilities.
| Leading Market Players |
|---|
| Indium Corporation |
| Heraeus Holding GmbH |
| AIM Solder |
| Henkel AG & Co. KGaA |
| Alpha Assembly Solutions |
| Kester |
| Shenmao Technology Inc. |
| Senju Metal Industry Co., Ltd. |
| Inventec Performance Chemicals |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Rotterdam container freight corridors transmit input cost volatility from Chinese indium refiners directly into European flux pricing, while simultaneously enabling Southeast Asian packaging hubs to arbitrage formulation premiums against legacy supply chain markups.
Pricing Analysis
Technical service contracts and formulation customization fees generate lifetime value exceeding base chemical sales by substantial multiples. Three-tier pricing structure across AEC-Q100 certified premium, industrial-standard, and economy consumer grades separates automotive electronics procurement from cost-sensitive smartphone assembly. Cost compression in economy-tier synthetic-base formulations is intensifying because Vietnamese EMS providers consolidate volume procurement. Consumer electronics contractors exhibit highest price sensitivity; German automotive Tier 1s absorb premium positioning without volume elasticity.
Supply Chain Analysis
Export-control restrictions on advanced packaging equipment to Chinese facilities fragment activator supply chain transparency and complicate cross-border inventory positioning. Ultra-high-purity indium refining capacity clusters in Chinese and Canadian smelters, while synthetic resin base production centers on Japanese and German chemical complexes. Palladium and silver salt feedstock price volatility creates margin unpredictability for high-reliability grades. Distribution runs through direct technical partnerships with OSAT giants, displacing fragmented regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against laser and conductive adhesive bonding technologies that threaten solder joint applications in ultra-miniaturized packages.
For Market Incumbents: Build formulation IP moats around halogen-free activator synthesis expertise that retiring Japanese and German specialists currently monopolize. Deepen backward integration into ultra-high-purity indium refining to secure captive activator supply against Chinese smelter concentration risk. Expand technical service presence in Vietnam's emerging packaging corridor before competitor qualification cycles lock in procurement relationships. For New Entrants and Emerging Players: Establish a beachhead in photovoltaic ribbon interconnect applications where semiconductor-grade flux specifications are newly penetrating solar cell stringing processes. Target Vietnamese and Mexican contract manufacturers serving Apple and Samsung supply chains with cost-optimized synthetic-base formulations. Lead with localized blending operations and rapid technical response capabilities against incumbent distributor networks. For Investors and Strategic Acquirers: Regional compounders with captive precious-metal refining integration and established OSAT technical partnerships represent the most defensible acquisition archetype. Long-term viability hinges on formulation chemistry expertise concentration rather than commodity scale. Monitor MIIT green manufacturing credit expansions as inflection signal for Chinese domestic producer cost advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ultra-High-Purity Indium Refining | Secures captive activator supply against Chinese and Canadian smelter concentration vulnerability. |
| Direct Technical Partnership with OSAT Giants | Bypasses distributor margins in Singapore and Penang packaging corridors where qualification costs exceed intermediary value. |
| Halogen-Free Activator R&D Investment | Addresses REACH Article 33 disclosure burdens and automotive underfill compatibility requirements simultaneously. |
| Localized Blending Operations in Vietnam | Captures Intel and Amkor facility-driven demand with reduced logistics exposure and faster technical service response. |
| Photovoltaic Ribbon Interconnect Qualification | Extends semiconductor-grade specifications into solar cell stringing as module efficiency targets tighten. |
Research Methodology
Initial hypotheses were tested against primary input from flux formulation chemists, OSAT procurement directors, automotive electronics Tier 1 supplier quality engineers, and precious-metal refinery technical leads, then refined against secondary validation from customs trade data, SEMI equipment shipment reports, EPA Method 24 VOC testing protocols, and REACH Article 33 disclosure filings. Bottom-up segment sizing triangulated against top-down materials consumption estimates across semiconductor packaging, PCB assembly, and EMS verticals.
Demand-supply-balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning product type chemistry tiers, reflow versus selective soldering technology adoption, automotive versus consumer electronics end-use reliability requirements, and captive packaging versus outsourced assembly application structures. CAGRs derived from iterative convergence of input cost trajectory assumptions and end-use semiconductor content expansion rates, incorporating AEC-Q100 qualification timeline constraints and MIIT green manufacturing credit elasticity effects.
Sensitivities concentrate around indium supply disruption scenarios, REACH halogen-free specification accelerations, and laser bonding technology substitution thresholds. Forecasts reflect documented assumptions on automotive electrification semiconductor content multipliers and advanced packaging architecture diffusion rates. Material shifts in export-control regime stringency or photovoltaic ribbon interconnect specification adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Asia Pacific LED Packaging Market