
 Static Transfer Switches Market | 2026-2036
Static Transfer Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Static Transfer Switches Market Analytics
Direct OEM channel relationships in the static transfer switches sector is fragmenting as specialized distributors and systems integrators gain procurement influence. Schneider Electric leverages its global service network to sustain large-account relationships across critical infrastructure verticals. Eaton anchors North American utility partnerships through its electrical solutions division. ABB competes on modular architecture, allowing scalable deployment across varied facility footprints.
A static transfer switch is an electrical device that automatically transfers a load between two independent AC power sources with transfer times typically under 4 milliseconds, ensuring uninterrupted power to sensitive equipment. It employs solid-state switching using silicon-controlled rectifiers or insulated-gate bipolar transistors rather than mechanical contacts, eliminating arcing and wear in mission-critical environments. Automatic switches command the dominant share of product type revenue, driven by data center and healthcare mandates for zero-operator-intervention failover. Rack-mounted installations are expanding fastest among installation categories, reflecting hyperscale facility densification and edge computing node proliferation.
NFPA 70 (National Electrical Code) and IEC 62310 shape product certification requirements, with the former governing U.S. installation practices and the latter defining international performance benchmarks for automatic transfer equipment. OSHA workplace safety directives and EU CE marking obligations further constrain market access for uncertified suppliers. Stakeholders must monitor evolving efficiency standards from DOE and emerging grid-interconnection rules from FERC that could redefine transfer switch duty-cycle specifications and testing protocols.
Market Dynamics
Data center operators are forcing rapid product iteration as hyperscale facility densification creates thermal and spatial constraints that rack-mounted solid-state switching must resolve. This structural pressure cascades through certification requirements, supply chain configurations, and procurement specifications.
Growth Catalysts
- NFPA 70 compliance mandates:U.S. electrical safety codes now require automatic failover capabilities in critical infrastructure installations, redirecting procurement toward certified static transfer switch suppliers.
- Silicon carbide semiconductors:Wide-bandgap materials enable faster switching speeds and reduced heat dissipation, allowing higher density deployments in edge computing nodes.
- Shenzhen electronics corridor concentration:East Asian manufacturing clusters achieve component cost advantages through vertical specialization in power electronics assembly.
Market Restraints
- Copper and rare earth price volatility:Input cost fluctuations for silicon-controlled rectifiers and magnetic components compress margin structures for mid-tier suppliers.
- IEC 62310 testing backlog:European certification queue delays extend product launch timelines by six to nine months for uncertified entrants.
- Mechanical transfer switch substitution:Lower-cost electromechanical alternatives retain share in non-critical commercial applications where sub-4-millisecond transfer is unnecessary.
Strategic Opportunities
- India data center expansion:PLI scheme incentives for electronics manufacturing are attracting hyperscale investments requiring localized static transfer switch supply.
- Modular microgrid integration:Convergence of solid-state switching with battery energy storage systems creates new product categories for distributed generation.
- Direct OEM contracting:Bypassing traditional distributor channels allows manufacturers to capture service revenue through lifecycle maintenance agreements.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for silicon-controlled rectifier design and thermal management remains concentrated among incumbent suppliers.
- Legacy electrical infrastructure incompatibility:Integration with existing uninterruptible power supply architectures requires custom engineering that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static Transfer Switches Market |
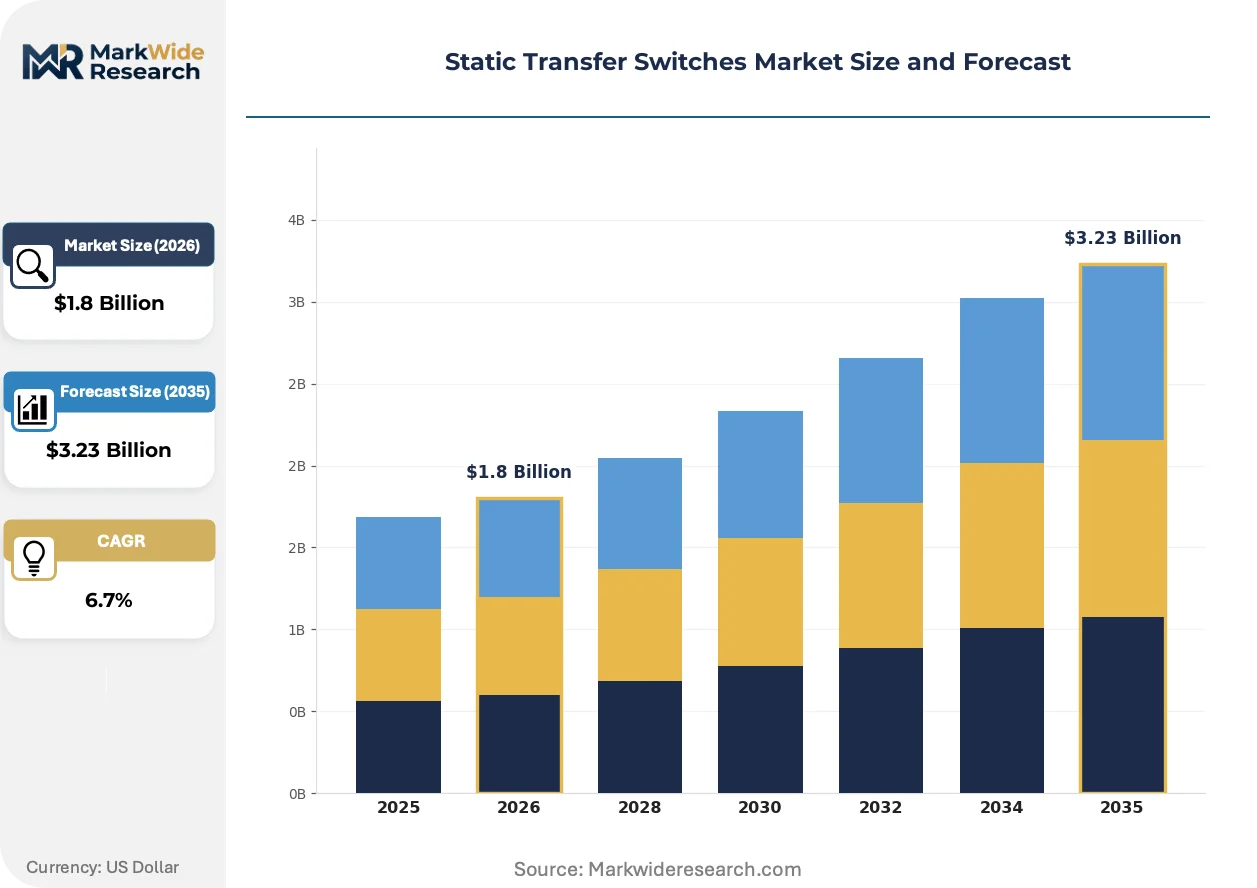
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Switches, Manual Switches, Modular Switches, Transfer Panels End User: Data Centers, Telecommunications, Healthcare Facilities, Industrial Plants Installation: Wall-Mounted, Rack-Mounted, Floor-Mounted, Integrated Systems Application: Power Distribution, Backup Systems, Load Management, Critical Operations |
| Companies Covered | ABB, Schneider Electric, Eaton, Vertiv Group, Socomec Group, LayerZero Power Systems, DELTA, Mitsubishi Electric, Piller Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static Transfer Switches Market Evolving Landscape
Solid-state power switching is undergoing material and architectural transformation as wide-bandgap semiconductors and intelligent control systems redefine performance benchmarks. These developments are compressing product lifecycles and reshaping competitive differentiation.
Silicon carbide power modules are rendering obsolete traditional silicon-based insulated-gate bipolar transistor designs in high-frequency switching applications. Hyperscale data center operators in Northern Virginia and Frankfurt are specifying SiC-based units for new 400V DC distribution architectures. The technology is rendering obsolete conventional thermal management approaches as operating temperatures drop and power density rises.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are accelerating dry-type transformer adoption in static transfer switch enclosures. Manufacturers must redesign cooling systems to eliminate SF6-dependent components from sealed cabinet designs. German industrial facilities face the most acute compliance pressure as the country's national climate regulator enforces accelerated phase-out schedules.
Specification authority is migrating from facilities engineering departments to procurement teams with total-cost-of-ownership mandates. Systems integrators are displacing electrical distributors as the primary specification channel for large-account data center projects. This shift is most visible in Singapore and Amsterdam, where colocation providers centralize purchasing decisions at corporate headquarters.
Static Transfer Switches Market Segmentation
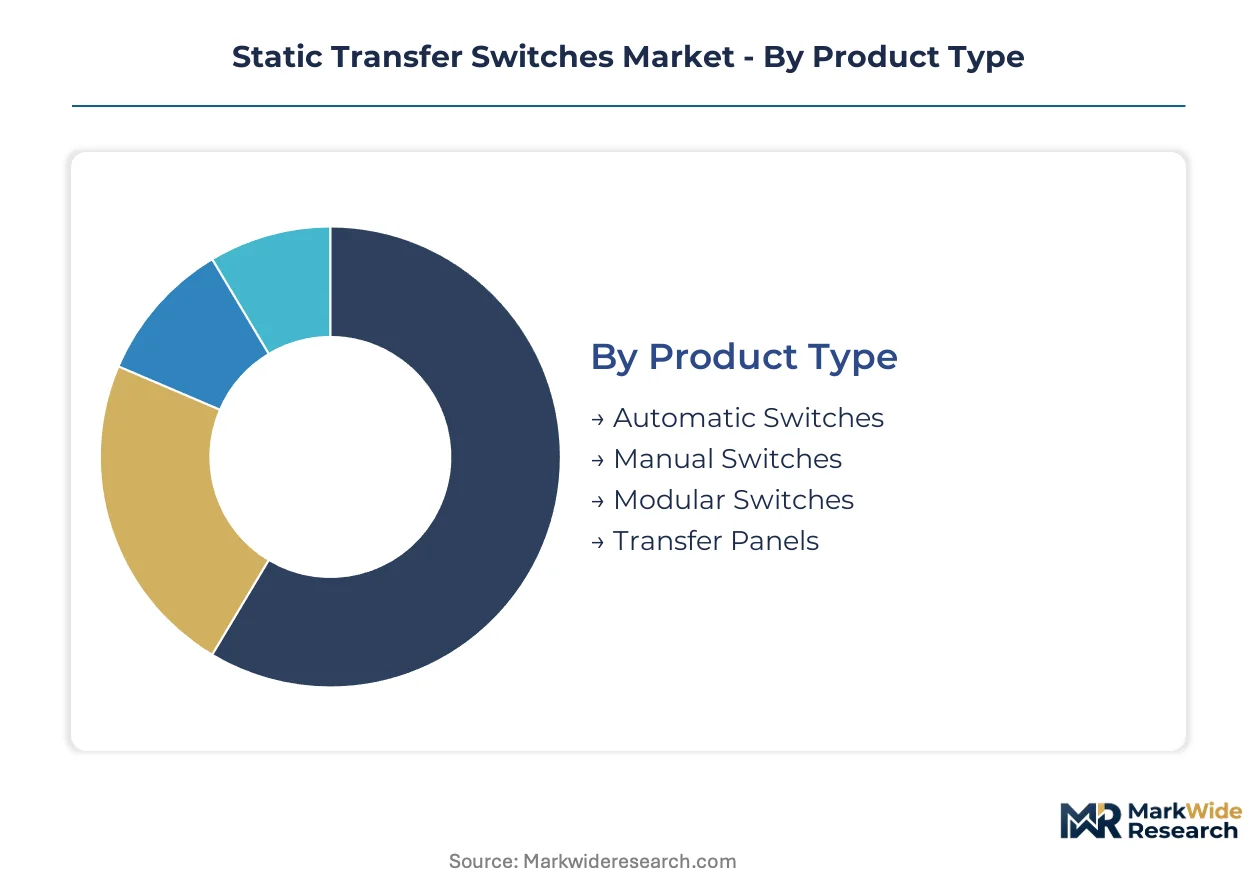
Static transfer switch procurement varies sharply across deployment contexts. Product architecture, facility type, and mounting constraints each reshape specification requirements and supplier selection criteria.
Product Type:
Cost tier determines switching sophistication and operator intervention requirements.
- Automatic Switches:Solid-state designs using silicon-controlled rectifiers execute sub-4-millisecond transfers without human intervention. Data centers in Northern Virginia and Frankfurt specify these units for Tier III and Tier IV uptime certifications under NFPA 70 and IEC 62310 mandates.
- Modular Switches:Scalable architectures allow incremental capacity expansion through paralleled power modules. ABB and Schneider Electric compete on this architecture for hyperscale facilities requiring phased deployment across multi-megawatt footprints.
- Manual Switches:Operator-actuated designs serve non-critical commercial loads where brief interruption tolerance exists.
- Transfer Panels:Pre-wired enclosure systems reduce field installation labor for electrical contractors.
Automatic switches command the established base. The steepest expansion runs through modular switches.
End User:
Application criticality drives specification stringency and certification requirements.
- Data Centers:Hyperscale operators demand rack-mounted solid-state units with 400V DC compatibility and intelligent monitoring integration. Northern Virginia's Ashburn corridor and Frankfurt's Flughafen district anchor procurement volume for cloud infrastructure expansion.
- Healthcare Facilities:Patient life-support systems require IEC 62310-certified automatic failover with documented transfer time verification. German hospital construction under federal energy efficiency mandates is accelerating replacement of electromechanical legacy systems.
- Telecommunications:Edge computing nodes and 5G base stations specify compact wall-mounted units for outdoor cabinet deployment.
- Industrial Plants:Process continuity requirements vary by sector, with semiconductor fabrication imposing stricter specifications than general manufacturing.
Data centers command the established base. The steepest expansion runs through healthcare facilities.
Installation:
Physical mounting constraints reshape thermal management and spatial optimization tradeoffs.
- Rack-Mounted:19-inch standard enclosures integrate directly into server cabinet rows, eliminating floor space consumption. Hyperscale densification in Shenzhen's electronics corridor and Amsterdam's Schiphol-Rijk district prioritizes these configurations for power distribution unit consolidation.
- Wall-Mounted:Compact enclosures serve telecommunications shelters and remote edge nodes where floor loading is restricted.
- Floor-Mounted:Freestanding cabinets accommodate higher current ratings for industrial substation applications.
- Integrated Systems:Factory-integrated uninterruptible power supply and switch combinations reduce field commissioning complexity.
Floor-mounted installations command the established base. The steepest expansion runs through rack-mounted configurations.
Application:
Functional use case determines duty cycle specifications and control system complexity.
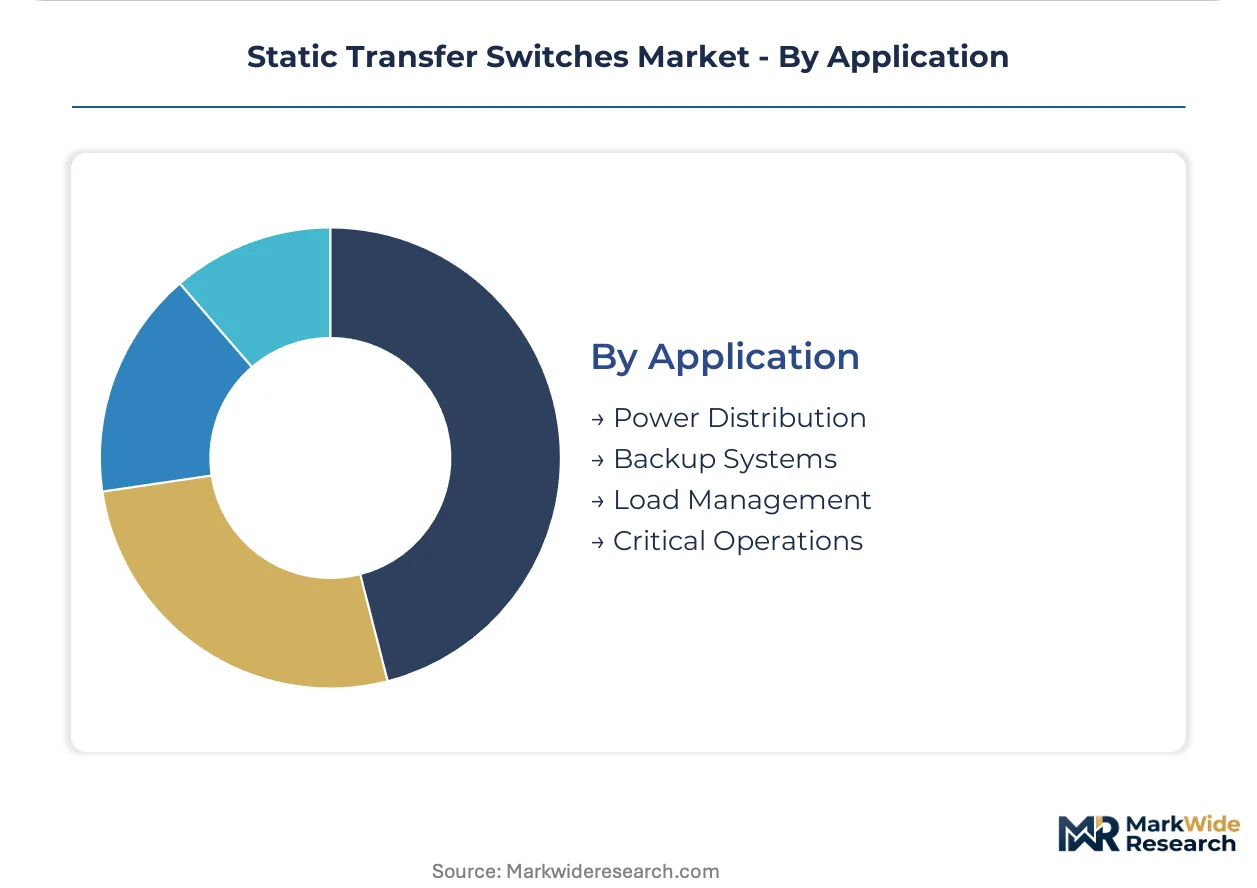
- Backup Systems:Automatic failover between utility and generator sources defines core static transfer switch functionality. Data center operators in Singapore and Mumbai specify these applications for grid instability resilience.
- Power Distribution:Load segregation across multiple feed sources enables maintenance windows without shutdown.
- Load Management:Peak shaving and demand response integration require bidirectional communication with grid operators.
- Critical Operations:Synchronized transfer for medical imaging and semiconductor processing demands phase-angle monitoring and inrush current suppression.
Backup systems command the established base. The steepest expansion runs through critical operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers in Germany command pricing premiums through IEC 62310 certification dominance, while Shenzhen-based suppliers compete on component cost efficiency for rack-mounted automatic units. This asymmetry reshapes procurement patterns across data center construction corridors.
United States
Hyperscale operators in Northern Virginia's Ashburn corridor drive automatic switch procurement for Tier III uptime mandates. NFPA 70 compliance requirements redirect hospital and financial sector procurement toward certified suppliers with documented sub-4-millisecond transfer verification. LayerZero Power Systems anchors domestic manufacturing for critical infrastructure verticals.
Germany
Federal energy efficiency mandates accelerate replacement of electromechanical legacy systems in hospital construction and industrial facilities. The country's national climate regulator enforces accelerated F-Gas phase-out schedules, forcing dry-type transformer redesigns in sealed cabinet architectures. Frankfurt's Flughafen district concentrates procurement volume for cloud infrastructure expansion.
China
Shenzhen's electronics corridor achieves vertical specialization advantages in power electronics assembly for rack-mounted configurations. Dual carbon goals under MEE supervision reshape cooling system specifications for sealed enclosures. Domestic hyperscale operators specify 400V DC compatible units for new data center builds.
India
PLI scheme incentives for electronics manufacturing attract hyperscale investments requiring localized static transfer switch supply. Mumbai and Singapore-based operators specify automatic failover systems for grid instability resilience. CEA mandates reshape installation practices for critical infrastructure applications.
Singapore
Colocation providers centralize purchasing decisions at corporate headquarters, displacing electrical distributors with systems integrators. Corporate procurement teams with total-cost-of-ownership mandates now control specification authority. The city-state's data center moratorium redirects investment toward edge computing node deployment.
Static Transfer Switches Market Competitive Landscape
Integrated electrical conglomerates and specialized power quality firms split the market between broad service networks and focused technical depth. The vendor base concentrates among incumbent suppliers with captive silicon-controlled rectifier design capabilities and established certification track records. Three archetypes dominate: global infrastructure conglomerates with lifecycle service offerings, regional specialists with modular architecture expertise, and component-integrated manufacturers with cost-optimized production. Competitive moves center on direct OEM contracting to capture maintenance revenue and silicon carbide semiconductor adoption for thermal density advantages.
Among the integrated infrastructure tier, ABB, Schneider Electric, and Eaton exemplify divergent strategic positioning. ABB represents modular architecture specialization with scalable deployment capabilities across varied facility footprints. Schneider Electric anchors large-account relationships through global service network density in critical infrastructure verticals. Eaton occupies a position tied to North American utility partnerships through electrical solutions integration. These three conglomerates collectively demonstrate how certification breadth, geographic service presence, and semiconductor integration capabilities define competitive differentiation in automatic transfer equipment procurement.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton |
| Vertiv Group |
| Socomec Group |
| LayerZero Power Systems |
| DELTA |
| Mitsubishi Electric |
| Piller Group |
| Others |
Value Network & Pricing Analysis
Shenzhen's electronics corridor concentrates silicon-controlled rectifier assembly capacity, anchoring margin pools with OEMs that control thermal management IP and IEC 62310 certification pathways. This upstream density allows certified suppliers to command project-based premiums while contract manufacturers compete on standard rack-mounted unit economics.
Pricing Analysis
Configured-to-order pricing for IEC 62310-certified units with integrated monitoring runs 40-60% above standard rack-mounted configurations. Project-based pricing dominates, with premiums attaching to NFPA 70 compliance documentation and sub-4-millisecond transfer guarantees. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in mid-tier automatic switches is intensifying because copper and rare earth volatility squeezes magnetic component suppliers. Data center operators show lowest price sensitivity; commercial building contractors exhibit highest.
Supply Chain Analysis
Hon Hai, Flex, and Jabil hold contract manufacturing capacity for power electronics enclosures across Taiwan, Mexico, and China. Geographic supply concentration centers on East Asian semiconductor packaging, German magnetic component specialists, and U.S. silicon carbide wafer production. Raw material dependencies include copper busbar, silicon carbide substrates, and rare earth magnetic alloys. Single-source vulnerability runs through silicon carbide substrate supply. Distribution runs through systems integrators displacing electrical distributors in large-account data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as specification authority migrates from facilities engineering to procurement teams, creating niche openings for modular architecture specialists and silicon carbide-integrated suppliers outside incumbent service networks.
For Market Incumbents: Insulate large-account relationships by embedding lifecycle maintenance agreements that capture recurring revenue beyond equipment sale. Deepen backward integration into silicon carbide power module design to secure thermal density advantages against emerging SiC-integrated competitors. Certification investment in India's BIS and CEA pathways defends position as PLI scheme incentives attract hyperscale construction.
For New Entrants and Emerging Players: India's data center expansion under PLI scheme incentives represents the most penetrable geography, with localized supply gaps for automatic failover systems. Edge computing node deployment in Singapore's moratorium aftermath offers white-space for compact wall-mounted units with 400V DC compatibility. Direct OEM contracting bypasses systems integrator gatekeepers in Amsterdam and Northern Virginia corridors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrical infrastructure specialists holding IEC 62310 certification but lacking silicon carbide integration capabilities. Five-to-ten year viability hinges on semiconductor material transition completion. Acquisition target archetype: modular architecture firms with captive thermal management IP. Monitor silicon carbide substrate price inflection and F-Gas Regulation enforcement acceleration as demand signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Enables 400V DC distribution architectures for hyperscale operators in Frankfurt and Northern Virginia. |
| Direct OEM Lifecycle Contracting | Captures maintenance revenue streams through embedded service agreements with data center operators. |
| India PLI Localization | Positions suppliers for hyperscale construction under CEA mandates and electronics manufacturing incentives. |
| Dry-Type Transformer Redesign | Eliminates SF6-dependent components to meet EU F-Gas Regulation phase-out schedules in German facilities. |
| Modular Microgrid Convergence | Creates new product categories integrating solid-state switching with battery energy storage systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EIA electrical infrastructure data, IEC certification registries, and hyperscaler capex disclosures. Primary interviews engaged data center engineering directors, electrical contractor procurement leads, power electronics OEM product managers, and systems integrator specification specialists. Bottom-up unit economics triangulate against top-down market sizing across product type, installation category, and end-use vertical dimensions.
Forecast inputs include silicon carbide adoption curves, data center construction permits by metropolitan cluster, and regulatory enforcement timelines for NFPA 70 and IEC 62310. Segmentation modeling spans automatic versus manual switching, rack-mounted versus floor-mounted installation, and data center versus healthcare versus industrial end-use. CAGRs derive from installed base replacement cycles and new build penetration assumptions across the projection horizon. Industry-specific inputs incorporate thermal density requirements from hyperscale operators and F-Gas Regulation compliance cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive silicon carbide integration moves by specialized power quality firms would shift outcomes beyond modeled parameters. Regulatory acceleration in EU F-Gas phase-out or India's CEA mandate expansion could compress adoption timelines. Quarterly review of hyperscaler procurement announcements, IEC certification queue lengths, and silicon carbide substrate pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Navigation Switches Market
Switches
Campus Switches Market
Switches
Dual Power Transfer Switches Market
Switches
Miniature-Circuit Breaker Market
Switches
Fusible Switches Market
Switches
Optical Cross Connect (OXC) Switches Market
Switches
Vibration Level Switch Market
Switches
China Switchgear Market
Switches
Carrier Router Switch Market
Switches
Smart Pole-Mounted Switch Market
Switches
Digital Crosspoint Switches Market
Switches
United States X by Wire Systems Market
Switches
Timer Switch Socket Market
Switches
South Korea Reed Sensors Switches Market
Switches
Global Switchgear Market
Switches
Matrix Switches Market