
 Semiconductor Packaging Market | 2026-2036
Semiconductor Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Packaging Market Intelligence
The shift from captive in-house packaging to outsourced semiconductor assembly and test is broadening the addressable base for pure-play providers. ASE Holdings leverages its scale across Greater China to anchor high-volume flip-chip production for mobile and computing clients. Amkor Technology competes through geographic diversification, with operational footprints in Portugal, Vietnam, and the Philippines that reduce concentration risk. Taiwan Semiconductor Manufacturing Company extends its foundry dominance into advanced packaging, integrating CoWoS and InFO technologies to capture margin pools previously retained by OSATs.
Semiconductor packaging encompasses the protective enclosure and electrical interconnection of integrated circuits through processes such as wire bonding, flip-chip bumping, and redistribution layer formation, enabling thermal dissipation, mechanical protection, and signal integrity for downstream device assembly. Wafer-level packaging formats are displacing traditional leadframe solutions in mobile and wearable applications where z-height constraints dominate design priorities. System-in-Package architectures concentrate margin pools in aerospace and medical end uses by integrating heterogeneous dies from multiple process nodes into single substrates. Fan-out technology leads growth trajectories as substrate shortages and escalating reticle limits for large dies drive adoption of reconstituted wafer approaches.
The US EPA regulates hazardous substance thresholds in packaging materials under TSCA, while REACH and RoHS in Europe restrict lead content and persistent organic pollutants in electronic components, directly influencing substrate metallurgy and mold compound formulations. China's SAMR enforces GB standards on semiconductor reliability testing that determine market access for imported and domestically produced packages. Japan's METI coordinates national packaging R&D consortia targeting heterogeneous integration roadmaps. Stakeholders must monitor evolving substrate material restrictions and assess captive versus outsourced packaging strategies as device complexity fragments across chiplets and disaggregated architectures.
Market Dynamics
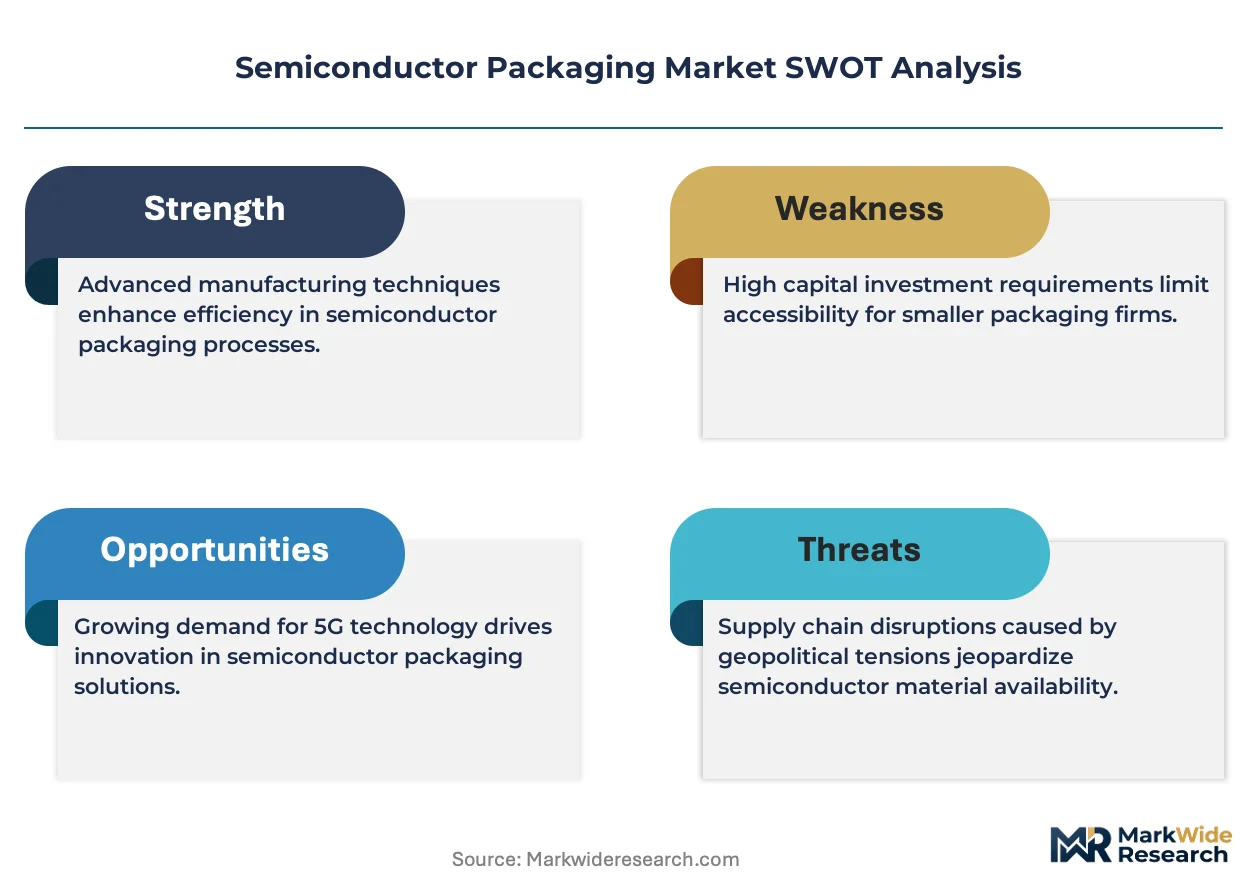
Substrate scarcity for advanced interposers is compressing profit margins across the supply chain while accelerating migration toward substrate-less fan-out formats. Foundries in Taiwan and South Korea are capturing margin pools previously retained by OSATs through captive advanced packaging capacity.
Growth Catalysts
- Automotive thermal compliance:NHTSA safety standards and EPA emissions frameworks mandate enhanced thermal management in electric vehicle power modules, expanding demand for copper-pillar flip-chip and embedded heat-spreader configurations.
- China's dual carbon mandate:GB standards on semiconductor reliability testing and carbon intensity thresholds are forcing domestic packaging upgrades, creating pull for advanced mold compounds and lead-free solder alloys.
- AI accelerator architecture:Reticle-size limitations for monolithic dies are driving chiplet disaggregation, concentrating CoWoS and InFO capacity expansion in Taiwan for high-bandwidth memory integration.
Market Restraints
- ABF substrate bottleneck:Ajinomoto Build-up Film substrate supply concentrates among three Japanese suppliers, constraining flip-chip BGA output for high-performance computing clients.
- Copper-palladium-gold metallurgy cost:Precious metal price volatility in wire bonding alloys compresses margins in automotive and industrial segments where gold wire remains specified for reliability.
- REACH substance restrictions:ECHA candidate list expansions on halogenated flame retardants force reformulation of epoxy mold compounds, extending qualification timelines by 12-18 months.
Strategic Opportunities
- Vietnam packaging corridor:Amkor and Intel have operationalized facilities near Ho Chi Minh City, creating a lower-cost alternative to China for US-bound electronics assembly subject to tariff exposure.
- Medical device miniaturization:Implantable neuromodulators and continuous glucose monitors require ultra-thin WLCSP formats, opening premium pricing tiers for hermetic sealing expertise.
- EU Green Deal alignment:CSRD reporting mandates and Ecodesign for Sustainable Products Regulation are creating first-mover advantage for packaging houses with verified lifecycle carbon footprints.
Industry Challenges
- Substrate-to-die bonding expertise:Hybrid bonding and thermocompression assembly require process engineers with atomic-scale alignment experience, creating talent scarcity in mature packaging regions.
- Multi-die test complexity:Known-good-die screening for chiplets demands probe card investments exceeding $5 million per platform, straining mid-tier OSAT balance sheets.
- IP licensing fragmentation:Redistribution layer routing patents held across TSMC, Intel, and Samsung complicate fan-out process development for second-tier foundries and OSATs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Packaging Market |
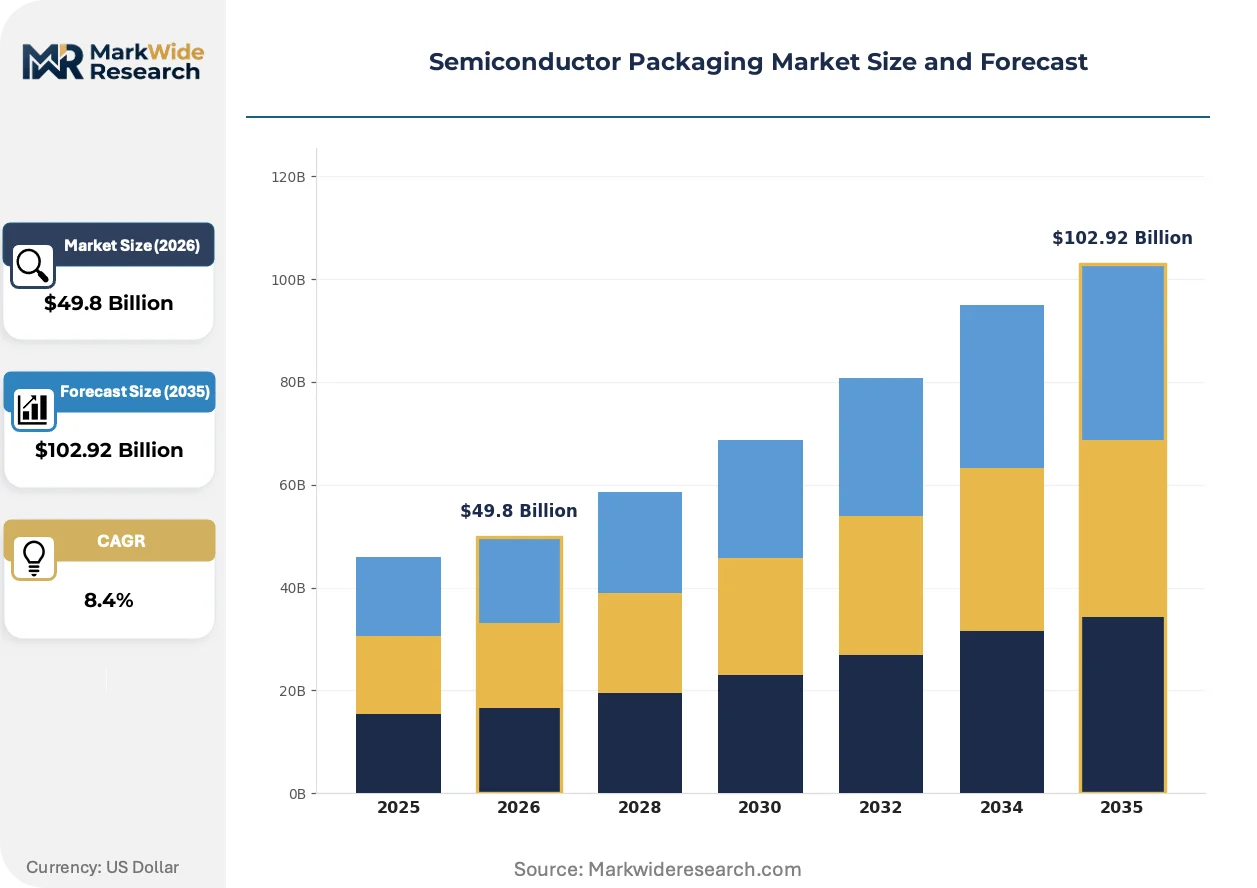
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $102.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
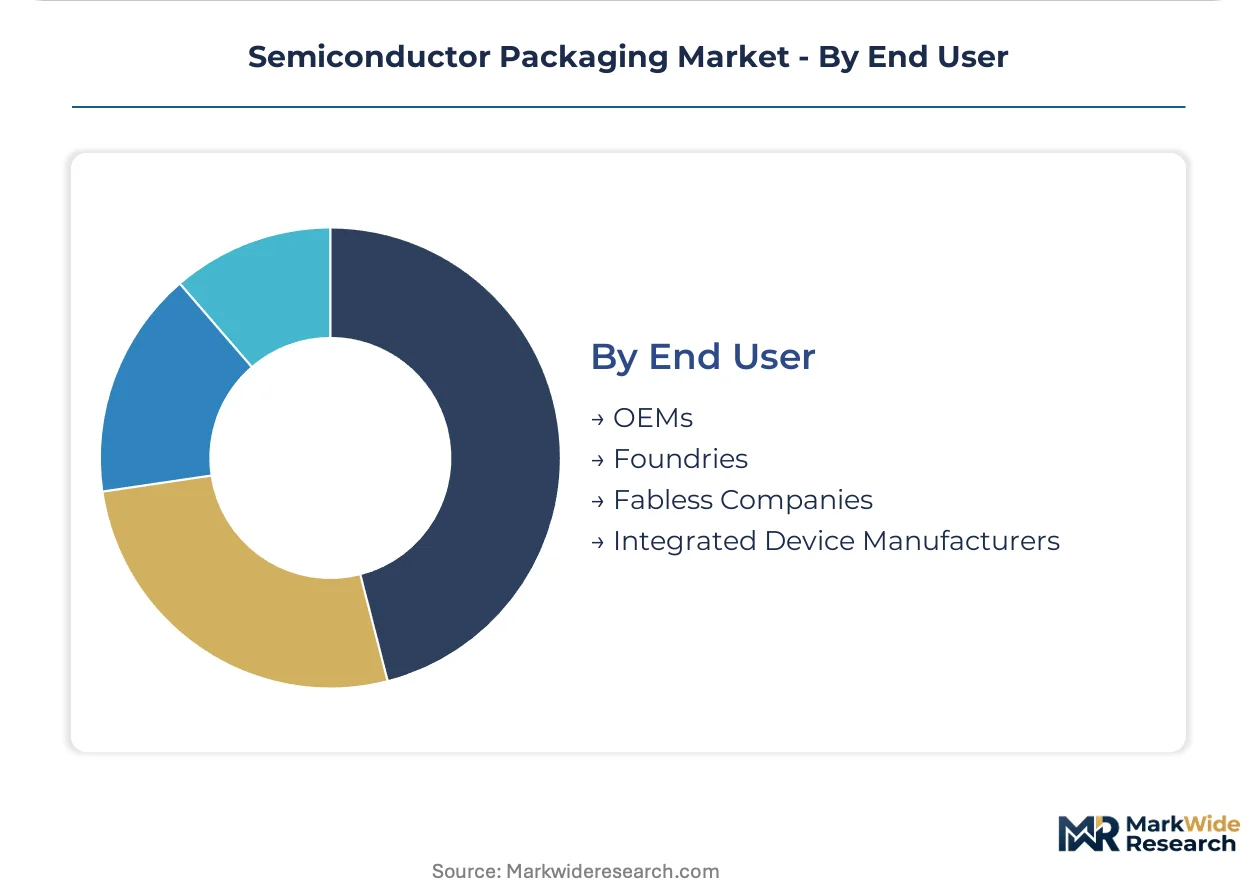
| Segmentation | Product Type: Chip-on-Board, Wafer-Level Packaging, System-in-Package, Ball Grid Array Application: Consumer Electronics, Telecommunications, Automotive, Industrial Automation Technology: Flip Chip, Fan-Out, Integrated Passive Device, 3D Packaging End User: OEMs, Foundries, Fabless Companies, Integrated Device Manufacturers |
| Companies Covered | QP Technologies, SHINKO ELECTRIC INDUSTRIES CO., LTD., Amkor Technology, ASMPT, Mercury, ASE Holdings, Integra Technologies, Taiwan Semiconductor Manufacturing Company, ISI - Interconnect Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Packaging Market Strategic Shifts & Innovations
Packaging technology trajectories are converging on heterogeneous integration architectures that dissolve traditional boundaries between front-end fabrication and back-end assembly. Three forces are compressing development cycles and redrawing competitive boundaries.
Glass core substrates are rewriting thermal and electrical performance benchmarks for high-density interconnects. Intel and Samsung have disclosed roadmaps integrating glass interposers for 2026-2027 high-performance computing products, targeting coefficient-of-thermal-expansion matching with silicon dies. This substrate transition is enabling larger reticle-stitched packages without warpage-induced yield loss.
REACH Annex XVII expansions on per- and polyfluoroalkyl substances are forcing mold compound reformulations across European-bound electronics. ECHA regulatory pressure is accelerating adoption of phosphorus-nitrogen flame retardant systems in epoxy molding compounds, with qualification bottlenecks concentrated in automotive and aerospace segments where historical reliability data carries contractual weight.
Consolidated procurement of advanced packaging services is concentrating negotiation leverage among hyperscale cloud providers and flagship smartphone OEMs. Direct foundry relationships for CoWoS and InFO are displacing traditional OSAT mediation for AI training and inference accelerators, with contract structures migrating from unit pricing to wafer-start commitments and capacity reservations.
Semiconductor Packaging Market Segmentation
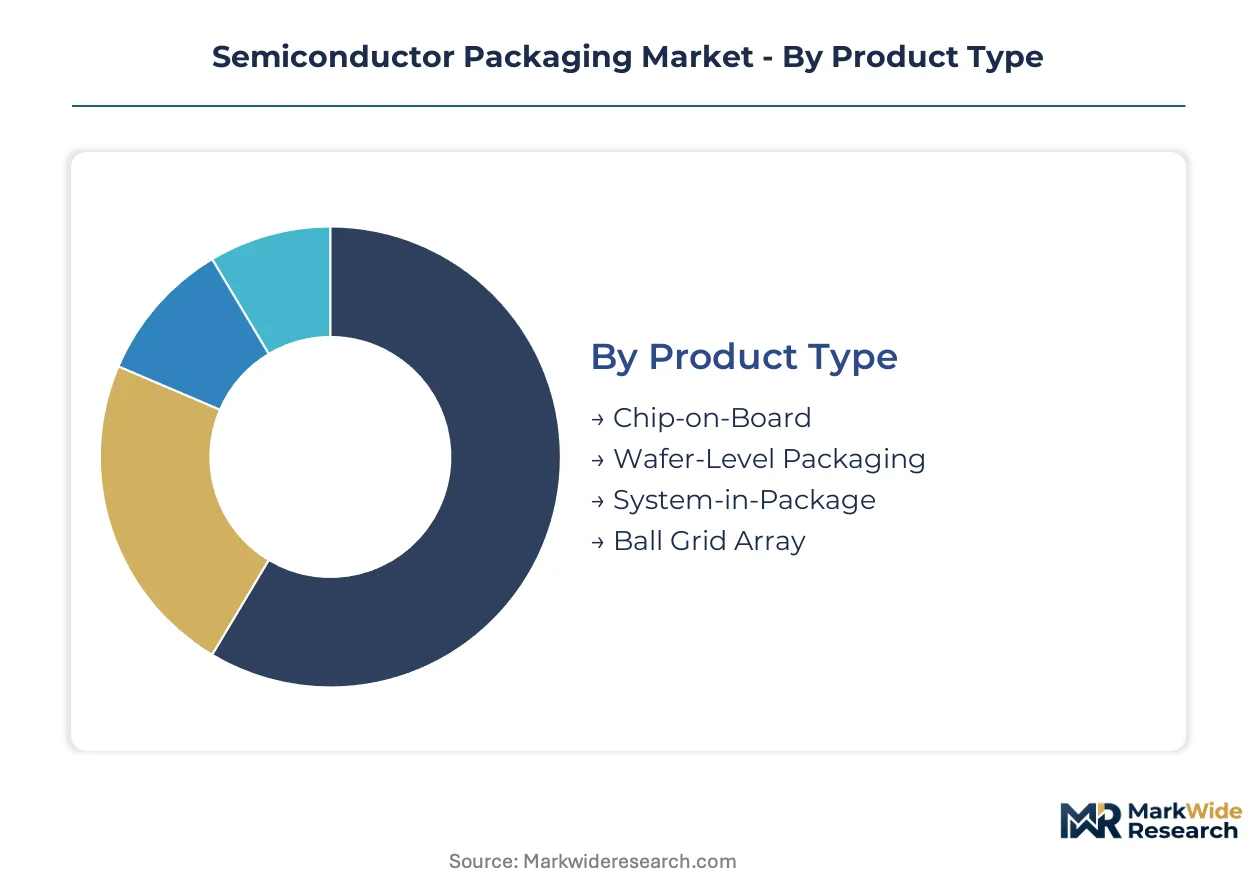
Semiconductor packaging architectures fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and qualification barriers. Understanding these segment boundaries enables suppliers to align capacity investments with the specific thermal, electrical, and form-factor requirements of downstream device categories.
Product Type:
Upgrade cycles in mobile computing and automotive electronics are accelerating displacement of legacy leadframe formats by advanced substrate-based and wafer-level alternatives.
- Wafer-Level Packaging:Dies receive protective encapsulation and redistribution layers while still in wafer form, eliminating traditional substrate carriers. Taiwan and South Korea concentrate capacity expansion for AI accelerator chiplets where z-height constraints dominate design specifications. Fan-out variants within this category are capturing share fastest as reticle limits force die disaggregation.
- System-in-Package:Multiple heterogeneous dies from disparate process nodes integrate onto single substrates with active or passive interposers. Aerospace and medical end uses concentrate demand where hermetic sealing and miniaturization justify premium pricing tiers. Hybrid bonding expertise creates scarcity premiums for suppliers with atomic-scale alignment capabilities.
- Chip-on-Board:Bare die attach directly to printed circuit boards with wire bond or flip-chip interconnection serves cost-sensitive consumer applications.
- Ball Grid Array:Solder ball arrays beneath ceramic or organic substrates remain specified for high-pin-count microprocessors and networking ASICs.
Ball Grid Array sits at the top of the volume ranking, with wafer-level packaging climbing the fastest.
Application:
Cost tier differentiation separates military-aerospace qualification premiums from high-volume consumer electronics where price per I/O dominates procurement decisions.
- Automotive:Power module packaging for electric vehicle inverters demands copper-pillar flip-chip and embedded heat-spreader configurations to meet NHTSA thermal compliance mandates. China's dual carbon goals and GB standards are forcing domestic packaging upgrades across imported and locally produced components. Copper-palladium-gold wire bonding persists in safety-critical segments despite precious metal cost volatility.
- Consumer Electronics:Smartphones and wearables drive wafer-level chip-scale formats where substrate elimination reduces bill-of-materials cost. Apple's procurement concentration and Samsung's vertical integration create dual sourcing pressures for OSATs serving this segment. Fan-out capacity for mobile APs concentrates in Taiwan alongside foundry proximity.
- Telecommunications:Baseband processors and RF front-end modules require mixed-signal packaging with precise impedance control.
- Industrial Automation:Extended temperature range specifications and long product lifecycles favor ceramic substrate formats with established reliability data.
Consumer electronics sits at the top of the volume ranking, with automotive climbing the fastest.
Technology:
Customer type fragmentation separates captive foundry packaging from merchant OSAT services, with margin pools concentrating at the advanced packaging frontier.
- Fan-Out:Reconstituted wafer approaches eliminate organic substrates by embedding dies in molded epoxy panels with subsequent redistribution layer formation. Taiwan concentrates CoWoS and InFO capacity for high-bandwidth memory integration in AI training accelerators. TSMC's foundry dominance extends into this packaging layer, displacing traditional OSAT mediation.
- Flip Chip:Solder bump or copper-pillar interconnection directly to organic laminates or ceramic substrates serves high-I/O microprocessors and networking silicon. ASE Holdings anchors high-volume production across Greater China for mobile and computing clients. ABF substrate supply constraints among three Japanese suppliers currently bottleneck output for high-performance computing.
- 3D Packaging:Through-silicon via stacking enables memory-on-logic and logic-on-logic integration for bandwidth-constrained workloads.
- Integrated Passive Device:Embedded resistors, capacitors, and inductors within packaging substrates reduce discrete component count in RF and power management applications.
Flip chip sits at the top of the volume ranking, with fan-out expanding most quickly.
End User:
Supply concentration dynamics favor foundries with captive advanced packaging capacity over merchant OSATs serving fragmented fabless demand.
- Foundries:TSMC, Samsung, and Intel have integrated CoWoS, InFO, and EMIB technologies into front-end manufacturing flows, capturing margin pools previously retained by back-end specialists. Direct relationships with hyperscale cloud providers concentrate negotiation leverage among a handful of AI accelerator customers. Wafer-start commitments and capacity reservations now displace traditional unit pricing structures.
- Fabless Companies:Qualcomm, NVIDIA, and AMD depend on foundry packaging or merchant OSATs for die assembly, creating dual sourcing complexity as advanced formats fragment across proprietary process flows. IP licensing fragmentation across redistribution layer patents complicates fan-out access for second-tier designers.
- OEMs:Apple and Samsung Electronics maintain captive packaging specifications that cascade through their contract manufacturer networks.
- Integrated Device Manufacturers:Intel and Texas Instruments retain in-house packaging for proprietary product flows with long lifecycle requirements.
OEMs sit at the top of the volume ranking, with foundries climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors global advanced packaging capacity, with foundry-integrated CoWoS and InFO production serving AI accelerator demand. Substrate scarcity and dual carbon mandates across East Asia are redrawing investment flows toward Vietnam and Malaysia.
United States
CHIPS and Science Act subsidies are attracting Intel and Samsung packaging investments to Arizona and Texas. The EPA regulates hazardous substance thresholds under TSCA, directly influencing mold compound formulations. Greater Phoenix clusters concentrate copper-pillar flip-chip capacity for automotive power modules serving domestic EV assembly.
China
Domestic packaging upgrades accelerate under GB reliability standards and dual carbon intensity targets for semiconductor manufacturing. SAMR enforces carbon accounting disclosure requirements that determine market access for imported components. Yangtze River Delta clusters in Jiangsu and Shanghai expand fan-out wafer-level capacity for AI training chips.
South Korea
Memory-on-logic integration for high-bandwidth architectures drives Samsung and SK Hynix packaging R&D concentration. METI-coordinated consortia in Japan influence regional heterogeneous integration roadmaps that Korean suppliers track closely. Pyeongtaek and Yongin host captive advanced packaging lines for AI accelerator exports.
Vietnam
Tariff exposure on China-sourced electronics accelerates Amkor and Intel facility expansion near Ho Chi Minh City. The country's Ministry of Planning and Investment offers tax incentives for semiconductor packaging foreign direct investment. Saigon Hi-Tech Park concentrates substrate-less fan-out pilot lines serving US-bound smartphone assembly.
Japan
ABF substrate supply concentration among Ajinomoto and two other suppliers constrains global flip-chip BGA output for high-performance computing. METI coordinates national packaging R&D consortia targeting glass interposer roadmaps. Kyoto-Osaka industrial corridors maintain wire bonding equipment and materials expertise for automotive reliability segments.
Semiconductor Packaging Market Key Industry Players
Global majors compete with regional champions across substrate access and foundry integration vectors. The vendor base separates into captive foundry packaging divisions, Greater China-scale OSATs, and geographic-diversified pure-plays. Three archetypes dominate: foundry-integrated packaging divisions capturing AI accelerator margin pools; high-volume OSATs anchoring mobile and automotive flip-chip; and regional specialists serving tariff-sensitive assembly corridors. Capacity reservations and wafer-start commitments displace traditional unit pricing as hyperscale cloud providers consolidate procurement leverage.
Within the foundry-integrated tier, Taiwan Semiconductor Manufacturing Company exemplifies vertical control over CoWoS and InFO process flows. Among Greater China-scale OSATs, ASE Holdings occupies a position serving high-volume mobile and computing clients across the region. On the geographic-diversification vector, Amkor Technology represents lower-cost alternatives to China-centric assembly for tariff-exposed electronics supply chains.
| Leading Market Players |
|---|
| QP Technologies |
| SHINKO ELECTRIC INDUSTRIES CO., LTD. |
| Amkor Technology |
| ASMPT |
| Mercury |
| ASE Holdings |
| Integra Technologies |
| Taiwan Semiconductor Manufacturing Company |
| ISI - Interconnect Systems |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud provider procurement consolidation for AI accelerator packaging is forcing foundries toward wafer-start commitment structures and away from unit pricing, compressing OSAT margins while elevating capacity reservation premiums for substrate-constrained formats. This demand-side restructuring concentrates pricing power among TSMC and Samsung captive packaging divisions as merchant competitors absorb ABF substrate cost pass-throughs.
Pricing Analysis
Input-cost pass-through from Ajinomoto Build-up Film substrate scarcity dominates pricing dynamics across high-performance computing segments. Three-tier pricing structure across premium, standard, and economy levels separates foundry-integrated CoWoS from OSAT-mediated flip-chip and legacy wire bonding. Cost compression in standard-tier flip-chip is intensifying because precious metal volatility in copper-palladium-gold alloys erodes automotive segment margins. Fabless AI chip designers exhibit lowest price sensitivity due to performance-per-watt imperatives, while consumer electronics OEMs drive hardest unit-cost negotiations.
Supply Chain Analysis
Freight cost differentials between Vietnam and Greater China are accelerating facility migration toward Ho Chi Minh City corridors for tariff-exposed US-bound assembly. Manufacturing concentrates in Taiwan, South Korea, and Vietnam, with substrate-less fan-out capacity expanding fastest in the first two. Raw material dependencies center on ABF film from Japan, epoxy mold compounds from German and Korean suppliers, and high-purity copper for pillar bumping. Single-source vulnerability in ABF substrate supply creates systemic bottleneck risk for flip-chip BGA output. Distribution runs through direct foundry relationships for AI accelerators and tiered OSAT networks for mobile and automotive volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Vietnam's tariff insulation against US Section 301 duties on China-sourced electronics creates 15-20 point margin advantages for packaging houses with operationalized Southeast Asian footprints.
For Market Incumbents: Anchor advanced packaging capacity in Vietnam and Malaysia to defend against tariff-driven customer migration while securing ABF substrate allocation through long-term offtake agreements with Ajinomoto. Hybrid bonding expertise represents the priority capability investment as chiplet architectures proliferate. Foundry packaging divisions threaten OSAT relevance through captive CoWoS and InFO integration. For New Entrants and Emerging Players: The 40-point spread between premium foundry-integrated and economy wire bonding pricing creates entry space for mid-tier fan-out specialists serving industrial automation and medical device miniaturization. Vietnam's packaging corridor offers lowest competitive density for greenfield substrate-less capacity. Target qualification partnerships with European automotive Tier 1s seeking REACH-compliant mold compound alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with Vietnam-based packaging assets possessing validated US customer relationships and GB standards compliance for China market optionality. Long-term viability hinges on substrate independence through glass interposer or fan-out process control. Watch Intel and Samsung glass core substrate roadmap disclosures as inflection signals for organic laminate displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate-less Fan-out Capacity Expansion | Eliminates ABF supply dependence for AI accelerator packaging in Taiwan and Korea. |
| Glass Core Substrate Pilot Line Investment | Intel and Samsung roadmaps target 2026-2027 high-performance computing product integration. |
| Vietnam Manufacturing Footprint Establishment | Amkor and Intel facilities near Ho Chi Minh City reduce China tariff exposure for US-bound electronics. |
| REACH-compliant Mold Compound Reformulation | ECHA Annex XVII expansions force phosphorus-nitrogen flame retardant system adoption. |
| Hybrid Bonding Process Engineering Acquisition | Atomic-scale alignment expertise commands scarcity premiums in chiplet integration architectures. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OSAT operations executives, foundry packaging division heads, ABF substrate procurement managers, and automotive Tier 1 component engineers with secondary validation against SEC filings, Taiwan Stock Exchange disclosures, Japan METI technology roadmaps, and Vietnam Ministry of Planning and Investment FDI statistics. Bottom-up capacity modeling and top-down end-use demand estimation triangulated volume and value outputs.
Segment-weighting approaches distributed value across wafer-level, system-in-package, and flip-chip formats proportionate to their contribution margins and capacity utilization rates observed across the analysis window. Technology trajectories modeled fan-out, 3D packaging, and integrated passive device adoption curves against heterogeneous integration roadmaps. CAGRs derived from supply-side capacity expansion announcements and demand-side silicon content-per-device trends in AI training accelerators and electric vehicle power modules.
The model assumes a particular technology adoption path; alternative pathways for glass interposer substrates would alter the outlook if coefficient-of-thermal-expansion matching yields exceed projected timelines or if ABF supply constraints resolve faster than anticipated. Forecasts reflect these assumptions alongside regulatory enforcement intensity for China's dual carbon mandates and REACH substance restrictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market