
 Global High-End Semiconductor Packaging Market | 2026-2036
Global High-End Semiconductor Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global High-End Semiconductor Packaging Market Foresight
Advanced packaging yield optimization is tilting margin pools away from traditional wirebond toward 2.5D and 3D integration flows. Taiwan Semiconductor Manufacturing Company leverages its CoWoS capacity monopoly to command pricing power on AI chiplet assemblies. Samsung Electronics anchors its position through in-house HBM stacking and fan-out panel-level R&D. ASE Technology Holding Co., Ltd competes via SiP dominance in smartphone and wearable RF modules.
High-end semiconductor packaging encompasses interconnect architectures that enable heterogeneous integration of multiple dies within a single substrate, typically employing bump pitches below 40 micrometers and through-silicon vias for vertical signal paths. These configurations address bandwidth and power-density constraints that planar scaling cannot resolve in AI processors, high-performance computing accelerators, and 5G baseband chipsets. Fan-out packaging leads volume growth by eliminating substrate cost while enabling larger die arrays, whereas 3D packaging captures the steepest margin premiums on HBM and logic-on-logic stacks. Co-Packaging of photonic engines with switch ASICs represents an emerging structural segment where supply scarcity currently outstrips foundry readiness.
US export controls administered by the Bureau of Industry and Security restrict packaging equipment shipments to certain Chinese fabs, redirecting capital expenditure toward Malaysia and South Korea. Japan's METI subsidizes domestic advanced packaging consortia under its semiconductor revitalization framework, while the EU Chips Act conditions facility funding on REACH-compliant material flows and local content thresholds. Stakeholders must monitor how substrate material qualification timelines interact with Co-Packaging optical integration roadmaps.
Market Dynamics
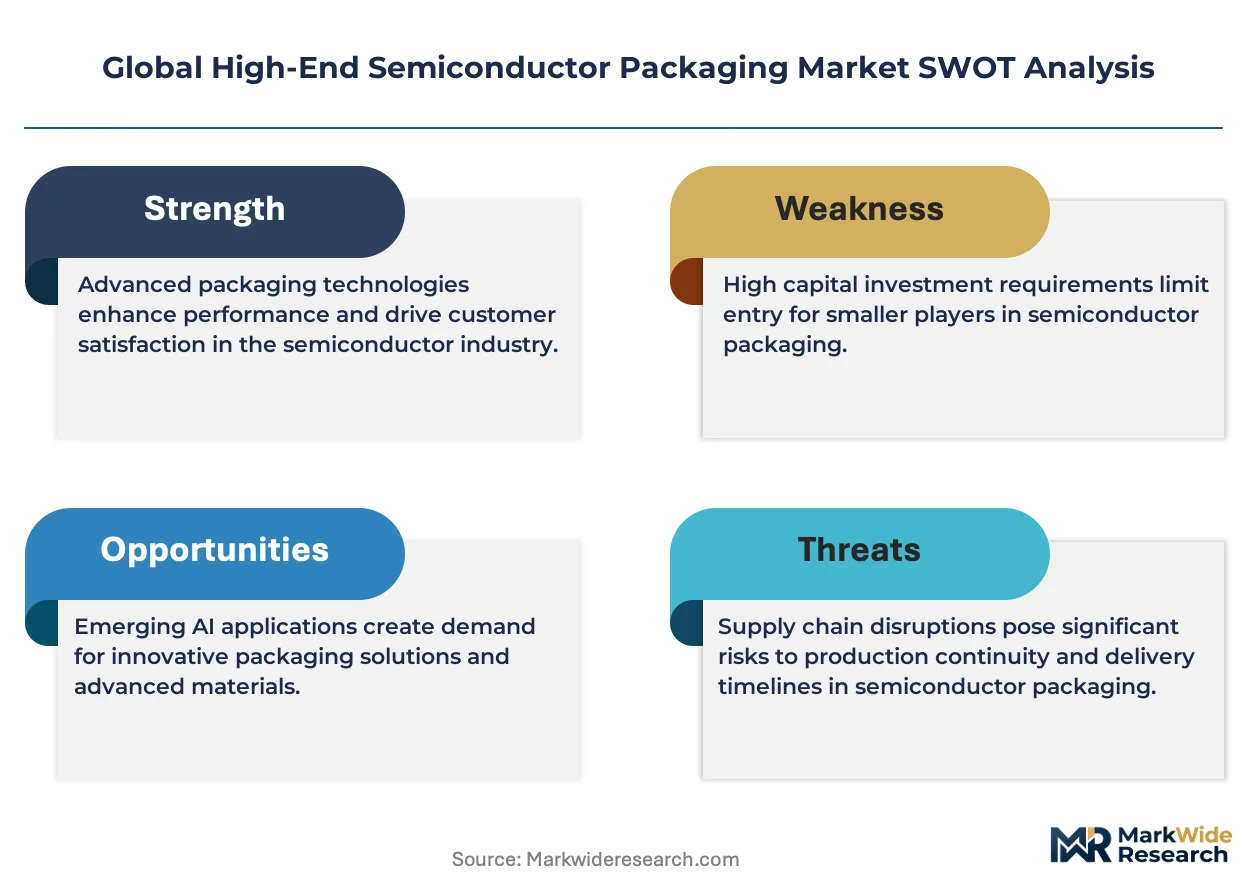
CoWoS capacity scarcity is redistributing margin pools across the advanced packaging value chain as hyperscale AI accelerator demand outstrips Taiwan's substrate-limited throughput.
Growth Catalysts
- US CHIPS and Science Act:Direct subsidies for domestic advanced packaging fabs are pulling capital expenditure toward Arizona and Texas, creating captive supply for defense-qualified AI processors.
- Heterogeneous integration:Chiplets displace monolithic die architectures in high-performance computing, multiplying interconnect density requirements per socket.
- Malaysia:Penang and Kulim backend clusters capture wirebond-to-flip-chip conversion as Chinese fabs face equipment access restrictions.
Market Restraints
- ABF substrate shortage:Mitsui Mining and Smelting plus Unimicron control 70% of ultra-thin build-up layer capacity, creating single-source dependency for 2.5D interposers.
- US BIS export controls:Restrictions on die bonder and flip-chip equipment shipments to specific Chinese entities fragment supply chain coordination.
- Organic substrate thermal limits:CTE mismatch above 150°C junction temperatures constrains power density in AI training accelerators.
Strategic Opportunities
- Vietnam:Bac Ninh and Hai Phong industrial zones attract Intel and Amkor expansion for smartphone SiP and automotive radar module assembly.
- Co-Packaging optics:Integration of silicon photonics engines with switch ASICs opens new margin pools in data center interconnects.
- Japan METI subsidies:Domestic 2.5D/3D packaging consortia receive funding under the semiconductor revitalization framework, targeting HBM-on-logic stacks.
Industry Challenges
- Process engineer scarcity:TSV etch and hybrid bonding yield optimization require specialists concentrated in Hsinchu and Seoul, constraining Malaysia and Vietnam facility ramp rates.
- Cleanroom capex intensity:Class 10,000 environments for fan-out wafer-level packaging demand $500M+ per greenfield site, extending payback periods.
- REACH material qualification:EU Chips Act funding requires compliant underfill and molding compound substitutions, delaying substrate tape-out schedules by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High-End Semiconductor Packaging Market |
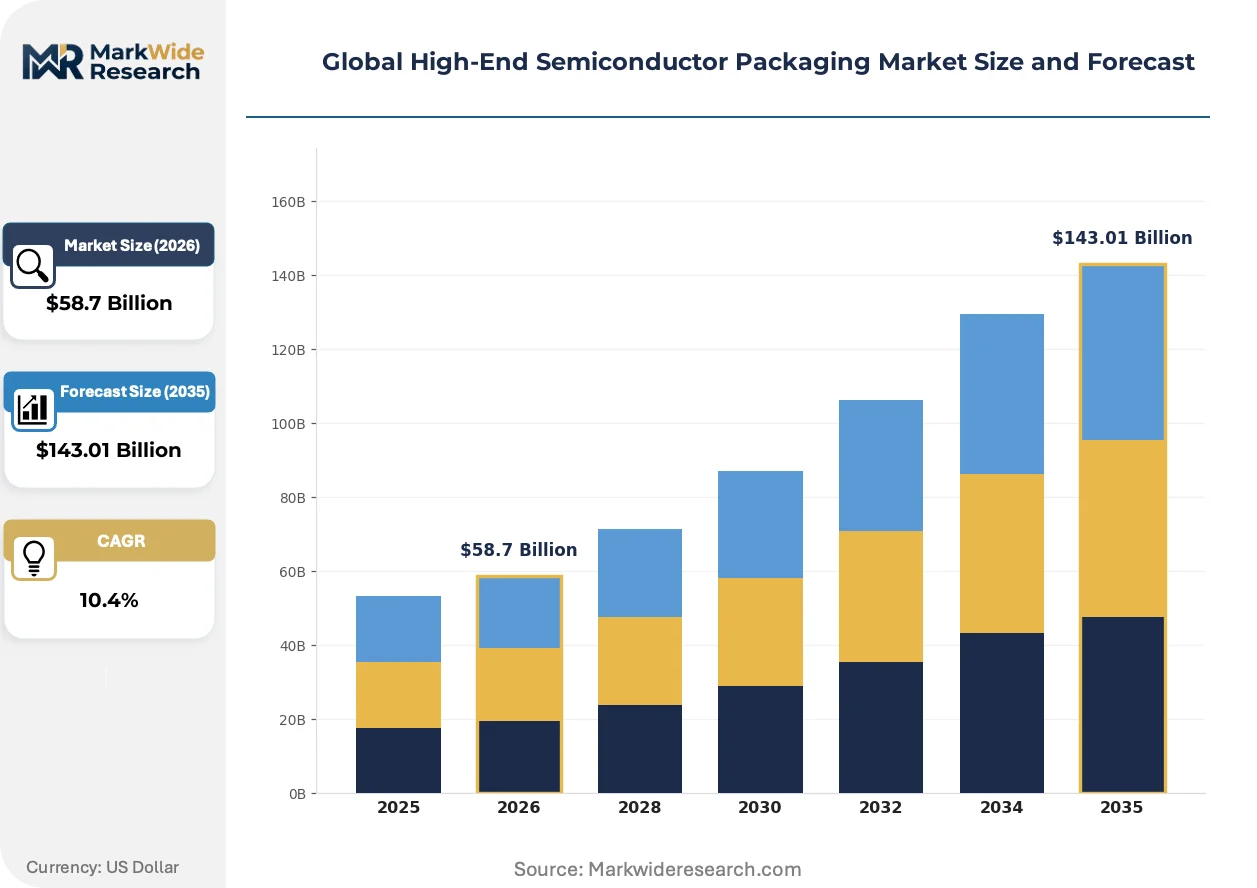
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $143.01 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: System in Package, Wafer Level Package, Flip Chip, Ball Grid Array, Chip Scale Package Technology: 3D Packaging, Fan-Out Packaging, Through Silicon Via, Embedded Die, Co-Packaging Application: Consumer Electronics, Aerospace Systems, Telecommunications, Industrial Automation, Military Defense End User: OEMs, Foundries, Design Houses, Assembly & Testing Companies, Fabless Companies |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, Samsung Electronics, ASE Technology Holding Co., Ltd, Amkor Technology, Intel Corporation, JCET Group, Powertech Technology, Siliconware Precision Industries, ChipMOS Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High-End Semiconductor Packaging Market Shifts & Advancements
Advanced packaging roadmaps are converging on hybrid bonding and panel-level fan-out as the primary vectors for cost reduction and interconnect density scaling.
Hybrid bonding is hybridizing copper-to-copper direct interconnect at sub-10 micrometer pitch, eliminating solder microbumps entirely. Apple and AMD have adopted this for 3D V-Cache and mobile application processors since 2022. The technology is hybridizing memory-logic stacking economics, compressing HBM4 cost structures toward mainstream GPU adoption.
Japan's METI has allocated subsidy pools specifically for panel-level fan-out R&D consortia targeting 600mm square substrates, displacing round wafer constraints on die placement efficiency. Equipment suppliers in Nagoya and Osaka are qualifying laser debonding and compression molding tools for this format. Automotive radar and 5G mmWave modules are the first volume applications, with European tier-1 suppliers piloting qualification batches.
Hyperscale procurement teams now mandate CoWoS-equivalent capacity reservations 18-24 months ahead of silicon tape-out, compressing traditional spot-market substrate purchasing cycles. NVIDIA and Google have secured multi-year foundry allotments through 2027. This behavior is most visible in Taiwan and the US West Coast, where AI accelerator design houses cluster.
Global High-End Semiconductor Packaging Market Segmentation
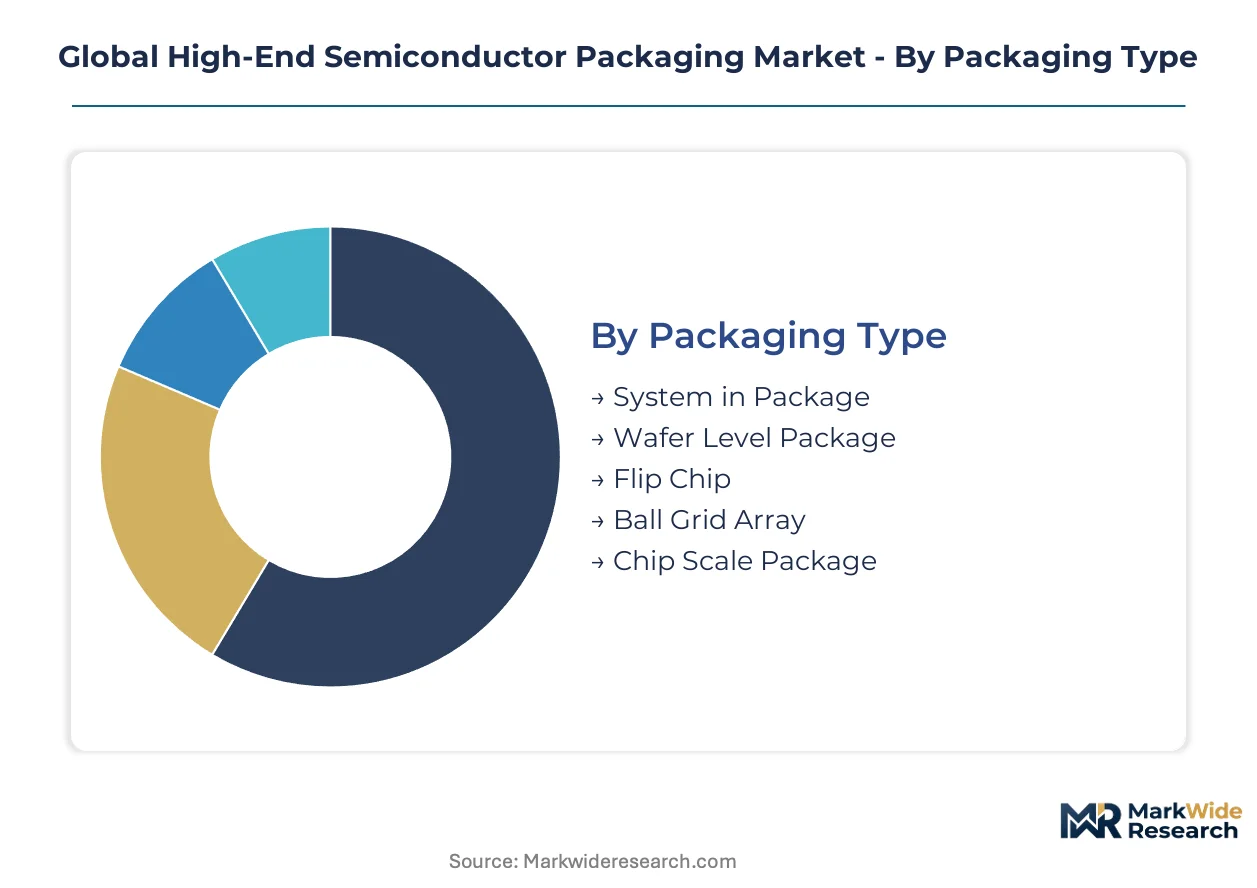
Packaging architecture selection determines thermal performance ceilings, signal integrity margins, and total cost structures across AI accelerator and 5G baseband deployments. Segmentation reveals how heterogeneous integration requirements fragment procurement patterns between high-volume smartphone modules and low-volume aerospace-qualified assemblies.
Packaging Type:
After-sales service intensity varies sharply across formats, with System in Package demanding dedicated field application engineering support while Ball Grid Array relies on standardized reliability documentation.
- System in Package:Multi-die integration within a single molded substrate combines logic, memory, and passive components for smartphone RF front-ends and wearable health monitors. Apple and Samsung procurement teams specify SiP for space-constrained designs in Cupertino and Seoul, though substrate warpage control limits yield at sub-10mm form factors.
- Wafer Level Package:Redistribution layers applied directly to singulated dies eliminate leadframe and substrate costs, enabling the thinnest profiles for image sensors and fingerprint modules. Taiwan's fan-out wafer-level capacity concentrates in Taichung and Tainan science parks, where ASE and TSMC backend facilities serve Qualcomm and MediaTek mobile chipset programs.
- Flip Chip:Solder bump interconnects face-down onto organic or ceramic substrates deliver superior electrical performance for high-pin-count processors.
- Ball Grid Array:Peripheral array configurations dominate FPGA and networking processor deployments with established reliability track records.
- Chip Scale Package:Near-die-size outlines suit memory and analog components where cost minimization outweighs density requirements.
By volume, Ball Grid Array leads. By growth pace, System in Package is ahead.
Technology:
Cost tier stratification separates qualification-intensive 3D stacks from mainstream fan-out formats, with hybrid bonding commanding 4-5x capital intensity per wafer start.
- 3D Packaging:Vertical die stacking through microbumps or hybrid bonding enables HBM memory cubes and logic-on-logic configurations for NVIDIA AI training accelerators. TSMC's CoWoS-S and CoWoS-L flows in Hsinchu and Taichung face 18-month order backlogs from hyperscale data center operators, constraining supply for AMD and Broadcom chiplet roadmaps.
- Fan-Out Packaging:Reconstituted wafer processing eliminates substrate cost while accommodating larger die footprints than traditional WLCSP, with panel-level formats targeting 600mm square substrates under Japan METI subsidy programs. Nagoya equipment consortia qualify compression molding tools for automotive radar modules destined for European tier-1 suppliers.
- Through Silicon Via:Vertical interconnects through silicon substrates enable the highest bandwidth density for memory-logic integration.
- Embedded Die:Active components buried within PCB or substrate cores suit power module and automotive inverter applications.
- Co-Packaging:Photonic engine integration with switch ASICs targets data center interconnect scaling, though foundry readiness lags design house roadmaps.
By installed base, Fan-Out Packaging leads. By margin expansion, 3D Packaging is climbing the fastest.
Application:
Customer type fragmentation separates high-volume smartphone procurement from defense-qualified traceability requirements, with aerospace systems demanding lot-level material genealogy.
- Consumer Electronics:Smartphone, tablet, and wearable volumes drive fan-out wafer-level and SiP capacity absorption, with annual flagship cycles compressing packaging development timelines to 12-18 months. Vietnam's Bac Ninh and Hai Phong industrial zones capture Intel and Amkor expansion for mid-range handset module assembly.
- Telecommunications:5G baseband and mmWave transceiver packaging requires sub-6GHz and FR2 frequency optimization, with thermal cycling reliability specifications exceeding consumer grades. Malaysia's Penang backend clusters convert wirebond capacity to flip-chip for Ericsson and Nokia radio unit programs facing US BIS equipment access restrictions on Chinese alternatives.
- Aerospace Systems:Radiation-hardened and extended-temperature qualifications impose 24-36 month certification cycles with limited supplier pools.
- Industrial Automation:Long-life reliability requirements favor ceramic substrate and hermetic sealing formats.
- Military Defense:Trusted foundry and packaging mandates restrict supply chains to US, UK, and qualified allied facilities.
By shipment volume, Consumer Electronics leads. By qualification timeline extension, Aerospace Systems is expanding most quickly.
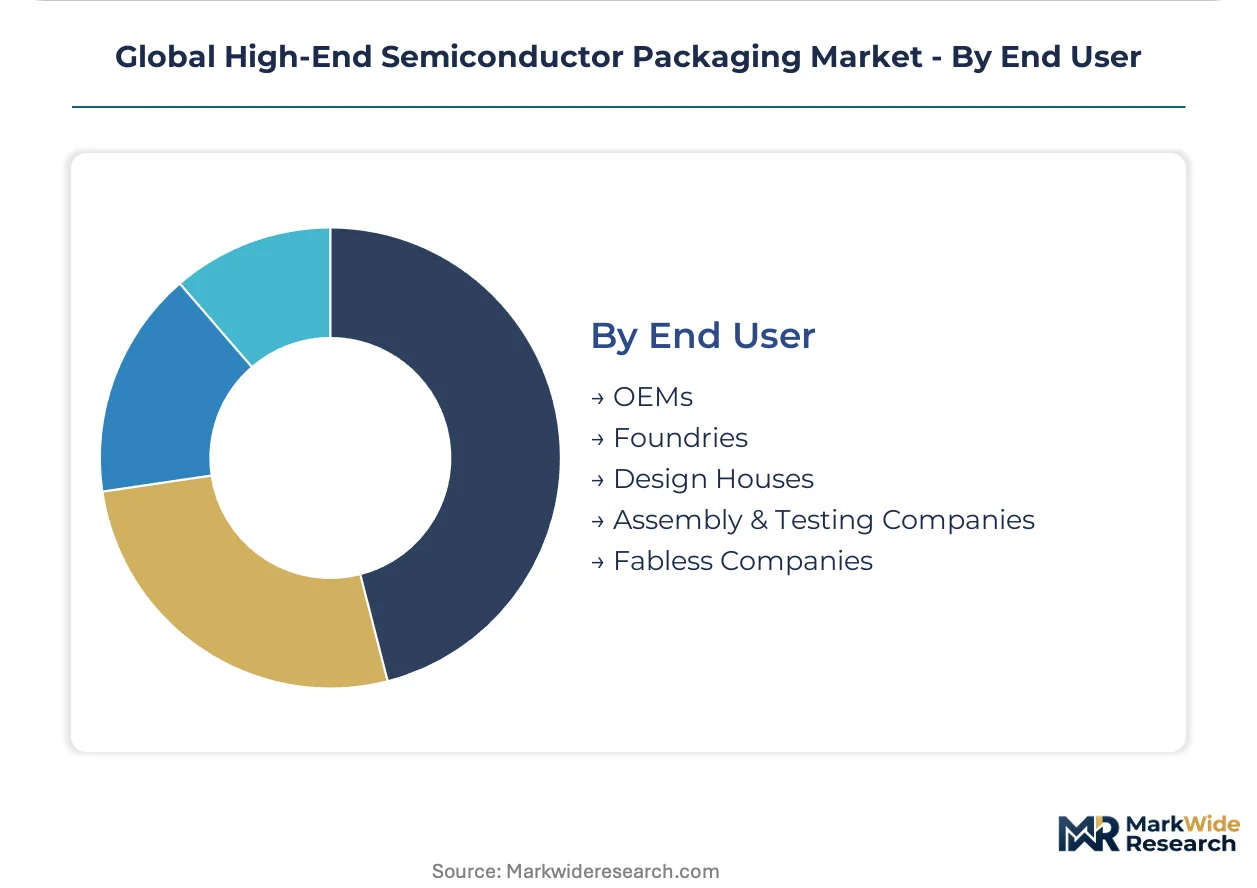
End User:
Supply concentration tilts toward foundry-captive packaging for leading-edge nodes, while OSATs compete at mature technology generations.
- Foundries:TSMC, Samsung, and Intel internalize CoWoS, EMIB, and Foveros flows for advanced node customers, capturing margin pools unavailable to merchant packaging houses. Taiwan's substrate-limited CoWoS throughput has redistributed AI accelerator assembly commitments toward Intel's New Mexico and Oregon packaging facilities under US CHIPS Act subsidies.
- Assembly & Testing Companies:ASE, Amkor, and JCET dominate outsourced flip-chip, wirebond, and test services, with Malaysia and Vietnam capturing backend expansion as Chinese fabs face equipment shipment restrictions. Penang's Kulim Hi-Tech Park hosts ASE's largest advanced packaging site outside Taiwan.
- OEMs:Apple and Samsung captive packaging teams specify proprietary SiP architectures for flagship differentiation.
- Design Houses:Fabless chiplet architects coordinate packaging co-design with foundry and OSAT partners.
- Fabless Companies:NVIDIA, AMD, and Broadcom procurement teams secure multi-year CoWoS allotments through 2027.
By capacity ownership, Assembly & Testing Companies leads. By technology access, Foundries is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Taiwan and South Korea deploy advanced packaging predominantly for AI accelerators and HBM memory cubes. The United States and Germany concentrate capacity on defense-qualified and automotive radar applications with stricter traceability mandates.
United States
Hyperscale data center operators in Arizona and Texas drive CoWoS-equivalent capacity reservations through 2027. The CHIPS and Science Act channels direct subsidies toward domestic advanced packaging fabs in New Mexico and Oregon. Intel's packaging facilities in these states capture redirected AI accelerator assembly commitments as Taiwan substrate constraints persist.
Taiwan
TSMC's CoWoS monopoly in Hsinchu and Taichung commands pricing power on AI chiplet assemblies for NVIDIA and AMD roadmaps. The National Development Council coordinates substrate material qualification timelines with foundry expansion permits. ASE Technology operates its largest advanced packaging site outside Hsinchu proper in Taichung's science park corridor.
South Korea
Samsung Electronics anchors HBM stacking capacity in Pyeongtaek and Hwaseong for internal GPU and external hyperscale supply. METI-style industrial policy through the Ministry of Trade, Industry and Energy subsidizes domestic 2.5D/3D packaging consortia targeting logic-on-memory integration. Seoul's concentration of TSV etch specialists constrains rival facility ramp rates in Southeast Asia.
Malaysia
Penang and Kulim backend clusters capture wirebond-to-flip-chip conversion as Chinese fabs face US BIS equipment access restrictions. The Malaysian Investment Development Authority grants tax incentives for advanced packaging equipment imports. ASE's Kulim Hi-Tech Park facility represents the largest OSAT footprint outside Taiwan proper.
Japan
Automotive radar and 5G mmWave module demand from Nagoya and Osaka equipment consortia pilots panel-level fan-out qualification batches. METI allocates subsidy pools specifically for 600mm square substrate R&D under the semiconductor revitalization framework. Kyushu's legacy packaging base reorients toward hybrid bonding tool qualification for memory-logic stacking economics.
Global High-End Semiconductor Packaging Market Competitive Landscape
Capability concentration sits with foundry-captive tiers; scale advantage sits with merchant OSAT networks. The market structures around three distinct tiers: integrated device manufacturers with in-house advanced packaging flows, pure-play foundries monetizing CoWoS and EMIB capacity monopolies, and outsourced assembly houses competing on flip-chip and SiP turnaround times. Dominant competitive moves include multi-year capacity reservation contracts with hyperscale procurement teams and geographic diversification into Malaysia and Vietnam to circumvent equipment shipment restrictions.
Within the foundry-captive tier, Taiwan Semiconductor Manufacturing Company and Samsung Electronics occupy positions defined by substrate-limited throughput and HBM stacking integration respectively. ASE Technology Holding Co., Ltd anchors the merchant OSAT archetype through SiP dominance in smartphone RF modules. These three entities exemplify how technology access and scale specialization partition margin pools across the value chain.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| Samsung Electronics |
| ASE Technology Holding Co., Ltd |
| Amkor Technology |
| Intel Corporation |
| JCET Group |
| Powertech Technology |
| Siliconware Precision Industries |
| ChipMOS Technologies |
| Others |
Supply & Pricing Matrix
Mitsui Mining and Smelting plus Unimicron control seventy percent of ultra-thin ABF substrate capacity, anchoring margin capture at the interposer tier while downstream OSATs absorb yield risk. This concentration feeds pricing power asymmetry between substrate suppliers and packaging houses across CoWoS and EMIB flows.
Pricing Analysis
Long-term offtake contracts dominate hyperscale procurement, with NVIDIA and Google securing multi-year CoWoS reservations through 2027. Price differentiation rests on bump pitch density and thermal performance certification, with hybrid bonding commanding four-to-five-fold capital intensity premiums over fan-out formats. Cost compression in mainstream flip-chip tiers is intensifying because Malaysia and Vietnam capacity expansion adds throughput without matching Hsinchu yield expertise. Smartphone OEMs exhibit highest price sensitivity, while AI accelerator design houses prioritize performance over unit economics.
Supply Chain Analysis
ABF resin, bismaleimide-triazine laminates, and sputtered copper seed layers feed from Japanese chemical consortia and Taiwanese copper foil mills. Geographic supply concentration centers on Taiwan, South Korea, and Japan for front-end interposer fabrication, with Malaysia and Vietnam capturing backend assembly expansion. Single-source vulnerability runs through substrate material qualification timelines that lag Co-Packaging optical integration roadmaps by six-to-twelve months. Distribution runs through foundry-direct channels for advanced nodes and merchant OSAT networks for mature packaging tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on process engineer scarcity and regulatory entrenchment through trusted foundry certification. Switching costs lock hyperscale customers into eighteen-to-twenty-four month capacity reservation cycles.
For Market Incumbents: Insulate CoWoS pricing power through captive substrate partnerships with Mitsui Mining and Unimicron, while expanding hybrid bonding yield expertise ahead of HBM4 ramps. ASE Technology should deepen backward integration into ABF laminate supply to offset margin pressure from Taiwan substrate constraints. Priority investment targets TSV etch tool qualification in Penang and Kulim to deflect emerging Vietnamese competition. For New Entrants and Emerging Players: Automotive radar module assembly in Vietnam's Bac Ninh industrial zones represents the most penetrable entry point, given Intel and Amkor expansion validates local infrastructure without saturating specialist labor pools. Panel-level fan-out equipment qualification for 600mm square substrates under Japan METI subsidy programs offers second-mover advantage in automotive 5G mmWave packaging. Go-to-market positioning should emphasize REACH-compliant material flows to capture EU Chips Act funding-conditioned procurement. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated packaging specialists with captive substrate access and defense-qualified facility certification. Long-term viability hinges on five-to-ten year visibility into hyperscale AI accelerator capex cycles. The signal to watch is Co-Packaging optics readiness timelines relative to silicon photonics engine design house roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | TSMC and Samsung capture HBM4 stacking economics ahead of mainstream GPU adoption curves. |
| Substrate Backward Integration | ASE Technology reduces ABF interposer cost exposure through Unimicron partnership structures. |
| Defense-Qualified Facility Certification | Intel's New Mexico and Oregon sites secure US CHIPS Act subsidies for trusted foundry packaging. |
| Panel-Level Fan-Out R&D Consortium | Japan METI funding accelerates 600mm square substrate qualification for automotive radar modules. |
| Co-Packaging Optics Integration | Photonic engine-switch ASIC integration opens data center interconnect margin pools ahead of foundry readiness. |
Research Methodology
Cross-validation between foundry capex disclosures and OSAT utilization rates anchors the qualitative findings on capacity tightness. Primary interviews with packaging process engineers, substrate procurement managers, hyperscale data center infrastructure leads, and semiconductor equipment sales directors combined with secondary validation from Bureau of Industry and Security export control filings, METI subsidy announcements, and EU Chips Act funding condition documents. Bottom-up die count forecasts and top-down packaging revenue triangulation resolved segment-level sizing.
Calibration against historical CoWoS order backlog patterns and HBM shipment data refined growth trajectory assumptions across the analysis window. Segmentation dimensions modeled include packaging architecture, interconnect technology, application vertical, and end-user type. CAGRs derived from slope-intercept fitting of capacity expansion announcements against hyperscale reservation timelines. Forecast inputs incorporated TSV etch yield learning curves and ABF substrate capacity build-out schedules.
Practitioners should monitor Bureau of Industry and Security export control expansion and EU REACH material qualification timeline extensions for early signals of supply chain disruption. Forecasts embed assumptions on substrate supplier concentration persistence and hybrid bonding adoption velocity. Cross-checking against SEMI equipment billings data and foundry utilization rate reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market