
 Bakery Mixes Market | 2026-2036
Bakery Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Mixes Market Analysis
Buyer concentration among industrial bakers is shifting as large commercial operations consolidate procurement and smaller artisan bakeries fragment across specialty niches. General Mills leverages its milling infrastructure and brand portfolio to anchor supply relationships with major foodservice distributors. Puratos Group differentiates through technical service teams that embed with industrial customers to customize fermentation and texture systems. Kerry Group competes by extending its clean-label ingredient expertise into reduced-sodium and enzyme-based mix formulations.
Bakery mixes are pre-blended combinations of flour, leavening agents, emulsifiers, and functional ingredients designed for reconstitution with water, eggs, or fat to produce consistent baked goods. These formulations typically specify hydration ratios, mixing times, and proofing parameters to ensure batch uniformity across varying equipment and operator skill levels. Cake mixes occupy the largest value share within product type segmentation, while bread mixes capture accelerating demand from in-store supermarket bakeries seeking operational simplicity. Professional bakers represent the fastest-growing end-user segment as hospitality chains outsource component production to reduce kitchen labor and capital requirements.
FDA oversight of sodium reduction targets and GRAS substance reviews shapes formulation decisions for US-manufactured mixes, while EFSA assessments of food enzymes and additives govern European product registrations. BIS certification requirements in India and GB standards enforcement by SAMR in China create divergent compliance pathways that regional producers must navigate. Stakeholders should monitor regulatory divergence on clean-label definitions and enzyme approvals, as these will determine which formulations achieve cross-border scale and which remain trapped in single-market production.
Market Dynamics
Industrial bakeries are consolidating procurement power while demanding clean-label reformulations, compressing margins for mix suppliers who must simultaneously absorb wheat price volatility and fund R&D for sodium-reduced, additive-free formulations.
Growth Catalysts
- FDA sodium reduction targets:The FDA's voluntary sodium reduction guidelines are forcing reformulation investments that create competitive differentiation for compliant suppliers. Industrial bakeries prioritize partners with validated reduced-sodium systems.
- In-store supermarket bakery expansion:Retailers operating in-store baking operations are outsourcing component production to reduce labor costs and equipment footprints. Bread mixes enable consistent output with minimal skilled labor.
- Enzyme-based texture systems:Advances in enzyme technology are replacing chemical emulsifiers and conditioners, satisfying clean-label demand while maintaining dough stability and shelf life performance.
Market Restraints
- Wheat supply concentration:North American wheat milling capacity concentrates among a handful of regional processors, exposing mix manufacturers to input price shocks and supply allocation constraints during crop shortfalls.
- EFSA additive approval timelines:European novel ingredient registrations face extended safety assessment periods, delaying clean-label product launches and trapping formulations in single-market production.
- Fresh-baked substitute competition:Par-baked and frozen dough systems compete directly with dry mixes for foodservice accounts, offering comparable labor savings with superior aroma and texture profiles.
Strategic Opportunities
- India BIS certification pathway:India's formalizing food safety standards create first-mover advantage for suppliers establishing localized production and technical service infrastructure ahead of enforcement tightening.
- Plant-based egg replacement convergence:Binding proteins from legume and algae sources combined with enzymatic strengthening systems are unlocking vegan cake and pastry mix categories previously limited by structural integrity failures.
- Direct-to-artisan digital channels:E-commerce platforms and subscription models are bypassing traditional foodservice distribution to reach small-batch bakeries seeking specialty fermentation and heritage grain formulations.
Industry Challenges
- Clean-label formulation expertise scarcity:Industrial mix development requires cross-functional knowledge spanning cereal chemistry, enzyme kinetics, and sensory science that outpaces current technical training pipeline output.
- Legacy equipment compatibility:Reformulated mixes with altered hydration profiles and fermentation behaviors require validation across customer-installed base of mixers, proofers, and ovens with varying age and calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Mixes Market |
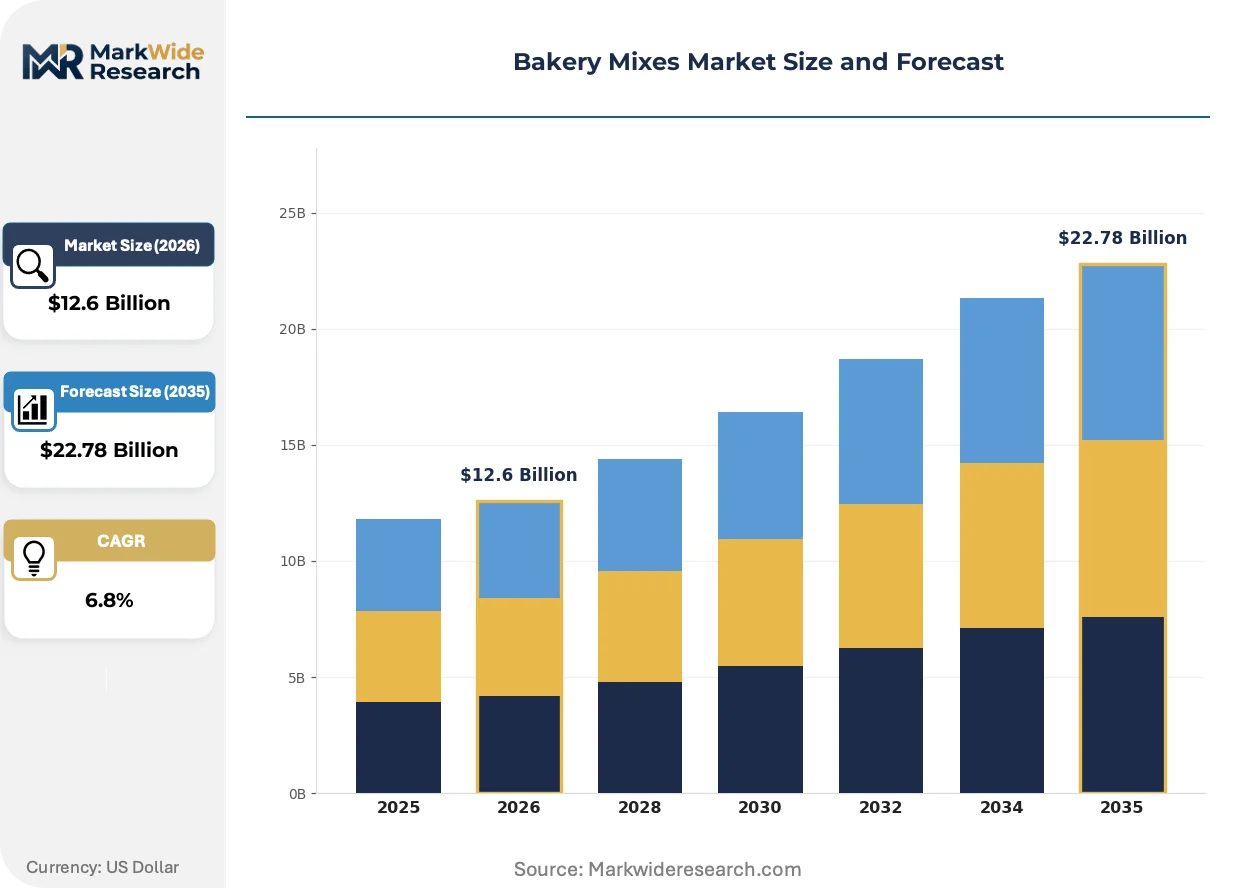
| Market Size in 2026 | $12.6 Billion |
| Market Size in 2035 | $22.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cake Mixes, Cookie Mixes, Bread Mixes, Pancake Mixes Packaging Type: Bags, Boxes, Pouches, Jars End User: Home Bakers, Professional Bakers, Industrial Bakers, Retail Outlets Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | General Mills, ADM (Archer Daniels Midland), Cargill, Puratos Group, Associated British Foods, Lesaffre, Bakels Worldwide, Kerry Group, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Mixes Market Emerging Trajectories
Active fermentation management systems and precision dosing hardware are displacing static mix formulations, while regulatory pressure on sodium and additive content accelerates ingredient innovation cycles across industrial and artisan segments.
Precision fermentation-derived proteins are rewriting protein functionality in bakery applications. Industrial bakeries in the United States and Germany are piloting these ingredients at commercial scale to replace chemical strengtheners. The technology is compressing the gap between clean-label marketing claims and industrial process tolerance requirements.
EFSA's systematic re-evaluation of food enzymes and emulsifiers is forcing preemptive formulation audits across European production facilities. Manufacturers are accelerating substitution programs for additives facing scrutiny, redirecting R&D budgets toward enzyme systems and natural hydrocolloids. Cake mix categories with complex emulsifier dependencies face the steepest compliance cost escalation.
Foodservice distributors are unbundling technical service from product supply, selling formulation expertise separately from ingredient procurement. Hospitality chains in France and Japan are contracting directly with enzyme suppliers and specialty millers, fragmenting traditional supplier relationships. This disintermediation is most advanced among mid-sized bakery chains with in-house technical capabilities seeking ingredient cost transparency.
Bakery Mixes Market Segmentation
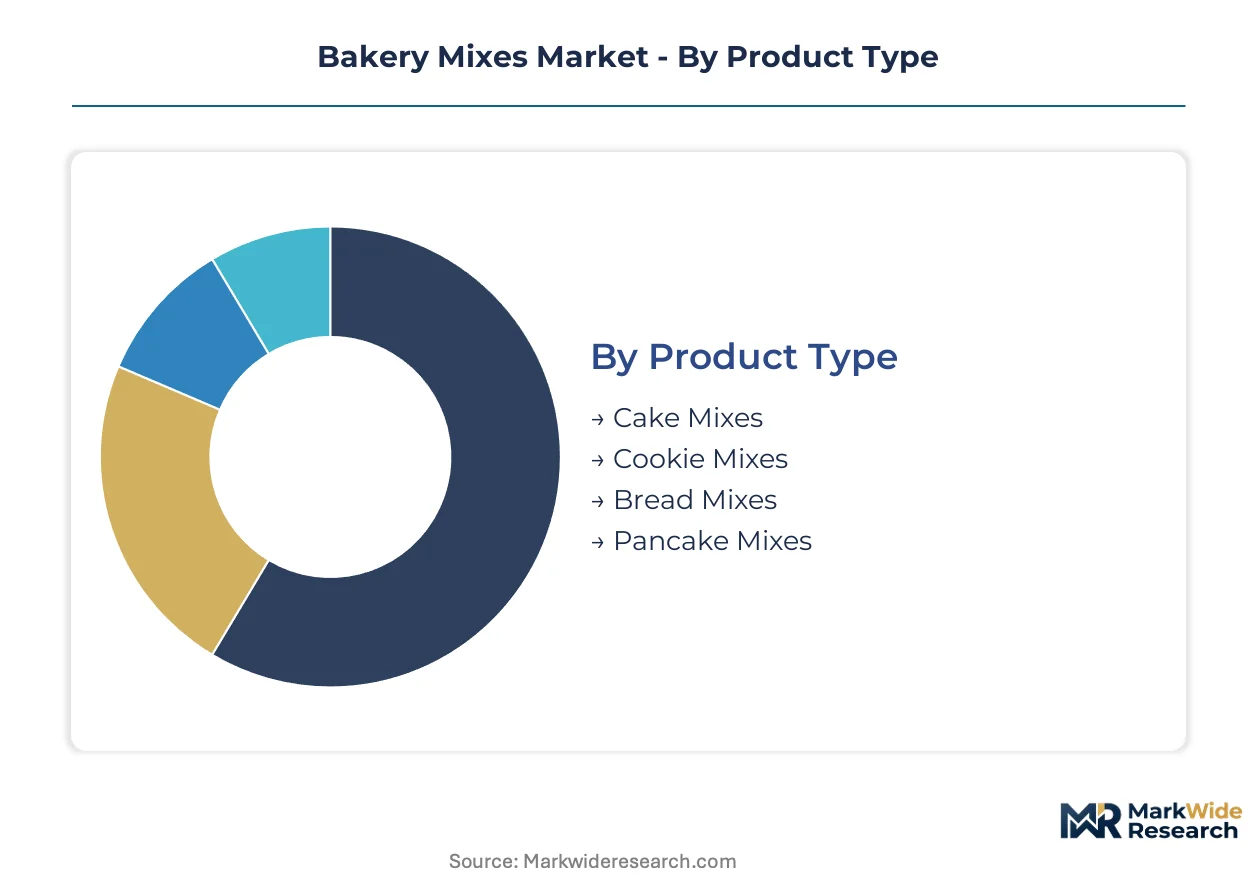
Bakery mix segmentation reflects divergent performance requirements across industrial scale and artisan precision. Volume economics favor standardized formulations for high-throughput channels, while premium tiers command specialized functionality for discriminating end-users.
Product Type:
Cake mixes dominate value capture through premium positioning, while bread mixes accelerate on foodservice outsourcing trends.
- Cake Mixes:Pre-formulated blends incorporating emulsifiers, leavening systems, and flavor carriers optimized for aeration and crumb structure. Demand concentrates in United States retail and foodservice channels where convenience expectations are highest, though EFSA emulsifier scrutiny is forcing reformulation investments.
- Bread Mixes:Fermentation-managed formulations specifying hydration ratios, proofing parameters, and enzyme-based conditioning systems. In-store supermarket bakeries across the United States and Germany are scaling procurement to reduce skilled labor dependency and equipment footprints.
- Cookie Mixes:Shortening-stabilized blends with controlled spread characteristics for consistent dimensional output.
- Pancake Mixes:Hydration-tolerant formulations with extended batter stability for foodservice batch preparation.
Mature deployment sits with cake mixes. Newer deployment is concentrated in bread mixes.
Packaging Type:
Industrial procurement favors bulk formats with dosing compatibility, while retail channels demand portion-controlled units with shelf-impact differentiation.
- Bags:Multi-wall paper or polymer constructions with moisture barriers and tear-resistant sealing for high-volume industrial transfer. Professional bakeries in France and Japan specify bag formats compatible with pneumatic conveying systems.
- Boxes:Rigid paperboard with printed branding surfaces and stack-stability engineering for retail shelf presence. United States supermarkets prioritize box formats for vertical merchandising and theft deterrence.
- Pouches:Flexible laminate constructions with reseal features for portion-controlled home baking segments.
- Jars:Rigid plastic or glass with wide-mouth access for premium specialty mixes targeting gift and artisan market positioning.
Volume concentration favors bags. Premium differentiation concentrates in jars.
End User:
Procurement authority is fragmenting as hospitality chains internalize technical capabilities and outsource component production.
- Industrial Bakers:Large-scale commercial operations with automated mixing, proofing, and baking lines requiring batch-to-batch coefficient of variation below 3%. These buyers are consolidating supplier relationships and demanding validated reduced-sodium systems compliant with FDA targets.
- Professional Bakers:Hospitality chains, hotels, and independent artisan operations seeking labor reduction without quality compromise. This segment is expanding most quickly as kitchen outsourcing accelerates across France, Japan, and the United States.
- Home Bakers:Consumer households purchasing through retail channels for occasional baking occasions with minimal technical investment.
- Retail Outlets:In-store supermarket baking operations with semi-skilled staff and limited equipment flexibility seeking operational simplicity.
Established procurement patterns sit with industrial bakers. Fastest share gain is occurring among professional bakers.
Distribution Channel:
Channel selection determines margin structure and technical service intensity, with direct digital access fragmenting traditional distributor control.
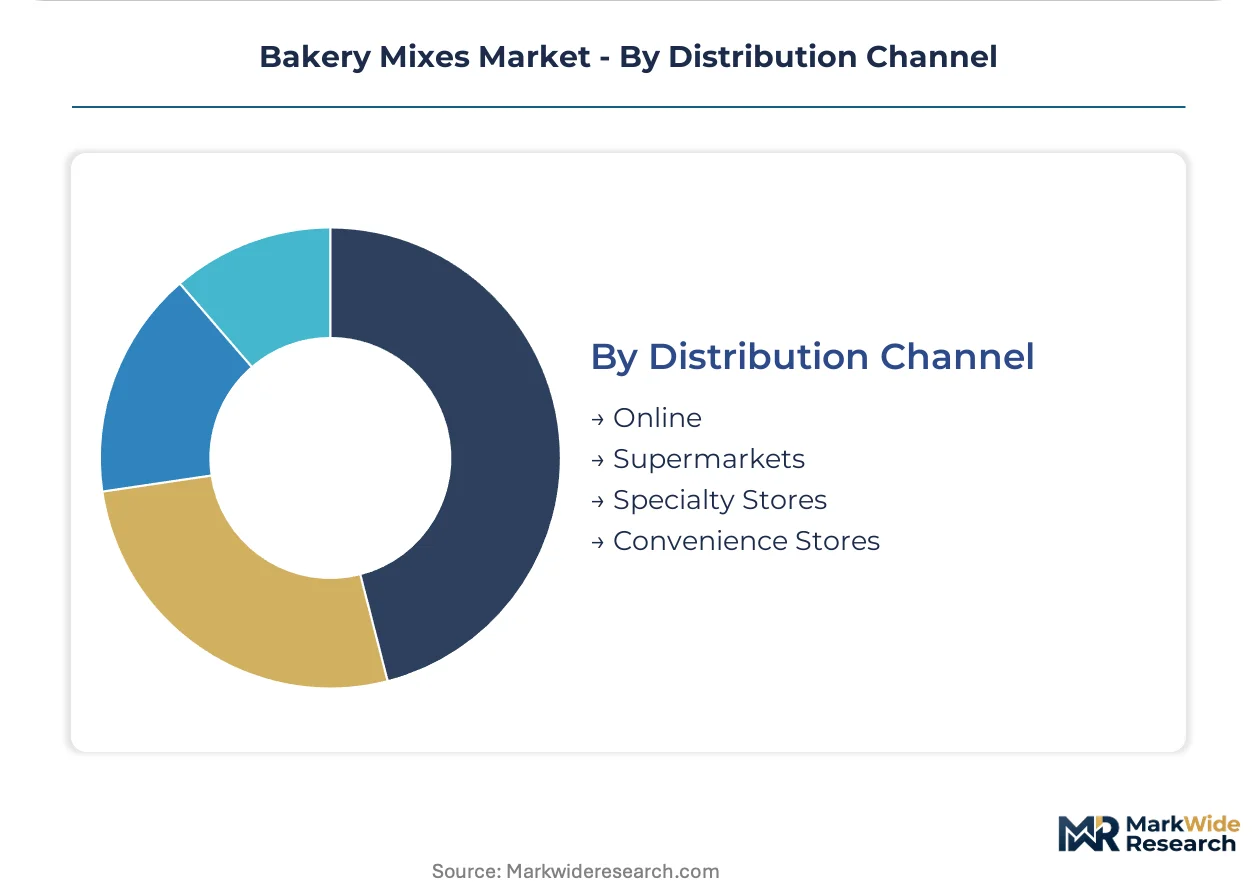
- Supermarkets:Dominant retail channel with category management discipline, promotional funding requirements, and private-label competition. United States and German retailers are expanding in-store bakery outsourcing, creating dual demand for consumer-facing and back-of-house mix procurement.
- Online:Direct-to-artisan platforms and subscription models bypassing foodservice distributors to reach small-batch bakeries with specialty fermentation and heritage grain formulations.
- Specialty Stores:Curated retail environments with premium positioning and educated staff supporting complex product explanation.
- Convenience Stores:Limited assortment, high-velocity formats targeting impulse and emergency replacement purchasing.
Volume infrastructure sits with supermarkets. Channel innovation is concentrating online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery procurement concentrates in the United States, where commercial-scale operations and in-store supermarket baking drive volume demand. Regulatory divergence between FDA sodium targets and EFSA additive scrutiny creates distinct formulation requirements across major production centers.
United States
Large-scale commercial bakeries and foodservice chains dominate procurement, with in-store supermarket baking operations scaling bread mix volumes to reduce skilled labor dependency. FDA voluntary sodium reduction guidelines are forcing reformulation investments, prioritizing suppliers with validated reduced-sodium systems. Chicago and Minneapolis-St. Paul anchor industrial mix production, with technical service teams embedded at major milling complexes.
Germany
Professional hospitality chains and industrial bakers are outsourcing component production to compress kitchen labor costs and equipment footprints. EFSA systematic re-evaluation of food enzymes and emulsifiers is accelerating substitution programs for additives facing regulatory scrutiny. The Munich-Stuttgart corridor hosts precision fermentation pilot facilities testing enzyme-based texture systems at commercial scale.
France
Mid-sized bakery chains with in-house technical capabilities are contracting directly with enzyme suppliers and specialty millers, fragmenting traditional distributor relationships. ANSM and DGCCRF enforcement of clean-label claims is tightening formulation transparency requirements. Lyon and Paris basin operations concentrate artisan-industrial hybrid production, blending heritage grain formulations with automated processing.
Japan
Hospitality chains are driving professional baker segment expansion through kitchen outsourcing and component standardization. METI guidance on food additive labeling is reshaping import mix registration requirements for European suppliers. Osaka-Kobe industrial zones concentrate technical service infrastructure supporting enzyme-based conditioning system adoption.
India
Formalizing food safety standards under BIS certification are creating first-mover opportunities for suppliers establishing localized production ahead of enforcement tightening. FSSAI alignment with Codex standards is accelerating ingredient registration timelines for multinational mix manufacturers. Maharashtra and Gujarat host emerging industrial bakery clusters scaling procurement of pre-formulated blends for quick-service restaurant supply chains.
Bakery Mixes Market Vendor Landscape
United States producers anchor one tier; European specialists hold formulation expertise advantages in enzyme systems and clean-label architectures. Market structure tilts toward consolidated procurement relationships at the industrial tier, with fragmented specialty niches serving artisan and regional bakery segments. Three archetypes dominate: diversified milling conglomerates with captive ingredient supply, enzyme technology specialists with embedded technical service models, and regional blenders with heritage grain and fermentation customization capabilities. Competitive intensity centers on M&A-driven portfolio expansion into adjacent texture systems and strategic partnerships bridging enzyme suppliers with industrial bakery accounts.
Among diversified milling conglomerates, General Mills and ADM occupy positions exemplifying backward integration into wheat procurement and downstream formulation control. Cargill sits within the agricultural commodity processing archetype, leveraging origination infrastructure across multiple geographies. Puratos Group and Kerry Group represent the technical service-intensive tier, with enzyme-based and clean-label formulation capabilities anchoring customer stickiness in sodium-reduced and additive-free product development. Associated British Foods and Lesaffre occupy intermediate positions spanning commodity and specialty formulation segments.
| Leading Market Players |
|---|
| General Mills |
| ADM (Archer Daniels Midland) |
| Cargill |
| Puratos Group |
| Associated British Foods |
| Lesaffre |
| Bakels Worldwide |
| Kerry Group |
| Conagra Brands |
| Others |
Supply Flow & Price Mechanics
FDA voluntary sodium reduction targets gate qualified supply and premium-tier pricing access for bakery mix manufacturers, forcing reformulation investments that stratify suppliers by clean-label capability and regulatory compliance depth.
Pricing Analysis
Volume versus margin splits sharply across the bakery mixes market. High-throughput industrial bakeries command contract-based long-term offtake pricing with volume scale discounts, while artisan and specialty segments absorb premium-mid-economy pricing differentiation driven by certification level and customization depth. Pricing pressure stems from wheat commodity volatility and R&D cost absorption for enzyme-based texture systems. Industrial bakeries exhibit lowest price sensitivity due to labor cost savings from mix outsourcing, while small artisan operations show highest sensitivity to input cost fluctuations.
Supply Chain Analysis
Certification and qualification requirements gate supplier access across major production corridors. Wheat milling capacity concentrates in the United States, Germany, and India, with mix manufacturing drawing from North American and European enzyme technology clusters. Raw material dependencies span wheat, fermentation-derived proteins, and emulsifier substitutes. Single-source vulnerability runs through concentrated North American wheat processing infrastructure. Distribution runs through foodservice distributors with embedded technical service teams, though direct digital channels are fragmenting traditional control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
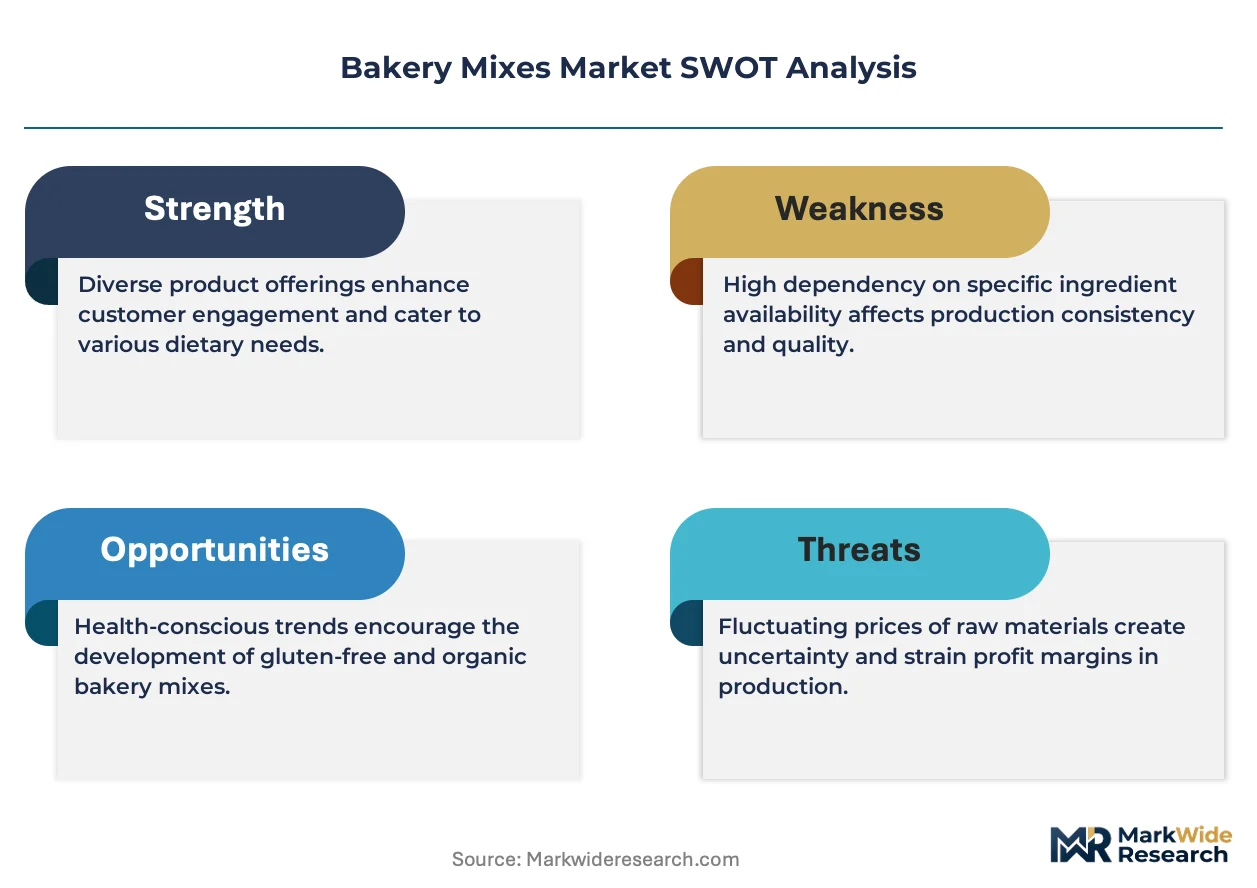
Clean-label formulation expertise scarcity props pricing power across the bakery mixes market, constraining qualified supply expansion and sustaining margin premiums for compliant suppliers.
For Market Incumbents: Anticipate EFSA additive approval timeline extensions and preemptively accelerate enzyme substitution programs to defend formulation leadership. Consolidate technical service infrastructure around precision fermentation partnerships to offset emerging entrant competition from enzyme specialists. Prioritize backward integration into wheat procurement to buffer commodity volatility exposure.
For New Entrants and Emerging Players: Small-batch artisan bakeries seeking heritage grain and specialty fermentation formulations represent the most penetrable white-space target. Direct-to-artisan digital channels bypass entrenched distributor relationships and unlock subscription-based recurring revenue. Plant-based egg replacement convergence in vegan cake and pastry categories offers differentiated entry with lower incumbent R&D lock-in.
For Investors and Strategic Acquirers: First commercial-scale precision fermentation protein adoption by United States or German industrial bakeries is the leading indicator that enzyme-based texture systems are crossing the manufacturing tolerance threshold. Long-term viability favors suppliers bridging clean-label marketing claims with industrial process reliability. Acquisition targets should demonstrate validated reduced-sodium systems and embedded technical service relationships with hospitality chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Commercial deployment of fermentation-derived proteins enables clean-label texture systems compliant with FDA sodium targets. |
| Technical Service Unbundling | Direct contracting between hospitality chains and enzyme suppliers fragments traditional foodservice distributor control. |
| BIS Certification Localization | First-mover production infrastructure in India captures share ahead of FSSAI enforcement tightening. |
| Direct-to-Artisan Channel Buildout | Digital platforms bypass legacy distribution to reach small-batch bakeries with specialty formulations. |
| Backward Integration into Milling | Captive wheat procurement buffers input price shocks and secures supply allocation during crop shortfalls. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with industrial bakery procurement directors, foodservice distributor category managers, enzyme supplier technical service leads, and retail bakery operations heads. FDA GRAS notifications, EFSA food enzyme assessments, BIS certification databases, and FSSAI ingredient registrations provided regulatory validation. Bottom-up volume modeling and top-down value reconciliation triangulated market sizing across product and end-user segments.
Data-stream reconciliation integrated production capacity disclosures, import-export flows, and channel shipment patterns across the analysis window. Segmentation dimensions modeled include product type, packaging format, end-user scale tier, and distribution channel structure. CAGRs derived from trend extrapolation of volume and value trajectories, calibrated against wheat price indices and enzyme technology adoption curves. Forecast inputs incorporated regulatory timeline assumptions for sodium reduction compliance and clean-label definition convergence.
Revisions become necessary when EFSA additive approval timelines extend beyond modeled assumptions or when precision fermentation protein costs fall below threshold levels for commercial bakery adoption. Forecasts reflect assumptions about industrial bakery consolidation rates and hospitality chain outsourcing intensity. A model refresh is warranted upon material change in FDA sodium reduction guideline enforcement posture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Europe Bakery Products Market
Bakery Products
Pastry Margarine Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Bread Dough Improver Market
Bakery Products
South America Ice Cream Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Bread Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Specula Market
Bakery Products
Oman Frozen Bakery Products Market