
 Asia-Pacific Bakery Products Market | 2026-2036
Asia-Pacific Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bakery Products Market Outlook
Subscription-based fresh delivery programs are shifting how bakery products reach consumers in Asia-Pacific. Yamazaki Baking leverages its refrigerated logistics network to sustain daily doorstep bread subscriptions across Japan. Britannia Industries Limited anchors its competitiveness through deep distribution into India's tier-two and tier-three cities. Grupo Bimbo differentiates by operating localized production hubs that adapt formulations to national taste preferences.
Bakery products encompass leavened and unleavened goods manufactured from flour, water, yeast or chemical leavening agents, and functional ingredients such as emulsifiers and preservatives, with moisture content typically ranging from 15% to 45% depending on category. These items serve as staple carbohydrates, convenience meal solutions, and impulse purchases across food service and retail channels. Bread maintains the largest volume share within product type segmentation, though pastries command stronger per-unit margins in urban premium channels. The end user dimension shows food service outpacing retail growth in Vietnam and Indonesia where out-of-home breakfast consumption is expanding. Distribution channel dynamics favor direct sales from industrial bakeries to chained supermarkets, squeezing traditional wholesaler margins.
Japan's Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards that mandate allergen labeling and restrict synthetic additive use in packaged breads. India's FSSAI has tightened fortification guidelines for mass-market bakery items, reshaping ingredient sourcing for pan-Asia brands. Australia's FSANZ maintains distinct processing and labeling requirements that create compliance thresholds for imported frozen dough. Stakeholders must monitor divergence between national food safety regimes and the harmonization pressures from regional trade agreements.
Market Dynamics
Subscription-based fresh delivery programs are restructuring Asia-Pacific bakery distribution, with refrigerated logistics networks now determining competitive reach rather than traditional retail shelf space. Japan's Food Sanitation Act revisions and India's FSSAI fortification mandates are simultaneously reshaping formulation requirements and compliance costs across the region.
Growth Catalysts
- Quick-service restaurant expansion:Café chains across Vietnam and Indonesia are scaling centralized bakery procurement, creating dedicated supply agreements with industrial bakers.
- Japan's Food Sanitation Act:Tighter additive disclosure requirements are accelerating clean-label reformulations, opening premium positioning for compliant domestic producers.
- Urban modern trade penetration:India's supermarket chains are displacing kirana stores in tier-two cities, consolidating purchasing power and favoring standardized packaged bread suppliers.
Market Restraints
- Wheat import dependency:Asia-Pacific bakers remain exposed to Black Sea supply volatility, with Australia and Canada as dominant alternative origins.
- Refrigerated logistics gaps:Cold chain infrastructure deficits in Indonesia's outer islands limit fresh bread distribution radius and subscription model viability.
- Technical shelf-life constraints:Clean-label formulations without calcium propionate face accelerated staling in tropical climates, compressing retail turnover windows.
Strategic Opportunities
- India's tier-three cities:Deep distribution networks into smaller urban centers remain underdeveloped, offering first-mover advantage for organized bakery brands.
- FSSAI fortification mandates:Mandatory micronutrient enrichment in mass-market bread creates technical differentiation opportunities for premix suppliers and compliant manufacturers.
- Direct-to-foodservice channels:Industrial bakeries are bypassing traditional wholesalers to supply chained supermarkets, capturing margin and demand data.
Industry Challenges
- Artisan baker skill scarcity:Traditional fermentation expertise is thinning as industrial automation displaces manual production methods across Japan and South Korea.
- Multi-jurisdiction compliance:Divergent allergen labeling between Japan's Ministry of Health, Labour and Welfare and Australia's FSANZ fragments packaging and inventory management.
- Legacy equipment retrofit costs:Existing production lines require substantial capital outlay to accommodate reduced-additive formulations and extended fermentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bakery Products Market |
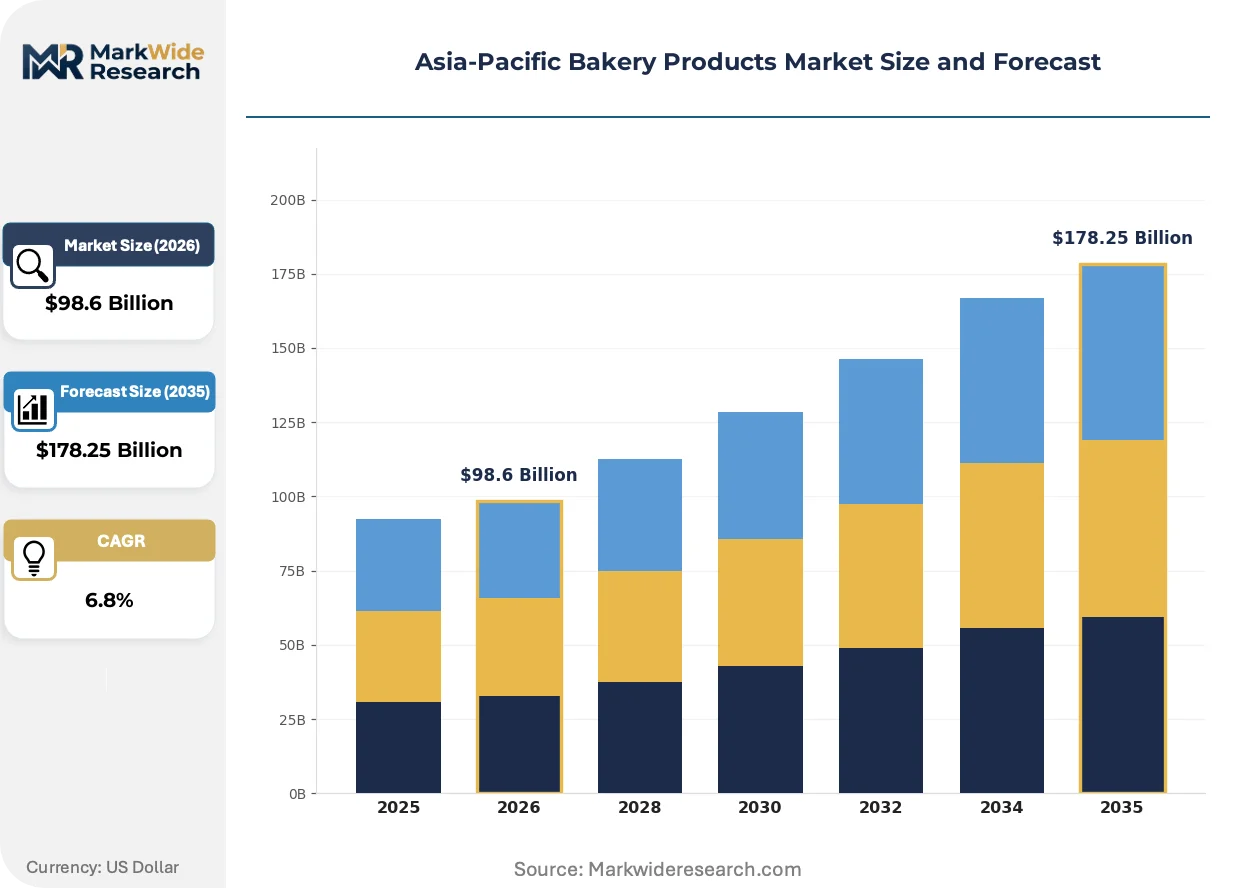
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Cookies End User: Food Service, Retail, Supermarkets, Online Stores Distribution Channel: Direct Sales, Wholesalers, Distributors, Convenience Stores Packaging Type: Flexible Packaging, Rigid Packaging, Boxes, Bags |
| Companies Covered | Yamazaki Baking, Meiji Holdings, Grupo Bimbo, President Bakery, QAF Limited, Mondelēz International, Wilmar International Limited, ITC Limited, Britannia Industries Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bakery Products Market Strategic Shifts
Digital subscription platforms and precision fermentation are converging to redefine freshness guarantees and ingredient sourcing across Asia-Pacific bakery supply chains. Three developments are compressing traditional competitive advantages.
Precision fermentation-derived proteins are converging with traditional wheat flour systems to reduce egg and dairy dependency in laminated pastries. Japanese industrial bakeries are piloting these ingredients at commercial scale, responding to allergen labeling pressures. This convergence is compressing ingredient cost volatility while opening vegan positioning in premium urban channels.
Japan's Food Sanitation Act revisions are mandating granular additive disclosure on packaged bread labels, extending to emulsifiers and preservatives previously exempt from front-panel declaration. Industrial bakers are reformulating around restricted synthetic additives, shifting toward enzyme-based shelf-life extension. Premium domestic brands are capturing margin from this compliance burden as import brands face reformulation timelines.
Breakfast consumption patterns are rotating toward out-of-home occasions in Vietnam and Indonesia, displacing home-prepared rice-based morning meals. Food service channels are capturing volume growth faster than retail, with chained cafés consolidating procurement through direct bakery contracts. This rotation is most visible in Ho Chi Minh City and Jakarta, where convenience-store bakery counters are expanding floor space allocation.
Asia-Pacific Bakery Products Market Segmentation
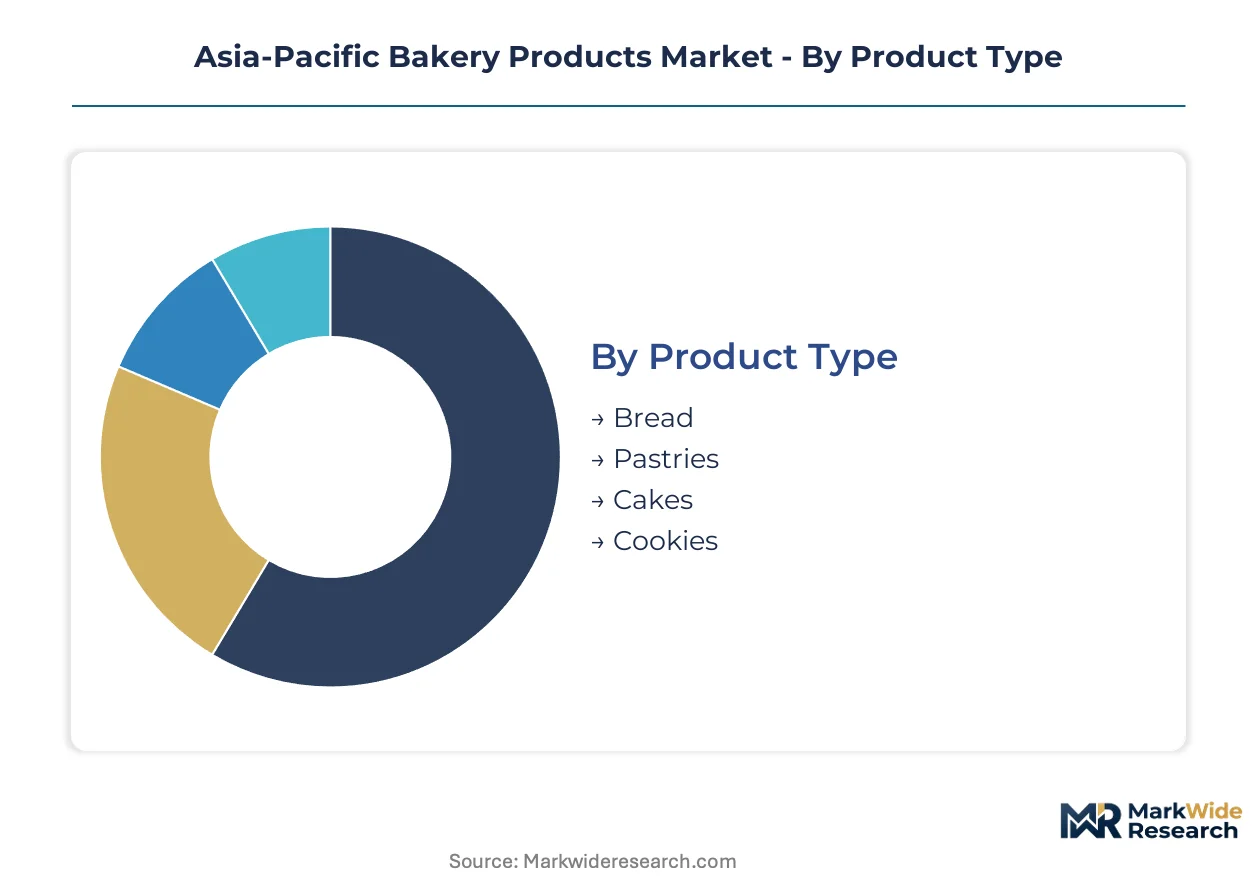
Segmentation in Asia-Pacific bakery markets determines which producers capture FSSAI fortification waivers versus Japan's Food Sanitation Act additive disclosure burdens. Product type and distribution channel choices dictate compliance costs, shelf-life engineering requirements, and refrigerated logistics investments across divergent national regulatory regimes.
Product Type:
Japan's Ministry of Health, Labour and Welfare mandates additive disclosure thresholds that vary sharply by moisture content and processing method, with bread facing stricter emulsifier labeling than dry cookies.
- Bread:Leavened goods with 35-45% moisture content require enzyme-based shelf-life extension to meet Japan's synthetic additive restrictions. Demand concentrates in Vietnam and Indonesia where out-of-home breakfast rotation from rice-based meals is accelerating food service procurement.
- Pastries:Laminated dough systems with layered fat structures command premium positioning in urban Japanese and South Korean convenience stores. Clean-label reformulation pressures are most acute here due to butter and margarine additive disclosure requirements.
- Cakes:High-moisture sponge formulations face compressed retail turnover windows in tropical climates without calcium propionate.
- Cookies:Low-moisture biscuits encounter fewer additive restrictions but compete intensely on FSSAI fortification compliance for India's mass-market penetration.
Leading the category by volume: Bread. Growing fastest: Pastries.
End User:
Cost tier stratification separates premium subscription models from mass-market retail, with food service commanding direct procurement contracts that bypass traditional wholesaler margins.
- Food Service:Chained cafés in Ho Chi Minh City and Jakarta are consolidating centralized bakery procurement through dedicated supply agreements. Direct contracts with industrial bakers capture demand data and compress distributor margins.
- Retail:India's tier-two and tier-three cities remain underdeveloped for organized bakery brands, offering first-mover advantage for deep distribution networks.
- Supermarkets:Modern trade formats in urban India are displacing kirana stores, consolidating purchasing power toward standardized packaged bread suppliers.
- Online Stores:Subscription-based fresh delivery programs require refrigerated logistics networks that determine competitive reach rather than traditional shelf space.
Volume concentration: Food Service. Steepest expansion trajectory: Online Stores.
Distribution Channel:
Supply concentration patterns favor direct industrial bakery-to-retailer relationships in markets where cold chain infrastructure gaps limit traditional wholesaler viability.
- Direct Sales:Industrial bakeries bypass wholesalers to supply chained supermarkets, capturing margin and demand data. This channel dominates where Australia's FSANZ labeling requirements create compliance thresholds that importers struggle to meet.
- Wholesalers:Traditional distribution faces margin compression as direct procurement expands, though remains entrenched in Indonesia's outer islands where refrigerated logistics gaps persist.
- Distributors:Regional fragmentation between Japan's allergen labeling and Australia's FSANZ requirements complicates inventory management for multi-jurisdiction operators.
- Convenience Stores:Floor space allocation for bakery counters is expanding in Jakarta and Ho Chi Minh City, driven by out-of-home breakfast consumption rotation.
Dominant by throughput: Direct Sales. Gaining share fastest: Convenience Stores.
Packaging Type:
Margin structure separates premium rigid formats from economy flexible films, with regulatory disclosure requirements driving material selection for front-panel additive transparency.
- Flexible Packaging:Polymer films dominate mass-market bread in India where FSSAI fortification mandates require cost-efficient barrier properties for micronutrient retention.
- Rigid Packaging:Clamshell and tray formats command premium positioning in Japanese convenience stores where Japan's Food Sanitation Act revisions mandate granular additive visibility.
- Boxes:Secondary packaging for gift-oriented cakes and premium pastries in South Korean and Japanese urban centers.
- Bags:Primary containment for bread and cookies with modified atmosphere requirements extending shelf life in tropical distribution.
Volume leader: Flexible Packaging. Premium expansion: Rigid Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Japan and Australia while consumption growth concentrates in Southeast Asian urban centers. Wheat-importing nations face supply volatility that shapes formulation strategies. Regulatory divergence between Japan's additive disclosure regime and India's fortification mandates fragments compliance architectures.
Japan
Tokyo-Osaka corridor sustains premium bread demand through refrigerated subscription networks. The Ministry of Health, Labour and Welfare enforces Food Sanitation Act revisions mandating granular emulsifier disclosure. Nagoya industrial bakeries pilot precision fermentation proteins to reduce allergen exposure in laminated pastries.
India
Tier-two and tier-three cities drive volume expansion as modern trade displaces kirana stores. The Food Safety and Standards Authority of India mandates micronutrient fortification in mass-market bread. Maharashtra and Gujarat host concentrated industrial bakery capacity serving organized retail chains.
Vietnam
Ho Chi Minh City anchors out-of-home breakfast rotation from rice-based meals toward bakery items. The national food safety regulator maintains evolving standards for processed food labeling. Centralized café procurement contracts are consolidating demand around direct industrial bakery relationships.
Indonesia
Jakarta and Surabaya concentrate food service channel growth for chained bakery counters. Cold chain infrastructure gaps in outer islands constrain fresh bread distribution radius. Java-based industrial bakeries capture margin through direct supermarket supply agreements bypassing traditional wholesalers.
Australia
FSANZ labeling requirements create compliance thresholds for imported frozen dough products. Sydney and Melbourne sustain premium positioning for clean-label artisan formats. Domestic producers leverage extended fermentation expertise as regional competitive differentiation.
Asia-Pacific Bakery Products Market Competitive Environment
Capital-heavy producers compete with asset-light brand licensors across divergent distribution architectures. The market structures around three tiers: integrated industrial bakeries with captive logistics, brand-centric licensors relying on co-manufacturing, and regional specialists commanding localized taste adaptation. Strategic moves concentrate on direct-to-foodservice channel capture and refrigerated network expansion.
Within the integrated industrial tier, Yamazaki Baking and Britannia Industries Limited exemplify divergent geographic anchoring strategies. Grupo Bimbo occupies a position bridging multinational scale with national formulation adaptation. These three represent the dominant competitive archetypes: Japanese precision logistics, Indian deep distribution penetration, and Mexican-American hybrid localization.
| Leading Market Players |
|---|
| Yamazaki Baking |
| Meiji Holdings |
| Grupo Bimbo |
| President Bakery |
| QAF Limited |
| Mondelēz International |
| Wilmar International Limited |
| ITC Limited |
| Britannia Industries Limited |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap industrial bakeries across Japan and South Korea anchor supply concentration and impose pricing discipline through captive refrigerated logistics networks. Their ownership structure limits private-equity rollup pressure, preserving margin stability even as wheat import costs fluctuate across Black Sea and Australian origins.
Pricing Analysis
Margin tightening in mass-market bread reflects FSSAI fortification compliance costs and enzyme-based shelf-life reformulation expenses. Three-tier pricing structure across premium, standard, and economy levels separates subscription-based fresh delivery from modern trade retail and traditional kirana channels. Price differentiation hinges on certification grade for clean-label compliance and refrigerated delivery radius. Cost-down pressure on economy tiers accelerates because wheat import volatility compresses baker margins. Food service buyers exhibit lowest price sensitivity due to direct procurement contracts, while kirana store operators in India's tier-three cities remain most price-sensitive.
Supply Chain Analysis
Reverse-logistics flows for reusable bread trays and temperature-controlled return containers concentrate operational complexity in Japan's subscription networks. Geographic supply concentration clusters in Japan, Australia, and India for industrial bakery capacity. Raw material dependencies center on Australian and Canadian wheat, palm oil derivatives for laminated pastries, and precision fermentation-derived proteins. Supply chain risk traces to single-source vulnerability in Black Sea wheat alternatives. Distribution runs through direct industrial bakery-to-supermarket relationships in urban corridors, bypassing traditional wholesalers where cold chain infrastructure permits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme-based shelf-life extension is displacing calcium propionate across clean-label formulations, restructuring competitive advantage around fermentation expertise rather than synthetic additive sourcing.
For Market Incumbents: Anticipate margin compression from precision fermentation protein suppliers by securing backward integration into enzyme production or exclusive supply agreements with Nagoya-based biotech pilot facilities. Defend channel control through refrigerated subscription network expansion before cold chain infrastructure gaps in Indonesia's outer islands close. Japan's Food Sanitation Act disclosure requirements threaten import brands with reformulation timelines; accelerate clean-label certification to capture premium positioning. For New Entrants and Emerging Players: FSSAI fortification mandates in India open a window for premix suppliers and compliant manufacturers to establish first-mover presence in underpenetrated tier-three cities. Target direct-to-foodservice channels in Ho Chi Minh City and Jakarta where out-of-home breakfast rotation consolidates procurement around industrial bakery contracts. White-space exists in Australia's FSANZ-compliant frozen dough imports where compliance thresholds exclude incumbent Asian exporters. For Investors and Strategic Acquirers: Subscription platform adoption rates in Tokyo-Osaka corridor are the leading indicator that refrigerated logistics networks will determine bakery market valuation multiples rather than production capacity alone. Long-term viability favors asset-light brand licensors with co-manufacturing relationships over capital-heavy integrated producers in markets where cold chain infrastructure matures. Acquisition target archetype: regional specialists with localized formulation adaptation and direct supermarket supply agreements. Monitor Japan's Ministry of Health, Labour and Welfare enforcement patterns for additive disclosure granularity as early signal of compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Logistics Network Expansion | Yamazaki Baking's daily doorstep subscriptions demonstrate that cold chain reach determines competitive boundary more than production scale. |
| Clean-Label Reformulation Investment | Enzyme-based shelf-life extension responds to Japan's Food Sanitation Act while opening premium positioning in urban convenience stores. |
| Direct-to-Foodservice Channel Development | Industrial bakeries bypassing wholesalers capture margin and demand data from chained cafés in Jakarta and Ho Chi Minh City. |
| Precision Fermentation Protein Sourcing | Nagoya pilot facilities reduce allergen exposure in laminated pastries while compressing butter and margarine cost volatility. |
| Tier-Three City Distribution Penetration | Britannia Industries Limited's deep distribution into smaller Indian urban centers exploits underdeveloped organized bakery presence. |
Study Parameters
Independent corroboration across bakery operations executives, refrigerated logistics planners, and FSSAI compliance officers underwrites the qualitative findings. Primary interviews with industrial bakery plant managers, modern trade category buyers, and food service procurement heads combined with secondary validation from customs wheat import records, Japan Ministry of Health enforcement disclosures, and India modern trade expansion databases. Bottom-up production capacity estimates and top-down consumption surveys triangulate market sizing.
Comparable-period anchoring to pre-pandemic baseline consumption patterns and post-regulatory-shift pricing responses structured the forecast window. Segmentation modeling spanned product moisture content tiers, distribution channel cold chain requirements, and national regulatory compliance clusters. CAGRs derived from production capacity expansion announcements and urban modern trade penetration trajectories. Industry-specific inputs included wheat futures volatility indices and refrigerated fleet deployment data across Southeast Asian corridors.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation protein scaling would alter the outlook. Forecasts reflect underlying assumptions about regulatory enforcement consistency and infrastructure investment continuity. Practitioners should monitor Japan's additive disclosure granularity revisions and India's fortification mandate expansion for early signals of compliance cost trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Qatar Bakery Product Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Pastry Margarine Market
Bakery Products
Baking Mats Market
Bakery Products
Pancakes Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Flour Mixes Market
Bakery Products
Europe Zwieback Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
No-Fat Cake Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Laminated Dough Market
Bakery Products
Baking Mixes Market