
 Bread Market | 2026-2036
Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Market Analysis
Multi-source flour procurement is shifting toward vertically integrated milling operations among large bread manufacturers. Grupo Bimbo leverages captive wheat sourcing across Latin American operations to stabilize input costs. Flowers Foods anchors its southeastern US network through direct relationships with regional grain cooperatives. Yamazaki Baking competes on fermentation technology leadership in the premium packaged bread segment.
Bread is a leavened baked product produced from flour, water, salt, and yeast or starter cultures, typically containing 35-40% moisture post-bake and serving as a staple carbohydrate source in food retail and food service channels. Whole wheat and multigrain varieties command margin premiums in supermarket channels where health-positioned labeling drives shelf placement. Sourdough fermentation, requiring 12-24 hour culture maturation, attracts artisan bakery positioning and above-average price realization in both European and North American markets.
The FDA governs standardized identity requirements for bread products sold in US interstate commerce, while the EU Green Deal and F-Gas Regulation constrain industrial baking energy profiles and refrigeration chemistry across European production facilities. BIS fortification mandates in India and GB standards under SAMR in China further fragment compliance obligations for multinational manufacturers. Stakeholders must monitor how diverging clean-label and carbon-accounting standards reshape capital allocation between regional production footprints and export-oriented centralized baking.
Market Dynamics
Clean-label mandates from the FDA and EU Green Deal carbon-accounting requirements are forcing simultaneous reformulation of bread products and retooling of industrial baking infrastructure. Capital allocation now splits between compliance-driven equipment upgrades and premium segment positioning.
Growth Catalysts
- EU Green Deal decarbonization:Industrial bakeries across Germany, France, and Italy are retrofitting ovens and refrigeration systems to meet F-Gas Regulation phase-down schedules, creating replacement demand for low-global-warming-potential equipment.
- Food service channel expansion:North American restaurant and hospitality procurement of fresh artisan loaves is accelerating as operators replace frozen-dough programs with localized sourcing partnerships.
- Fermentation biotechnology:Controlled-environment sourdough starter propagation systems are reducing culture maturation variability, enabling scaled production of premium-positioned loaves with consistent flavor profiles.
Market Restraints
- Wheat price volatility:Input cost instability linked to Black Sea supply disruptions and drought cycles in Australia and Argentina compresses margin buffers for non-integrated manufacturers lacking captive milling capacity.
- Energy cost concentration:Natural gas and electricity price spikes in European Union member states disproportionately impact continuous-baking operations versus batch artisan producers with lower thermal intensity.
- Refrigerant chemistry constraints:F-Gas Regulation hydrofluorocarbon quotas limit industrial freezer and retarder-proofer replacement options, extending equipment depreciation cycles.
Strategic Opportunities
- Indian BIS fortification mandates:Mandatory micronutrient enrichment requirements for packaged bread create formulation service opportunities for premix suppliers and equipment retrofit providers.
- Direct-to-retailer distribution:Bypassing traditional wholesale bakery distributors through dedicated fleet investments allows real-time production scheduling aligned with supermarket scan-data replenishment signals.
- Upcycled ingredient integration:Brewer's spent grain and oilseed processing byproducts offer cost-advantaged fiber and protein fortification for value-positioned whole wheat and multigrain lines.
Industry Challenges
- Artisan baker skill scarcity:Extended fermentation management and hand-shaping expertise required for premium sourdough production faces generational transfer gaps as traditional apprenticeship pipelines contract.
- Legacy equipment integration:Retrofitting continuous mixing and proofing lines with IoT-enabled monitoring systems creates data architecture incompatibilities with decades-old programmable logic controllers.
- Dual certification timelines:Simultaneous pursuit of organic certification and carbon-neutral labeling requires parallel audit streams with divergent documentation standards and verification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Market |
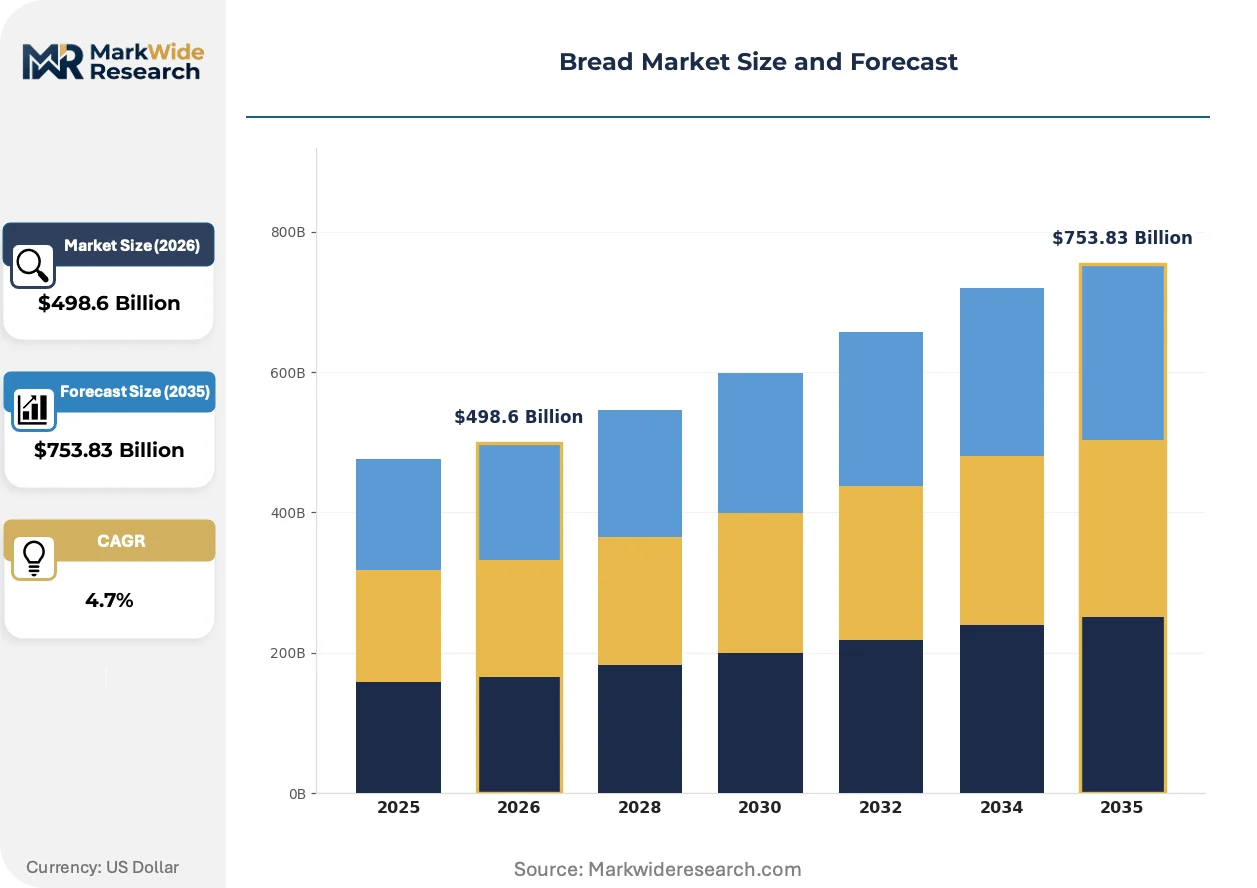
| Market Size in 2026 | $498.6 Billion |
| Market Size in 2035 | $753.83 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Gluten-Free, Sourdough, Multigrain Distribution Channel: Supermarkets, Online Retail, Bakeries, Convenience Stores End User: Households, Restaurants, Cafés, Food Service Packaging Type: Bags, Boxes, Wraps, Trays |
| Companies Covered | Grupo Bimbo, Flowers Foods, Associated British Foods, Yamazaki Baking, Barilla Group, General Mills, Almarai, Bimbo Bakeries USA, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Market Emerging Trajectories
Electrification of thermal processes and digitalization of fermentation control are converging to redefine capital intensity and product consistency thresholds across industrial and artisan production scales.
Electric tunnel ovens with regenerative thermal oxidizers are electrifying the heat-recovery architecture of high-volume bread lines. Industrial bakeries in the Netherlands and Denmark are piloting grid-responsive baking schedules that align production peaks with renewable energy availability. This technology is electrifying the competitive calculus between continuous-flow and batch-retarder systems by collapsing the energy-cost differential that previously favored gas-fired equipment.
REACH chemical authorization requirements are restricting processing aids and dough conditioners previously standard in extended-shelf-life formulations. European manufacturers are reformulating around enzyme-based alternatives and cultured wheat derivatives to maintain texture stability without flagged additives. Frozen par-baked and bake-off segments face the steepest compliance recalibration as their supply chains span multiple regulatory jurisdictions.
Food service operators are consolidating bread procurement through cooperative purchasing organizations that aggregate volume across independent restaurant groups. This buying-pattern shift is displacing the multi-distributor fragmentation that historically characterized regional bakery supply. The concentration is most visible in metropolitan clusters across the United Kingdom and Japan, where procurement managers now negotiate directly with mid-scale artisan producers for exclusive territory arrangements.
Bread Market Segmentation
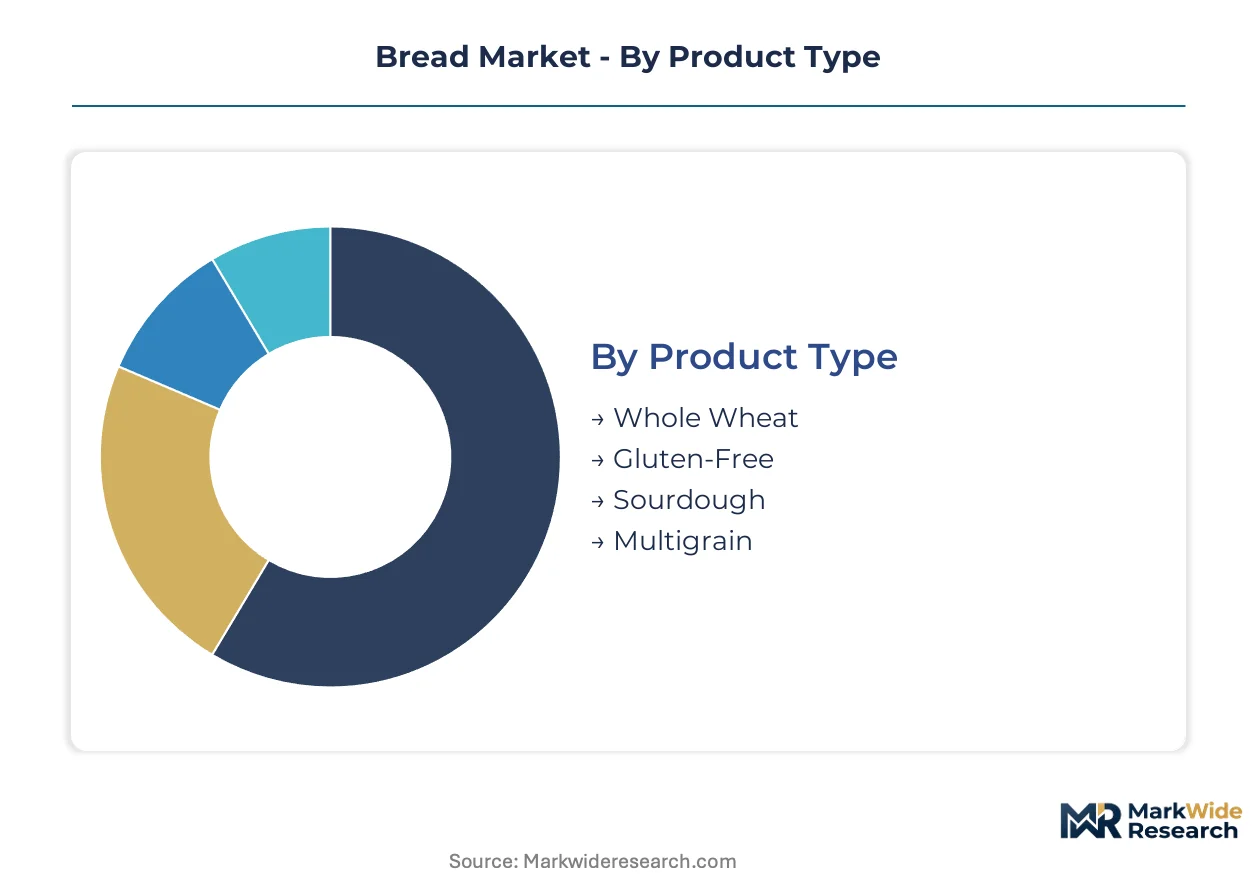
Bread market segmentation reveals divergent margin structures across production scales and channel access. Manufacturers configure product portfolios around fermentation complexity, distribution control, and end-use service requirements rather than uniform mass-market positioning.
Product Type:
Supply concentration clusters around heritage grain sourcing and controlled fermentation infrastructure, with premium positioning tied to provenance verification and extended culture maturation capabilities.
- Whole Wheat:Stone-ground flour with bran and germ retention delivers elevated fiber content and nuttier flavor profiles. German and United Kingdom retail channels prioritize whole wheat SKUs as baseline health-positioned offerings, with shelf placement premiums contingent on clean-label certification and regional grain provenance documentation.
- Sourdough:Wild yeast and lactobacillus fermentation over 12-24 hours produces distinctive acidity and extended shelf stability without chemical preservatives. Artisan producers across Japan and metropolitan United States clusters command price multiples through controlled-environment starter propagation and hand-scoring techniques that signal authenticity.
- Gluten-Free:Rice, tapioca, and almond flour formulations replace wheat protein matrices with hydrocolloid binding systems. Dedicated allergen-free production lines and third-party certification requirements create capital barriers that favor contract manufacturers over in-house conversion.
- Multigrain:Composite flour blends incorporating oats, flax, and sunflower seeds target fiber-forward positioning in supermarket channels. Ingredient cost volatility and sourcing complexity limit penetration to mid-tier pricing bands.
Today's leader: Sourdough. Tomorrow's challenger: Whole wheat.
Distribution Channel:
Channel economics fragment around inventory velocity, temperature control requirements, and direct relationship access to procurement decision-makers.
- Supermarkets:High-frequency replenishment cycles and scan-data visibility drive production scheduling for national brand portfolios. Slotting fees and promotional fund obligations compress net margins despite volume concentration.
- Bakeries:Direct retail baking with same-day production and minimal distribution overhead supports premium positioning. Urban clusters in France and Italy sustain independent bakery density through protected designation of origin sourcing and localized consumption rituals.
- Online Retail:Frozen par-baked and ambient-stable packaged formats enable national fulfillment without refrigerated last-mile infrastructure. Subscription models and direct-to-consumer branding bypass traditional wholesale markups.
- Convenience Stores:Extended-shelf-life formulations and single-serve packaging address impulse purchase occasions. Price ceilings and limited facing availability constrain product mix to value-positioned white and wheat varieties.
Supermarkets dominate volume. Online retail is climbing the fastest.
End User:
Service level requirements separate commodity procurement from customized production relationships, with food service operators demanding technical specification alignment and flexible minimum order quantities.
- Households:Weekly purchase cycles favor multipack formats and freezer-compatible slicing. Brand loyalty weakens as private label quality convergence reduces perceived differentiation.
- Food Service:Centralized procurement for hospitality and institutional accounts requires HACCP documentation, consistent portioning, and delivery windows aligned with kitchen prep schedules. United Kingdom and Japan cooperative purchasing organizations aggregate independent restaurant demand into volume commitments.
- Restaurants:Menu-specific loaf dimensions and crust characteristics drive custom formulation partnerships with regional artisan producers. Exclusive territory arrangements protect chef relationships from competitive supply.
- Cafés:Visual presentation and crumb structure for sandwich assembly prioritize pullman and batard shapes over standard sandwich slices. Morning delivery windows and day-fresh requirements favor proximate bakery relationships.
Food service commands margin expansion. Households anchor volume stability.
Packaging Type:
Material selection balances moisture retention, shelf-life extension, and sustainability positioning against unit economics and equipment compatibility.
- Bags:Polyethylene and paper-poly laminates dominate high-volume sliced bread with twist-tie or clip closures. Recyclability mandates from EU packaging regulations accelerate transition to mono-material structures.
- Wraps:Flow-wrapped artisan loaves and baguettes preserve crust texture through perforated film or paper combinations. Premium positioning supports higher packaging cost absorption.
- Boxes:Rigid paperboard structures protect frozen par-baked and specialty gift assortments during distribution. E-commerce fulfillment requirements drive crush-resistant specification tightening.
- Trays:Thermoformed PET and molded fiber platforms display unsliced boules and rolls in bakery service cases. Reusable tray programs in German retail reduce single-use packaging waste.
Bags retain volume dominance. Wraps are gaining share fastest through artisan segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing bread production capacity toward jurisdictions with lower compliance costs for clean-label reformulation and carbon-accounting mandates. Manufacturers now weigh F-Gas phase-down timelines, fortification mandates, and energy pricing when siting new baking facilities.
United States
Food service operators in metropolitan clusters from New York to Los Angeles are replacing frozen-dough programs with localized fresh bread sourcing. FDA standardized identity requirements for interstate commerce force continuous reformulation of extended-shelf-life products. The southeastern states anchor Flowers Foods' network through direct grain cooperative relationships.
Germany
Artisan sourdough demand concentrates in Berlin and Munich retail channels where protected designation of origin sourcing commands shelf placement premiums. EU Green Deal F-Gas Regulation phase-down schedules accelerate oven and refrigeration retrofit cycles across industrial bakeries. The Baden-Württemberg region sustains independent bakery density through localized consumption rituals.
Japan
Yamazaki Baking competes on fermentation technology leadership in the premium packaged bread segment across Tokyo and Osaka metropolitan areas. METI energy efficiency standards shape capital allocation toward electric tunnel oven installations. The Kanto region hosts controlled-environment sourdough starter propagation pilot facilities reducing culture maturation variability.
India
BIS fortification mandates for packaged bread create formulation service opportunities for premix suppliers in Maharashtra and Gujarat. FSSAI micronutrient enrichment requirements drive equipment retrofit demand across mid-scale producers. The Delhi-NCR corridor concentrates contract manufacturing capacity for dedicated allergen-free production lines.
United Kingdom
Cooperative purchasing organizations aggregate independent restaurant demand into volume commitments across London and metropolitan clusters. REACH chemical authorization restricts processing aids previously standard in extended-shelf-life formulations. The Midlands region hosts reformulation centers developing enzyme-based texture stability alternatives.
Bread Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue premium-positioned artisan segments through controlled fermentation differentiation. Market structure consolidates around vertically integrated milling operations and captive wheat sourcing networks. Three archetypes dominate: multinational brand portfolios with continental distribution footprints, regional specialists leveraging grain cooperative relationships, and artisan-scale operators competing on provenance verification. Competitive moves center on backward integration into milling capacity and direct-to-retailer distribution fleet investments bypassing wholesale markups.
Within the multinational tier, Grupo Bimbo and Flowers Foods exemplify divergent geographic anchoring strategies. Grupo Bimbo leverages Latin American captive wheat sourcing to stabilize input cost volatility across its operational footprint. Flowers Foods anchors southeastern United States production through regional grain cooperative relationships rather than owned milling assets. Yamazaki Baking occupies a distinct position competing on fermentation technology leadership in premium packaged bread segments.
| Leading Market Players |
|---|
| Grupo Bimbo |
| Flowers Foods |
| Associated British Foods |
| Yamazaki Baking |
| Barilla Group |
| General Mills |
| Almarai |
| Bimbo Bakeries USA |
| Mondelez International |
| Others |
Supply Flow & Price Mechanics
Captive wheat sourcing across vertically integrated milling operations anchors both cost predictability and pricing power for large bread manufacturers. Grupo Bimbo's Latin American supply network and Flowers Foods' southeastern US grain cooperative relationships demonstrate how upstream control insulates margin structures from Black Sea supply volatility and Australian drought cycles.
Pricing Analysis
Distributor margin compression in traditional wholesale bakery channels is accelerating direct-to-retailer fleet investments. Three-tier pricing structure across premium artisan, standard packaged, and economy private-label levels stratifies by fermentation complexity and provenance documentation. Cost compression in the economy tier is intensifying because private label quality convergence erodes brand premiums. Food service operators demonstrate lowest price sensitivity due to menu-positioning requirements, while convenience store channels face ceiling constraints.
Supply Chain Analysis
Direct-to-retailer channels handle hyperscale supermarket demand through dedicated fleet investments bypassing wholesale markups. Wheat sourcing concentrates in Argentina, Australia, and the Black Sea region, with flour milling anchored in Germany, the United States, and Japan. The supply chain rests on natural gas-dependent thermal processes and F-Gas constrained refrigeration chemistry. Single-source vulnerability in heritage grain varieties limits artisan producer scaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
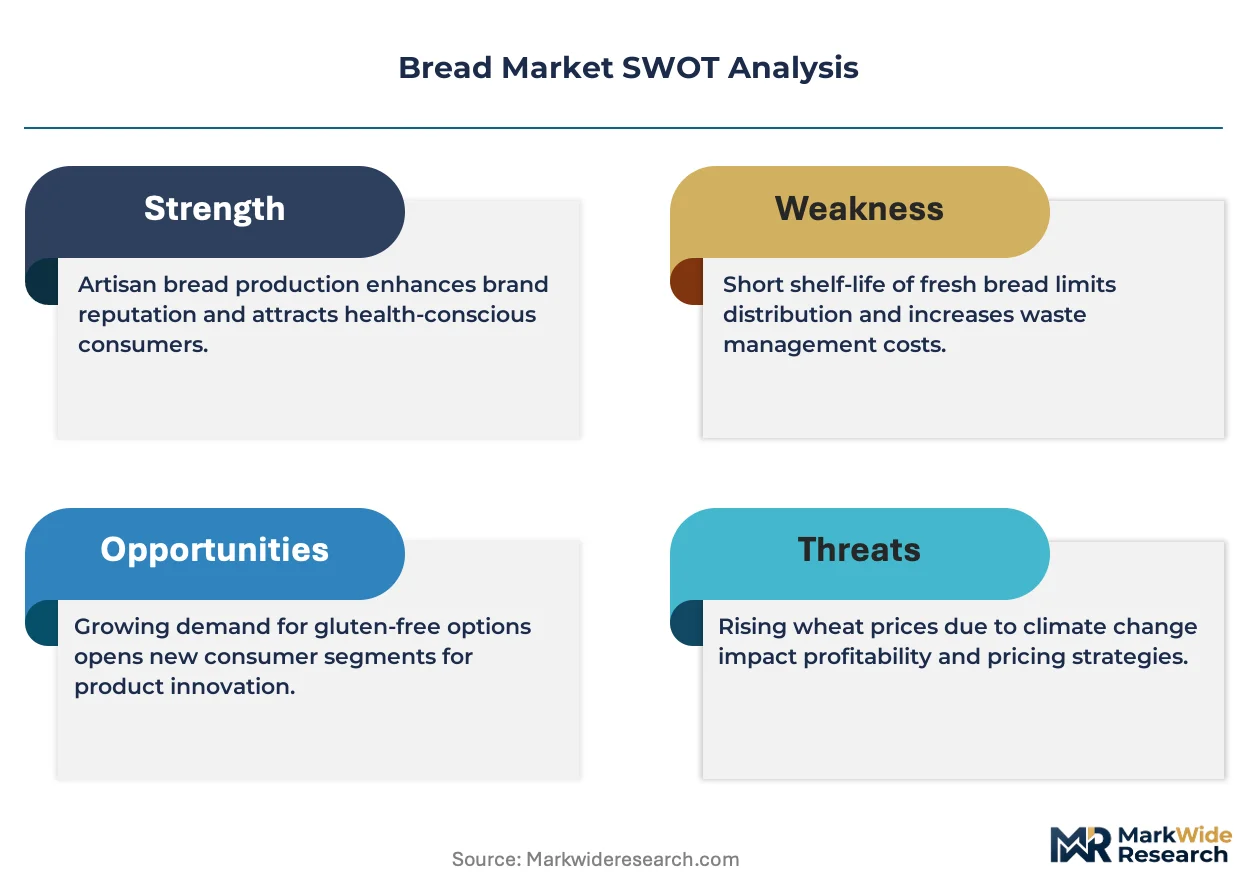
The bread market represents a late-cycle quality story as food service procurement shifts toward clean-label artisan specifications with extended fermentation protocols. This demand migration favors producers with controlled-environment starter propagation capabilities over commodity-scale continuous baking.
For Market Incumbents: Cement fermentation technology leadership through controlled-environment starter propagation system investments. Secure exclusive territory arrangements with metropolitan food service cooperative purchasing organizations. Defend against emerging artisan-scale entrants by retrofitting legacy continuous lines with IoT-enabled monitoring for real-time production scheduling.
For New Entrants and Emerging Players: The mid-tier price gap between premium sourdough and economy private-label creates white-space for whole wheat positioning with regional grain provenance documentation. Target Indian BIS fortification mandate compliance services as a formulation partnership entry point. Pursue direct-to-retailer distribution bypassing traditional wholesale bakery distributor networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where artisan baker skill scarcity meets generational transfer gaps in traditional apprenticeship pipelines. Five-to-ten year viability favors mid-scale producers with captive milling capacity and clean-label certification infrastructure. Monitor F-Gas Regulation phase-down timelines as capital expenditure inflection signals for equipment retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milling Capacity | Captive wheat sourcing stabilizes input costs against Black Sea supply disruptions. |
| Direct-to-Retailer Distribution Launch | Dedicated fleet investments align production with supermarket scan-data replenishment signals. |
| Clean-Label Reformulation Program | Enzyme-based alternatives to REACH-restricted dough conditioners maintain texture stability. |
| Electric Tunnel Oven Installation | Grid-responsive baking schedules align production peaks with renewable energy availability. |
| Heritage Grain Sourcing Partnership | Protected designation of origin documentation commands shelf placement premiums in German retail. |
Methodological Framework
Bottom-up food service channel modeling reconciled against top-down flour milling capacity tracking forms the analytical core. Primary interviews with artisan bakery owners, supermarket category buyers, grain cooperative procurement managers, and food service cooperative purchasing directors combined with secondary validation from FDA standardized identity filings, EU F-Gas Regulation implementation schedules, BIS fortification mandate documentation, and customs trade data for wheat and flour movements. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map wheat procurement through milling, fermentation, baking, and distribution stages across product type, distribution channel, end user, and packaging format segmentation dimensions. CAGRs derive from regression analysis against historical volume trajectories and elasticity-adjusted price projections. Forecast inputs incorporate EU Green Deal carbon-accounting compliance cost modeling and METI energy efficiency standard implementation timelines.
Caveats apply where Black Sea supply disruptions, Australian drought cycles, or F-Gas Regulation phase-down schedule accelerations could materially shift the outlook. Forecasts reflect documented assumptions regarding clean-label adoption rates and food service channel migration from frozen-dough programs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Waffle Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Malted Rye Flour Market
Bakery Products
South America Bakery Products Market
Bakery Products
South America Ice Cream Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Packaged Bread Market
Bakery Products
Matcha Cookie Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Global Cake Mix Market