
 Paper Carrier Bags Market | 2026-2036
Paper Carrier Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Carrier Bags Market Analytics
FSC certification is bifurcating the competitive landscape into certified and non-certified supply tiers. International Paper Company leverages its integrated pulp-to-bag operations across North American mills to sustain volume leadership. Mondi Group Plc anchors European demand through specialized kraft paper grades engineered for high-strength retail applications. Smurfit Kappa Group differentiates via recycled-content portfolios that compete aggressively on sustainability credentials in supermarket channels.
Paper carrier bags are portable containers manufactured from kraft, recycled, or coated paper stock, typically featuring twisted or flat handles and load-bearing capacities from 2 kg to 20 kg depending on ply construction and adhesive reinforcement. Block bottom bags command premium positioning in supermarket and retail segments where shelf stability and stacking efficiency determine procurement decisions, while patch handle variants occupy faster-growing e-commerce channels demanding tear-resistant handholds for doorstep delivery. Kraft paper material leads volume production due to its tensile strength and natural biodegradability, though coated paper grades capture margin pools in food outlet applications requiring grease and moisture barriers.
EU REACH and F-Gas Regulation frameworks govern chemical inputs in paper processing and coatings, while FDA food-contact standards in the United States restrict adhesive and ink compositions for grocery-adjacent bag applications. Germany's national packaging ordinance enforces extended producer responsibility fees that shift cost structures toward recyclable mono-material designs. Stakeholders must monitor evolving extended producer responsibility schemes across multiple jurisdictions to anticipate compliance-driven sourcing requirements.
Market Dynamics
Extended producer responsibility schemes across European Union member states are forcing rapid conversion from plastic to paper carrier formats, with compliance costs now embedded in procurement decisions for retail chains and food service operators.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive mandates phase-out of conventional plastic bags in all member states, creating immediate substitution demand for kraft paper alternatives in supermarket and grocery channels.
- FSC certification tiering:Forest Stewardship Council standards now separate supply tiers, with certified material commanding preferential placement in premium retail contracts across Germany and France.
- Block bottom engineering:Structural innovations in bag base construction enable shelf-stable stacking, opening procurement pathways previously dominated by rigid plastic containers.
Market Restraints
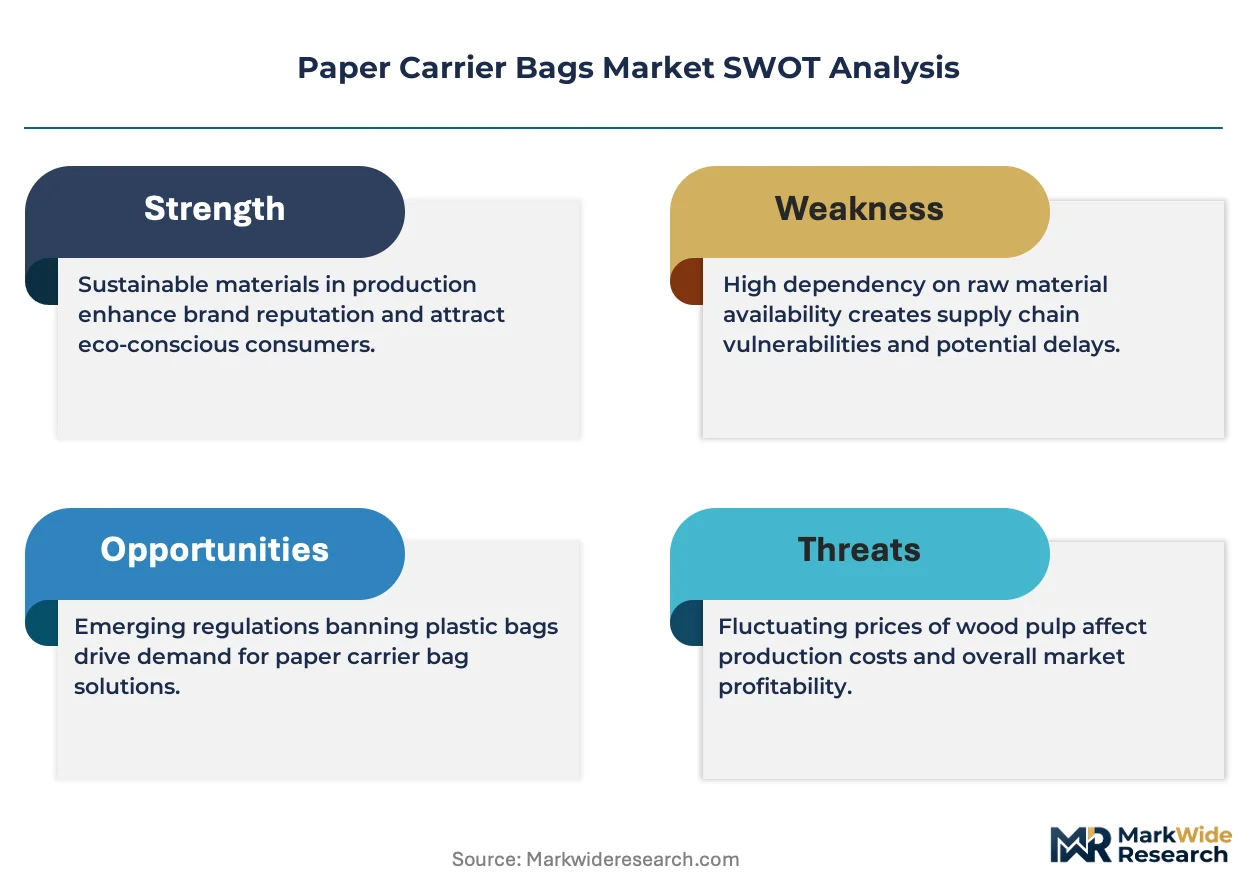
- Pulp cost volatility:Softwood kraft pulp prices fluctuate with Nordic and North American timber harvest cycles, compressing margin predictability for converters without long-term fiber supply agreements.
- Moisture barrier limitations:Uncoated kraft paper lacks grease and liquid resistance for hot food applications, restricting penetration into quick-service restaurant takeaway segments where plastic and compostable films retain dominance.
- Recycling infrastructure gaps:Contaminated paper bags with food residue face rejection from municipal sorting facilities in jurisdictions with strict fiber quality standards, undermining circular economy claims.
Strategic Opportunities
- Coated paper convergence:Water-based barrier coatings combined with heat-sealable adhesives are opening fresh produce and chilled meat applications previously closed to paper formats.
- E-commerce patch handle demand:Tear-resistant handhold designs engineered for doorstep delivery are capturing share in online grocery fulfillment centers across the United Kingdom and Netherlands.
- German EPR fee differentials:Germany's packaging ordinance creates cost advantages for mono-material recyclable designs, rewarding investments in simplified adhesive and ink systems.
Industry Challenges
- FSC chain-of-custody certification timelines:Audit and documentation requirements for forest-to-retailer traceability extend 12-18 months, delaying contract eligibility for smaller converters.
- Legacy equipment retrofit costs:Converting machinery originally configured for plastic film production requires substantial capital outlay for tension control and adhesive application modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Carrier Bags Market |
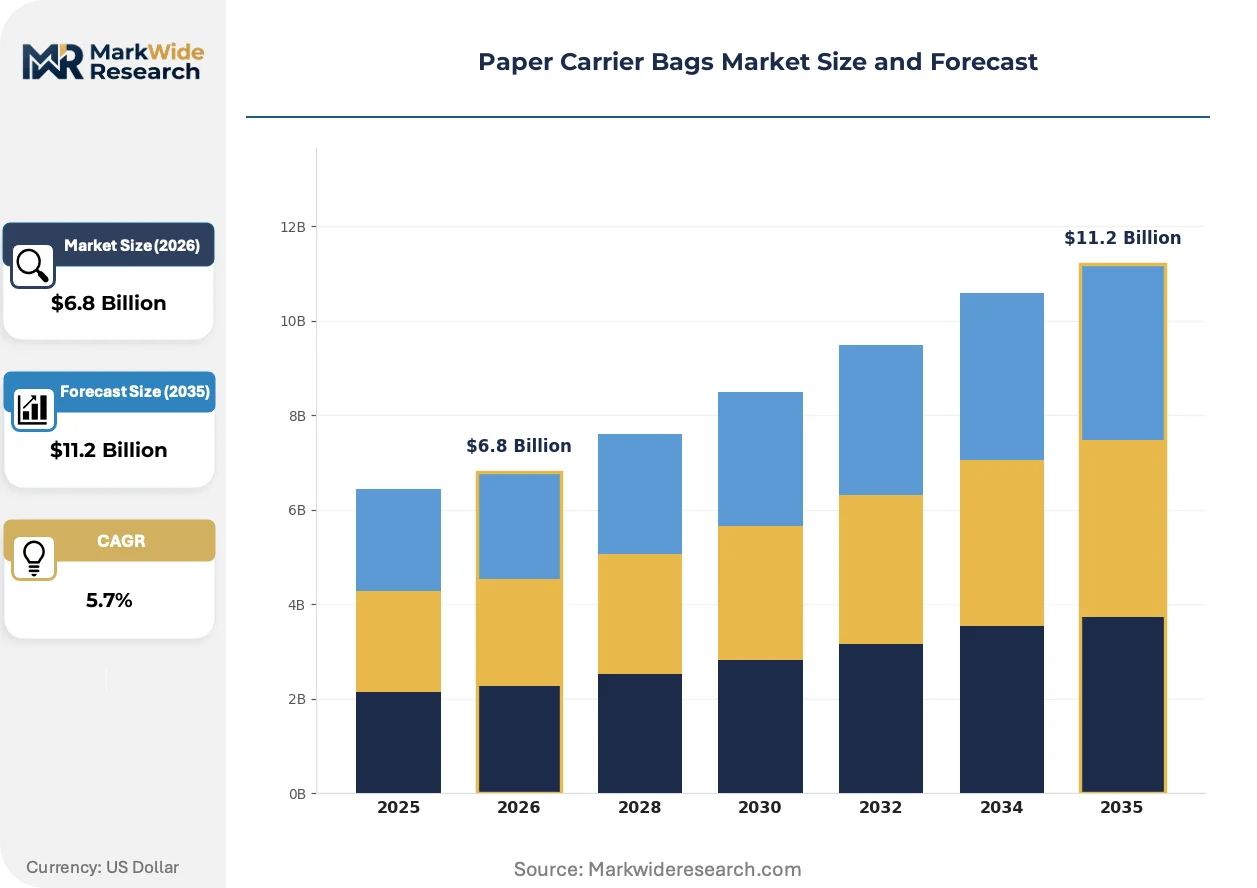
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Satchel Bags, Patch Handle Bags, Block Bottom Bags End User: Retail Stores, Food Outlets, E-commerce, Supermarkets Material: Kraft Paper, Recycled Paper, Coated Paper, Brown Paper Weight Capacity: Lightweight, Medium Weight, Heavyweight, Super Heavyweight |
| Companies Covered | International Paper Company, Smurfit Kappa Group, Mondi Group Plc, WestRock Company, Novolex Holdings, DS Smith, Oji Holdings Corporation, ProAmpac LLC, Global-Pak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Carrier Bags Market Evolving Landscape
Active innovation centers on material science breakthroughs that close performance gaps with plastic alternatives, regulatory frameworks that accelerate format substitution, and procurement models that reward verifiable sustainability credentials over unit cost minimization.
Reinforced kraft ply construction with cross-directional fiber alignment is miniaturizing the thickness required for equivalent load-bearing capacity. Major German supermarket chains now specify 80-gram basis weight specifications previously requiring 100-gram stock, reducing fiber input costs and shipping cube. The technology is compressing the premium gap between standard and high-performance bag grades.
REACH chemical authorization restrictions on per- and polyfluoroalkyl substances are eliminating traditional grease-resistant coatings from food-contact paper applications. Industrial consequence includes accelerated migration to bio-based barrier formulations using chitosan or alginate derivatives. Quick-service restaurant chains in France and Belgium face 2025 compliance deadlines and are pre-qualifying alternative-coated suppliers now.
Corporate sustainability scorecards now weight Scope 3 emissions from packaging procurement, altering buyer evaluation criteria. Retail category managers increasingly require supplier-provided lifecycle assessment documentation alongside unit pricing. This behavioral shift is most visible in Nordic markets where consumer-facing carbon labeling regulations amplify downstream pressure.
Paper Carrier Bags Market Segmentation
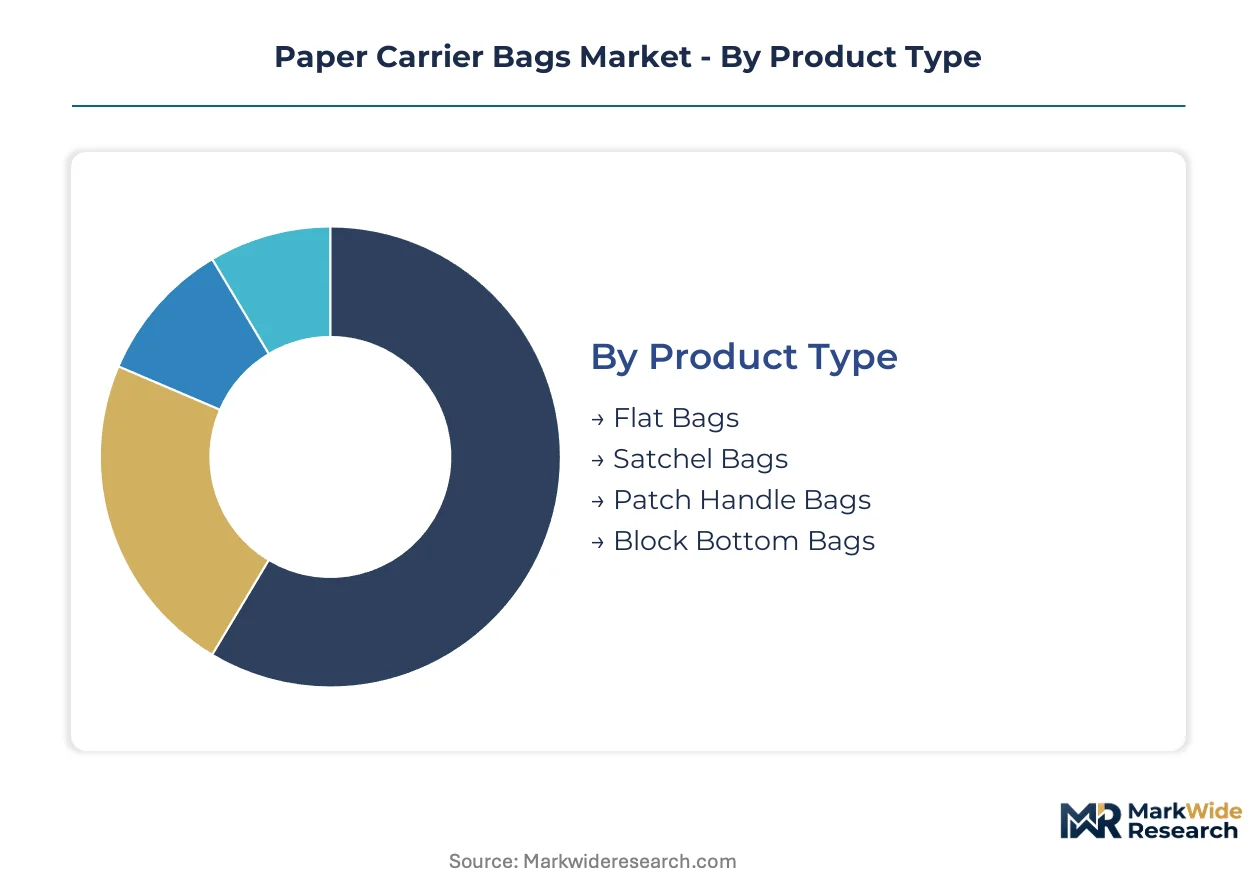
Paper carrier bag specifications diverge sharply across retail channels, with load-bearing requirements and regulatory compliance tiers determining procurement patterns. Material composition and structural engineering create distinct performance-price positioning that shapes supplier selection in supermarket and food service verticals.
Product Type:
EU REACH chemical restrictions and FDA food-contact standards differentiate bag formats by coating compatibility and adhesive specifications.
- Block Bottom Bags:Engineered with reinforced gusset construction enabling vertical shelf stability for stacked merchandise. German supermarket chains specify these for private-label grocery lines where display aesthetics drive procurement. REACH-compliant water-based adhesives now dominate this segment.
- Patch Handle Bags:Reinforced handhold attachments withstand 15-20 kg dynamic loads during doorstep delivery. United Kingdom e-commerce fulfillment centers specify tear-resistant variants for online grocery channels where carrier failure generates return costs.
- Flat Bags:Single-ply construction suits lightweight non-food retail with minimal barrier requirements.
- Satchel Bags:Self-opening design with integrated closure flaps serves boutique apparel and gift segments.
Established volume favors block bottom engineering; emerging adoption favors patch handle reinforcement.
End User:
Customer procurement authority concentrates in retail category managers with divergent performance specifications and sustainability scorecard weightings.
- Supermarkets:High-volume procurement with FSC certification mandates and mono-material recyclability requirements. French and Belgian retail chains enforce strict chain-of-custody documentation for private-label packaging, with Germany's EPR fee structures rewarding simplified adhesive systems.
- Food Outlets:Grease and moisture barrier specifications dominate quick-service restaurant procurement. France's 2025 PFAS coating deadlines are accelerating bio-based chitosan formulation adoption for hot food takeaway applications.
- Retail Stores:Brand-conscious positioning drives premium kraft specifications with custom print compatibility.
- E-commerce:Automated fulfillment compatibility and dimensional efficiency determine bag selection for warehouse operations.
Procurement scale concentrates in supermarket channels; sustainability compliance pressure intensifies fastest in food outlet verticals.
Material:
Fiber sourcing geography and certification tiering create supply stratification that separates premium contract eligibility from commodity positioning.
- Kraft Paper:Virgin softwood pulp delivers tensile strength for 10-20 kg load ratings with minimal ply count. Nordic timber harvest cycles influence pricing volatility, with long-term fiber agreements separating stable suppliers from spot-market exposed competitors.
- Coated Paper:Water-based barrier formulations enable fresh produce and chilled meat applications previously closed to uncoated stock. Bio-based chitosan and alginate derivatives are displacing legacy PFAS coatings under REACH authorization restrictions.
- Recycled Paper:Post-consumer fiber content satisfies corporate Scope 3 emissions targets in Nordic markets with carbon labeling regulations.
- Brown Paper:Unbleached natural finish serves organic and artisanal brand positioning with minimal processing.
Performance specifications anchor demand in kraft grades; regulatory pressure is reshaping coated paper formulation chemistry.
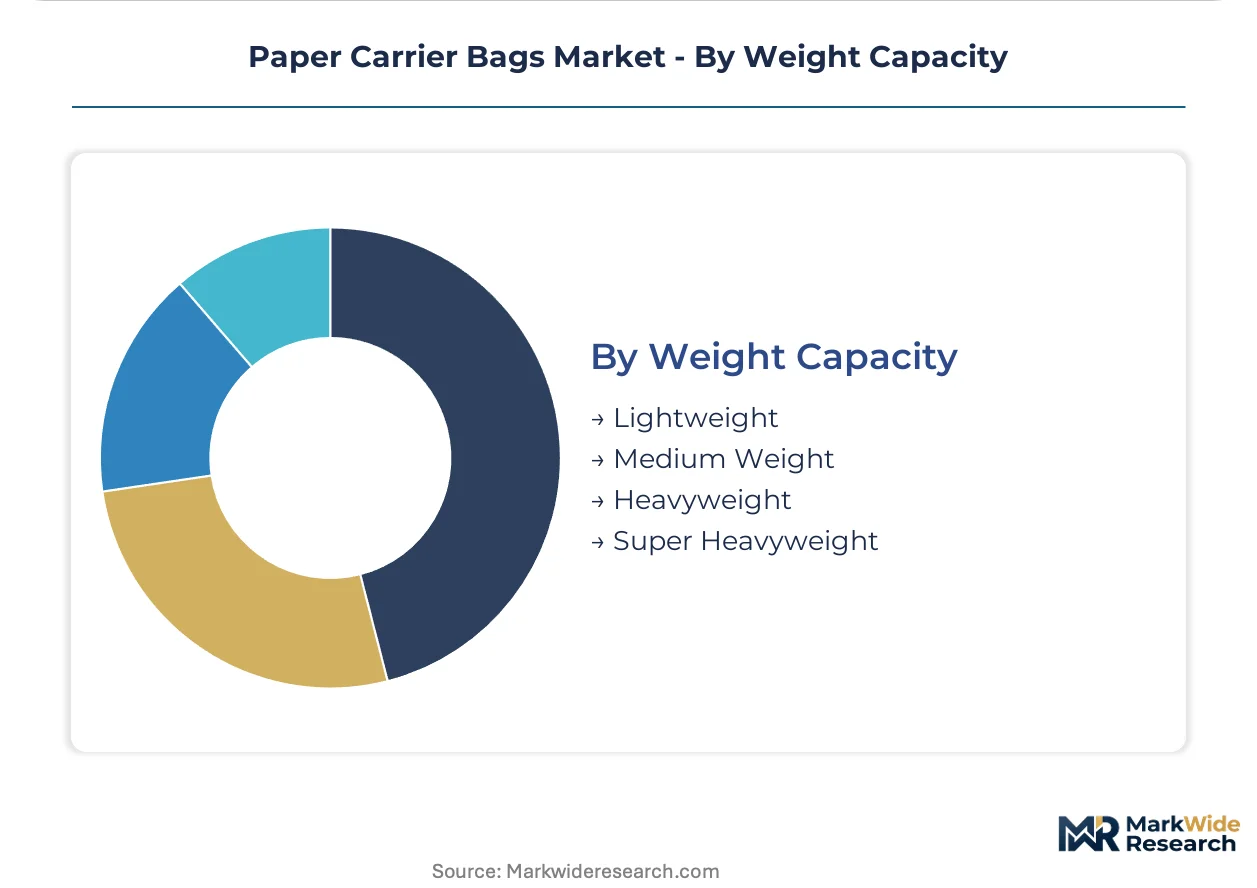
Weight Capacity:
Ply construction and fiber alignment engineering determine load-bearing thresholds that match bag specification to merchandise category.
- Heavyweight:Cross-directional fiber alignment and reinforced adhesive bonding support 15-20 kg dynamic loads for beverage and bulk grocery applications. German engineering innovations have compressed 100-gram equivalent performance into 80-gram basis weight specifications.
- Medium Weight:Standard 5-10 kg rating dominates general merchandise retail with balanced cost-performance positioning for mid-tier supermarket private labels.
- Lightweight:Single-ply construction suits apparel and soft goods with minimal puncture risk.
- Super Heavyweight:Multi-ply reinforced construction serves industrial and bulk retail applications with extreme load requirements.
Volume production clusters in medium weight specifications; engineering innovation concentrates in heavyweight miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail category managers in Germany and France command the highest procurement volumes, while converters in these markets face divergent certification timelines and EPR fee structures that reshape sourcing decisions.
Germany
Supermarket chains Rewe and Edeka drive block bottom bag specifications for private-label grocery lines. The national packaging ordinance enforces extended producer responsibility fees that reward mono-material recyclable designs. Converting clusters in North Rhine-Westphalia and Bavaria specialize in 80-gram basis weight engineering that matches previous 100-gram performance.
France
Quick-service restaurant chains accelerate bio-based coating adoption for hot food takeaway packaging. ANSM enforces 2025 PFAS coating deadlines under REACH authorization restrictions. Industrial concentration around Lyon and Paris hosts pre-qualified suppliers scaling chitosan and alginate barrier formulations.
United Kingdom
E-commerce fulfillment centers specify tear-resistant patch handle variants for online grocery doorstep delivery. The Competition and Markets Authority monitors packaging sustainability claims under greenwashing enforcement protocols. Converting capacity clusters in the Midlands and Greater Manchester serve Tesco and Sainsbury's automated warehouse operations.
United States
Supermarket chains Kroger and Albertsons mandate FDA food-contact compliant adhesives for grocery-adjacent bag applications. State-level plastic bag bans in California and New York create patchwork substitution demand. Integrated pulp-to-bag operations in the Southeast and Pacific Northwest sustain volume leadership through captive fiber supply.
Netherlands
Retail chains Albert Heijn and Jumbo enforce FSC chain-of-custody documentation for all private-label packaging procurement. The Dutch national packaging covenant aligns with EU Single-Use Plastics Directive implementation timelines. Converting specialists in the Randstad region engineer dimensional efficiency for automated fulfillment compatibility.
Paper Carrier Bags Market Competitive Landscape
Player mix skews toward integrated paper and packaging conglomerates with captive pulp supply, mid-tier converters competing on sustainability certification, and regional specialists serving single-country procurement channels. Tiered competitive positioning separates FSC-certified premium supply from commodity-grade alternatives. Dominant competitive moves include backward integration into kraft pulp production and strategic partnerships with retail chains for private-label packaging development.
Within the integrated conglomerate tier, International Paper Company and Mondi Group Plc exemplify scale-driven positioning through captive fiber operations across multiple continents. Smurfit Kappa Group occupies a distinct archetype as a recycled-content specialist competing aggressively on sustainability credentials in European supermarket channels. These three entities represent the structural concentration where volume leadership, certification tiering, and geographic coverage intersect.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Kappa Group |
| Mondi Group Plc |
| WestRock Company |
| Novolex Holdings |
| DS Smith |
| Oji Holdings Corporation |
| ProAmpac LLC |
| Global-Pak Inc. |
| Others |
Value Network & Pricing Analysis
Mill-scale fiber integration in Nordic and North American timber basins compresses unit economics for kraft pulp converters, concentrating pricing power among suppliers with captive softwood supply and establishing cost floors that spot-market dependent competitors struggle to match. German supermarket procurement offices exploit this concentration through multi-year offtake contracts indexed to pulp futures, while smaller converters absorb margin volatility without volume leverage.
Pricing Analysis
Cost-plus contracts with Nordic pulp indexation dominate procurement between German retail chains and integrated bag manufacturers, creating three-tier pricing structure across premium, standard, and economy levels. FSC certification tiering and 80-gram basis weight engineering separate premium contract eligibility from commodity positioning. Price differentiation stems from certification grade and volume scale, with pricing pressure intensifying as supermarket category managers consolidate procurement authority under sustainability scorecard mandates. Quick-service restaurant chains exhibit highest price sensitivity due to thin takeaway margins, while e-commerce fulfillment centers prioritize tear-resistance specifications over unit cost.
Supply Chain Analysis
Sweden, Finland, and Canada anchor softwood kraft pulp production for high-tensile bag grades, with German and French converting clusters drawing from Nordic fiber supply. Raw material dependencies center on softwood pulp, water-based barrier coatings, and REACH-compliant adhesives. Supply chain risk rests on single-source vulnerability for specialized chitosan barrier formulations as PFAS coating deadlines approach. Distribution runs through supermarket private-label procurement offices and quick-service restaurant supply chain managers with direct converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German and French supermarket chains consolidate category management functions under centralized sustainability procurement offices, fragmenting supplier access and compressing margin pools for non-integrated converters.
For Market Incumbents: Consolidate backward integration into Nordic pulp supply to defend against spot-market volatility and secure FSC chain-of-custody certification ahead of 12-18 month audit timelines. Prioritize captive fiber agreements in Sweden and Finland as competitive moats against emerging recycled-content specialists. For New Entrants and Emerging Players: Differentiate on bio-based barrier coating specialization for French and Belgian quick-service restaurant channels facing REACH PFAS deadlines. Target white-space in chitosan and alginate formulation supply where pre-qualified supplier lists remain thin, leveraging technical partnership positioning with ANSM-compliant converters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pulp-to-bag operators with multi-year supermarket offtake contracts and captive Nordic fiber supply. Long-term viability favors acquisition targets with established FSC certification and German EPR fee-optimized mono-material designs. The signal to watch is supermarket procurement consolidation velocity and EPR scheme expansion across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic fiber access insulates margin volatility from timber harvest cycles. |
| FSC Certification Investment | Chain-of-custody documentation unlocks premium German and French retail contract eligibility. |
| Bio-Based Barrier Development | Chitosan formulation capabilities capture French quick-service restaurant substitution demand. |
| 80-Gram Basis Weight Engineering | German supermarket specifications reward fiber input reduction with volume placement. |
| EPR-Optimized Mono-Material Design | Simplified adhesive systems reduce Germany packaging ordinance compliance costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with supermarket category managers, quick-service restaurant supply chain directors, converting plant managers, and kraft pulp procurement leads. Secondary validation drew from EU REACH regulatory filings, ECHA chemical authorization databases, German packaging ordinance fee schedules, and FSC chain-of-custody audit records. Bottom-up volume modeling triangulated against top-down retail packaging expenditure estimates.
Across the analysis window, forecasts employed product type, end-user channel, material grade, and weight capacity segmentation with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of pulp cost trajectories, EPR scheme adoption curves, and substitution elasticity modeling against plastic bag phase-out timelines. Industry-specific inputs included Nordic timber harvest cycle data and supermarket private-label packaging procurement patterns.
Decision-makers should treat outputs as directional under sustained EU Single-Use Plastics Directive enforcement and stable Nordic pulp supply assumptions; material deviation in regulatory timelines or fiber cost volatility would warrant model refresh. Recalibration cycles align with material shifts in EPR fee structures and REACH chemical authorization updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
North America Corrugated Board Packaging Market