
 Bag-In-Box Packaging Market | 2026-2036
Bag-In-Box Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bag-In-Box Packaging Market Insights
Foodservice operators and institutional buyers is unwinding the traditional retail-centric demand model for bag-in-box packaging. Scholle IPN leverages its tap-and-bag integration expertise to anchor North American liquid food contracts. Smurfit Kappa competes through corrugated outer box specialization and European manufacturing scale. Liquibox sustains R&D intensity in aseptic filling systems for extended shelf-life applications.
Bag-in-box packaging consists of a flexible multi-layer bladder sealed inside a rigid corrugated fiberboard or solid board outer container, typically incorporating ethylene vinyl alcohol or metallized film barriers to achieve oxygen transmission rates below one cubic centimeter per square meter per day. The assembly delivers collapsible liquid containment with minimal headspace, reducing oxidation and enabling precise dispensing through integrated spigots or vitop taps. Flexible bags and outer boxes together constitute the dominant value pool, with plastic and composite materials capturing margin from barrier performance requirements. The beverage end user segment leads volume absorption, while pharmaceuticals and chemicals represent faster-growing niches demanding higher purity certifications and customized extraction ports.
FDA food contact regulations and EU REACH compliance frameworks govern material migration limits and chemical safety thresholds for bag-in-box liquid containment systems. The EU Green Deal and impending Packaging and Packaging Waste Regulation revisions are forcing redesigns toward recyclable mono-material structures and minimum recycled content thresholds. Stakeholders must monitor regulatory divergence between FDA's substance-by-substance clearance approach and Europe's broader extended producer responsibility mandates to avoid compliance fragmentation in cross-border supply chains.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material redesigns toward mono-material recyclable structures, compressing multi-layer barrier film margins while elevating corrugated outer box specifications.
Growth Catalysts
- Wine producer cost migration:French and Italian vintners are abandoning glass bottling lines for bag-in-box formats to cut logistics expenditure and reduce carbon intensity per liter shipped.
- REACH compliance acceleration:ECHA migration thresholds for ethylene vinyl alcohol and metallized films are pushing converters toward certified barrier material suppliers with pre-validated compliance dossiers.
- Aseptic filling penetration:Extended shelf-life dairy and liquid food processors are retrofitting lines with sterile bag-in-box systems to access institutional foodservice channels previously closed to refrigerated distribution.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Korean and Japanese resin producers control over 70% of high-barrier EVOH grades suitable for oxygen transmission below one cubic centimeter per square meter per day.
- Corrugated fiberboard input volatility:Kraft pulp price swings and energy costs at European paper mills are compressing outer box margins and triggering quarterly price renegotiation clauses.
- Mechanical recycling incompatibility:Multi-layer laminates combining polyethylene, EVOH, and nylon fail European sorting infrastructure tests, forcing reliance on chemical recycling with limited commercial scale.
Strategic Opportunities
- Indian wine market emergence:Maharashtra and Karnataka state excise reforms are permitting bag-in-box wine retail formats previously restricted to hospitality channels, opening volume absorption for European filling equipment exporters.
- Pharmaceutical extraction port customization:Biologic drug manufacturers require sterile sampling interfaces incompatible with standard vitop taps, creating margin-rich engineering contracts for specialized port designers.
- EU Green Deal recycled content mandates:Minimum thresholds for post-consumer plastic in packaging are advantaging converters with secured rPE and rPP supply contracts over virgin-material competitors.
Industry Challenges
- Multi-layer coextrusion technician scarcity:European and North American converters face recruitment gaps for operators capable of calibrating seven-layer blown film lines to sub-micron tolerance specifications.
- FDA substance-by-substance clearance timelines:New barrier adhesives and oxygen scavenger additives face 18-24 month pre-market notification reviews, delaying product launches versus EU REACH self-certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag-In-Box Packaging Market |
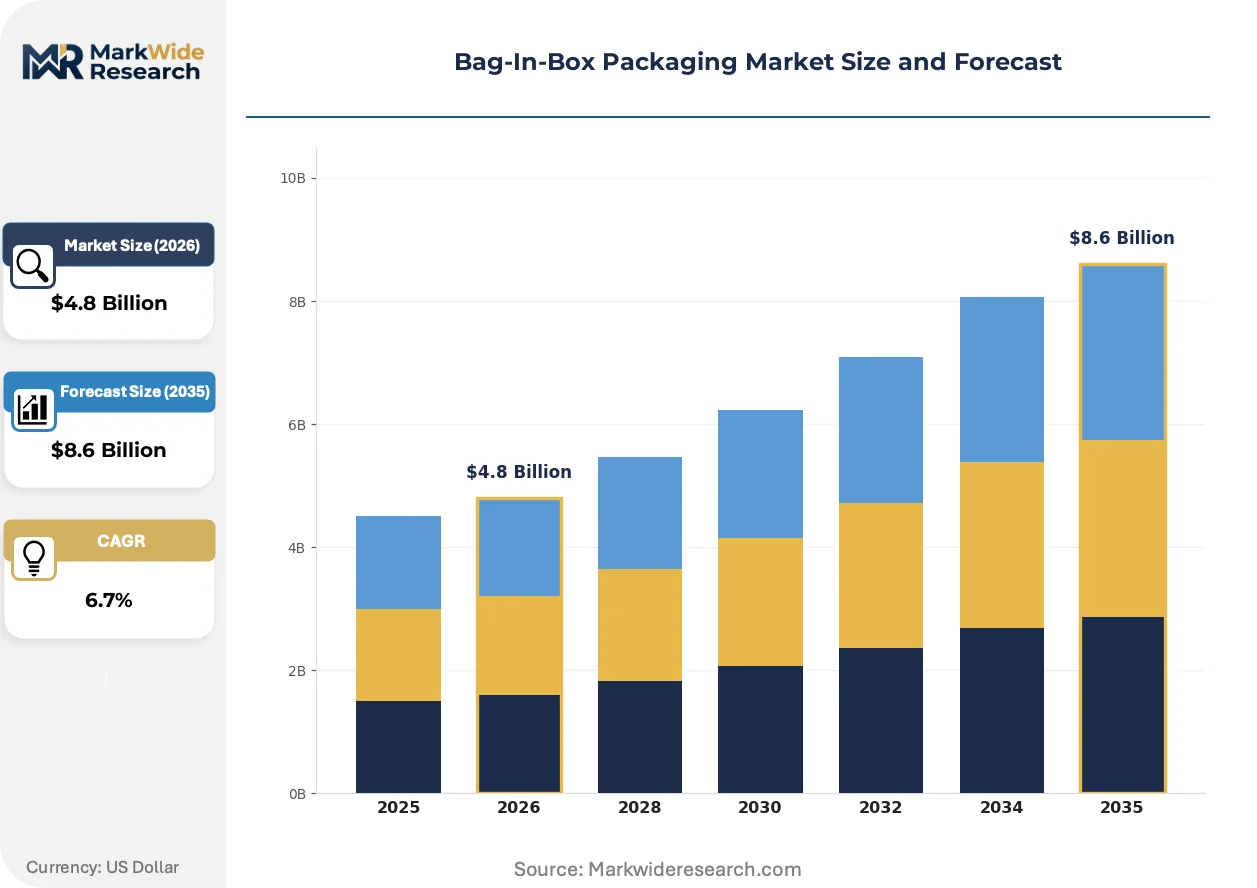
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Taps, Totes, Outer Boxes Material: Plastic, Aluminum, Cardboard, Composite End User: Beverage, Food, Pharmaceuticals, Chemicals Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Smurfit Kappa, DS Smith, Liquibox, Scholle IPN, Amcor, CDF Corporation, Mondi, Aran Group, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag-In-Box Packaging Market Trends and Innovations
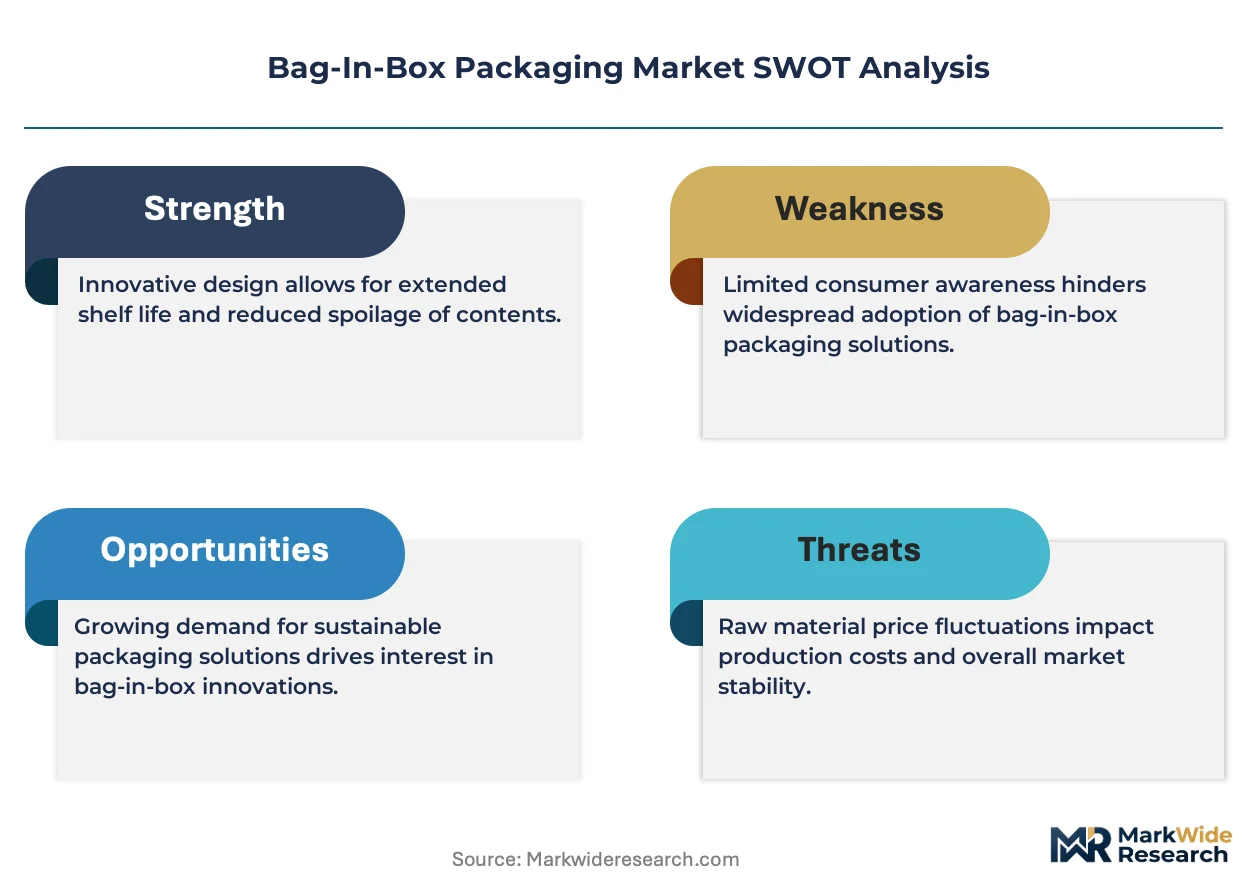
Material science breakthroughs and regulatory redesign mandates are collapsing the traditional multi-layer barrier paradigm while elevating tap-and-dispense integration as a competitive differentiator.
Metallized polyethylene terephthalate films with aluminum oxide vapor deposition are supplanting ethylene vinyl alcohol coextrusions in mid-barrier wine applications. Italian and Spanish bulk wine exporters are specifying these films for 12-month shelf-life products where oxygen ingress tolerance permits slightly elevated transmission rates. The shift is compressing EVOH resin demand in the sub-premium wine tier while expanding metallized film coating capacity.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer grease barriers from bag-in-box tap lubrication systems. German and Dutch filling equipment manufacturers are retrofitting dispensing valve designs with silicone-based alternatives and ceramic bearing surfaces. Pharmaceutical and high-purity chemical segments are absorbing the transition costs fastest due to existing cleanroom validation protocols.
Foodservice operators are consolidating procurement through group purchasing organizations that specify bag-in-box format standardization across beverage, oil, and cleaning chemical categories. Institutional buyers in the US healthcare and education sectors are mandating interchangeable tap interfaces and uniform outer box footprints to reduce warehouse slotting complexity. This concentration is visible most acutely in California and Texas state procurement contracts where volume aggregation has compressed supplier margins by 8-12 percentage points.
Bag-In-Box Packaging Market Segmentation
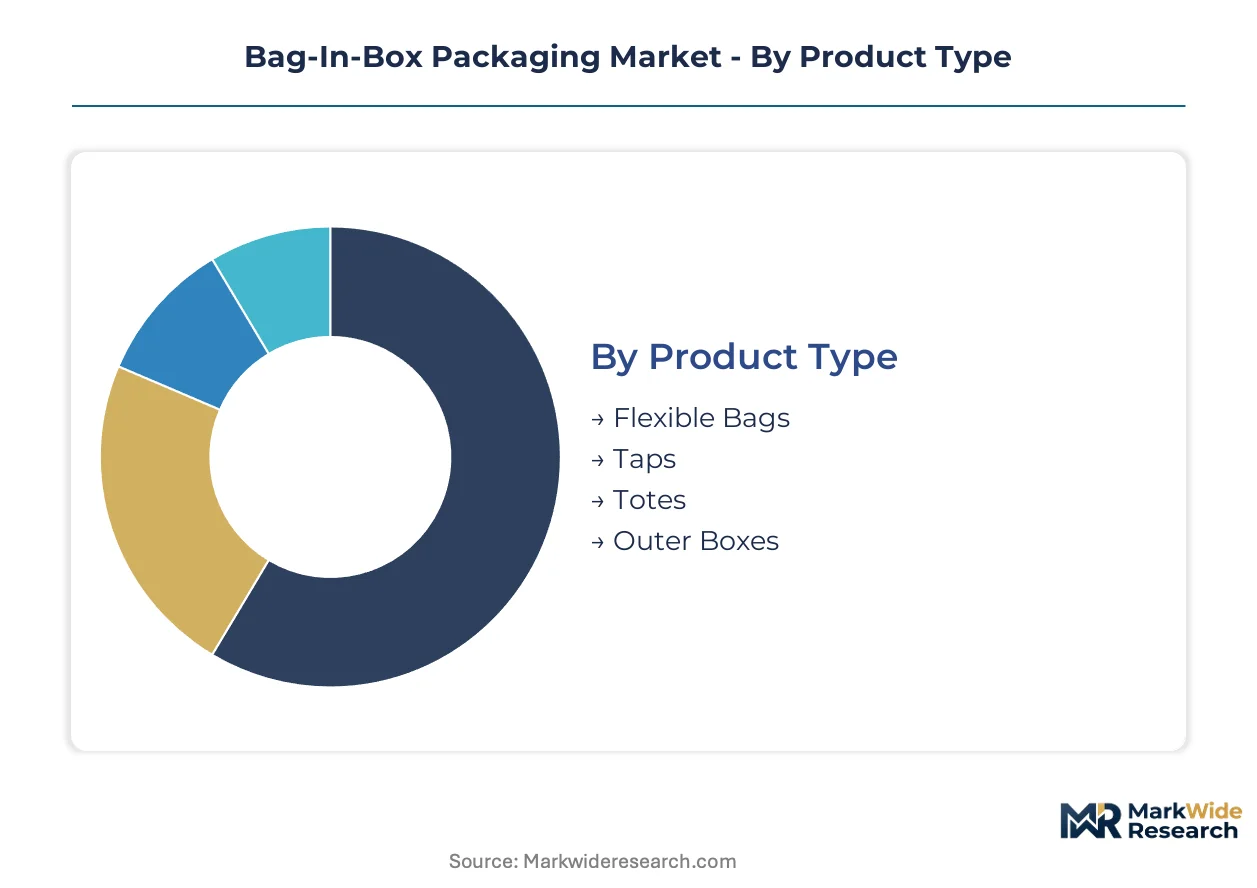
Segmentation in bag-in-box packaging reveals how material substitution pressures and regulatory redesign mandates reshape competitive positioning across product tiers. Understanding these fault lines exposes where margin pools concentrate and which configurations face imminent displacement.
Product Type:
Flexible bags face the most acute substitution threat as metallized film barriers displace traditional EVOH coextrusions in mid-shelf wine applications, while rigid outer boxes gain defensive strength from corrugated fiberboard recyclability mandates.
- Flexible Bags:Multi-layer bladders incorporating EVOH or metallized PET barriers achieve oxygen transmission below one cubic centimeter per square meter per day. French and Italian bulk wine exporters are migrating specifications toward thinner-gauge metallized films to cut resin exposure and satisfy EU Green Deal recyclability thresholds.
- Taps:Integrated dispensing valves with vitop or screw-cap interfaces incorporate silicone-based lubrication systems replacing fluoropolymer greases under REACH Annex XVII restrictions. German filling equipment manufacturers dominate engineering contracts for pharmaceutical-grade sterile sampling ports.
- Totes:Intermediate bulk containers with bag-in-box inserts target institutional foodservice and chemical distribution where volume aggregation reduces per-liter handling costs.
- Outer Boxes:Corrugated fiberboard or solid board containers provide structural rigidity and printable branding surfaces, with European mills facing margin compression from kraft pulp volatility.
Flexible bags retain volume leadership; taps hold the steepest expansion curve as foodservice standardization mandates proliferate.
Material:
Cost tier stratification separates premium barrier performance from economy-grade containment, with virgin resin exposure now penalized against recycled-content competitors under EU Packaging and Packaging Waste Regulation thresholds.
- Plastic:Polyethylene and polypropylene films form the structural backbone, with converters securing rPE and rPP supply contracts to meet minimum post-consumer content mandates.
- Aluminum:Metallized vapor-deposited layers on PET substrates deliver mid-barrier oxygen protection at lower cost than EVOH coextrusions, capturing share in 12-month shelf-life wine tiers.
- Cardboard:Kraft linerboard and fluting for outer containers face input cost volatility at European paper mills, triggering quarterly price renegotiation clauses in long-term supply agreements.
- Composite:Multi-layer laminates combining PE, EVOH, and nylon fail mechanical recycling sortation tests, forcing reliance on chemical recycling with limited commercial scale.
Plastic dominates volume absorption; aluminum composites are climbing fastest as metallized film capacity expands.
End User:
Application maturity varies sharply, with beverage volume concentration contrasting against pharmaceutical purity premiums and chemical resistance requirements.
- Beverage:Wine and spirits producers anchor demand, with French and Italian vintners abandoning glass bottling lines to cut logistics expenditure and carbon intensity per liter shipped.
- Food:Extended shelf-life dairy and liquid food processors retrofit aseptic filling lines to access institutional channels previously closed to refrigerated distribution.
- Pharmaceuticals:Biologic drug manufacturers require sterile sampling interfaces and extraction port customization incompatible with standard vitop taps, creating margin-rich engineering contracts.
- Chemicals:Industrial solvents and cleaning agents demand chemical resistance and customized extraction ports, with US healthcare and education sectors mandating interchangeable tap interfaces.
Beverage retains volume leadership; pharmaceuticals holds the steepest expansion curve driven by purity certification premiums.
Distribution Channel:
Customer type concentration through group purchasing organizations compresses supplier margins and forces format standardization across beverage, oil, and cleaning chemical categories.
- Retail:Supermarket and hypermarket channels for consumer wine and food products face format standardization pressure from private label consolidation.
- Online:E-commerce fulfillment demands optimized outer box footprints for parcel logistics, with California and Texas procurement contracts showing acute concentration effects.
- Wholesale:Institutional foodservice and industrial chemical distributors aggregate volume across categories, mandating uniform tap interfaces to reduce warehouse slotting complexity.
- Direct Sales:Equipment-integrated supply contracts for aseptic filling systems bypass distributor markups and lock in multi-year bag supply agreements.
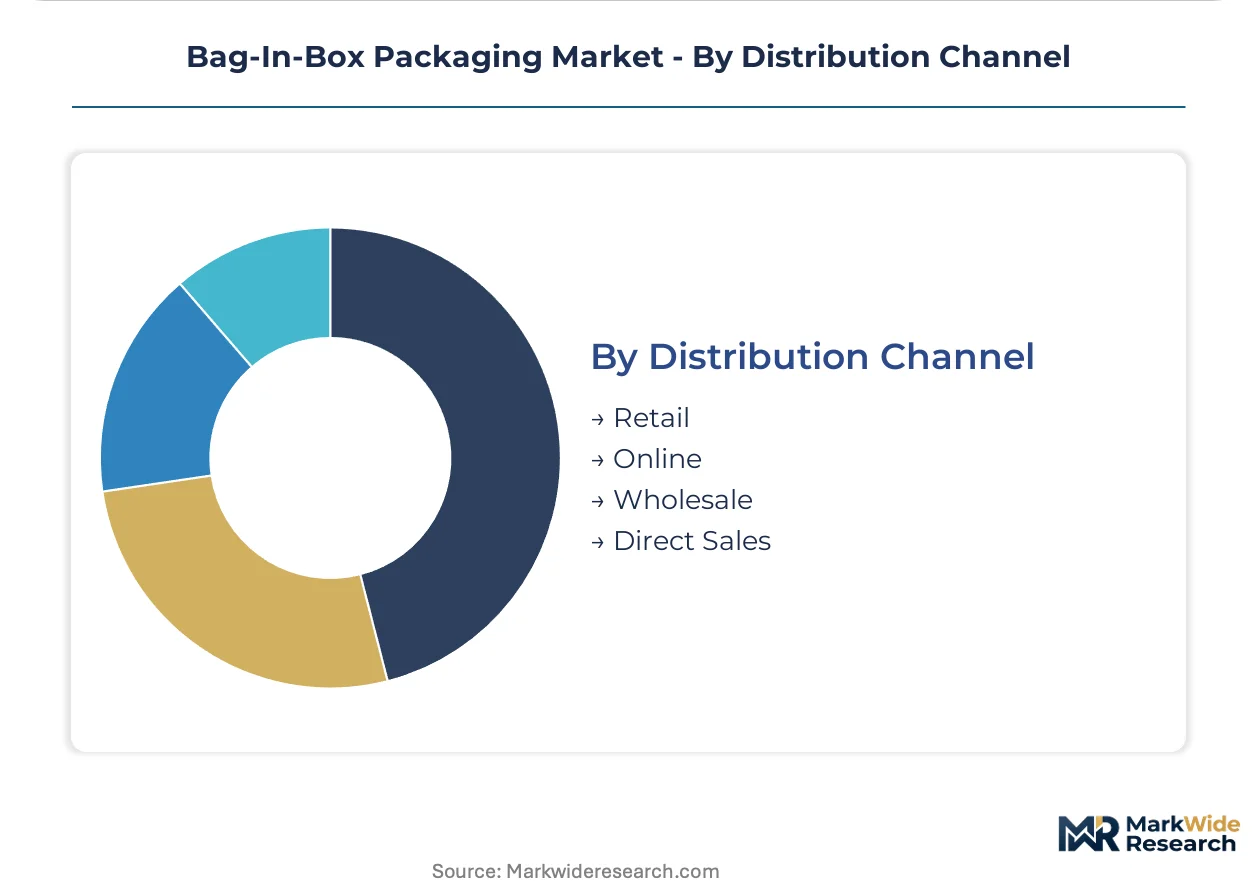
Wholesale retains volume leadership; online channels are expanding most quickly as parcel-optimized formats penetrate consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk handling infrastructure anchors European bag-in-box distribution, while the Rhine-Alpine rail corridor connects corrugated board mills to filling operations across the continent's wine belt.
France
Bordeaux and Languedoc-Roussillon vintners are converting glass bottling capacity to bag-in-box lines to reduce per-liter shipping weight. The EU Packaging and Packaging Waste Regulation mandates mono-material designs by 2030, accelerating converter investments in recyclable barrier films. The Burgundy-Beaujolais corridor now hosts three specialist filling equipment manufacturers serving premium wine exporters.
Germany
Rhineland-Palatinate packaging converters supply barrier film laminates to French and Italian wine producers under long-term supply contracts. ECHA REACH Annex XVII restrictions on fluoropolymer lubricants are forcing tap equipment redesigns toward silicone-based alternatives. The Stuttgart industrial cluster concentrates metallized PET coating capacity for mid-barrier wine applications.
Italy
Veneto and Emilia-Romagna bulk wine exporters specify thinner-gauge metallized films to cut material costs and satisfy EU Green Deal recyclability thresholds. The national competition authority is reviewing group purchasing organization contracts for potential margin compression effects on smaller converters. The Verona packaging machinery district exports aseptic filling systems to Indian and Brazilian wine markets.
United States
California Central Valley wine cooperatives aggregate bag-in-box volume through state procurement contracts that mandate standardized tap interfaces. FDA food contact substance notification timelines delay new barrier adhesive launches versus European REACH self-certification pathways. The Pacific Northwest corrugated board industry supplies outer boxes to beverage and liquid food processors nationwide.
India
Maharashtra and Karnataka state excise reforms permit bag-in-box wine retail formats previously restricted to hospitality channels. The Food Safety and Standards Authority of India is drafting liquid food packaging migration limits aligned with Codex Alimentarius standards. Nashik's wine-growing belt is attracting European filling equipment exporters targeting institutional buyers.
Bag-In-Box Packaging Market Competitive Landscape
Listed leaders compete with private specialists across barrier technology and filling equipment integration, creating a tiered structure where scale-driven corrugated converters face off against flexible film innovators. The vendor base separates into three archetypes: integrated packaging conglomerates with board and film capabilities, pure-play bag-and-tap specialists with deep liquid food expertise, and regional converters serving single-country wine markets. Dominant competitive moves include backward integration into EVOH resin sourcing and strategic partnerships with aseptic filling equipment manufacturers.
Among integrated packaging conglomerates, Smurfit Kappa and Mondi occupy positions spanning corrugated outer box production and flexible film laminating capacity. Scholle IPN and Liquibox exemplify the bag-and-tap specialist archetype, with Scholle IPN representing deep integration between dispensing valve engineering and flexible bladder manufacturing. These named entities anchor the competitive landscape without exhausting its full composition.
| Leading Market Players |
|---|
| Smurfit Kappa |
| DS Smith |
| Liquibox |
| Scholle IPN |
| Amcor |
| CDF Corporation |
| Mondi |
| Aran Group |
| International Paper |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day inventory cycles for EVOH resin and metallized film stock expose converters to both Korean-Japanese supply concentration and quarterly kraft pulp renegotiation clauses, compressing margin buffers across the value chain while amplifying pricing power for backward-integrated specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs bag-in-box procurement, with barrier performance certification and volume scale as the primary differentiation drivers. Premium tiers capture margin through sub-one-cc-per-square-meter-per-day oxygen transmission specifications validated by ECHA REACH dossiers, while economy segments face intensifying cost compression from group purchasing organization consolidation. Institutional foodservice buyers in California and Texas exhibit highest price sensitivity, whereas pharmaceutical biologics manufacturers absorb premium positioning for sterile port customization.
Supply Chain Analysis
Inbound logistics costs on Asia-Europe container lanes and Rhine-Alpine rail congestion expose European converters to inventory carrying cost volatility. Supply concentrates in South Korea, Japan, and Germany for high-barrier EVOH resins and metallized PET coating capacity, with corrugated fiberboard feeds from Swedish and Finnish kraft pulp mills. Single-source vulnerability for seven-layer blown film line technicians amplifies operational risk. Distribution runs through Rotterdam liquid bulk terminals and regional filling equipment clusters in Verona and Stuttgart.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against aseptic carton and pouch formats penetrating extended shelf-life dairy, requiring strategic repositioning around barrier performance certification and tap integration lock-in.
For Market Incumbents: Compound defensive positioning through captive EVOH resin sourcing agreements with Korean suppliers and in-house production of metallized PET coating capacity at Stuttgart-area facilities. Accelerate sterile port engineering contracts with German filling equipment manufacturers to lock out aseptic carton substitutes from pharmaceutical channels. Prioritize REACH Annex XVII pre-validation dossiers to compress competitor product launch timelines.
For New Entrants and Emerging Players: Lead with pharmaceutical-grade extraction port customization as the most penetrable white-space segment, where biologic drug manufacturers pay certification premiums incompatible with standard vitop tap designs. Target Maharashtra and Karnataka state excise reforms in India for volume absorption of economy-tier wine formats. Pursue equipment-integrated supply contracts that bypass distributor markups and secure multi-year bag supply lock-in.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated packaging conglomerates divesting non-core flexible film laminating capacity under EU Green Deal recyclability mandates. Five-to-ten-year viability hinges on secured rPE and rPP supply contracts advantaging converters over virgin-material competitors. Monitor ECHA migration threshold tightening for ethylene vinyl alcohol as the inflection signal for barrier material substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin Sourcing | Korean and Japanese suppliers control seventy percent of high-barrier grades suitable for wine applications. |
| Sterile Port Engineering Partnership | German filling equipment manufacturers dominate pharmaceutical-grade extraction interface contracts. |
| Metallized PET Coating Capacity Expansion | Italian and Spanish bulk wine exporters specify aluminum oxide vapor deposition for mid-barrier tiers. |
| Recycled Content Supply Contracting | EU Packaging and Packaging Waste Regulation minimum thresholds penalize virgin resin exposure. |
| Aseptic Filling Equipment Integration | Extended shelf-life dairy processors retrofit lines to access institutional foodservice channels. |
Research Methodology
A standing panel of flexible film plant managers, corrugated board procurement leads at European mills, wine cooperative logistics directors, pharmaceutical packaging engineers, and aseptic filling equipment specialists provided ongoing calibration. Primary interview findings triangulated against secondary validation from ECHA REACH registration dossiers, EU Packaging and Packaging Waste Regulation impact assessments, FDA food contact substance notifications, and customs trade data on EVOH resin flows. Bottom-up volume modeling from filling line capacity installations reconciled with top-down value estimates across the analysis window.
Consistency checks against external benchmarks validated output robustness. The analytical framework segmented volume and value across product type, material composition, end-use application, and distribution channel throughout the projection horizon. CAGRs derived from regression analysis of historical capacity utilization and forward-looking regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated ECHA migration threshold revision timelines and EU Green Deal recycled content mandate phase-in schedules.
Forecasts assume regulatory continuity in EU REACH and FDA food contact frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated fluoropolymer lubricant bans, kraft pulp price spike persistence beyond quarterly renegotiation clauses, and chemical recycling scale-up failures for multi-layer laminates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Bag Clips Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Commodity Liners Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Nonwoven Containers Market