
 Mesh Bags Market | 2026-2036
Mesh Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Mesh Bags Market Foresight
Buyer concentration among European retail chains is recalibrating procurement volumes for mesh bag suppliers. Karatzis leverages its Mediterranean manufacturing base to sustain cost-competitive exports across EU grocery networks. LC Packaging anchors its position through certified food-contact compliance programs that dominate Nordic retail specifications. Nutec Manufacturing competes on custom weaving capabilities for high-durability produce handling.
Mesh bags are woven textile containers engineered from monofilament or multifilament yarns with calibrated apertures between 2 mm and 10 mm, designed for breathable containment of agricultural goods and consumer merchandise. Their open structure permits airflow that reduces moisture accumulation during transport and storage of perishables. Reusable mesh bags command the widest margin pools as retail chains shift from disposable formats under extended producer responsibility frameworks. Polypropylene material grades represent the fastest-growing segment due to tensile strength advantages and compatibility with industrial recycling streams. Bulk mesh bags remain mature in agricultural wholesale channels where price sensitivity limits innovation uptake.
FDA food-contact regulations and EU REACH compliance requirements shape material selection and migration testing protocols for mesh bag producers targeting developed markets. The EU Packaging and Packaging Waste Regulation, California's SB 54 recycling mandates, and India's Plastic Waste Management Rules collectively tighten specifications for reusable packaging formats. Stakeholders must monitor evolving extended producer responsibility thresholds to anticipate which material certifications will become mandatory for market access.
Market Dynamics
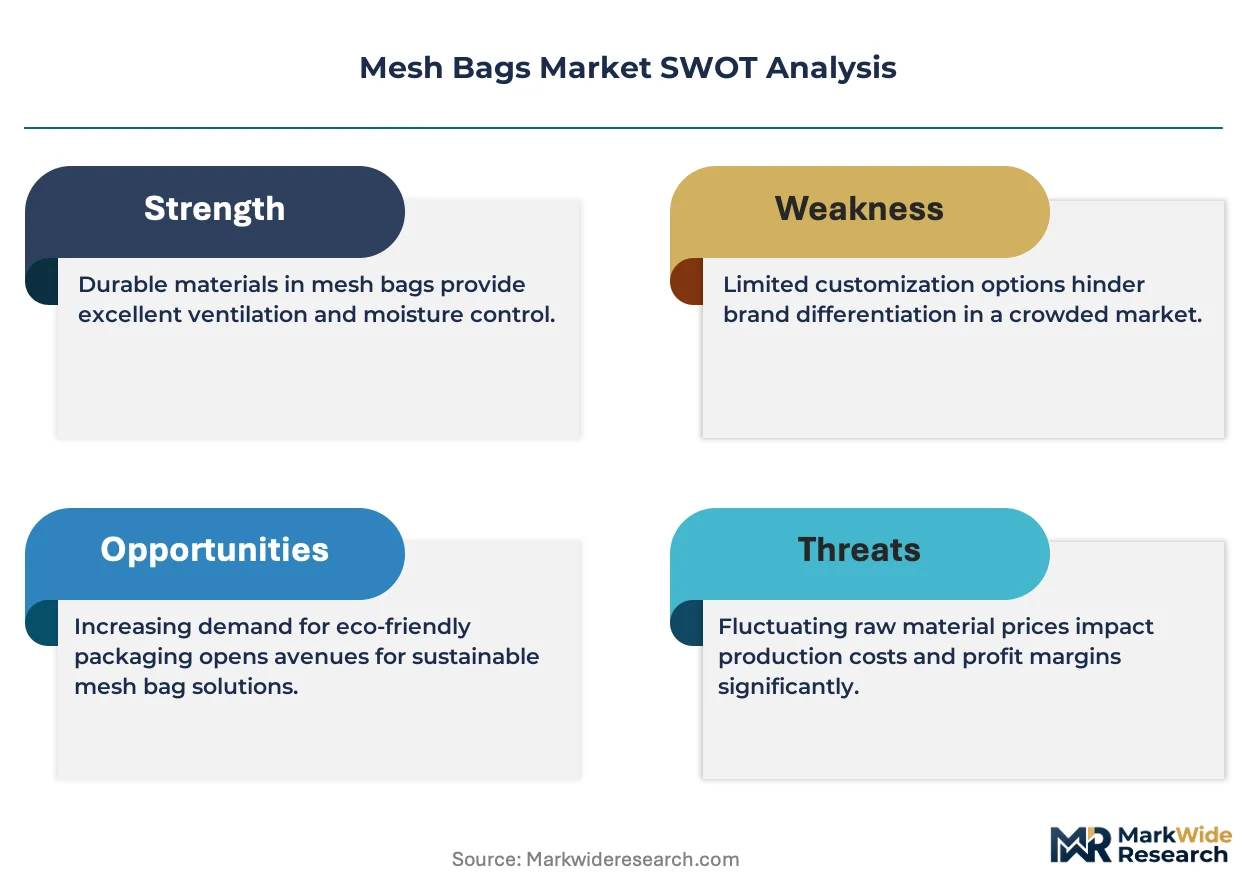
Extended producer responsibility frameworks are redistributing packaging procurement volumes toward certified reusable formats as retail chains internalize end-of-life costs previously borne by municipal waste systems.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for disposable food packaging are redirecting grocery procurement toward certified mesh alternatives across German and French retail networks.
- Polypropylene recycling infrastructure:Industrial-scale mechanical recycling streams for PP monofilament are closing material loops and lowering net input costs for bag manufacturers.
- California SB 54 mandates:Source reduction and recyclability requirements for plastic packaging are accelerating retailer adoption of reusable mesh formats in produce and bulk goods sections.
Market Restraints
- Petrochemical feedstock volatility:Propylene monomer price swings directly compress margin pools for extruded mesh producers without long-term supply contracts.
- Weaving equipment concentration:Specialized circular loom manufacturing concentrates in Chinese industrial clusters, creating import dependency and lead time exposure for European converters.
- Competing fiberboard and molded pulp formats:Corrugated produce trays and pressed fiber containers are capturing shelf space in premium organic retail segments.
Strategic Opportunities
- Indian Plastic Waste Management Rules enforcement gaps:Tier-2 and Tier-3 city retail modernization is creating first-mover advantage for reusable bag suppliers ahead of formal compliance deadlines.
- RFID-embedded traceability:Convergence of woven textile manufacturing with passive sensor integration is enabling deposit-return scheme participation and inventory automation.
- B2B rental pooling models:Third-party logistics providers are piloting mesh container leasing for agricultural cooperatives, shifting capital burden from growers to service operators.
Industry Challenges
- Migration testing capacity:EU REACH food-contact certification backlogs at accredited laboratories are extending product launch timelines by six to twelve months.
- Colorant reformulation:Heavy metal-free pigment transitions for food-contact compliance are requiring full production line recalibration and scrap rate increases during qualification.
- Legacy ERP integration:Batch-level traceability requirements for extended producer responsibility reporting are forcing mid-tier weavers to replace manual inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesh Bags Market |
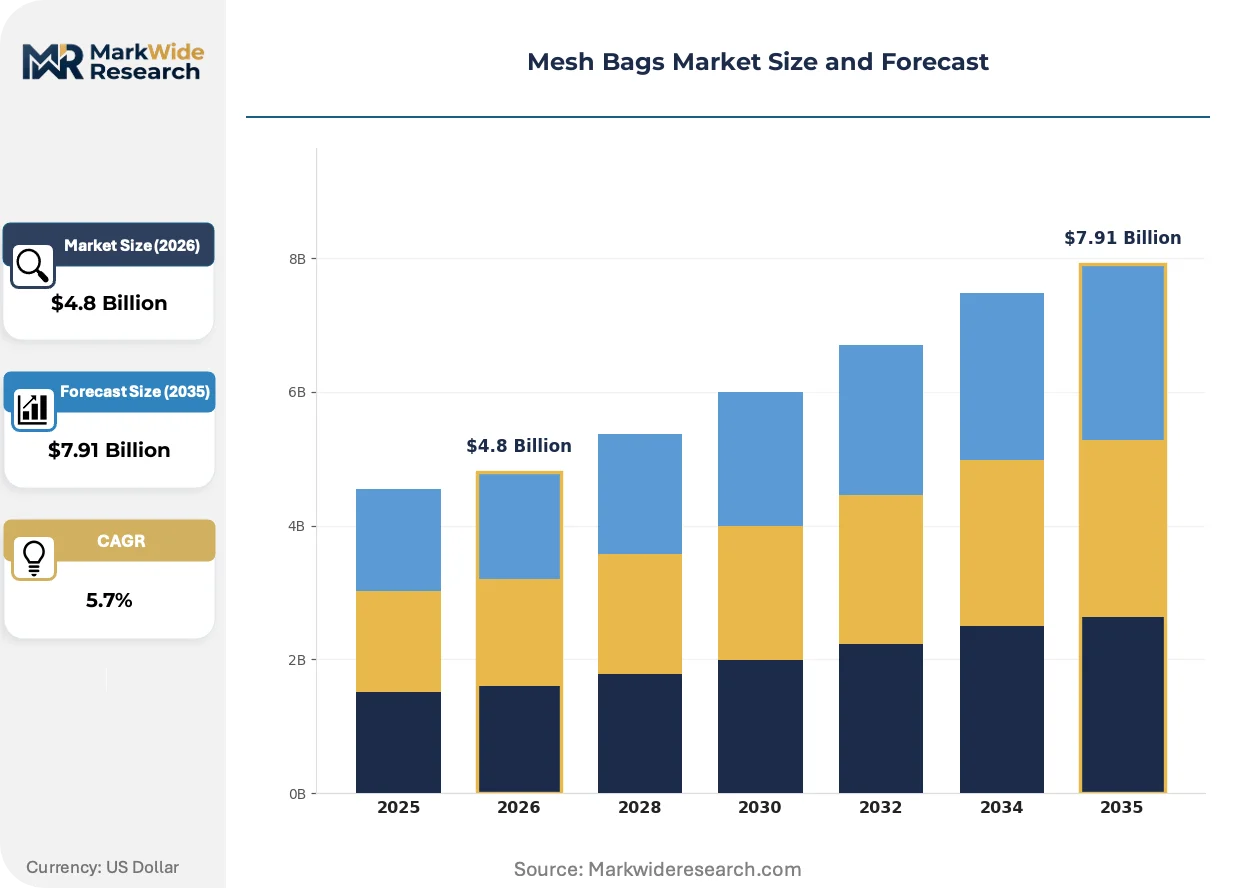
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Mesh Bags, Drawstring Mesh Bags, Bulk Mesh Bags, Produce Mesh Bags Material: Polyester, Nylon, Cotton, Polypropylene End User: Retail Chains, Grocery Stores, Wholesalers, E-commerce Platforms Application: Grocery Shopping, Packaging, Storage, Recycling |
| Companies Covered | Volm Companies, Karatzis, Agribag International, Vedder Industrial, Knack Packaging Private Limited, Nutec Manufacturing, Tex-Pro, Tufbag Industrial, LC Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesh Bags Market Shifts & Advancements
Material science advances and digital traceability are compressing the gap between commodity woven containers and smart packaging systems capable of supporting circular economy business models.
Post-consumer recycled polypropylene is absorbing growing shares of virgin polymer demand in European mesh bag production. German retail chains now specify minimum recycled content thresholds in produce bag tenders. The technology is absorbing price premiums previously commanded by virgin grades as mechanical recycling yields improve and batch consistency stabilizes.
REACH SVHC candidate list expansion is forcing reformulation of plasticizers and UV stabilizers used in outdoor agricultural mesh. ECHA screening assessments for endocrine-disrupting properties are accelerating substitution of legacy additive packages. Nordic grocery retailers are responding with preemptive bans on substances not yet formally restricted, creating specification divergence across EU member states.
Deposit-return scheme participation is altering procurement criteria for reusable produce bags. Dutch supermarket chains now prioritize mesh formats compatible with automated washing and sorting infrastructure. The shift is most visible in Benelux markets where packaging pool operators have achieved critical mass in reverse logistics coverage.
Mesh Bags Market Segmentation
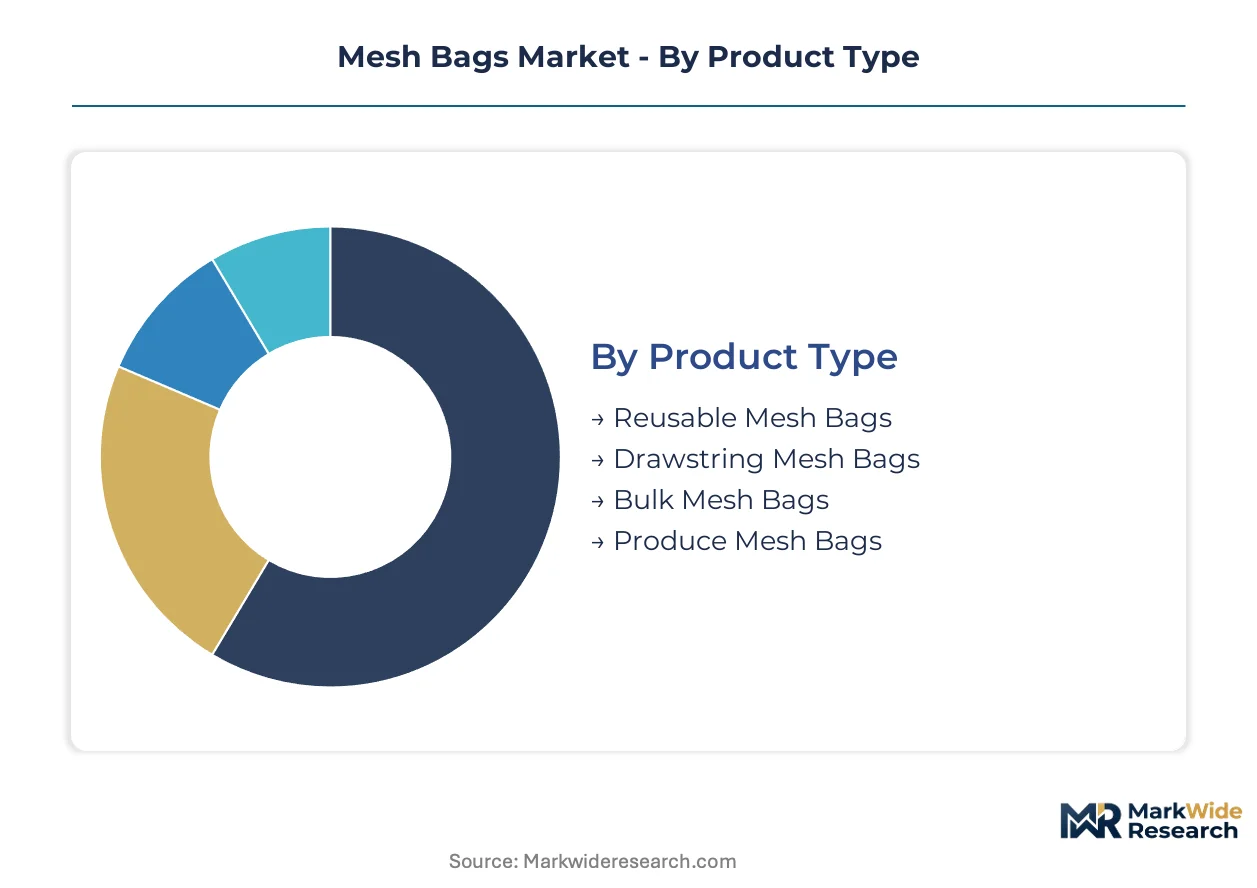
Mesh bag suppliers configure production lines around distinct use-case durability requirements and regulatory exposure levels. Segmentation clarity determines which material grades and weaving specifications capture procurement volume from retail compliance programs versus agricultural spot markets.
Product Type:
Integration depth separates standalone consumer formats from embedded supply-chain infrastructure serving automated logistics networks.
- Reusable Mesh Bags:Woven polypropylene or cotton constructions rated for 100+ wash cycles, specified by EU retail chains under extended producer responsibility mandates. German supermarket networks now mandate these formats for produce sections ahead of national compliance deadlines.
- Drawstring Mesh Bags:Closure-integrated designs using braided cord locks or heat-sealed channels, favored by organic food cooperatives and farmers market vendors for self-service bulk dispensing. Nordic retailers specify these for nut and grain sections to reduce spillage losses.
- Bulk Mesh Bags:High-capacity formats with reinforced lifting straps and 50 kg+ load ratings, serving agricultural wholesale channels for onion, potato, and citrus handling.
- Produce Mesh Bags:Lightweight 2-5 mm aperture designs optimized for breathable containment of soft fruits, standard in North American grocery produce aisles.
Volume placements concentrate in Reusable Mesh Bags; the faster expansion belongs to Drawstring Mesh Bags as bulk dispensing infrastructure spreads.
Material:
Cost tiers stratify around virgin polymer premiums versus recycled-content specifications and natural fiber processing overheads.
- Polypropylene:Extruded monofilament grades dominate industrial applications for tensile strength and compatibility with mechanical recycling streams. REACH-compliant UV stabilizer packages are becoming mandatory for outdoor agricultural use.
- Nylon:Multifilament constructions offer abrasion resistance for heavy-duty handling, though petrochemical feedstock volatility compresses margins for producers without long-term supply contracts.
- Polyester:PET monofilament alternatives with lower moisture absorption, specified for humid climate storage applications.
- Cotton:Natural fiber formats command certification premiums in organic retail segments, constrained by water-intensive cultivation and dye compliance costs.
Procurement volumes cluster in Polypropylene; Cotton climbs the fastest as organic certification thresholds tighten.
End User:
Customer-type segmentation tracks purchasing sophistication from centralized retail compliance teams to fragmented agricultural procurement.
- Retail Chains:Centralized sustainability procurement offices specifying certified reusable formats with batch-level traceability for extended producer responsibility reporting. French and German networks lead specification complexity.
- Grocery Stores:Independent and small-chain operators balancing unit economics against local plastic restriction enforcement, concentrated in California and EU member states with active mandate implementation.
- Wholesalers:Price-sensitive volume purchasers for agricultural distribution, prioritizing load capacity over certification compliance.
- E-commerce Platforms:Emerging channel with packaging standardization requirements for automated fulfillment centers, specifying uniform dimensions for sorting machinery compatibility.
Contract value concentrates in Retail Chains; E-commerce Platforms gain share fastest as direct-to-consumer fresh produce delivery scales.
Application:
Use-case maturity spans established grocery workflows versus emerging circular economy infrastructure still achieving critical mass.
- Grocery Shopping:Point-of-sale consumer-facing formats, now subject to single-use plastic bans across EU member states and California retail environments.
- Packaging:Industrial containment for agricultural transport, where breathable structures reduce spoilage versus sealed alternatives.
- Storage:Long-duration agricultural and warehouse applications requiring UV resistance and pest-exclusion specifications.
- Recycling:Deposit-return scheme participation driving demand for automated washing-compatible designs in Dutch and Belgian supermarket networks.
Deployment scale concentrates in Grocery Shopping; Recycling applications expand most steeply as reverse logistics infrastructure achieves coverage density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail procurement offices in Germany are concentrating demand for certified reusable formats ahead of EU Packaging and Packaging Waste Regulation deadlines. French supermarket chains are mandating batch-level traceability specifications. California's SB 54 implementation is redirecting produce aisle procurement toward mesh alternatives.
Germany
Centralized sustainability procurement at Rewe and Edeka networks is specifying minimum recycled content thresholds for produce bag tenders. The EU Single-Use Plastics Directive reduction targets are accelerating format transitions ahead of national transposition deadlines. Manufacturing clusters in North Rhine-Westphalia are scaling post-consumer recycled polypropylene processing capacity for retail contract fulfillment.
France
Carrefour and Intermarché compliance teams are requiring REACH-certified UV stabilizer packages for outdoor agricultural mesh applications. ECHA screening assessments for endocrine-disrupting properties are preemptively banning legacy additive formulations. Lyon-based textile converters are reformulating colorant systems to eliminate heavy metal pigments ahead of formal restrictions.
United States
California grocery retailers are sourcing reusable mesh formats to meet SB 54 source reduction mandates for produce and bulk goods sections. FDA food-contact regulations are shaping migration testing protocols for bag producers targeting West Coast retail networks. Los Angeles-area logistics hubs are piloting RFID-embedded traceability for deposit-return scheme participation.
India
Tier-2 and Tier-3 city retail modernization in Maharashtra and Gujarat is creating first-mover procurement opportunities ahead of Plastic Waste Management Rules enforcement. FSSAI food-contact compliance requirements are emerging as procurement gatekeepers for organized retail chains. Ahmedabad weaving clusters are expanding circular loom capacity to serve domestic grocery network expansion.
Netherlands
Albert Heijn and Jumbo supermarket chains are prioritizing mesh formats compatible with automated washing infrastructure for packaging pool participation. Extended producer responsibility frameworks are internalizing end-of-life costs previously borne by municipal waste systems. Rotterdam port logistics operators are developing reverse logistics coverage for agricultural cooperative container pooling.
Mesh Bags Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue RFID-embedded traceability and rental pooling models as differentiation vectors. The vendor base stratifies around Mediterranean manufacturing cost positions, Nordic compliance certification depth, and custom weaving capability specialization. Three archetypes dominate: vertically integrated extrusion-to-bag converters, compliance-focused certification specialists, and flexible job-shop weavers serving agricultural spot markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as retailers consolidate procurement volumes.
Among Mediterranean-based fabricators, Karatzis anchors the cost-competitive export tier serving EU grocery networks. LC Packaging exemplifies the compliance-specialist archetype through certified food-contact programs dominating Nordic retail specifications. Nutec Manufacturing occupies a position within the custom-weaving tier for high-durability produce handling applications. These three entities represent distinct strategic postures without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Volm Companies |
| Karatzis |
| Agribag International |
| Vedder Industrial |
| Knack Packaging Private Limited |
| Nutec Manufacturing |
| Tex-Pro |
| Tufbag Industrial |
| LC Packaging |
| Others |
Supply & Pricing Matrix
Propylene monomer feedstock costs cascade through extrusion-to-bag converters, compressing margin pools for European weavers lacking long-term supply contracts while rewarding Mediterranean fabricators with captive polymer sourcing. Retail procurement offices in Germany and France now specify minimum recycled content thresholds, bifurcating pricing tiers between virgin-grade agricultural spot markets and certified reusable formats commanding compliance premiums.
Pricing Analysis
Volume placements concentrate in bulk agricultural channels where price sensitivity limits innovation uptake, while margin pools accrue to REACH-certified reusable formats specified by EU retail chains. Three-tier pricing structure across premium certification-grade, standard food-contact, and economy agricultural tiers separates compliant producers from commodity weavers. Pricing pressure stems from petrochemical feedstock volatility and competing fiberboard formats capturing organic retail shelf space. Wholesalers exhibit highest price sensitivity; centralized retail sustainability procurement offices demonstrate lowest sensitivity due to extended producer responsibility cost internalization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese industrial clusters dominating specialized circular loom manufacturing, creating import dependency and lead time exposure for European converters. Raw material sourcing draws from Saudi Arabian and Qatari propylene feedstock, German recycled polypropylene processing capacity, and Indian cotton cultivation belts. Supply chain risk centers on tariff exposure for weaving equipment imports and REACH SVHC candidate list expansion forcing additive reformulation. Distribution runs through Rotterdam and Hamburg port logistics hubs serving retail network consolidation, with agricultural cooperatives sourcing direct from Mediterranean extrusion plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH food-contact certification backlogs at accredited laboratories erect barrier-to-entry moats favoring incumbents with established testing relationships.
For Market Incumbents: Acquire accredited laboratory testing capacity or secure exclusive queue priority at ECHA-recognized facilities to compress product launch timelines. Backward integration into post-consumer recycled polypropylene processing in North Rhine-Westphalia secures raw material cost positions against virgin polymer volatility. Defensive positioning requires pre-emptive reformulation of UV stabilizer packages ahead of ECHA endocrine-disrupting property screenings, as Nordic retailers already ban legacy additives not yet formally restricted. For New Entrants and Emerging Players: RFID-embedded traceability integration offers technology-first wedge into Dutch and Belgian deposit-return scheme infrastructure where automated washing compatibility specifications remain under-penetrated. Target tier-2 and tier-3 Indian city retail modernization ahead of Plastic Waste Management Rules enforcement gaps, leveraging Ahmedabad weaving cluster capacity expansion. Go-to-market positioning as FSSAI food-contact compliance specialists for organized retail chains replaces commodity weaving in fragmented agricultural spot markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-specialist weavers with REACH-certified production lines in Benelux and Nordic markets where retailer consolidation concentrates procurement volumes. Long-term viability over the mid-decade horizon rests on circular economy infrastructure maturation and extended producer responsibility threshold expansion across EU member states. Monitor ECHA screening assessment publication schedules as inflection indicator for additive reformulation cost spikes and qualification timeline extensions.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | ECHA-recognized laboratory partnerships compress six-to-twelve month product launch backlogs for retail contract eligibility. |
| Post-Consumer Recycled PP Processing | German retail chain tender specifications now mandate minimum recycled content thresholds for produce bag procurement. |
| RFID Traceability Integration | Dutch supermarket deposit-return schemes prioritize mesh formats compatible with automated washing infrastructure. |
| Backward Integration into Extrusion | Captive propylene monomer sourcing insulates margin pools from petrochemical feedstock volatility exposure. |
| Indian Market Entry | Tier-2 city retail modernization ahead of Plastic Waste Management Rules enforcement creates first-mover positioning. |
Research Methodology
Document review covered EU Packaging and Packaging Waste Regulation implementation schedules, ECHA SVHC candidate list expansions, and FDA food-contact migration testing protocols, complemented by interviews with sustainability procurement directors at German and French retail chains, technical directors at Mediterranean extrusion-to-bag converters, and compliance officers at REACH-accredited testing laboratories. Secondary validation drew from customs trade data for polypropylene monofilament imports, SEC filings of listed packaging converters, and national transposition documents for EU Single-Use Plastics Directive deadlines. Bottom-up volume estimates from weaving capacity utilization and top-down retail procurement spend analysis were triangulated for convergence.
Segment-level value outputs across the projection horizon reflect modeled interactions between material grade specifications, end-use durability requirements, and regulatory compliance tier penetration. Segmentation dimensions included product type integration depth, material grade certification status, end-user purchasing sophistication, and application maturity within circular economy infrastructure. CAGRs were derived from regression analysis of historical retail procurement volumes against regulatory deadline proximity and mechanical recycling capacity expansion curves. Forecast inputs incorporated ECHA screening assessment timelines and Indian organized retail network expansion trajectories.
Several conditions sit outside the modeled scope, including unforeseen ECHA additive restriction acceleration, abrupt propylene supply disruptions from geopolitical events, and breakthrough molded pulp format cost reductions displacing mesh in premium organic segments. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and recycling infrastructure buildout pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Woven Sacks Market
Bags and Containers
Bag Clips Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Bulk Tote Dumpers Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Counter Bags Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Liquid Packaging Bag Market