
 United States Natural Gas Market | 2026-2036
United States Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
United States Natural Gas Market Analytics
Master limited partnership restructuring and asset-light midstream spin-offs is rewriting competitive entry barriers for upstream producers. EQT Corporation leverages Appalachia's Marcellus position through scaled horizontal drilling programs. Cheniere Energy anchors Gulf Coast LNG export capacity with long-term offtake contracting. ExxonMobil Corporation dominates integrated gas-to-liquids operations across the Permian and Bakken basins.
Natural gas comprises methane-dominated hydrocarbon mixtures extracted through conventional vertical drilling or unconventional hydraulic fracturing, with specifications typically requiring 90-95% methane content for pipeline injection and combustion efficiency in turbines and boilers. The type segmentation splits between conventional onshore reservoirs, unconventional shale plays, liquefied natural gas for marine transport, and compressed natural gas for vehicle fueling. Unconventional production from the Permian and Marcellus formations leads volume contribution, while LNG exports represent the fastest-growing margin pool as global arbitrage widens. Application demand from power generation commands the largest share of delivered volumes, though industrial heating sustains higher per-unit profitability through long-term baseload contracts.
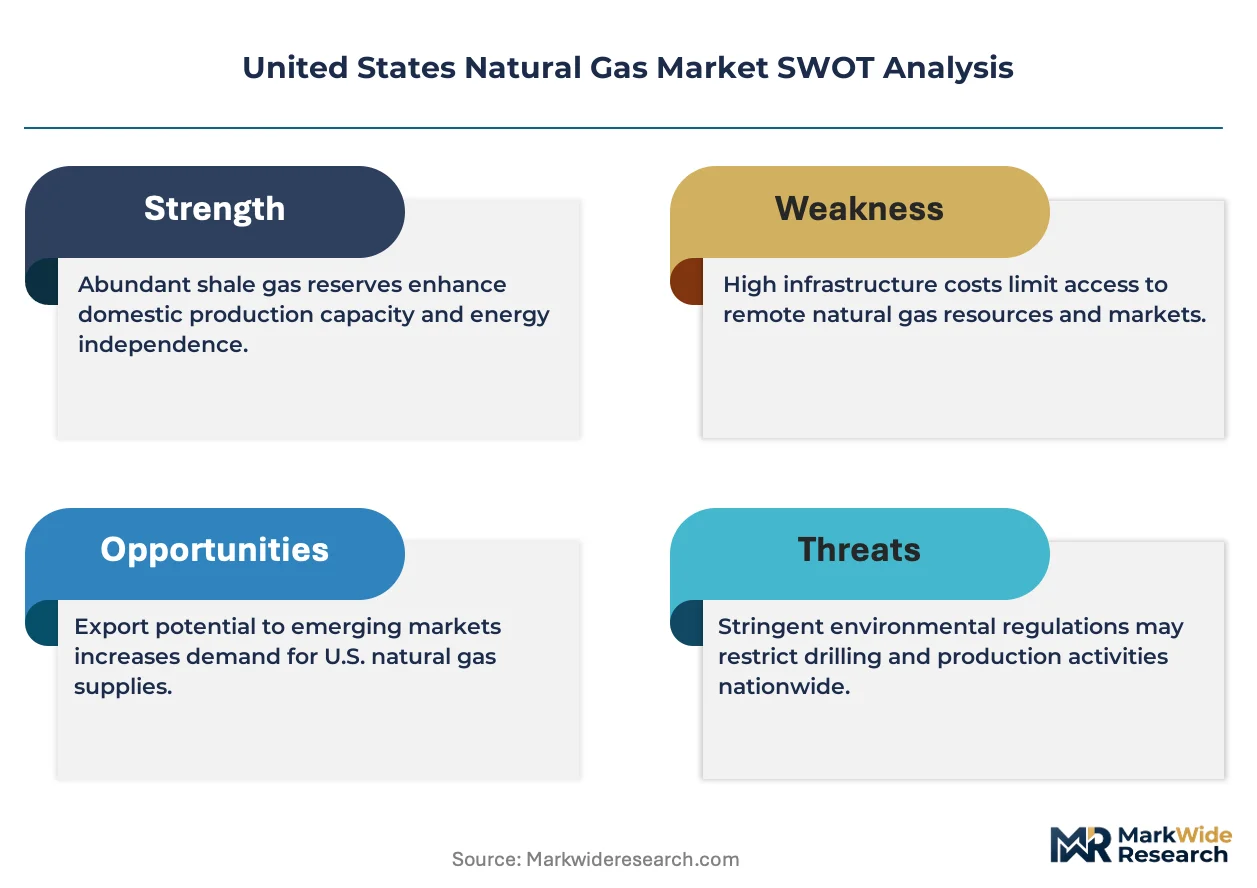
FERC governs interstate pipeline rates and siting approvals, while EPA methane rules under the Inflation Reduction Act impose escalating fees on vented and leaked emissions. OSHA standards for confined-space entry and process safety management shape operational compliance costs across gathering and processing facilities. State regulators in Texas and Pennsylvania overlay additional wellhead integrity and water disposal requirements. Stakeholders must monitor how FERC's evolving certificate policy for new pipeline construction alters regional basis differentials and producer netbacks.
Market Dynamics
The EPA's methane emissions fee structure under the Inflation Reduction Act is compressing wellhead economics and forcing capital reallocation toward leak detection infrastructure across the Permian and Appalachian basins.
Growth Catalysts
- Power generation fuel switching:Retiring coal capacity across the Ohio River Valley and Southwest is redirecting baseload demand toward combined-cycle gas turbines. Utilities in Texas and Pennsylvania are contracting long-term pipeline deliveries to anchor dispatch reliability.
- IRA methane fee escalation:The Inflation Reduction Act's escalating charges on vented emissions are accelerating optical gas imaging and continuous monitoring deployment at gathering facilities. Midstream operators are consolidating pad sites to reduce fugitive source density.
- Gulf Coast LNG terminal expansion:Brownsville and Corpus Christi liquefaction trains are absorbing excess Marcellus and Haynesville supply. Export offtake contracting is pulling Appalachian production south through new pipeline reversals.
Market Restraints
- Steel input cost volatility:Pipeline grade steel and OCTG tubulars fluctuate with scrap metal and alloy surcharges. Gathering system buildouts in the Bakken face 18-24 month delivery lags on high-yield line pipe.
- FERC certificate policy uncertainty:Interstate pipeline approvals now require climate impact documentation that extends pre-construction timelines. Northeast supply growth is bottlenecked by constrained capacity into New England demand centers.
- Renewable plus storage substitution:Utility-scale solar and battery configurations in California and the Southwest are eroding gas-fired peaker economics. Merchant generators face capacity factor compression during high-renewable output hours.
Strategic Opportunities
- Hydrogen blending infrastructure:Gulf Coast pipeline repurposing for hydrogen-natural gas mixtures is attracting utility pilot funding. Texas industrial corridors are positioning for federal hydrogen hub grants under the IRA.
- Certified Responsibly Sourced Gas:Third-party methane intensity verification is opening premium contracting channels to European LNG buyers. Appalachian producers with low-leak operations are capturing basis premiums over Permian supply.
- Direct air capture co-location:Permian gas-fired power and CO2 pipeline networks are enabling integrated carbon removal projects. EOR operators are contracting fixed-price CO2 offtake from DAC facilities.
Industry Challenges
- Emissions quantification skill scarcity:Continuous monitoring system deployment requires technicians trained in optical spectroscopy and data analytics. Baseline survey firms are poaching talent from upstream engineering departments.
- Legacy SCADA integration:Leak detection algorithms must interface with decades-old distributed control systems at fractionation plants. Cybersecurity hardening of field sensors adds commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Natural Gas Market |
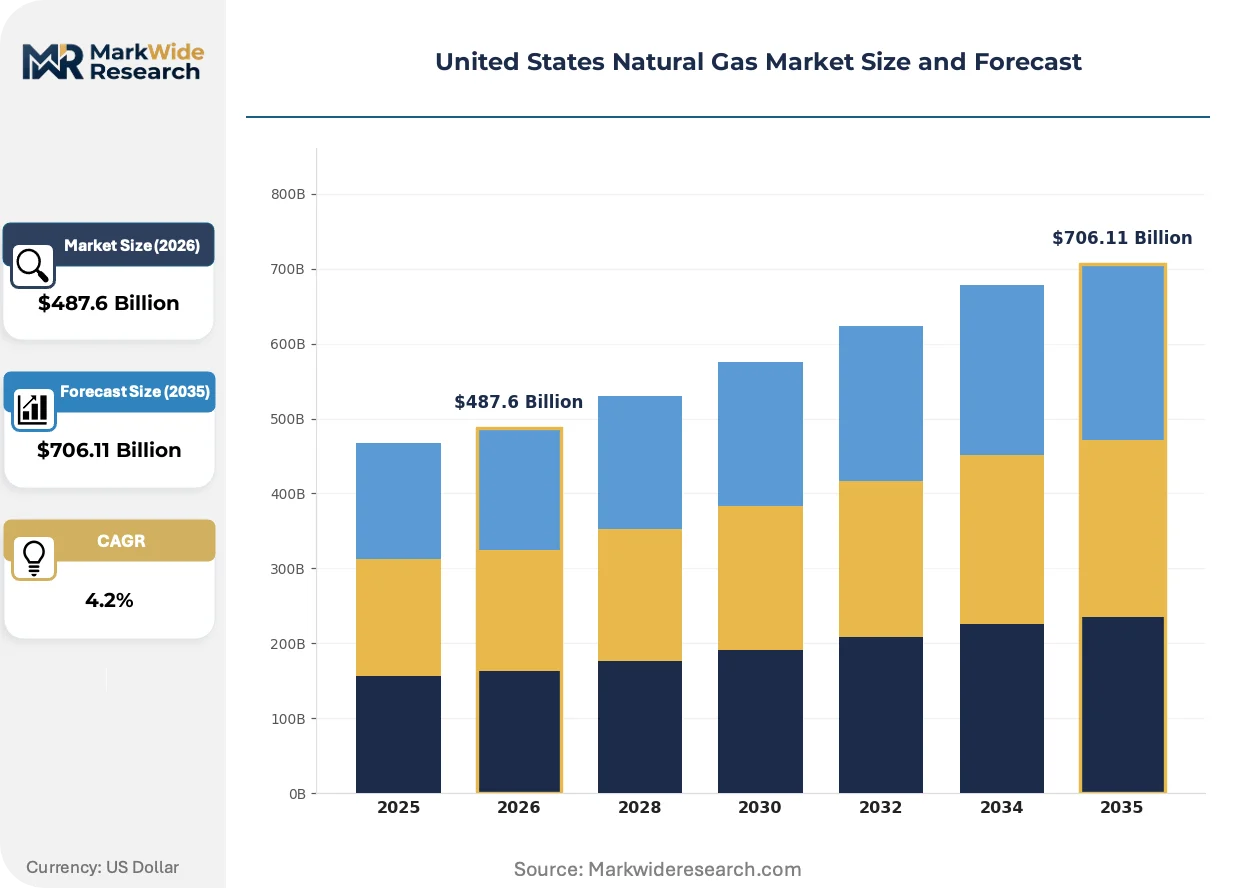
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $706.11 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Industrial Heating, Residential Heating, Transportation Type: Conventional, Unconventional, Liquefied Natural Gas, Compressed Natural Gas Distribution Channel: Direct Sales, Wholesale, Retail, Utilities End User: Power Plants, Manufacturing Facilities, Households, Commercial Establishments |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, ConocoPhillips, EQT Corporation, EOG Resources, Occidental Petroleum Corporation, Cheniere Energy, Nisource, Atmos Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Natural Gas Market Evolving Landscape
Digital methane monitoring and automated wellhead controls are compressing the detection-to-repair cycle from weeks to hours, rewiring how operators manage fugitive liability and field labor deployment.
Continuous emissions monitoring hardware is collapsing the cost structure of regulatory compliance for dispersed well pads. Appalachian independents are retrofitting older vertical wells with solar-powered sensor networks. The technology is collapsing the traditional tradeoff between survey frequency and field labor intensity, enabling daily methane balance accounting.
The Inflation Reduction Act's methane waste emissions charge is forcing capital into detection infrastructure ahead of 2026 fee escalation. Midstream gatherers are consolidating compressor stations to reduce monitored source counts. The policy is reshaping wellhead economics most severely in the Permian, where high-density drilling creates complex fugitive source matrices.
Buyers are unbundling long-term supply contracts into baseload-flexibility-option tiers. Industrial offtakers in Texas and Louisiana are negotiating interruptible clauses tied to real-time Henry Hub pricing. The restructuring is visible most acutely in the Gulf Coast petrochemical corridor, where steam cracker operators are optimizing feedstock flexibility between ethane and propane alternatives.
United States Natural Gas Market Segmentation
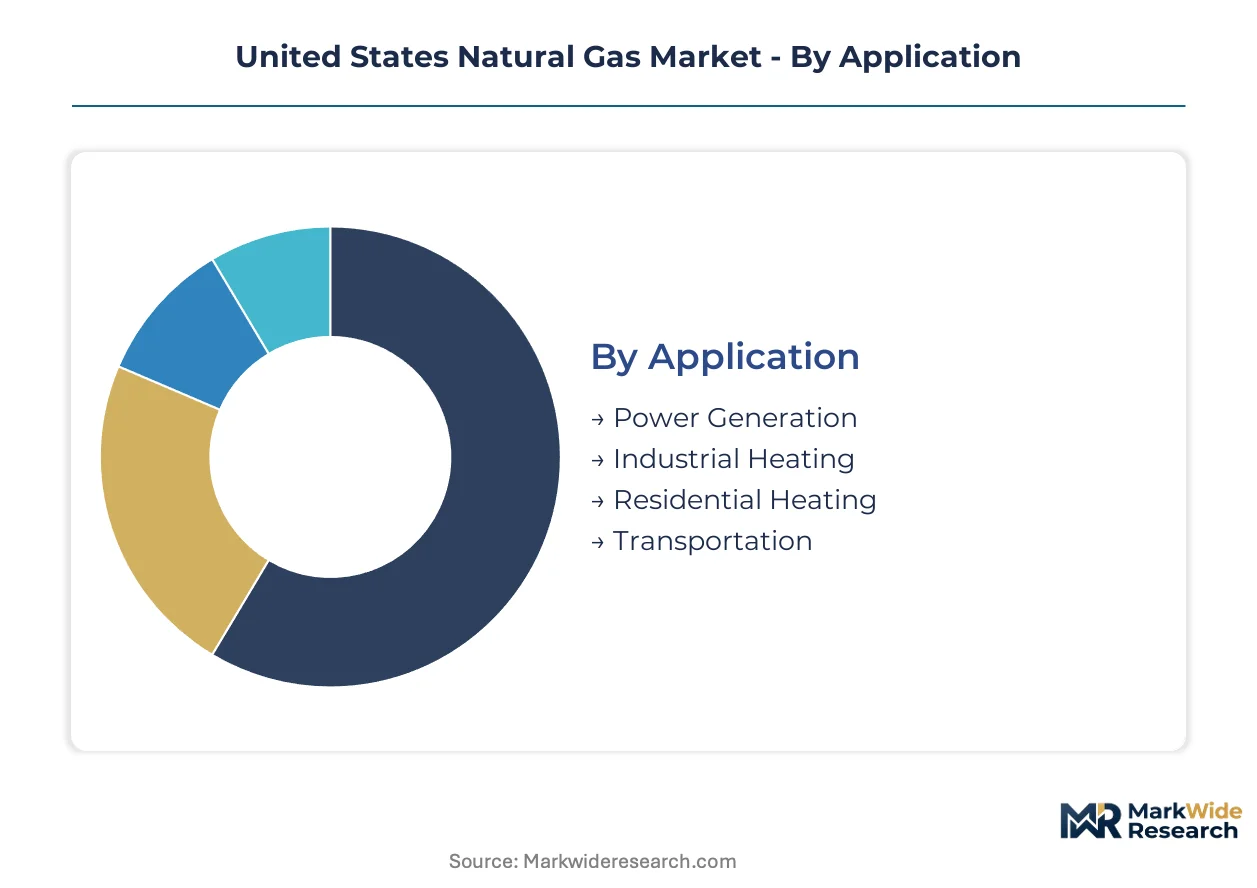
Segmentation in the United States natural gas market reveals how infrastructure constraints and regulatory pressure reshape profit pools across distinct demand channels. Each dimension exposes different vulnerability to methane fees, pipeline access, and electrification risk.
Application:
Application segmentation tracks where delivered molecules combust across the US economy, from baseload power to residential furnaces.
- Power Generation:Combined-cycle gas turbines consume pipeline-grade methane at 90-95% purity specifications. Texas and Pennsylvania utilities anchor long-term offtake contracts to replace retiring coal capacity across the Ohio River Valley.
- Industrial Heating:Process heat applications in petrochemical crackers and refinery operations sustain higher per-unit margins through baseload contracts with interruptible clauses. Gulf Coast steam methane reformers and ethylene producers concentrate demand.
- Residential Heating:Local distribution companies meter seasonal demand through city-gate interconnections in cold-climate states.
- Transportation:Compressed natural gas fuels fleet vehicles and heavy-duty trucking corridors with limited infrastructure penetration.
Power Generation holds installed capacity. Industrial Heating is rotating up the share rankings.
Type:
Type classification separates extraction methodology and physical state, determining transport economics and regulatory exposure.
- Unconventional:Horizontal drilling and hydraulic fracturing in the Permian and Marcellus formations dominate current US production volumes. EPA methane fees compress wellhead economics most severely here due to high-density drilling and complex fugitive source matrices.
- Liquefied Natural Gas:Cryogenic liquefaction at Gulf Coast terminals enables marine export to European and Asian buyers. Brownsville and Corpus Christi capacity expansions absorb excess Appalachian supply through pipeline reversals.
- Conventional:Vertical well production from traditional reservoir structures contributes declining share of national output.
- Compressed Natural Gas:Pressurized storage for vehicle fueling and distributed power generation serves niche mobility applications.
Unconventional maintains production dominance. LNG is climbing the fastest as export capacity multiplies.
Distribution Channel:
Channel structure reflects how custody transfers from wellhead to burner tip, with each tier bearing different price risk and capital intensity.
- Wholesale:Interstate pipeline nominations and hub trading at Henry Hub, Dominion South Point, and Waha establish regional price benchmarks. FERC rate regulation governs tariff structures for long-haul transport.
- Utilities:Investor-owned and municipal gas utilities aggregate residential and commercial demand through LDC networks. Rate-base regulation by state public utility commissions shapes return on pipeline infrastructure investment.
- Direct Sales:Large industrial offtakers contract directly with producers or marketers, bypassing utility markup.
- Retail:Competitive marketers and energy service companies serve deregulated state markets with variable pricing products.
Utilities control last-mile infrastructure. Wholesale is gaining transaction volume as producer-marketer consolidation accelerates.
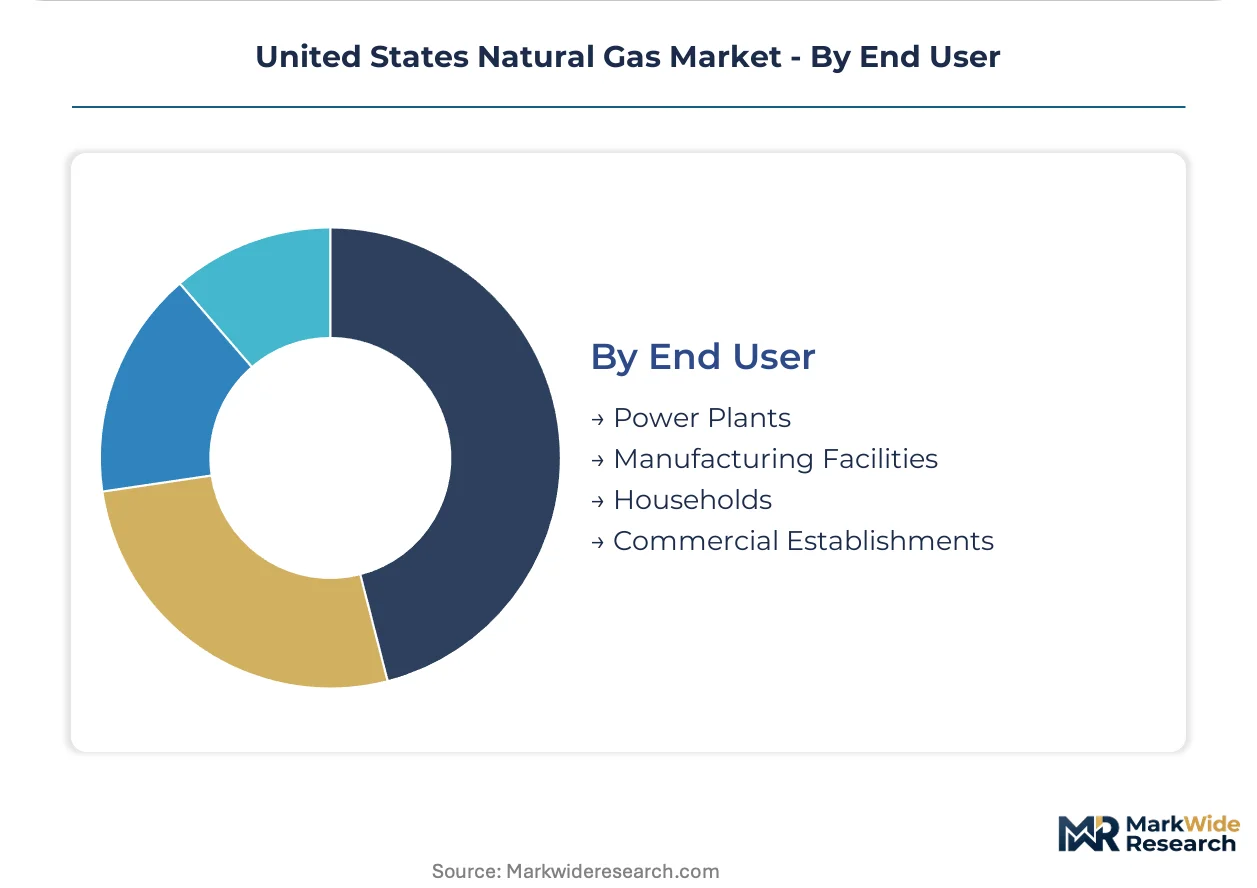
End User:
End-user segmentation isolates demand concentration by facility type and scale, exposing differential sensitivity to price volatility and supply interruption.
- Power Plants:Merchant and regulated generators dispatch gas-fired capacity against renewable output curves. Battery storage co-location in California and the Southwest erodes peaker economics during high-renewable hours.
- Manufacturing Facilities:Petrochemical complexes, refineries, and food processors maintain dual-fuel capability where infrastructure permits. Texas and Louisiana steam cracker operators optimize feedstock flexibility between ethane and propane alternatives.
- Households:Residential consumers exhibit inelastic winter demand concentrated in Northeast and Midwest heating-degree-day markets.
- Commercial Establishments:Hospitals, universities, and office buildings consume through utility tariffs or retail supply contracts with demand-charge structures.
Power Plants anchor volume offtake. Manufacturing Facilities are expanding fastest on Gulf Coast industrial buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Henry Hub pricing in Louisiana diverges sharply from Appalachian supply points, creating arbitrage windows that pipeline reversals exploit. Gulf Coast export terminals absorb surplus Marcellus production while Permian basis differentials compress under takeaway constraints. Regional infrastructure asymmetries reshape producer netbacks across the Lower 48.
Texas Gulf Coast
Corpus Christi and Brownsville liquefaction trains anchor LNG export capacity expansion. FERC certificate delays for interstate pipelines constrain northeast-bound flows from the Permian. Houston petrochemical complexes consume feedstock gas for ethylene and ammonia production.
Appalachia
Marcellus and Utica shale wells in Pennsylvania and West Virginia supply low-cost methane to mid-Atlantic power generators. EPA methane waste emissions charges compress wellhead economics for high-density drilling pads. Pittsburgh-area processing plants fractionate NGL streams for regional petrochemical feedstock.
Permian Basin
West Texas and southeast New Mexico production faces takeaway bottlenecks on pipelines to Gulf Coast markets. IRA methane fees escalate compliance costs for dispersed well pads and compressor stations. Midland-Odessa gathering systems consolidate to reduce monitored fugitive source counts.
Louisiana
Henry Hub trading establishes the national price benchmark for physical and financial gas contracts. Cheniere Energy's Sabine Pass terminal anchors Gulf Coast LNG export capacity with long-term offtake contracting. Lake Charles industrial corridors consume gas for refinery hydrogen and methanol production.
California
Utility-scale solar and battery storage erode gas-fired peaker economics during high-renewable output hours. CPUC resource adequacy requirements sustain capacity payments for flexible generation. Los Angeles Basin local distribution networks face decarbonization mandates under state climate legislation.
United States Natural Gas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The United States natural gas market consolidates around integrated majors with Permian-to-Gulf Coast value chain control, while independents concentrate in single-basin unconventional positions. Two archetypes dominate: integrated gas-to-liquids operators spanning upstream, midstream, and export terminals; and pure-play shale specialists leveraging scaled horizontal drilling programs. Competitive moves center on midstream asset consolidation and certified responsibly sourced gas differentiation for European LNG buyers.
Within the integrated major tier, ExxonMobil Corporation and Chevron Corporation occupy positions spanning Permian and Bakken production through Gulf Coast liquefaction. Among independent shale specialists, EQT Corporation exemplifies scaled Marcellus development with pipeline-linked delivery to mid-Atlantic demand centers. Cheniere Energy anchors the LNG export infrastructure layer with terminal capacity at Sabine Pass and Corpus Christi.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| ConocoPhillips |
| EQT Corporation |
| EOG Resources |
| Occidental Petroleum Corporation |
| Cheniere Energy |
| Nisource |
| Atmos Energy |
| Others |
Value Network & Pricing Analysis
Permian Basin takeaway undercapacity compresses regional netbacks while forcing producers toward long-haul pipeline commitments that reshape contract negotiation leverage. This utilization squeeze simultaneously elevates Henry Hub basis premiums and accelerates consolidation among midstream gatherers seeking scale efficiencies.
Pricing Analysis
Long-term offtake premiums over spot Henry Hub pricing widen for certified responsibly sourced gas with third-party methane intensity verification. Price differentiation hinges on EPA compliance tier and pipeline access priority, with Appalachian low-leak producers commanding premiums over Permian supply. Cost compression in standard pipeline-grade deliveries intensifies as renewable plus storage configurations erode peaker economics. Industrial steam cracker operators exhibit lowest price sensitivity through dual-fuel flexibility, while merchant generators face acute margin pressure during high-renewable output hours.
Supply Chain Analysis
Domestic steel mills and specialized OCTG tubular suppliers hold concentrated capacity for pipeline-grade materials serving Permian and Appalachian buildouts. Raw material flows draw from domestic scrap metal recovery and alloy import channels, with fabrication anchored in Texas and Louisiana industrial corridors. Tariff exposure on specialty steel inputs creates procurement risk for gathering system expansions facing 18-24 month delivery lags. Distribution runs through FERC-regulated interstate pipelines to utility city-gate interconnections and direct industrial offtake contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leak detection technology and continuous monitoring services expand faster than base production infrastructure, creating recurring-revenue layers with superior retention economics. This service-attach dynamic rewards operators who bundle compliance hardware with data analytics subscriptions.
For Market Incumbents: Pre-empt IRA methane fee escalation by consolidating compressor stations and deploying optical gas imaging networks ahead of regulatory deadlines. Secure pipeline-linked delivery positions to mid-Atlantic power generators before FERC certificate delays harden capacity constraints. Vertical integration into certified responsibly sourced gas verification creates defensible premium contracting channels to European LNG buyers.
For New Entrants and Emerging Players: Northeast supply growth into New England demand centers remains structurally constrained by interstate pipeline bottlenecks, creating white-space opportunity for LNG trucking and virtual pipeline solutions. Target industrial heating applications in Gulf Coast petrochemical corridors where interruptible contract structures lower entry barriers. Pursue hydrogen blending pilot funding under IRA hub grants to establish early infrastructure positioning.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among midstream operators with long-term take-or-pay contracts and leak detection service overlays. Five-to-ten year viability favors integrated gas-to-liquids majors with Permian-to-Gulf Coast value chain control over pure-play shale specialists exposed to single-basin basis risk. Monitor FERC certificate approval velocity as inflection signal for regional supply-demand rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Responsibly Sourced Gas Program | Third-party methane verification opens premium European LNG contracting channels for Appalachian producers. |
| Pipeline Reversal Capacity Expansion | Southbound flows from Marcellus to Gulf Coast terminals absorb excess supply and compress regional basis differentials. |
| Hydrogen Hub Infrastructure Positioning | Texas industrial corridor repurposing for hydrogen-natural gas mixtures attracts federal IRA grant funding. |
| Continuous Emissions Monitoring Deployment | Solar-powered sensor networks at well pads collapse compliance costs ahead of escalating EPA waste emissions charges. |
| Midstream Asset Consolidation | Compressor station consolidation reduces fugitive source counts and lowers per-unit methane monitoring overhead. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, EPC contractors, fuel supply specialists, and regulatory affairs leads at midstream operators, then refined through secondary validation. EIA production data, FERC pipeline filings, EPA enforcement databases, and project development tracking supplied quantitative anchors. Bottom-up wellhead economics modeling and top-down demand-sector aggregation were cross-checked for consistency.
Demand-supply balance dynamics across the projection horizon were modeled through segmented analysis by extraction type, application end-use, and regional infrastructure access. CAGRs were derived from production volume trajectories, capacity expansion timelines, and regulatory cost pass-through assumptions. Forecast inputs incorporated IRA methane fee escalation schedules and LNG export terminal commissioning progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated majors on midstream consolidation or hydrogen hub positioning would shift outcomes. Regulatory acceleration on emissions enforcement or FERC certificate policy reversal represents primary revision risk. Quarterly review of Henry Hub basis differentials, pipeline utilization rates, and LNG offtake contracting velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Blowout Preventers (BOP) Market