
 Colombia Oil and Gas Downstream Market | 2026-2036
Colombia Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Oil and Gas Downstream Market Outlook
Buyer concentration among large fleet operators and industrial consumers is restructuring procurement patterns across Colombia's downstream sector. Ecopetrol S.A. anchors the national refining base through its Barrancabermeja and Cartagena complexes. Shell Colombia S.A. competes in premium lubricants and specialized fuel formulations. BP Colombia differentiates through natural gas liquids integration and petrochemical feedstock supply.
Colombia oil and gas downstream operations encompass refining crude oil into transportation fuels, producing petrochemical intermediates, and blending lubricants and asphalt binders for industrial and infrastructure applications. Atmospheric and vacuum distillation units typically process crude at temperatures ranging from 350°C to 400°C to separate fractions before catalytic cracking or hydrotreating. Refined Fuels dominates volume throughput, while Petrochemicals captures expanding margin pools from polyethylene and polypropylene derivatives. The Service Type dimension shows Logistics and Refining as mature, capital-intensive segments, with Marketing emerging as a value-added layer as deregulation advances.
ANH, the national hydrocarbons agency, sets fuel quality mandates and blending requirements that directly shape refinery investment schedules and product slate decisions. Colombia's Ministry of Mines and Energy enforces downstream pricing formulas and import parity mechanisms that affect margin distribution between domestic refiners and marketers. Environmental licensing through the national environmental authority introduces compliance costs for emissions-intensive upgrading units. Stakeholders must weigh refinery modernization timelines against the pace of electrification in Colombia's transport sector and the policy signals emerging from Bogotá's energy transition planning.
Market Dynamics
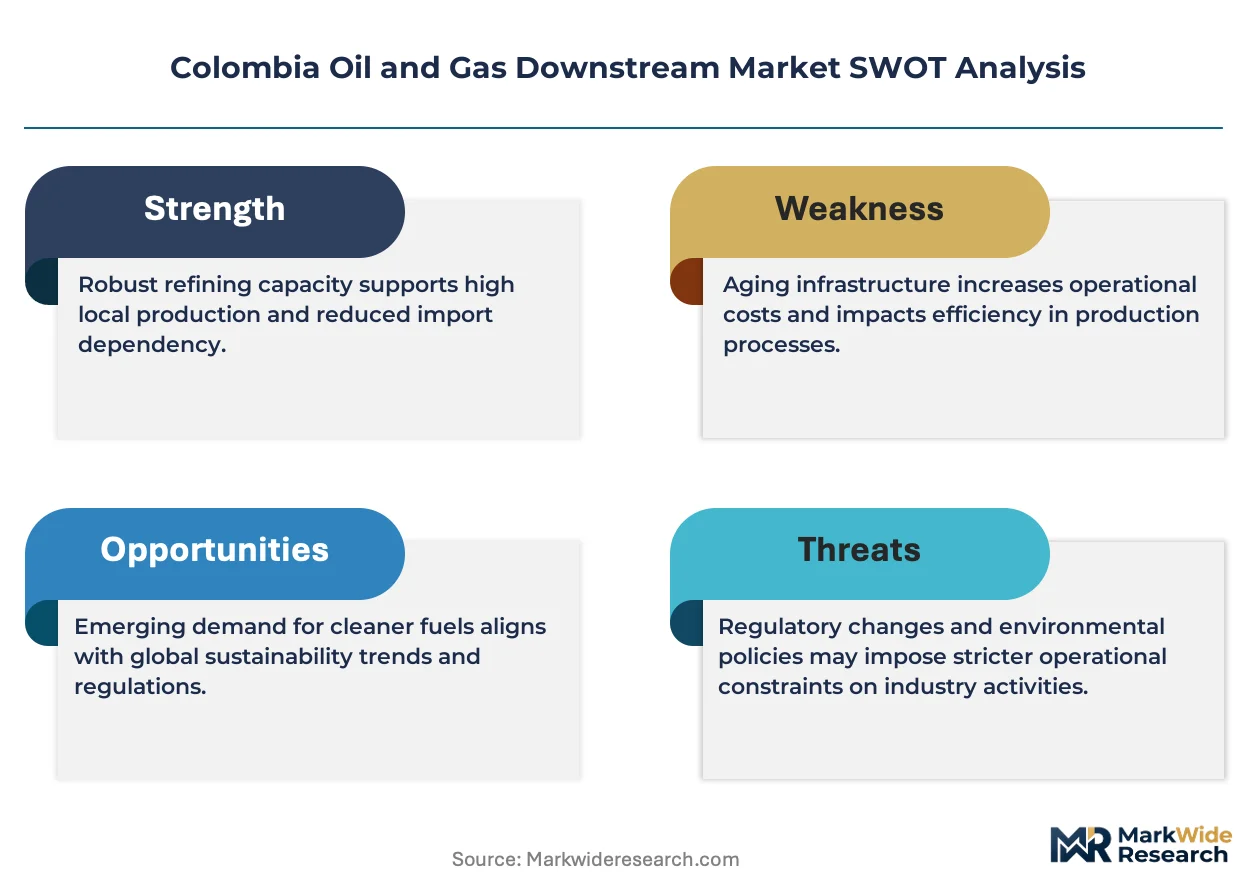
ANH fuel quality mandates are compressing refinery investment timelines while fleet operators consolidate procurement volumes, creating a bifurcated market structure between modernized upgraders and import-dependent marketers.
Growth Catalysts
- Andean industrial corridor expansion:Manufacturing clusters around Bogotá and Medellín are lifting diesel and lubricant offtake from domestic refiners.
- ANH biofuel blending mandates:Ethanol and biodiesel minimums are forcing infrastructure upgrades that expand capacity for higher-margin blended products.
- Natural gas liquids fractionation:NGL processing is diversifying feedstock supply for petrochemical derivatives beyond traditional crude streams.
Market Restraints
- Import parity pricing mechanics:Ministry of Mines and Energy formulas cap domestic refiner margins when international benchmarks spike.
- Single-refinery concentration risk:Barrancabermeja and Cartagena complexes account for overwhelming national throughput, creating supply vulnerability.
- Electrification substitution pressure:Bogotá's energy transition planning signals long-term compression in gasoline demand pools.
Strategic Opportunities
- Pacific coast logistics expansion:Buenaventura port capacity upgrades could redirect product flows toward Ecuador and Peru export markets.
- Polypropylene derivative demand:Packaging and automotive applications are absorbing expanding petrochemical output from integrated refiners.
- Carbon capture retrofit eligibility:ANH environmental licensing pathways may subsidize emissions reduction investments at aging hydrotreating units.
Industry Challenges
- Catalytic reformer catalyst replacement cycles:Platinum group metal volatility is complicating maintenance scheduling at upgrading units.
- Hydrogen supply integration:Refinery hydrogen networks require costly reconfiguration to support desulfurization targets under tightening ANH specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Oil and Gas Downstream Market |
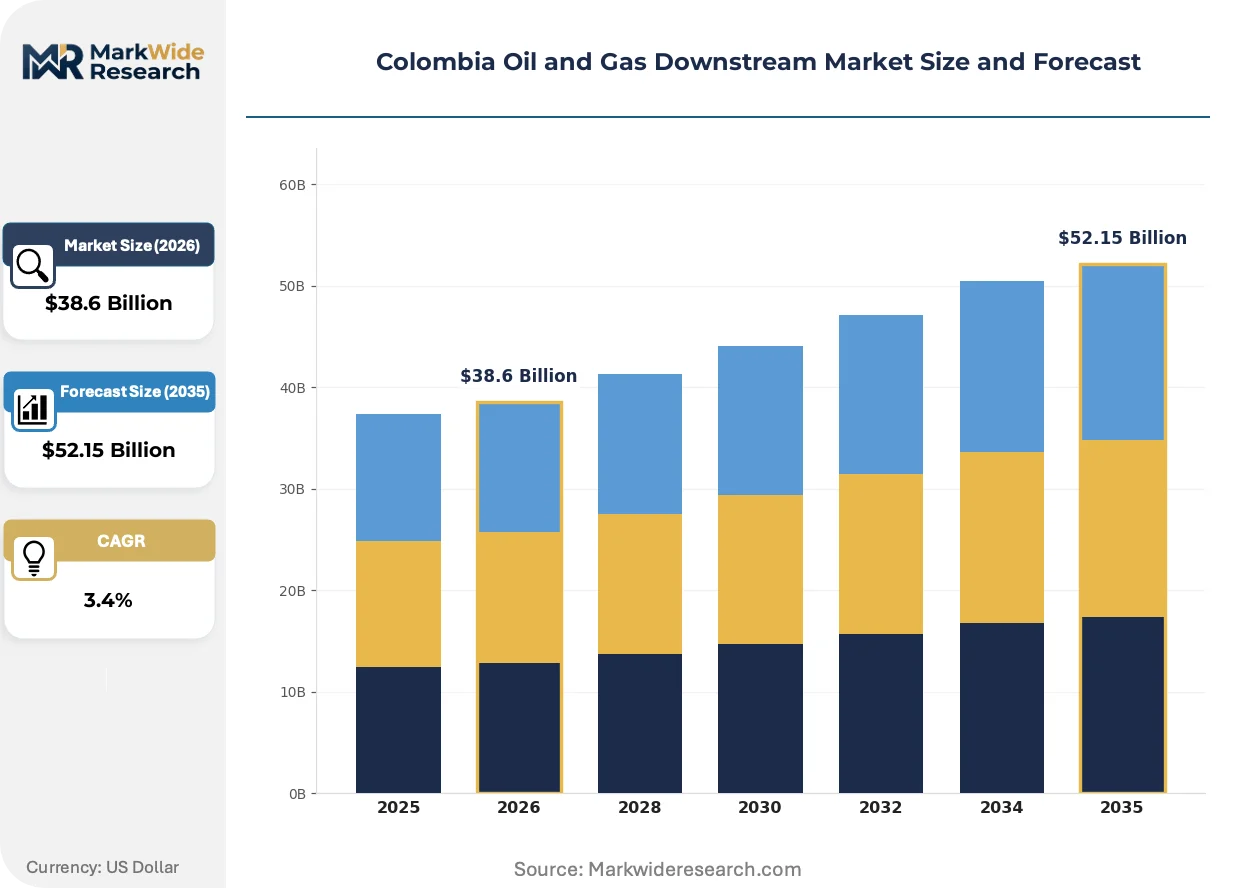
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $52.15 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Asphalt Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce Service Type: Logistics, Refining, Marketing, Consulting End User: Automotive, Industrial, Residential, Commercial |
| Companies Covered | Shell Colombia S.A., BP Colombia, Ecopetrol S.A., Reficar, Occidental Petroleum, Exxon Mobil Corporation, Fluor Corporation, Colombia Petrochemicals, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Oil and Gas Downstream Market Strategic Shifts
Digital instrumentation and modular process architectures are compressing capital deployment timelines across Colombia's refining and logistics infrastructure. These shifts are redrawing competitive boundaries between integrated operators and specialized service providers.
Small-scale modular refining is modularizing distributed fuel production for remote mining and agricultural operations. Rural extractive companies are piloting containerized distillation units to bypass pipeline-dependent supply chains. This architecture is modularizing capital efficiency thresholds that previously favored only large-volume refiners.
ANH real-time fuel quality tracking mandates are forcing terminal operators to deploy automated sampling and blockchain-verified certification systems. Downstream marketers must now maintain continuous emissions and composition data streams for regulatory audit. The Andean region's urban distributors are responding by consolidating into technology-capable networks that can absorb compliance overhead.
Fleet operators are consolidating annual fuel contracts around total cost-per-kilometer metrics rather than spot price indexing. Large logistics buyers are displacing fragmented retail purchasing through direct refinery offtake agreements. This concentration is most visible in Medellín's trucking corridors, where cooperative buying pools now negotiate volume commitments with single suppliers.
Colombia Oil and Gas Downstream Market Segmentation
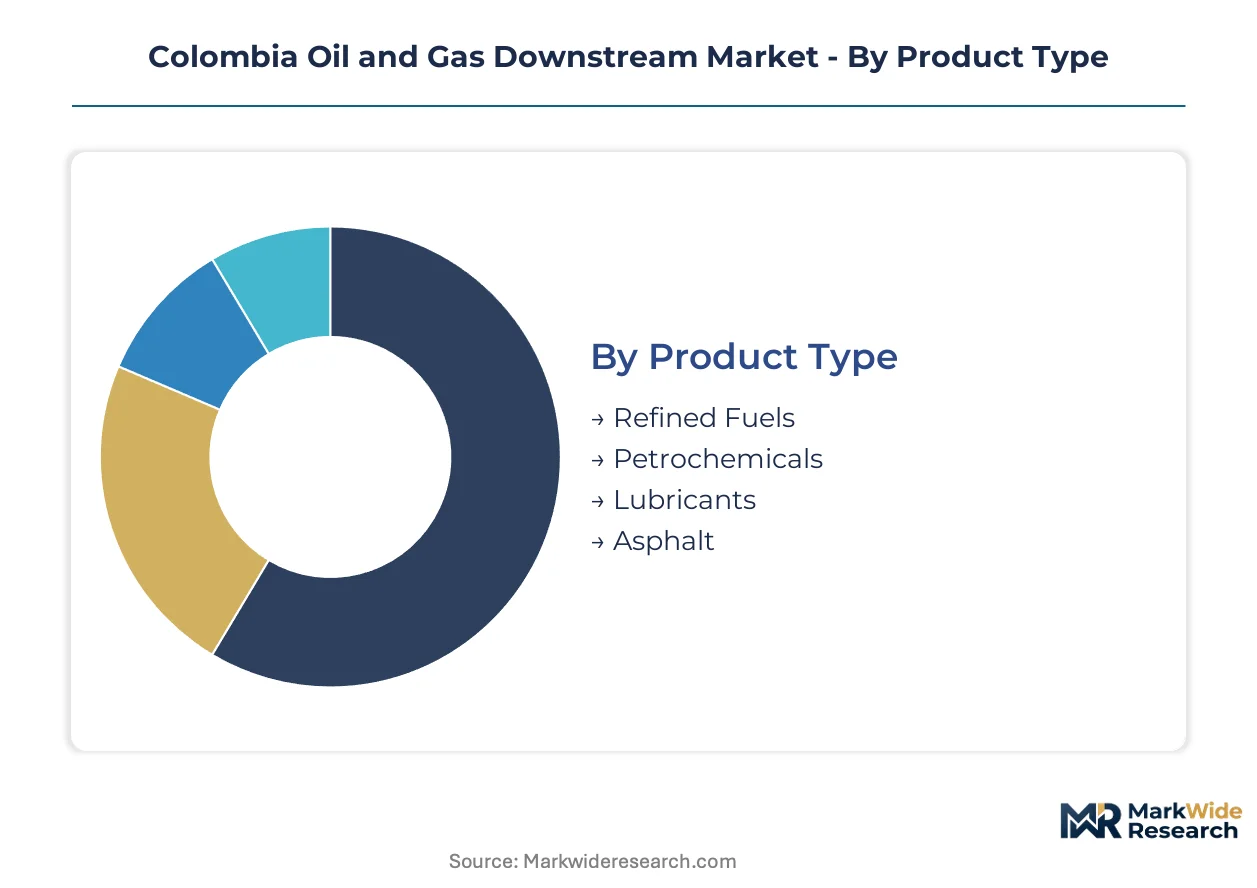
Downstream segmentation in Colombia tracks how ANH regulations, refinery configuration, and fleet procurement patterns split value across product, channel, service, and customer dimensions. Each category carries distinct margin profiles and capital intensity requirements that shape competitive positioning.
Product Type:
Standardization dominates at the commodity end while specialty formulations command premium pricing tiers across this spectrum.
- Refined Fuels:Atmospheric and vacuum distillation yields gasoline, diesel, and jet kerosene meeting ANH sulfur and biofuel blending mandates. Barrancabermeja and Cartagena complexes push the bulk of this volume toward Bogotá and Medellín fleet operators under Ministry of Mines and Energy pricing formulas.
- Petrochemicals:Catalytic cracking and steam cracking output polyethylene, polypropylene, and aromatics feedstocks. Demand concentrates in Andean packaging manufacturers and automotive injection molders seeking integrated supply from domestic refiners.
- Lubricants:Base oil blending with additive packages for engine and industrial applications.
- Asphalt:Vacuum residue processing for road construction and waterproofing binders.
Most installed capacity flows through Refined Fuels. Expansion is steepest in Petrochemicals.
Distribution Channel:
Channel selection maps directly to buyer scale and inventory carrying capacity across Colombia's terrain.
- Retail:Branded and unbranded service stations serving individual motorists and small commercial fleets. Site concentration clusters along the Bogotá-Medellín-Cali corridor where traffic density supports throughput economics.
- Wholesale:Terminal-to-dealer bulk transfers for regional distributors and cooperative buying pools. Medellín trucking corridors show cooperative consolidation into single-supplier volume commitments.
- Direct Sales:Refinery offtake agreements with mining companies, airlines, and municipal bus fleets.
- E-commerce:Digital platforms for lubricant and specialty product ordering with logistics coordination.
Volume concentrates in Wholesale. Digital infrastructure investment is climbing fastest in E-commerce.
Service Type:
Capital intensity and regulatory exposure separate mature infrastructure plays from emerging advisory layers.
- Logistics:Pipeline, marine, and trucking networks connecting refineries to consumption centers. Pacific coast routes through Buenaventura are absorbing port capacity upgrades for potential Ecuador and Peru export redirection.
- Refining:Crude processing through distillation, cracking, and treating units at Barrancabermeja and Cartagena. ANH environmental licensing is adding compliance cost layers to emissions-intensive upgrading investments.
- Marketing:Brand development, pricing strategy, and customer relationship management for differentiated products.
- Consulting:Technical advisory on refinery optimization, biofuel integration, and carbon capture retrofit planning.
Asset-heavy segments dominate revenue. Advisory services are gaining share fastest as deregulation deepens.
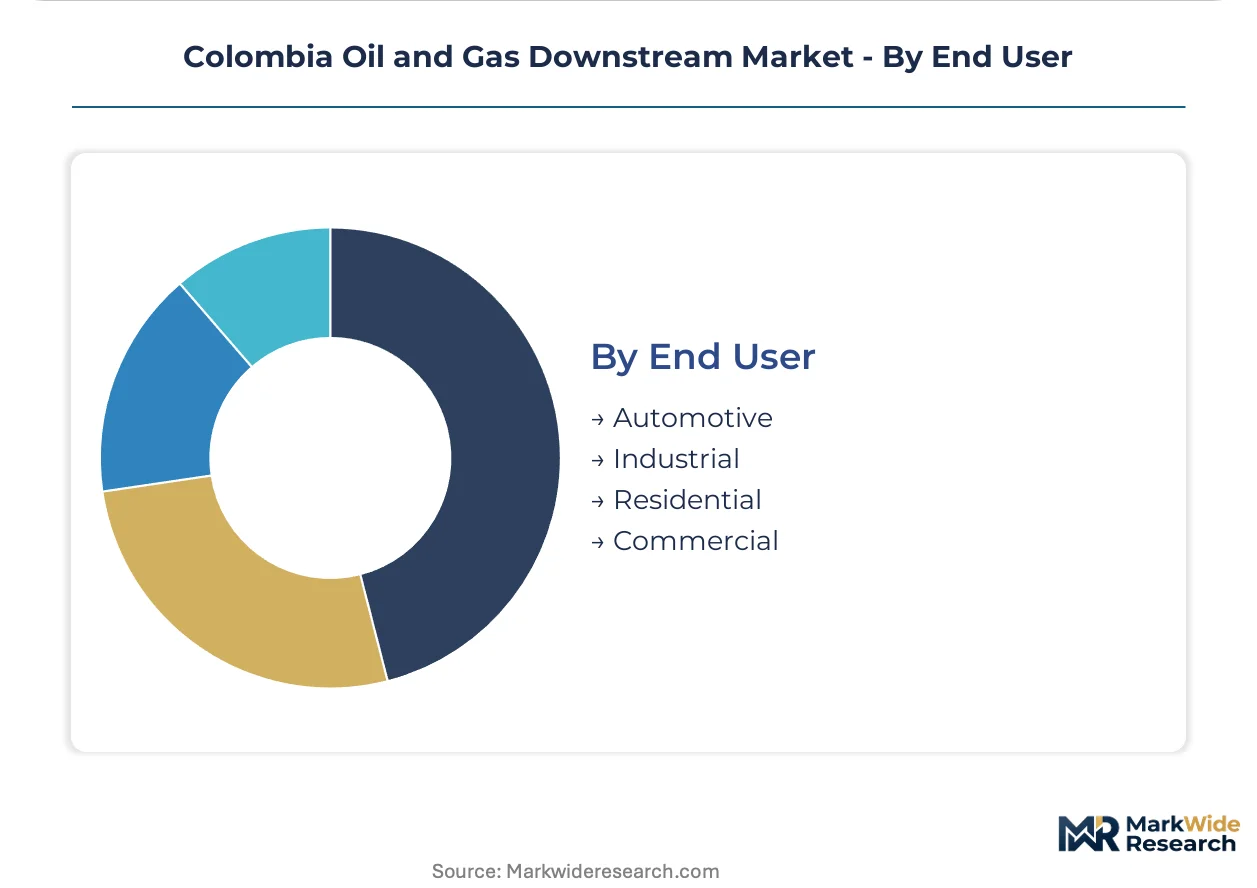
End User:
Application requirements split demand between mobility, manufacturing, heating, and commercial operations.
- Automotive:Private vehicles, taxis, and buses consuming gasoline, diesel, and lubricants. Fleet operators are consolidating procurement around total cost-per-kilometer metrics rather than spot indexing.
- Industrial:Manufacturing plants, mining operations, and agricultural processors requiring diesel, fuel oil, and petrochemical feedstocks. Andean industrial corridors around Bogotá and Medellín are lifting diesel and lubricant offtake.
- Residential:LPG and heating fuel for household energy needs.
- Commercial:Retail, hospitality, and office buildings consuming diesel for backup generation and LPG for thermal applications.
Industrial buyers absorb the largest volume. Automotive electrification pressure is compressing long-term gasoline demand pools most severely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's downstream sector processes nearly triple the refined fuel volume of Colombia, yet both Andean nations face parallel pressures from biofuel mandates and electrification timelines.
Andean Region
The Bogotá-Medellín industrial corridor absorbs the majority of national diesel and lubricant offtake from domestic refiners. ANH biofuel blending mandates are forcing terminal infrastructure upgrades across Cundinamarca and Antioquia departments. Manufacturing clusters in Sabaneta and Funza are lifting petrochemical feedstock demand for packaging derivatives.
Caribbean Coast
The Cartagena refinery complex anchors Atlantic fuel supply for maritime bunkering and coastal power generation. Ministry of Mines and Energy import parity formulas cap margins when international benchmarks spike. Barranquilla's port logistics networks are expanding storage capacity for regional product redistribution.
Pacific Region
Buenaventura port capacity upgrades could redirect refined product flows toward Ecuador and Peru export markets. Valle del Cauca's sugarcane ethanol producers supply ANH-mandated blending requirements for gasoline formulations. Cali's industrial parks are absorbing expanding asphalt output for road infrastructure programs.
Orinoquía
Remote oilfield operations in Meta and Casanare departments rely on direct refinery offtake agreements for diesel and fuel oil. Small-scale modular refining pilots are bypassing pipeline-dependent supply chains for extractive companies. Villavicencio logistics hubs are consolidating procurement volumes for agricultural processing cooperatives.
Border Zones
Cross-border fuel arbitrage pressures shape pricing mechanics in Cúcuta and other Venezuelan frontier municipalities. Contraband diesel flows complicate ANH quality enforcement and tax collection mechanisms. Ipiales and other Ecuadorian border points face parallel smuggling dynamics affecting official distribution channels.
Colombia Oil and Gas Downstream Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Colombia's downstream sector, creating a tiered structure where scale advantages clash with operational agility. The market consolidates around integrated refiners with captive logistics networks and independent marketers dependent on import terminals. Three archetypes dominate: state-linked national champions, international majors with lubricant and specialty positions, and regional service contractors. Competitive moves center on refinery modernization timelines and Pacific coast logistics expansion.
Among international majors, Shell Colombia S.A. and BP Colombia exemplify the premium lubricants and natural gas liquids integration archetypes respectively. Ecopetrol S.A. anchors the national champion position through its Barrancabermeja and Cartagena refining complexes. These three entities occupy distinct competitive positions that reflect their upstream heritage and downstream configuration choices.
| Leading Market Players |
|---|
| Shell Colombia S.A. |
| BP Colombia |
| Ecopetrol S.A. |
| Reficar |
| Occidental Petroleum |
| Exxon Mobil Corporation |
| Fluor Corporation |
| Colombia Petrochemicals |
| Chevron Corporation |
| Others |
Value Chain & Pricing Dynamics
Refinery configuration divergence between modernized upgraders and import-dependent marketers splits Colombia's downstream sector into parallel pricing regimes. ANH fuel quality mandates compress investment timelines for domestic refiners while import parity formulas cap margin capture during international benchmark spikes, creating asymmetric cost pass-through capabilities across the value chain.
Pricing Analysis
Capacity additions in Cartagena are reshaping price floors for low-sulfur diesel and gasoline formulations across the Andean region. Contract-based long-term offtake agreements dominate procurement between Ecopetrol and large fleet operators, with price differentiation driven by volume scale and ANH certification tier. Cost compression in standard-grade fuels is intensifying because import parity mechanics prevent full cost recovery during crude volatility. Industrial buyers in Bogotá's manufacturing corridors show lowest price sensitivity due to operational continuity requirements, while fragmented retail motorists face highest spot-price exposure.
Supply Chain Analysis
Direct-to-industry channels handle hyperscale demand from mining consortia and municipal bus fleets across Colombia's interior. Domestic supply concentrates at Barrancabermeja and Cartagena complexes, with supplemental draws from US Gulf Coast and Caribbean refineries during maintenance turnarounds. Feedstock supply rests on Castilla and Vasconia crude streams from Llanos Basin fields, plus imported diluents for heavy oil processing. Single-refinery concentration risk creates supply vulnerability during unplanned outages or environmental licensing delays. Distribution runs through Pacific coast marine terminals at Buenaventura, pipeline networks to Bogotá-Medellín corridors, and trucking fleets serving Orinoquía extractive zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's downstream market represents a late-cycle quality story as ANH specifications tighten and fleet operators consolidate procurement around total cost-per-kilometer metrics rather than spot indexing.
For Market Incumbents: To counter electrification substitution pressure in Bogotá's transport sector, Ecopetrol and integrated refiners should accelerate hydrotreater upgrades to capture premium margins on ultra-low-sulfur diesel. Backward integration into NGL fractionation at Cartagena diversifies petrochemical feedstock supply and reduces crude price correlation. Channel control through direct refinery offtake agreements with mining and airline accounts locks in volume commitments ahead of demand erosion. For New Entrants and Emerging Players: Capture white-space in Pacific coast logistics expansion as Buenaventura port capacity upgrades enable Ecuador and Peru export redirection. Modular refining pilots for remote Orinoquía oilfield operations bypass pipeline-dependent supply chains and serve extractive companies with captive diesel demand. The most penetrable segment lies in carbon capture retrofit advisory services, where ANH environmental licensing pathways subsidize emissions reduction investments. For Investors and Strategic Acquirers: Consolidation pressure builds where single-refinery concentration risk meets aging hydrotreating infrastructure requiring platinum group metal catalyst replacement cycles. Long-term viability favors operators with integrated NGL-to-petrochemicals capability and Pacific logistics optionality. Target acquisition profile centers on mid-scale terminal operators with technology-capable networks absorbing ANH real-time fuel quality tracking compliance overhead. The signal to watch is Ministry of Mines and Energy adjustments to import parity formulas that would restructure margin distribution between domestic refiners and marketers.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Modernization | ANH sulfur mandates force capital deployment to capture ultra-low-sulfur diesel premium pools. |
| NGL Fractionation Expansion | Natural gas liquids processing diversifies petrochemical feedstock beyond crude-dependent cracking economics. |
| Pacific Logistics Buildout | Buenaventura terminal upgrades redirect product flows toward Ecuador and Peru export arbitrage opportunities. |
| Carbon Capture Retrofit | ANH environmental licensing subsidies reduce emissions compliance costs at aging catalytic reforming units. |
| Fleet Contract Consolidation | Direct refinery offtake agreements with cooperative buying pools displace fragmented retail purchasing volumes. |
Study Parameters
Coverage spans Andean, Caribbean Coast, Pacific, and Orinoquía sub-regions, with primary inputs from each. The research combines structured interviews with refinery operations managers, ANH regulatory affairs officers, fleet procurement directors at logistics cooperatives, and terminal infrastructure planners with secondary validation from Ministry of Mines and Energy pricing bulletins, ANH fuel quality compliance databases, Ecopetrol operational disclosures, and customs trade flow records. Bottom-up segment sizing triangulates against top-down macroeconomic anchors across energy demand models.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, service tier, and end-use application, with additional granularity on refinery configuration and biofuel blending mandate compliance status. CAGRs derive from historical trajectory analysis adjusted for policy inflection points and infrastructure commissioning schedules. Industry-specific inputs incorporate ANH regulatory timeline assumptions and electrification penetration curves from Bogotá energy transition planning documents.
Underlying measurement precision varies by segment; Refined Fuels and Logistics carry tighter precision than emerging Consulting advisory services. Forecasts reflect assumptions on ANH mandate enforcement consistency, import parity formula stability, and Pacific coast export market access. Specific risks that could revise projections include unplanned refinery outages, platinum group metal price volatility affecting catalyst replacement cycles, and accelerated electrification timelines compressing gasoline demand pools. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Sidetracking Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Mud Balance Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Intelligent Pigging Services Market