
 Downhole Equipment Market | 2026-2036
Downhole Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Downhole Equipment Market Analytics
Modularization of downhole tool packages is shifting buyer choice toward configurable systems that reduce rig time and simplify logistics. Schlumberger Limited leverages its integrated drilling and evaluation portfolio to anchor premium positions in complex well architectures. Baker Hughes Company differentiates through advanced completions technology, while Halliburton Company dominates North American pressure pumping with extensive service infrastructure.
Downhole equipment comprises specialized tools and systems deployed within wellbores to drill, complete, intervene, or monitor subsurface formations, typically constructed from high-strength alloy steels rated for pressures exceeding 15,000 psi and temperatures above 350°F to ensure integrity in hostile downhole environments. These systems enable hydrocarbon extraction, geological data acquisition, and reservoir management across onshore and offshore operations. Completion equipment leads product type segments due to sustained unconventional well completion intensity, while automation solutions within technology segments represent the fastest-growing category as operators deploy remote-actuated intelligent completions to optimize production without well intervention. Well intervention tools command premium margins where aging well populations in mature basins require workover and recompletion services.
API standards govern material specifications and performance testing for downhole tubulars across North American operations, while BSEE regulations impose stringent safety and environmental compliance requirements for offshore equipment deployment in US federal waters. The EPA's methane emissions rules are forcing equipment redesigns to minimize fugitive releases through improved sealing technologies and monitoring integration. Stakeholders must monitor regulatory acceleration toward electrification and automation mandates that will reshape capital allocation across the supply chain.
Market Dynamics
Pad drilling economics in the Permian Basin and other North American shale plays are compressing well construction cycles and forcing downhole equipment suppliers to engineer faster-deployment tool systems. This operational tempo shift rewards modular, rig-up-optimized designs while penalizing legacy equipment requiring extended surface handling time.
Growth Catalysts
- EPA Methane Emissions Rules:Operators retrofit wellheads with improved sealing technologies and integrated monitoring systems to comply with tightened fugitive release standards, creating replacement demand across installed bases.
- Intelligent Completion Systems:Remote-actuated valves and downhole sensors enable real-time production optimization without well intervention, driving capital allocation toward digitally instrumented architectures.
- Permian Basin Drilling Intensity:Extended lateral lengths exceeding 15,000 feet require specialized liner hangers, multistage fracturing sleeves, and premium connections rated for higher fatigue cycles.
Market Restraints
- Alloy Steel Input Volatility:Chromium and molybdenum price swings directly impact tubular manufacturing costs, compressing margins for producers lacking long-term raw material contracts.
- Supplier Concentration in Premium Connections:Proprietary thread designs from a limited set of licensors create dependency risks and constrain pricing flexibility for independent tool manufacturers.
- Deepwater Technical Limitations:Ultra-high-pressure high-temperature reservoirs exceeding 20,000 psi and 400°F exceed current elastomer and electronics reliability thresholds, restricting addressable reservoir inventory.
Strategic Opportunities
- Argentina Vaca Muerta Development:Unconventional resource expansion in Neuquén Basin creates demand for North American-proven completion technologies adapted to local supply chain constraints.
- Electrification Mandates:BSEE and EPA regulatory acceleration toward reduced diesel combustion on offshore platforms incentivizes electrically actuated downhole tools with lower emissions profiles.
- Geothermal Energy Convergence:Oilfield drilling and completion technologies transfer to enhanced geothermal systems, opening equipment reuse channels as hydrocarbon operators diversify.
Industry Challenges
- Downhole Electronics Reliability Engineering:Sustained performance of sensors and actuators at 350°F-plus temperatures requires specialized semiconductor packaging expertise scarce outside integrated service companies.
- API 5CT Certification Timelines:Extended testing protocols for new material grades delay product commercialization, compressing revenue recognition windows against competitor first-mover advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Downhole Equipment Market |
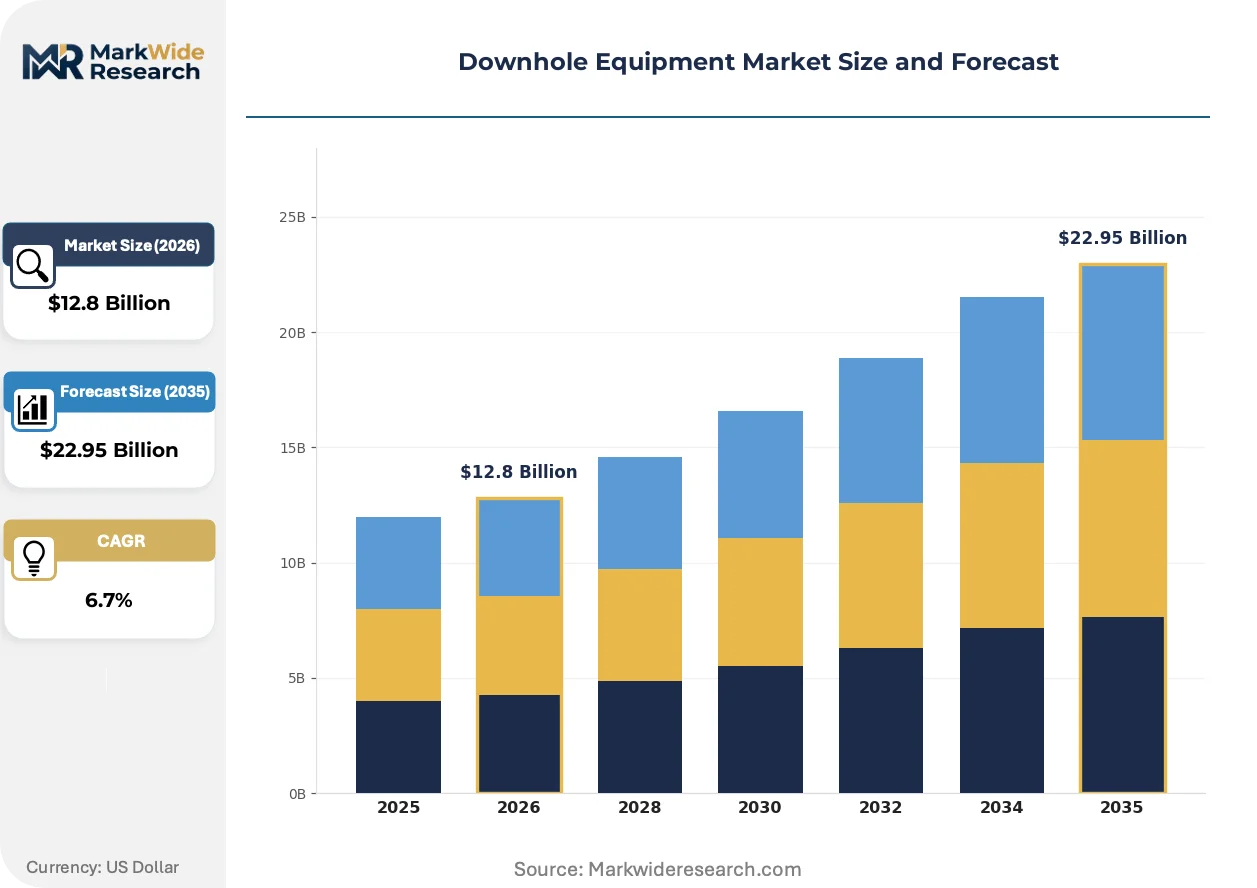
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Tools, Completion Equipment, Pressure Control Equipment, Well Intervention Tools Application: Oil Extraction, Natural Gas Recovery, Geological Exploration, Subsurface Monitoring End User: Oil & Gas Companies, Energy Service Providers, Mining Corporations, Environmental Agencies Technology: Hydraulic Systems, Mechanical Systems, Electrical Systems, Automation Solutions |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton Company, National Oilwell Varco, Weatherford International, TechnipFMC, Hunting PLC, Tenaris, Core Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Downhole Equipment Market Evolving Landscape
Digital instrumentation and remote operability are redefining equipment specifications across drilling, completion, and intervention phases. Operators now prioritize tool systems that minimize personnel exposure and enable subsea or remote-location control.
Intelligent completion technology is expanding into mature field redevelopment projects where marginal economics previously prohibited intervention-heavy optimization. Independent operators in the Permian and Eagle Ford are deploying remote-actuated inflow control devices to manage water breakthrough without rig mobilization. This capability compression extends productive life on older wells while reducing operating expenditure volatility.
The EPA's methane emissions regulations are forcing equipment redesigns across the wellhead-to-reservoir interface. Sealing technology improvements and continuous monitoring integration now feature in procurement specifications for new completions. Offshore operators in US federal waters face the most stringent compliance timelines, accelerating adoption of zero-emission valve actuation and closed-loop venting systems.
Integrated service contracts are displacing discrete equipment purchases as the dominant commercial model. National oil companies in the Middle East and major independents in North America now favor performance-based arrangements where suppliers assume deployment risk and uptime accountability. This shift concentrates purchasing authority with integrated service providers and compresses margins for standalone equipment manufacturers lacking field execution capabilities.
Downhole Equipment Market Segmentation
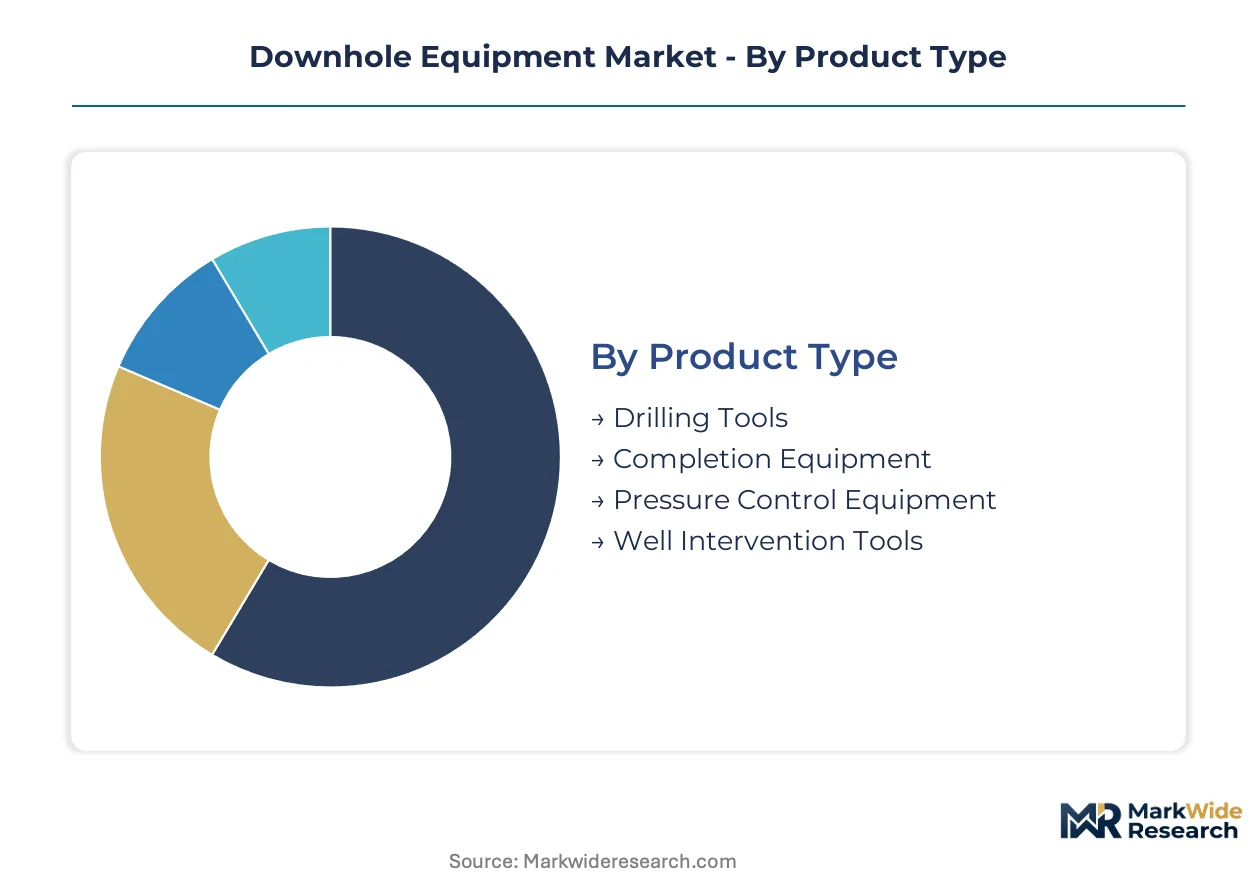
Downhole equipment procurement varies sharply by operational phase and technical complexity. Capital allocation patterns differ between exploration drilling, completion-intensive shale development, and mature field intervention work.
Product Type:
Completion equipment demands the heaviest upfront capital outlay due to multistage fracturing hardware and intelligent well architectures. Drilling tools require substantial investment in premium connections and directional steering systems. Pressure control equipment and well intervention tools occupy lower capital tiers but carry critical safety specifications.
- Completion Equipment:Multistage fracturing sleeves, liner hangers, and packers constructed from high-chrome alloys rated for 15,000-plus psi environments. Demand concentrates in the Permian Basin where extended lateral wells exceeding 15,000 feet require fatigue-resistant connections and remote-actuated inflow control devices. EPA methane rules are forcing redesigns of sealing interfaces across new installations.
- Drilling Tools:Directional drilling assemblies, measurement-while-drilling sensors, and polycrystalline diamond compact bits engineered for abrasive formations. North American shale operators deploy these in pad drilling configurations that compress rig-up cycles and reward modular tool packages. API 5CT specification upgrades are reshaping procurement criteria for premium tubulars.
- Pressure Control Equipment:Blowout preventers, wellheads, and annular seals maintaining wellbore integrity during pressure fluctuations.
- Well Intervention Tools:Coiled tubing units, wireline logging instruments, and thru-tubing fishing systems for workover operations in aging basins.
Most installed capacity flows through Completion Equipment. Expansion is steepest in Well Intervention Tools.
Application:
Volume concentration tracks hydrocarbon development intensity rather than exploration activity. Oil extraction applications dominate capital deployment, while geological exploration represents a smaller, specification-driven segment.
- Oil Extraction:Artificial lift systems, electric submersible pumps, and rodless progressive cavity pumps deployed in primary and secondary recovery phases. Unconventional operators in the Permian and Eagle Ford basins drive specification requirements for higher-flow-rate configurations. Intelligent completion adoption enables real-time production optimization without well intervention.
- Natural Gas Recovery:Gas lift valves, plunger lift systems, and dew point control equipment for dry and wet gas formations. Appalachian Basin operators deploy these in extended-reach horizontal wells where liquid loading management determines economic viability. Fugitive emissions monitoring integration is becoming standard procurement requirement.
- Geological Exploration:Core sampling tools, formation evaluation sensors, and sidewall coring devices for data acquisition in frontier basins.
- Subsurface Monitoring:Distributed temperature sensing, permanent downhole gauges, and microseismic arrays for reservoir surveillance.
Oil Extraction commands the largest equipment installed base. Subsurface Monitoring is climbing the fastest as operators prioritize data-driven reservoir management.
End User:
Procurement authority concentrates with entities controlling drilling schedules and reservoir access. Oil and gas companies retain specification-setting power, while service providers execute field deployment.
- Oil & Gas Companies:Integrated majors and independent operators defining technical specifications and awarding integrated service contracts. These entities in the Permian Basin and Gulf of Mexico drive standardization around intelligent completion architectures. BSEE safety mandates and EPA emissions rules directly shape their procurement criteria.
- Energy Service Providers:Drilling contractors, completion specialists, and intervention companies deploying owned or leased equipment under performance-based arrangements. North American pressure pumping fleets and coiled tubing units operate under this model. Margin compression in commoditized services is forcing asset-light strategies.
- Mining Corporations:Entities adapting oilfield drilling technologies for mineral extraction and in-situ leaching operations.
- Environmental Agencies:Government bodies procuring monitoring equipment for groundwater protection and carbon sequestration verification.
Oil & Gas Companies account for the majority of specification authority. Energy Service Providers are gaining share fastest through integrated contract expansion.
Technology:
Electrification trajectories and automation readiness now differentiate technology categories more than mechanical reliability alone. Hydraulic systems retain volume dominance while electrical architectures capture specification attention.
- Automation Solutions:Remote-actuated valves, autonomous inflow control devices, and digitally integrated completion systems enabling subsea or surface-controlled optimization. Permian Basin independents deploy these to manage water breakthrough and gas coning without rig mobilization. BSEE electrification mandates for offshore platforms accelerate adoption of electrically actuated architectures.
- Hydraulic Systems:Conventional fracturing pumps, power tongs, and hydraulic setting tools proven in high-pressure operations. These systems dominate legacy installed bases across North American land operations. Maintenance intensity and diesel combustion profiles face regulatory pressure under EPA emissions frameworks.
- Mechanical Systems:Simple intervention tools, manual packers, and mechanical slips for low-complexity well servicing.
- Electrical Systems:Electric submersible pumps, permanent magnet motors, and cable-deployed sensors for power-efficient artificial lift.
Hydraulic Systems retain the largest installed base. Automation Solutions are expanding most quickly as operators prioritize remote operability and emissions reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The downhole equipment industry traces its modern scale to early 20th-century American oilfield development, when rotary drilling innovations in Texas and California established the technical foundations for today's high-pressure, high-temperature tool systems deployed worldwide.
United States
Permian Basin operators drive specification requirements for extended-reach laterals exceeding 15,000 feet, demanding fatigue-resistant connections and remote-actuated completion systems. EPA methane emissions rules mandate improved sealing technologies and continuous monitoring integration across new wellhead installations. Midland-Odessa anchors the densest concentration of pressure pumping fleets and coiled tubing units globally.
Saudi Arabia
Aramco's mega-field development programs sustain demand for intelligent completion architectures and premium tubulars rated for sour gas service. The country's national oil company procurement frameworks prioritize integrated service contracts with uptime accountability clauses. Dhahran-Riyadh corridor hosts the dominant engineering centers for Middle East well construction technology adaptation.
China
Sinopec and PetroChina accelerate shale gas development in Sichuan Basin, importing North American-proven multistage fracturing technologies adapted to local geological conditions. MIIT industrial standards and GB certification protocols govern material specifications for domestic tubular manufacturing. Chongqing-Chengdu cluster concentrates drilling tool fabrication capacity serving western domestic basins.
Brazil
Pre-salt carbonate developments offshore drive demand for subsea completion systems and high-pressure riser equipment exceeding 15,000 psi ratings. ANP regulatory frameworks impose local content requirements that reshape supplier qualification criteria for deepwater projects. Rio de Janeiro metropolitan area anchors engineering centers for floating production system integration.
Norway
Equinor's Johan Sverdrup and Northern Lights carbon capture projects sustain demand for subsea tieback systems and electrified well intervention tools. Petroleum Safety Authority regulations mandate redundant barrier systems and real-time monitoring for subsea well control equipment. Stavanger-Bergen corridor concentrates subsea technology engineering expertise for North Sea harsh-environment applications.
Downhole Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with integrated service providers commanding performance-based contract premiums while standalone manufacturers face procurement authority concentration. The vendor base stratifies into three tiers: full-service companies bundling equipment with field execution, technology licensors controlling proprietary connection designs, and regional fabricators competing on delivery speed and customization flexibility. Dominant competitive moves include vertical integration into raw material supply chains and strategic partnerships to secure semiconductor packaging expertise for high-temperature electronics.
Within the integrated service tier, Schlumberger Limited and Baker Hughes Company occupy positions anchoring premium market segments through bundled drilling-evaluation-completion portfolios. Halliburton Company exemplifies the North American infrastructure-heavy archetype, with extensive pressure pumping and intervention service networks. These three entities represent the dominant competitive anchors against which independent equipment manufacturers and regional specialists define differentiation strategies.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton Company |
| National Oilwell Varco |
| Weatherford International |
| TechnipFMC |
| Hunting PLC |
| Tenaris |
| Core Laboratories |
| Others |
Value Network & Pricing Analysis
Specialized metallurgical engineering talent concentrated in Houston-Greenville corridors commands wage premiums that compress margins at standard-tier equipment manufacturers while amplifying spreads between premium and economy product lines. API 5CT-certified alloy steel procurement costs and BSEE compliance investments further stratify pricing tiers as buyers sort by certification grade and field-proven reliability.
Pricing Analysis
Project-based contract pricing with performance-linked incentives dominates capital equipment procurement, separating intelligent completion systems with uptime guarantees from commodity tubulars sold on spot delivery terms. Price differentiation rests on fatigue-cycle certification grades and integrated service bundling rather than hardware alone. Cost compression in standard-connection manufacturing intensifies as Chinese mills expand API-licensed capacity. Independent Permian operators exhibit highest price sensitivity, while Aramco and Equinor procurement frameworks prioritize lifecycle reliability over upfront capital outlay.
Supply Chain Analysis
Direct-to-operator channels handle mega-project demand from national oil companies, while distributor networks serve independent North American shale operators requiring rapid field delivery. Manufacturing concentrates in the United States, China, and Norway, with high-chrome alloy forging capacity anchored in Houston and Stavanger corridors. Raw material dependencies draw from chromium suppliers in South Africa and Kazakhstan, plus molybdenum from Chilean mining operations. Single-source vulnerability around proprietary thread design licensors creates procurement bottlenecks for independent tool manufacturers. Distribution runs through integrated service company inventories and regional stocking locations near Permian and Appalachian drilling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in intelligent completion architectures where EPA methane compliance mandates and BSEE electrification rules force replacement cycles across installed bases. Premium-tier suppliers capture this value through integrated service contracts bundling hardware with remote monitoring capabilities.
For Market Incumbents: Extend intelligent completion platform coverage into mature field redevelopment segments where marginal economics previously prohibited intervention-heavy optimization. Consolidate semiconductor packaging expertise for 350°F-plus downhole electronics through targeted capability acquisition, defending against integrated service competitors with captive high-temperature sensor manufacturing. Deepen backward integration into chromium and molybdenum supply channels to insulate margins from alloy price volatility. For New Entrants and Emerging Players: EPA methane emissions rules in US federal waters open a window for sealing technology specialists with integrated monitoring architectures to penetrate offshore completion markets. Target Argentina Vaca Muerta development where Neuquén Basin operators seek North American-proven multistage fracturing technologies adapted to local supply chain constraints. Pursue geothermal energy convergence opportunities where oilfield drilling expertise transfers to enhanced geothermal system deployment with minimal technology adaptation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with API 5CT certification and customization flexibility serving Permian independents. Long-term viability favors entities with demonstrated high-temperature electronics reliability and electrified actuation portfolios aligned with regulatory trajectories. Watch BSEE electrification mandate implementation timelines as inflection indicator for electrically actuated tool demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Intelligent Completion Platform Expansion | Remote-actuated architectures capture EPA compliance-driven replacement demand across Permian well populations. |
| High-Temperature Electronics Capability Acquisition | Semiconductor packaging expertise for 350°F-plus sensors differentiates against integrated service competitors. |
| Backward Integration into Alloy Supply | Captive chromium and molybdenum sourcing insulates margins from raw material price volatility. |
| Geothermal Technology Transfer | Oilfield drilling expertise opens equipment reuse channels as hydrocarbon operators diversify revenue. |
| Argentina Market Entry Partnership | Vaca Muerta development creates demand for North American-proven completion technologies with local adaptation. |
Research Methodology
Bottom-up drilling and completion activity modeling reconciled against top-down tubular manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drilling engineers, completion specialists, procurement managers at Permian independents, and subsea project directors at integrated majors inform operational assumptions. Secondary validation draws from API certification registries, BSEE incident reporting databases, EPA emissions compliance filings, and customs records for alloy steel imports. Cross-referencing field deployment data against manufacturer order backlogs enables triangulation of equipment demand by product category.
Historical trendline analysis of capital allocation patterns across unconventional basins establishes baseline growth trajectories, with projection adjustments for regulatory acceleration and technology substitution effects. The modeling framework segments by completion intensity, well architecture complexity, automation readiness, and regional regulatory cluster. CAGRs derive from equipment unit economics tied to lateral length extensions and stage count proliferation. Forecast inputs include rig count trajectories, frac fleet utilization, and intelligent completion adoption curves across mature field redevelopment projects.
Revisions become necessary when EPA methane rule enforcement timelines shift, BSEE electrification mandates accelerate, or alloy steel price volatility exceeds historical bands. Forecasts reflect documented assumptions regarding Permian drilling intensity and subsea project sanctioning rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Qatar Oilfield Chemicals Market