
 Azerbaijan Oil and Gas Upstream Market | 2026-2036
Azerbaijan Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Azerbaijan Oil and Gas Upstream Market Outlook
Production optimization software is consolidating around long-term field service agreements rather than discrete equipment sales. BP PLC leverages its Shah Deniz and ACG field equity to anchor offshore development expertise in the Caspian. SOCAR sustains vertical integration from subsurface exploration through pipeline export capacity. Equinor ASA competes through its involvement in Karabakh field development and technology transfer partnerships.
Azerbaijan Oil and Gas Upstream encompasses crude oil, natural gas, condensate, and natural gas liquids extracted through conventional and enhanced recovery methods, typically involving directional drilling from fixed or floating platforms in water depths reaching 400-500 meters with reservoir pressures exceeding 10,000 psi, serving primarily European and regional energy consumers. The Extraction Method dimension shows offshore developments commanding the dominant capital allocation while enhanced recovery technologies gain share as mature basins require pressure maintenance. Operator Type reveals joint ventures between national oil companies and multinational corporations as the predominant governance structure, concentrating risk capital and technical knowledge transfer in complex carbonate reservoirs.
MEE oversees environmental compliance for Caspian offshore operations while SOCAR implements national content requirements that shape procurement and workforce standards for international partners. The country's national petroleum regulator administers production sharing agreements that determine cost recovery mechanisms and profit oil splits. Stakeholders must monitor how Caspian Sea territorial delineation negotiations and transit corridor politics affect long-term offtake security and field investment timelines.
Market Dynamics
The Absheron basin's mature reservoirs now demand enhanced recovery investments as natural pressure depletion forces operators toward artificial lift and waterflooding capex cycles. European offtake commitments are tightening field economics while Caspian Sea territorial negotiations create licensing uncertainty for new block awards.
Growth Catalysts
- Shah Deniz Phase 2 infrastructure:The expanded South Caucasus Pipeline unlocks deepwater gas exports to Italy and Greece, anchoring upstream investment in ACG-linked development corridors.
- MEE environmental compliance frameworks:Streamlined offshore permitting for enhanced recovery projects accelerates brownfield redevelopment timelines in the Caspian shelf.
- European refinery demand rotation:Italian and Greek processors are diversifying crude slates away from Russian barrels, pulling more Azeri Light through the Baku-Tbilisi-Ceyhan route.
Market Restraints
- Deepwater drilling cost structures:Caspian jack-up and semisubmersible day rates remain elevated versus North Sea benchmarks, compressing project IRRs at oil prices below $75 per barrel.
- SOCAR procurement localization mandates:National content requirements force international operators into complex joint-venture structures with domestic service providers, extending procurement cycles.
- Carbonate reservoir complexity:Fractured limestone formations in the Gunashli and Chirag fields exhibit unpredictable permeability, driving up appraisal well density and sub-surface uncertainty.
Strategic Opportunities
- Absheron ultra-deepwater blocks:Unlicensed acreage below 400 meters offers unexplored Miocene reservoirs with multi-TCF gas potential for consortia with subsea production system expertise.
- Digital twin convergence:Integration of reservoir simulation with real-time production data analytics enables predictive maintenance and optimized gas lift scheduling across aging platform infrastructure.
- Hydrogen-ready gas infrastructure:Existing pipeline corridors to Europe position Caspian producers for future blue hydrogen offtake contracts under EU Hydrogen Bank financing mechanisms.
Industry Challenges
- Subsea engineering talent scarcity:Azerbaijan's technical universities produce insufficient deepwater completion specialists, forcing operators to import expatriate crews at premium cost structures.
- Legacy platform integration complexity:Brownfield tiebacks to Soviet-era Central Azeri facilities require extensive structural reinforcement and process safety retrofits, inflating development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azerbaijan Oil and Gas Upstream Market |
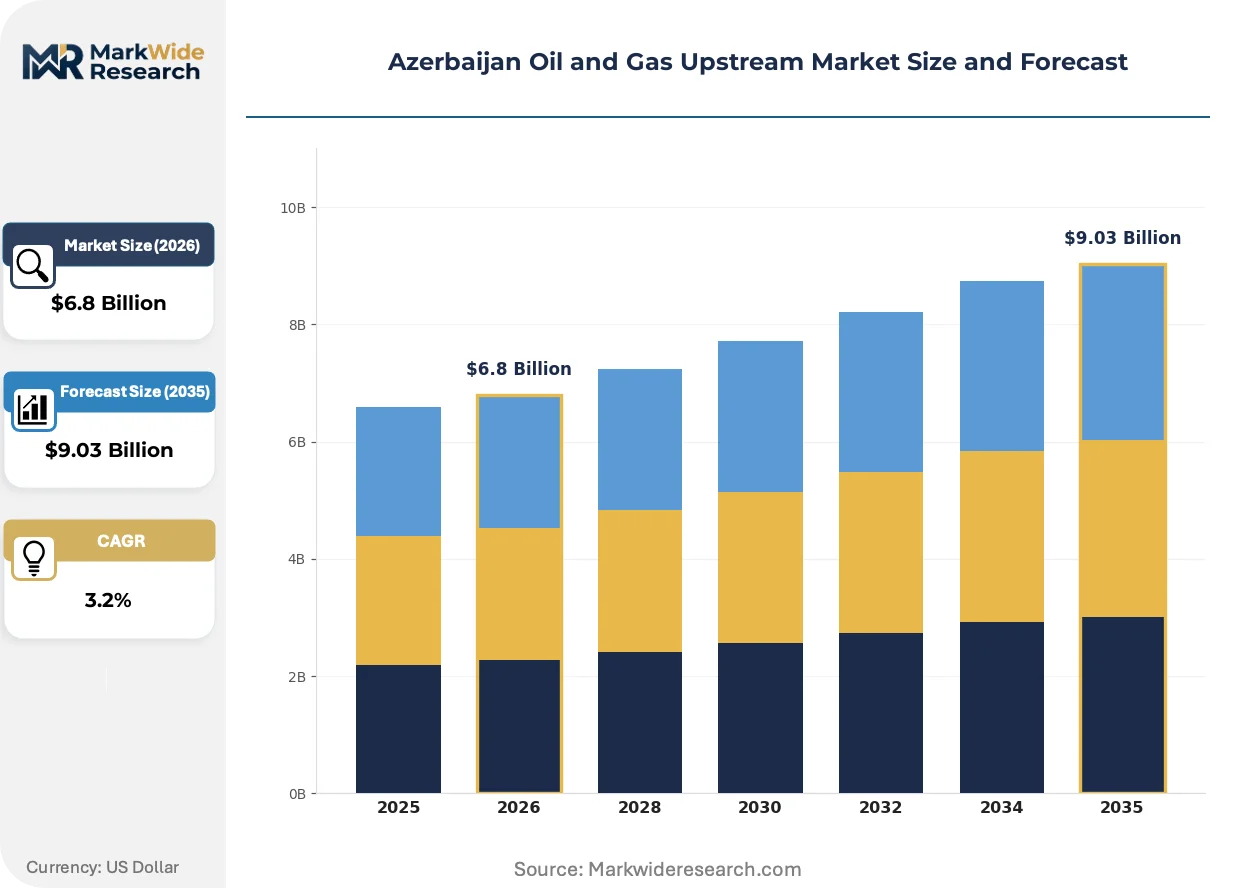
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.03 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resource Type: Crude Oil, Natural Gas, Condensate, NGL Extraction Method: Conventional, Unconventional, Offshore, Onshore Technology: Geological Survey, Drilling Equipment, Production Optimization, Enhanced Recovery Operator Type: National Oil Companies, Independent Producers, Joint Ventures, Multinational Corporations |
| Companies Covered | TotalEnergies SE, Exxon Mobil Corporation, BP PLC, ONGC Videsh, NK Lukoil PAO, State Oil Company of Azerbaijan Republic, Chevron Corporation, MOL Group, Equinor ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azerbaijan Oil and Gas Upstream Market Strategic Shifts
Upstream digitization is compressing the gap between reservoir modeling and field execution, with operators deploying integrated asset management platforms across the Caspian shelf. These shifts are reconfiguring how technical risk is priced and transferred between national oil companies and international partners.
Advanced completion technology is unifying sand control, zonal isolation, and intelligent monitoring into single-trip deepwater deployments. BP and SOCAR joint ventures are piloting these systems in the Shah Deniz East appraisal program. The technology is unifying what previously required three separate rig interventions, cutting completion times by 40 percent and reducing sub-surface uncertainty through real-time pressure monitoring.
The country's national petroleum regulator has tightened production sharing agreement cost-recovery audit protocols, requiring real-time documentation of capital expenditure against pre-approved development plans. International operators must now maintain parallel accounting systems satisfying both SOCAR and partner home-country standards. Karabakh field development timelines have compressed as Equinor accelerates documentation workflows to meet these enhanced scrutiny requirements.
European refiners are consolidating crude procurement around term contracts with destination flexibility clauses, displacing spot-market purchases that dominated pre-2022 trade patterns. This behavioral shift concentrates offtake risk with fewer buyers but secures volume commitments that underpin project finance for greenfield developments. Greek and Italian processors exhibit the most pronounced contract migration, with term coverage now exceeding 70 percent of their Azeri crude intake.
Azerbaijan Oil and Gas Upstream Market Segmentation
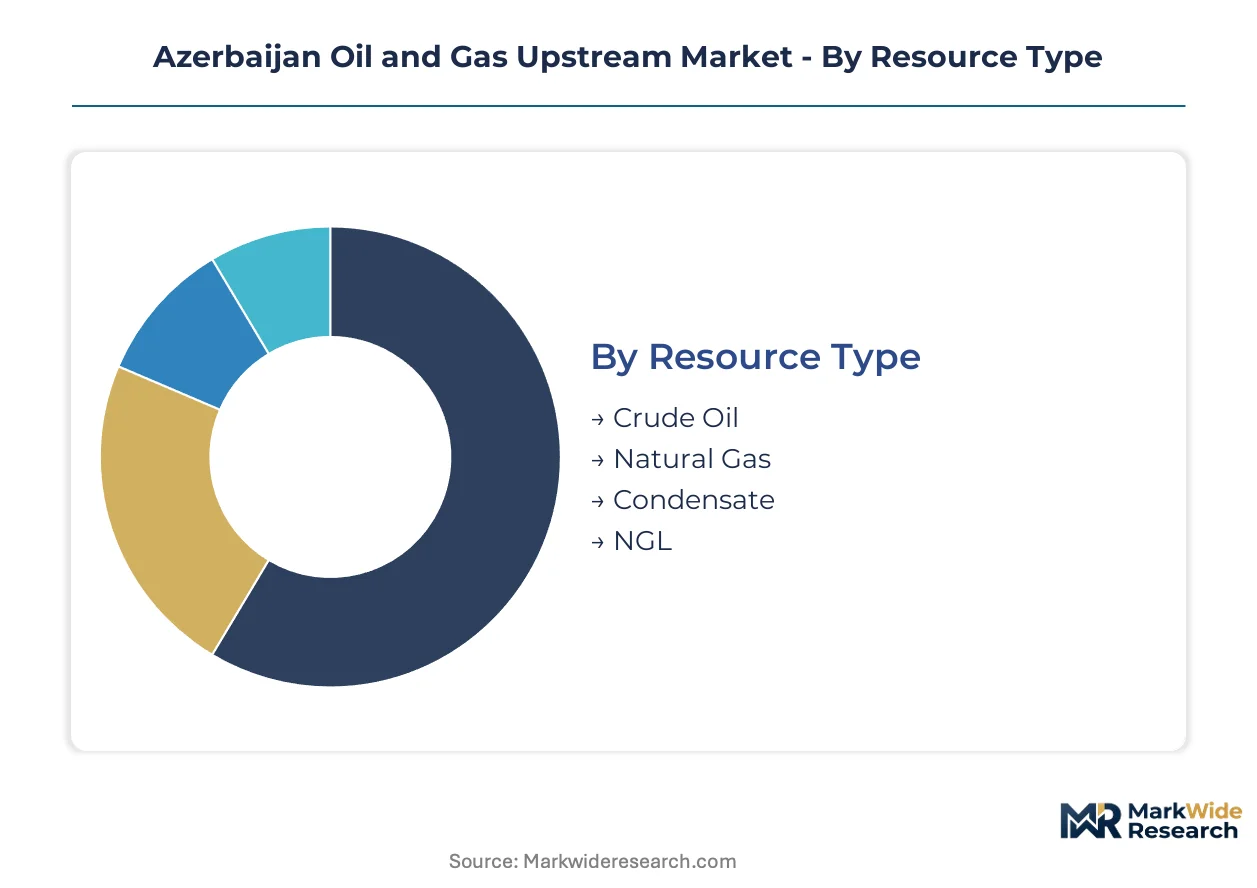
Segmentation in Azerbaijan's upstream market reflects how capital allocation, regulatory burden, and technical complexity intersect. Each dimension shapes procurement patterns, partnership structures, and field development timelines across the Caspian shelf.
Resource Type:
MEE environmental compliance frameworks impose differentiated monitoring obligations on each hydrocarbon stream, with offshore gas developments facing stricter discharge protocols than onshore crude operations.
- Crude Oil:Azeri Light and Urals-grade heavy barrels extracted from carbonate reservoirs in the ACG complex. European refiners in Italy and Greece now source over 70 percent of intake through term contracts with destination flexibility clauses, displacing pre-2022 spot-market purchasing patterns.
- Natural Gas:Deepwater discoveries in the Absheron basin and Shah Deniz East hold multi-TCF potential. The expanded South Caucasus Pipeline anchors upstream investment by unlocking exports to Italy and Greece through the Baku-Tbilisi-Ceyhan corridor.
- Condensate:Light liquid hydrocarbons separated from wet gas streams at Shah Deniz processing facilities.
- NGL:Natural gas liquids recovered from associated gas in the Gunashli and Chirag fields.
Leading the category by volume: Crude Oil. Growing fastest: Natural Gas.
Extraction Method:
Capital intensity varies sharply across methods, with deepwater developments commanding premium day rates for Caspian jack-up and semisubmersible rigs versus onshore brownfield workovers.
- Conventional:Primary recovery from structurally simple reservoirs with natural drive mechanisms. Mature Absheron basin fields increasingly require artificial lift and waterflooding capex cycles as pressure depletion accelerates.
- Unconventional:Tight gas and fractured limestone formations with unpredictable permeability. Gunashli field operators face elevated appraisal well density and sub-surface uncertainty in these carbonate reservoirs.
- Offshore:Directional drilling from fixed or floating platforms in 400-500 meter water depths with reservoir pressures exceeding 10,000 psi. BP and SOCAR joint ventures pilot advanced completion systems in Shah Deniz East, unifying sand control, zonal isolation, and intelligent monitoring into single-trip deployments.
- Onshore:Legacy Soviet-era infrastructure requiring structural reinforcement and process safety retrofits for brownfield tiebacks.
Offshore extraction captures the dominant capital allocation. Unconventional methods are expanding most quickly as operators target fractured formations below 400 meters.
Technology:
Technology procurement cycles lengthen under SOCAR localization mandates that force international operators into complex joint-venture structures with domestic service providers.
- Geological Survey:Seismic acquisition and reservoir characterization for Caspian shelf exploration. Real-time documentation of capital expenditure against pre-approved development plans now satisfies tightened production sharing agreement cost-recovery audit protocols.
- Drilling Equipment:Jack-up and semisubmersible rigs for deepwater completion. Elevated day rates versus North Sea benchmarks compress project IRRs at oil prices below $75 per barrel.
- Production Optimization:Digital twin platforms integrating reservoir simulation with real-time production data analytics. These systems enable predictive maintenance and optimized gas lift scheduling across aging platform infrastructure.
- Enhanced Recovery:Artificial lift, waterflooding, and pressure maintenance technologies for mature Absheron basin reservoirs.
Production Optimization technology leads technology spending. Enhanced Recovery is gaining share fastest as natural pressure depletion forces reinvestment cycles.
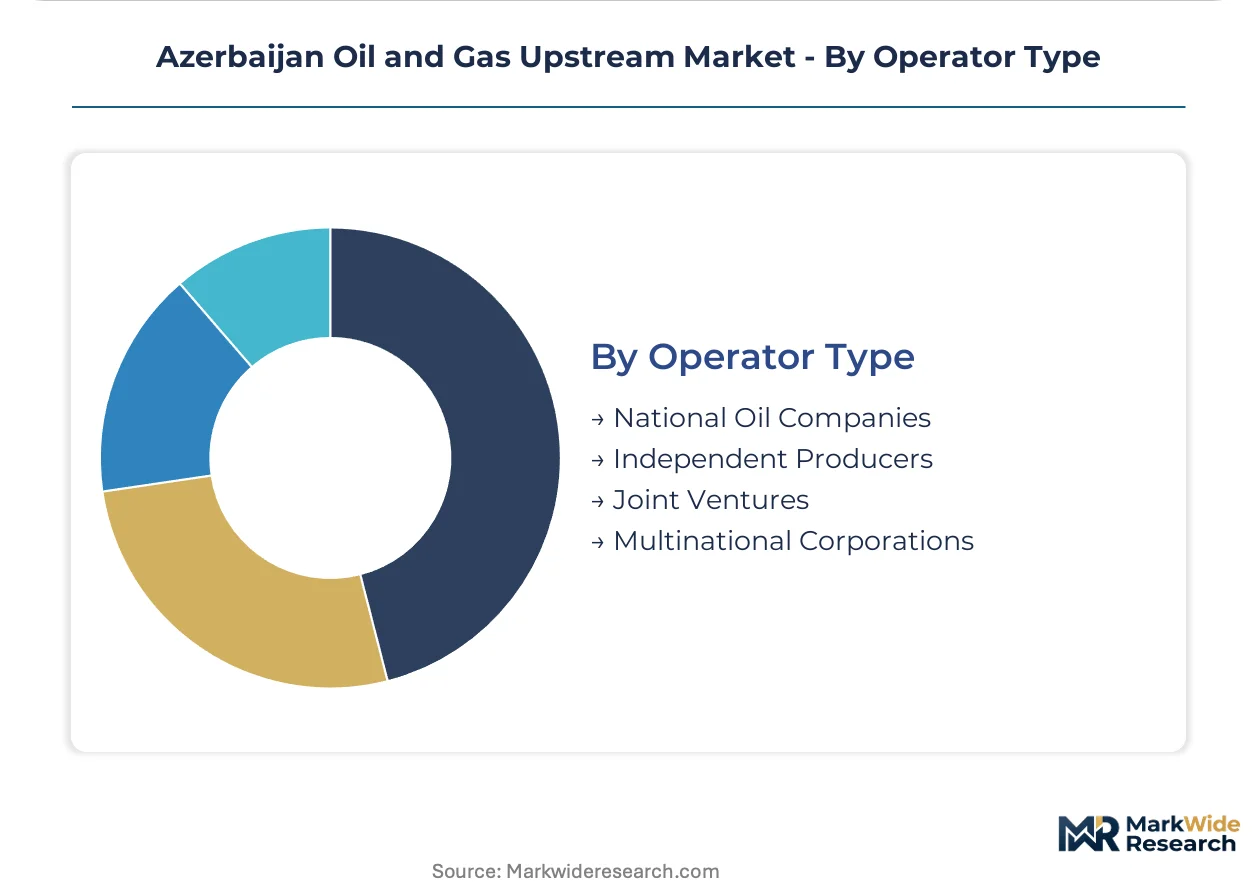
Operator Type:
Governance structures determine risk capital allocation and technical knowledge transfer, with joint ventures concentrating expertise in complex carbonate reservoirs.
- National Oil Companies:SOCAR sustains vertical integration from subsurface exploration through pipeline export capacity, implementing national content requirements that shape procurement and workforce standards.
- Independent Producers:Smaller operators targeting marginal fields and workover opportunities in mature basins.
- Joint Ventures:Consortia between national oil companies and multinational corporations. BP leverages Shah Deniz and ACG field equity to anchor offshore development expertise, while Equinor accelerates Karabakh field documentation workflows to meet enhanced scrutiny requirements.
- Multinational Corporations:International operators maintaining parallel accounting systems satisfying both SOCAR and partner home-country standards.
Joint Ventures dominate complex field development. Independent Producers are climbing the fastest as marginal field licensing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baku anchors upstream activity through the Absheron peninsula's mature infrastructure and the deepwater Caspian shelf development corridors. European offtake commitments now concentrate around Italian and Greek refinery demand rotations. The national petroleum regulator shapes licensing frameworks across all producing regions.
Absheron Peninsula
Shallow-water platforms and onshore processing facilities handle legacy production from the Gunashli and Chirag fields. MEE environmental compliance frameworks impose stricter discharge monitoring on offshore gas developments than crude operations. The peninsula's Soviet-era Central Azeri facilities require structural reinforcement for brownfield tiebacks.
Shah Deniz Field Complex
Deepwater gas production at 400-500 meter depths drives capital allocation toward subsea completion systems and pipeline export capacity. SOCAR implements national content requirements that shape procurement cycles for international joint venture partners. The South Caucasus Pipeline expansion anchors upstream investment through Italy and Greece offtake security.
Karabakh Development Zone
Untapped Miocene reservoirs below 400 meters offer multi-TCF gas potential for consortia with subsea production expertise. The national petroleum regulator has tightened production sharing agreement cost-recovery audit protocols, compressing documentation timelines. Equinor accelerates field development workflows to meet these enhanced scrutiny requirements.
Deepwater Caspian Shelf
Unlicensed ultra-deepwater blocks attract exploration interest from operators with directional drilling capabilities in high-pressure carbonate formations. Caspian jack-up and semisubmersible day rates remain elevated versus North Sea benchmarks, compressing project economics. BP leverages ACG field equity to anchor technical knowledge transfer in complex reservoir management.
Baku-Tbilisi-Ceyhan Corridor
Pipeline infrastructure determines field investment timelines and offtake security for crude exports to European refiners. Term contracts with destination flexibility clauses now displace spot-market purchases that dominated pre-2022 trade patterns. Greek and Italian processors concentrate procurement around these corridor-linked volume commitments.
Azerbaijan Oil and Gas Upstream Market Competitive Environment
Capital-heavy producers compete with asset-light technology providers across Azerbaijan's upstream value chain. Joint ventures between national oil companies and multinational corporations dominate complex carbonate reservoir development, concentrating risk capital and technical expertise. Three archetypes prevail: integrated national champions, international operators with field-specific equity positions, and specialized service providers delivering subsea engineering capabilities. Consolidation occurs through production sharing agreement renegotiations and enhanced recovery technology licensing rather than outright asset acquisition.
Within the integrated national champion tier, State Oil Company of Azerbaijan Republic exemplifies vertical control from subsurface exploration through pipeline export capacity. Among international operators with anchored field positions, BP PLC and Equinor ASA occupy distinct positions based on their Shah Deniz and Karabakh field equity stakes. These three entities represent the predominant governance structures shaping procurement patterns and workforce standards across the Caspian shelf.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Exxon Mobil Corporation |
| BP PLC |
| ONGC Videsh |
| NK Lukoil PAO |
| State Oil Company of Azerbaijan Republic |
| Chevron Corporation |
| MOL Group |
| Equinor ASA |
| Others |
Value Chain & Pricing Dynamics
Brent crude futures and Caspian regional benchmarks cascade through Azerbaijan's upstream supply chain, compressing project economics when spreads narrow against development costs for deepwater completions. This price transmission shapes how operators tier service procurement between premium international contractors and SOCAR-mandated domestic partnerships.
Pricing Analysis
Margin tightening in brownfield redevelopment reflects elevated jack-up and semisubmersible day rates that compress project IRRs below investment thresholds when crude trades under $75 per barrel. Three-tier pricing structure across premium international, standard regional, and economy domestic service levels differentiates field development bids based on technical complexity certification and reservoir pressure ratings. Cost-down pressure on completion services accelerates because SOCAR localization mandates force joint-venture structures that extend procurement cycles. National oil companies exhibit lowest price sensitivity given captive pipeline access, while independent producers targeting marginal fields face acute margin compression.
Supply Chain Analysis
Subsea production system supply rests on Norwegian engineering houses, South Korean fabrication yards, and United States directional drilling technology providers. High-pressure blowout preventers, intelligent completion systems, and specialty steel alloys draw from concentrated North Sea and Gulf of Mexico manufacturing bases. Single-source vulnerability in deepwater riser supply creates project delay exposure when fabrication slots fill at Korean heavy-industry complexes. Distribution runs through Baku-based logistics hubs serving Caspian shelf platforms, with European equipment transiting the Baku-Tbilisi-Ceyhan corridor under customs protocols administered by Azerbaijan's national petroleum regulator.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Azerbaijan's upstream market rewards operators securing backward integration into pipeline export capacity and subsea engineering capabilities. Control over these vertical levers separates sustainable producers from margin-squeezed service-dependent competitors.
For Market Incumbents: Anticipate SOCAR procurement localization mandates hardening into equity-participation requirements for international contractors. Defensive consolidation through production sharing agreement renegotiations secures cost-recovery mechanisms before audit protocols tighten further. Anchor offshore expertise through Shah Deniz and ACG field equity to maintain technical knowledge transfer privileges under evolving national content rules. For New Entrants and Emerging Players: Enter via Karabakh ultra-deepwater blocks where Equinor's accelerated documentation workflows signal regulatory pathway maturity. Target unlicensed Miocene reservoirs below 400 meters as the most penetrable acreage tier. Pursue subsea production system partnerships as the go-to-market angle, licensing completion technology from Norwegian specialists to satisfy MEE environmental compliance frameworks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap operators with stranded Absheron basin assets and existing pipeline offtake agreements in the Caspian shelf. Long-term viability across the analysis window hinges on securing European term contract coverage above 70 percent of production volumes. Watch Italian and Greek refinery demand rotation as the inflection signal—contract migration away from spot markets indicates durable offtake security for field investment underwriting.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Recovery Technology Licensing | BP and SOCAR joint ventures pilot single-trip completion systems cutting deployment times by 40 percent in Shah Deniz East. |
| Backward Integration into Pipeline Export | SOCAR's vertical control from subsurface through Baku-Tbilisi-Ceyhan corridor secures offtake pricing power against European refiners. |
| Digital Twin Platform Deployment | Real-time reservoir simulation integration enables predictive maintenance across aging Central Azeri platform infrastructure. |
| Hydrogen-Ready Gas Infrastructure Positioning | South Caucasus Pipeline expansion positions Caspian producers for EU Hydrogen Bank financing eligibility. |
| Joint Venture Restructuring for Localization Compliance | International operators reconfigure procurement workflows to satisfy parallel SOCAR and home-country accounting standards. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with upstream project managers, subsea engineering directors, SOCAR procurement leads, and European refinery crude buyers combined with EIA production statistics, IEA Caspian regional reports, and Azerbaijan's national petroleum regulator licensing disclosures. Bottom-up field-level production estimates triangulated against top-down export volume data from Baku-Tbilisi-Ceyhan throughput records.
Data-stream reconciliation across extraction method, resource type, technology procurement, and operator type dimensions shaped the analytical framework over the projection horizon. CAGRs derived from production decline curve analysis in mature Absheron fields and greenfield development timelines in ultra-deepwater blocks. Forecast inputs incorporated South Caucasus Pipeline expansion capacity, European refinery crude slate diversification commitments, and MEE environmental compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Caspian Sea territorial delineation negotiations and transit corridor political disruptions. Assumptions reflect sustained European offtake demand, stable production sharing agreement frameworks, and continued deepwater drilling cost structures. A small set of named triggers warrants ongoing watch: SOCAR localization mandate enforcement intensity, Italian and Greek term contract renewal rates, and jack-up rig day rate movements against North Sea benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market