
 Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market | 2026-2036
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market Outlook
The capital-intensity divergence between plasma fractionation specialists and biotech innovators is unwinding competitive boundaries in CIDP therapeutics. CSL Behring leverages its vertically integrated plasma collection network to sustain immunoglobulin supply security. Grifols anchors European manufacturing capacity while competing on fractionation yield efficiency.
Chronic Inflammatory Demyelinating Polyneuropathy is an autoimmune disorder characterized by progressive weakness and impaired sensory function due to peripheral nerve demyelination, typically diagnosed through nerve conduction studies and cerebrospinal fluid analysis. The condition requires sustained immunomodulatory intervention to prevent axonal loss and permanent disability. Intravenous immunoglobulin commands the largest revenue pool among product types, reflecting its established efficacy profile and broad prescriber familiarity. Monoclonal antibodies represent the fastest-expanding segment as novel mechanisms target FcRn receptors and complement pathways with improved dosing convenience.
FDA orphan drug incentives, EMA's centralized marketing authorization for rare neurological conditions, and Japan's PMDA Sakigake designation framework collectively shape clinical trial investment and market access timelines for CIDP therapies. Health technology assessment bodies in Germany and France increasingly weigh quality-adjusted life year thresholds against therapy costs, pressuring pricing for chronic administration regimens. Stakeholders must monitor regulatory precedent for biosimilar immunoglobulin entry and its implications for reference product defense strategies.
Market Dynamics
The CIDP therapeutics market is restructuring around plasma supply security and FcRn-targeting biologics, with manufacturers racing to secure fractionation capacity while neurology clinics demand subcutaneous administration alternatives to intravenous infusion centers.
Growth Catalysts
- FDA Orphan Drug Incentives:The FDA's orphan drug designation pathway accelerates clinical trial timelines and provides seven-year market exclusivity, drawing venture capital into novel monoclonal antibody programs targeting complement inhibition.
- Subcutaneous Immunoglobulin Formulations:Home-based subcutaneous delivery systems reduce infusion center dependency and improve patient adherence, expanding prescriber willingness to initiate maintenance therapy earlier in disease progression.
- Germany's Neurologist Density:Concentrated specialist infrastructure in German university hospitals supports rapid adoption of advanced immunomodulatory protocols and facilitates patient enrollment in investigator-initiated trials.
Market Restraints
- Plasma Collection Concentration:North American plasma collection networks dominate raw material supply, exposing European and Asian manufacturers to geopolitical disruption and donor pool access constraints.
- Health Technology Assessment Thresholds:France's HAS and Germany's IQWiG apply stringent quality-adjusted life year ceilings to chronic immunoglobulin regimens, pressuring reimbursement rates for maintenance therapy.
- Diagnostic Latency:Average eighteen-month delay from symptom onset to CIDP confirmation through nerve conduction studies and cerebrospinal fluid analysis delays treatment initiation and compresses addressable patient pools.
Strategic Opportunities
- Japan's PMDA Sakigake Designation:Japan's priority review framework for innovative neurological therapies offers expedited approval pathways and enhanced reimbursement for first-in-class FcRn antagonists entering the market.
- Biosimilar Immunoglobulin Entry:Emerging biosimilar entrants create white space for cost-conscious payers in Medicaid and European statutory health insurance systems seeking to diversify supplier bases.
- Neuromuscular Telemonitoring Integration:Remote patient monitoring platforms combining wearable grip-strength sensors with video-based disability scoring enable decentralized trial endpoints and real-world evidence generation.
Industry Challenges
- Specialized Neuromuscular Pathology Talent:Shortage of board-certified neuromuscular specialists capable of interpreting electrodiagnostic studies limits diagnostic throughput and clinical trial site activation.
- Plasma Fractionation Capex Requirements:New fractionation facilities demand substantial capital deployment for viral inactivation infrastructure and cold-chain logistics, constraining new market entry.
- Longitudinal Trial Design Complexity:CIDP's fluctuating disease course requires extended placebo-controlled observation periods, inflating per-patient trial costs and recruitment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market |
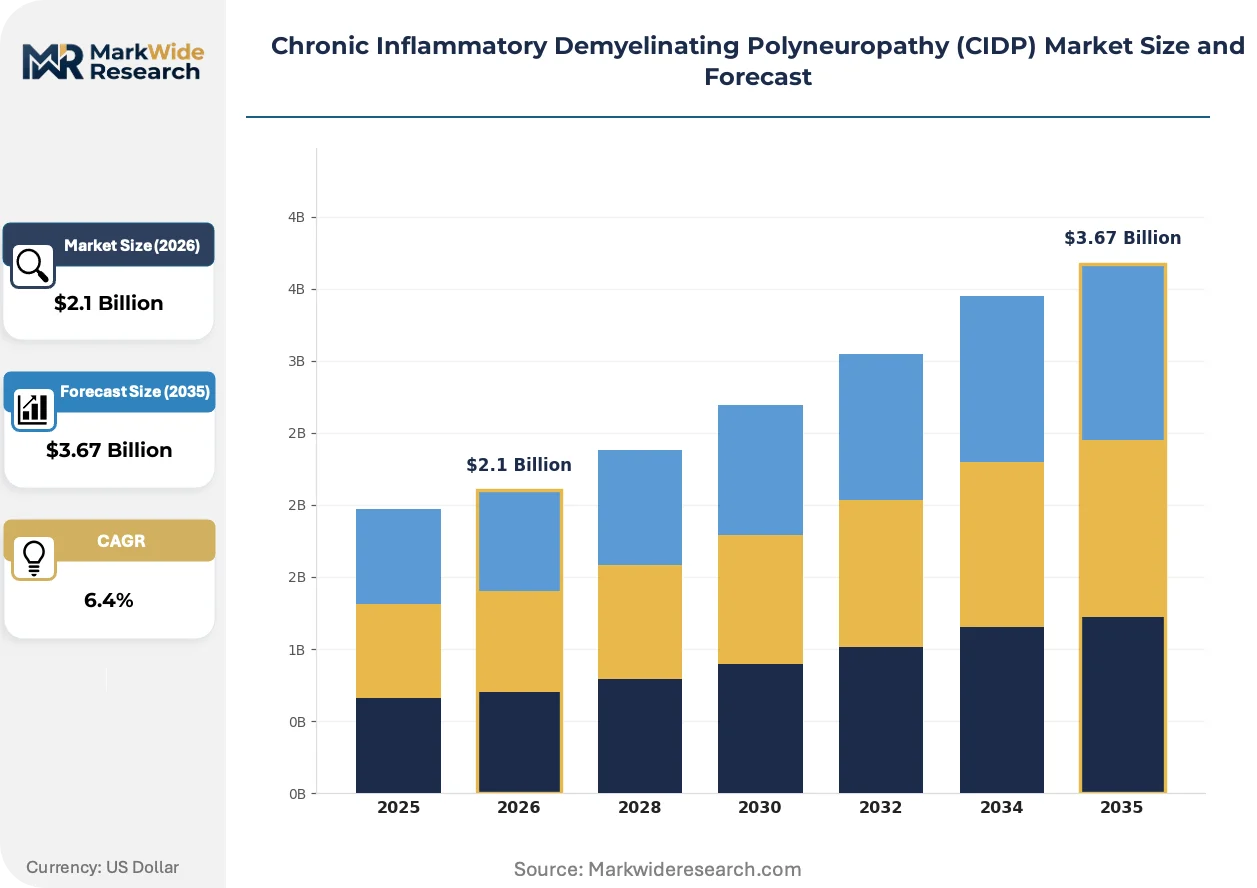
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Immunoglobulin, Corticosteroids, Plasma Exchange, Immunosuppressants, Monoclonal Antibodies Therapy Area: Autoimmune Neuropathies, Peripheral Nerve Disorders, Chronic Neurological Diseases, Inflammatory Disorders, Immune-Mediated Conditions End User: Neurology Clinics, Specialty Hospitals, Diagnostic Laboratories, Rehabilitation Centers, Academic Research Institutes Delivery Mode: Intravenous, Subcutaneous, Oral, Subdermal, Transdermal |
| Companies Covered | Octapharma, Sanofi, Grifols, Kedrion, Pfizer, CSL Behring, Takeda Pharmaceutical, Argenx, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market Strategic Shifts
Biologics development is pivoting toward FcRn receptor blockade and complement pathway inhibition, while regulatory frameworks and care delivery models co-evolve to accommodate chronic autoimmune neurology management outside traditional hospital settings.
Subcutaneous immunoglobulin pump technology is miniaturizing infusion volumes and enabling patient self-administration without nursing supervision. Neurology clinics in Germany and the United States are converting intravenous-dependent patients to weekly subcutaneous protocols. This shift is compressing site-of-care economics and reallocating reimbursement from hospital outpatient departments to home health channels.
EMA's centralized marketing authorization procedure for rare neurological conditions harmonizes clinical evidence requirements across member states, reducing redundant national submissions. The framework accelerates cross-border patient access but demands standardized disability outcome measures that complicate trial design for heterogeneous CIDP phenotypes. Biotech sponsors are responding by pre-negotiating parallel scientific advice with EMA and FDA to align development programs.
Patients and caregivers are organizing digital communities that aggregate real-world treatment experience and exert direct pressure on formulary decisions. These peer networks in Japan and France bypass traditional physician education channels and accelerate switching between immunoglobulin brands based on perceived tolerability profiles. Pharmaceutical account teams are reallocating field resources from specialist detailing to patient advocacy engagement and copay assistance program management.
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market Segmentation
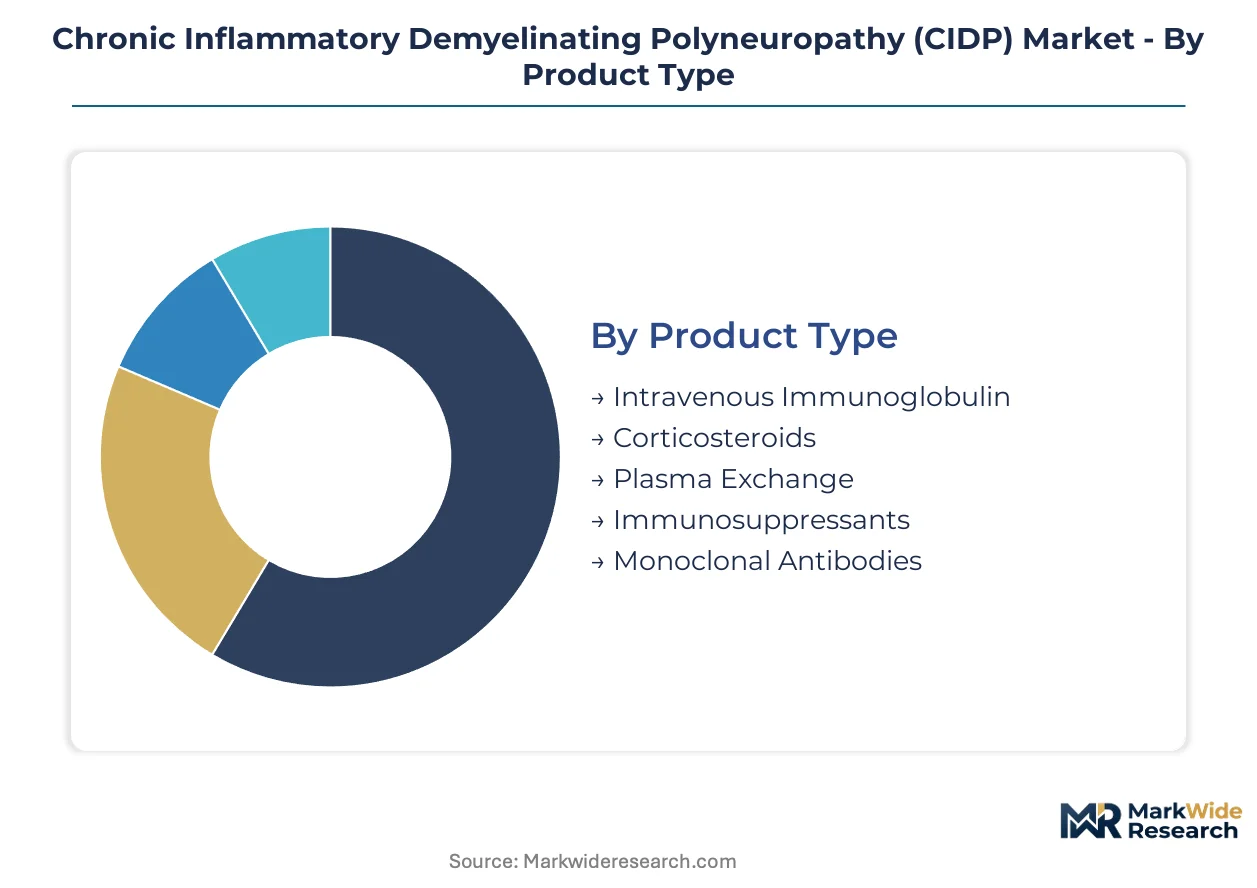
CIDP therapeutics stratify across mechanism of action, care setting, and administration convenience, with substitution dynamics reshaping competitive boundaries between plasma-derived and recombinant modalities. Understanding segment-level pressure points reveals where manufacturers must defend incumbent positions versus attack emerging white space.
Product Type:
Monoclonal antibodies and novel biologics exert mounting substitution pressure on established plasma-derived therapies, threatening incumbent revenue pools through improved dosing intervals and targeted mechanisms.
- Intravenous Immunoglobulin:Polyclonal antibody preparations pooled from thousands of plasma donors deliver broad immunomodulatory effects through Fc receptor saturation and complement modulation. German university hospitals and Japanese tertiary centers anchor demand for high-dose induction regimens, though infusion center capacity constraints limit patient throughput.
- Monoclonal Antibodies:Engineered therapeutics targeting FcRn receptors or complement C1s offer subcutaneous administration and extended dosing intervals compared to immunoglobulin. The FDA's orphan drug designation pathway accelerates development timelines for these agents, drawing venture investment into CIDP-specific programs.
- Corticosteroids:First-line immunosuppressants with established efficacy in acute CIDP flares face long-term tolerability limitations that restrict chronic use.
- Plasma Exchange:Mechanical antibody removal via apheresis serves refractory cases but requires specialized equipment and vascular access that constrain scalability.
- Immunosuppressants:Small-molecule agents including azathioprine and mycophenolate mofetil occupy maintenance niches where immunoglobulin access or cost presents barriers.
Intravenous immunoglobulin retains volume leadership; monoclonal antibodies hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic maintenance regimens, with reimbursement intensity varying across disease chronicity and disability severity.
- Autoimmune Neuropathies:The core CIDP indication commands premium pricing due to chronic administration requirements and irreversible disability risk. German statutory health insurance and Japan's Diagnosis Procedure Combination system sustain reimbursement for prolonged immunomodulatory therapy.
- Peripheral Nerve Disorders:Adjacent conditions including multifocal motor neuropathy and Lewis-Sumner syndrome share electrodiagnostic features with CIDP, creating off-label utilization and payer scrutiny.
- Chronic Neurological Diseases:Long-term management frameworks developed for multiple sclerosis and myasthenia gravis are adapting to CIDP's fluctuating course.
- Inflammatory Disorders:Systemic conditions with peripheral nerve involvement drive diagnostic complexity and treatment heterogeneity.
- Immune-Mediated Conditions:Broad mechanistic category capturing emerging indications where B-cell or complement targeting shows preliminary efficacy.
Autoimmune neuropathies concentrate the majority of commercial investment; peripheral nerve disorders offer the most accessible expansion pathway.
End User:
Patient volume concentrates in settings with electrodiagnostic capability and infusion infrastructure, creating geographic access disparities that shape segment economics.
- Neurology Clinics:Outpatient specialist practices in the United States and Germany are converting intravenous-dependent patients to subcutaneous protocols, reallocating site-of-care economics toward home health channels.
- Specialty Hospitals:Academic medical centers with dedicated neuromuscular units anchor clinical trial enrollment and complex case management for refractory CIDP phenotypes.
- Diagnostic Laboratories:Nerve conduction study and cerebrospinal fluid analysis capabilities determine diagnostic throughput and treatment initiation timelines.
- Rehabilitation Centers:Post-acute facilities manage functional recovery and disability assessment for CIDP patients with residual motor deficits.
- Academic Research Institutes:Investigator-initiated trials and biomarker development programs originate from university-affiliated centers in Japan and France.
Neurology clinics capture the highest patient touchpoint frequency; specialty hospitals command the most complex case referrals.
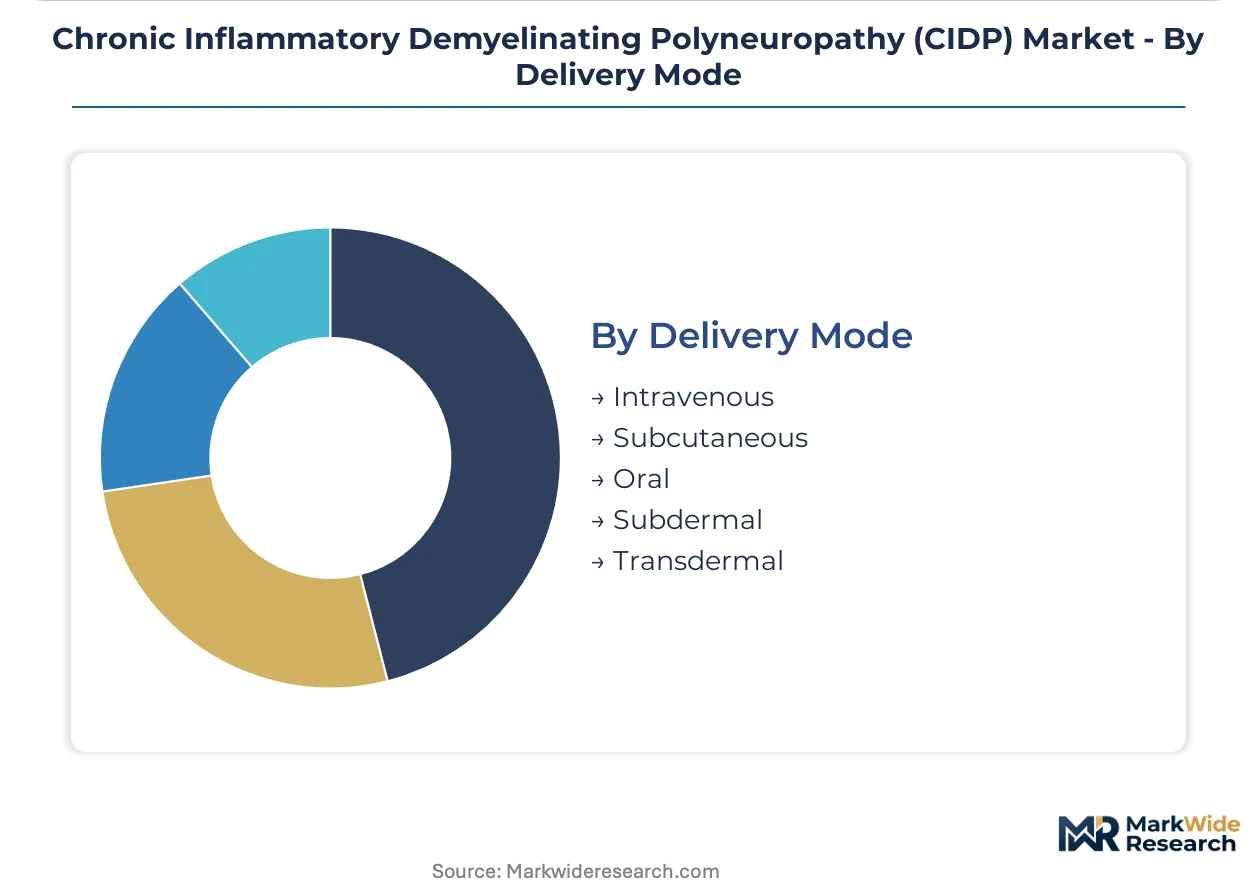
Delivery Mode:
Margin structures diverge sharply between hospital-based infusion services and patient-administered home therapy, with manufacturers racing to capture the subcutaneous transition.
- Subcutaneous:Pump-assisted immunoglobulin delivery enables weekly self-administration without nursing supervision, improving adherence and compressing total cost of care. Neurology clinics in Germany and the United States are accelerating patient conversions from intravenous protocols.
- Intravenous:Hospital and infusion center-based administration remains standard for induction dosing and high-volume immunoglobulin delivery, though site-of-care economics face reimbursement pressure.
- Oral:Small-molecule immunosuppressants offer convenience but limited efficacy in established CIDP, occupying niche maintenance roles.
- Subdermal:Emerging depot formulations promise extended release kinetics with reduced injection frequency.
- Transdermal:Experimental delivery platforms seek to bypass gastrointestinal and injection barriers for peptide-based therapeutics.
Intravenous administration maintains the installed base; subcutaneous delivery is climbing the fastest as home-based protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States sustains premium immunoglobulin reimbursement rates that German statutory health insurers resist, creating a transatlantic divergence in therapy access economics. Japan commands intermediate pricing with accelerated approval premiums under PMDA Sakigake. France and the United Kingdom occupy cost-containment positions where health technology assessment thresholds compress margins.
United States
Commercial payer dominance and Medicare Part B infusion reimbursement sustain the world's highest immunoglobulin pricing levels. FDA orphan drug exclusivity provisions shield novel FcRn antagonists from immediate competition. Boston and New York City anchor the largest neuromuscular specialist clusters, driving rapid adoption of subcutaneous conversion protocols.
Germany
Statutory health insurance density and concentrated university hospital infrastructure generate Europe's highest CIDP treatment penetration. IQWiG quality-adjusted life year thresholds pressure chronic immunoglobulin maintenance pricing. The Rhine-Ruhr and Munich metropolitan regions host the continent's densest neuromuscular pathology referral networks.
Japan
Aging demographics and concentrated tertiary neurology capacity create sustained demand for advanced immunomodulatory therapy. PMDA Sakigake designation accelerates reimbursement for first-in-class biologics entering the CIDP indication. Tokyo and Osaka academic medical centers anchor investigator-initiated trial enrollment for novel mechanisms.
France
HAS health technology assessment applies stringent cost-effectiveness ceilings to chronic immunoglobulin regimens, compressing manufacturer net pricing. ANSM pharmacovigilance requirements shape post-market study obligations for subcutaneous formulations. The Paris-Saclay cluster concentrates neuromuscular research capacity and diagnostic laboratory throughput.
United Kingdom
NICE single technology appraisals subject CIDP biologics to rigorous incremental cost-effectiveness ratios, delaying access for premium-priced entrants. NHS England specialized commissioning frameworks concentrate treatment authorization in designated neuromuscular centers. London and Manchester house the national referral networks for complex peripheral nerve disorder diagnosis.
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with plasma fractionation specialists defending incumbent positions against biotech innovators attacking via novel mechanisms. The market structures around vertically integrated plasma collectors, targeted biologic developers, and diversified pharmaceutical conglomerates. Three archetypes dominate: plasma-dependent incumbents with captive collection networks, FcRn-targeting biotechs with subcutaneous convenience advantages, and diversified majors leveraging neurology franchise infrastructure. Competitive moves concentrate on fractionation capacity expansion and FcRn antagonist clinical trial acceleration.
Among plasma fractionation specialists, CSL Behring and Grifols occupy positions defined by collection network scale and European manufacturing concentration. Within the biotech innovation tier, Argenx represents the FcRn-targeting archetype. Takeda Pharmaceutical and Sanofi sit within diversified pharmaceutical conglomerates seeking neurology portfolio expansion. Baxter International and Octapharma exemplify mid-scale fractionators competing on yield efficiency and regional supply security.
| Leading Market Players |
|---|
| Octapharma |
| Sanofi |
| Grifols |
| Kedrion |
| Pfizer |
| CSL Behring |
| Takeda Pharmaceutical |
| Argenx |
| Baxter International |
| Others |
Value Chain & Pricing Dynamics
FDA orphan drug designation gates both supply qualification and price differentiation in CIDP therapeutics, requiring seven-year exclusivity commitments that manufacturers leverage against standard immunoglobulin pricing tiers while plasma fractionation economics constrain entry.
Pricing Analysis
Configured-to-order pricing for patient-specific immunoglobulin dosing commands substantial premiums over standard per-gram catalog rates. Three-tier pricing structure across premium, standard, and economy levels separates high-concentration subcutaneous formulations from hospital-contracted intravenous volumes and emerging biosimilar entrants. Price differentiation rests on fractionation yield efficiency and cold-chain certification grades. Cost compression in maintenance therapy segments is intensifying because Germany's IQWiG and France's HAS apply stringent quality-adjusted life year ceilings. Medicaid programs and European statutory health insurers exhibit highest price sensitivity; Japanese tertiary centers under PMDA Sakigake demonstrate lowest sensitivity due to accelerated reimbursement premiums.
Supply Chain Analysis
North American plasma collection network concentration creates a chokepoint that exposes European and Asian manufacturers to donor pool access constraints and geopolitical disruption. Raw material supply draws from United States, Germany, and Austria-based collection centers while viral inactivation reagents and specialized fractionation equipment sources from Switzerland and Japan. Single-source vulnerability runs through CSL Behring's vertically integrated collection-to-finished-goods pipeline. Distribution runs through hospital outpatient departments shifting toward home health channels as subcutaneous protocols expand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FcRn-targeting biologics represent a high-growth disruption in CIDP therapeutics, with FDA orphan drug exclusivity provisions creating seven-year competitive moats that justify venture capital allocation against established immunoglobulin incumbents.
For Market Incumbents: Consolidate plasma collection network control through captive donor center expansion in United States metropolitan corridors and backward integration into specialized fractionation equipment manufacturing. Defend against FcRn antagonist substitution by accelerating subcutaneous immunoglobulin pump miniaturization and locking hospital system contracts through integrated site-of-care economics. Prioritize yield efficiency investments at European manufacturing hubs to offset biosimilar price erosion. For New Entrants and Emerging Players: Anchor in Japan's PMDA Sakigake designation pathway to capture accelerated reimbursement for first-in-class FcRn receptor blockers with extended dosing intervals. Target white space in neuromuscular telemonitoring platforms combining wearable grip-strength sensors with decentralized trial endpoints. Pursue parallel scientific advice pre-negotiation with EMA and FDA to align development programs and compress regulatory timelines. For Investors and Strategic Acquirers: FDA orphan drug exclusivity provisions reshape the acquisition landscape by extending revenue protection windows for novel monoclonal antibody platforms. Long-term viability over the next decade hinges on mechanism differentiation and administration convenience rather than plasma-dependent supply security. Target acquisition archetypes: biotechs with validated FcRn pharmacology and subcutaneous delivery technology. Watch for biosimilar immunoglobulin entry signals as inflection indicators for reference product defense spending.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FcRn antagonist Phase III programs in CIDP-specific indications accelerate under FDA orphan drug incentives. |
| Manufacturing Scale-Up | Plasma fractionation capacity expansion in United States and Germany secures immunoglobulin supply security against collection volatility. |
| Regulatory Approval Pathway | PMDA Sakigake designation in Japan unlocks premium reimbursement for novel neurological biologics. |
| Licensing Agreement | Subcutaneous pump technology partnerships enable neurology clinic conversion from intravenous protocols. |
| Pipeline Diversification | Complement pathway inhibition programs reduce dependency on FcRn mechanism concentration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neuromuscular specialists, hospital formulary directors, plasma fractionation executives, payer access specialists, and regulatory affairs leads at biopharmaceutical developers. Secondary validation drew from FDA orphan drug designation filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov protocol registries, and Japanese PMDA Sakigake designation records. Bottom-up patient pool modeling and top-down therapy revenue triangulation anchored market size estimation.
Across the analysis window, the forecasting framework modeled CIDP therapeutics through segmentation dimensions spanning product type, therapy area, end user setting, and delivery mode, with regional regulatory clusters capturing United States, Germany, Japan, France, and United Kingdom-specific reimbursement dynamics. CAGRs were derived from epidemiological progression rates, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated diagnostic latency timelines, subcutaneous conversion velocity, and health technology assessment threshold evolution.
Material uncertainties — biosimilar immunoglobulin entry timing, FcRn antagonist clinical trial outcomes, and plasma collection network disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions about specialist neurologist density expansion and subcutaneous protocol adoption curves. Practitioners should keep alternative scenarios live as health technology assessment body stringency and orphan drug incentive durability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market