
 Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market | 2026-2036
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market Outlook
Outcome-based contracting for cell and gene therapy administration is pivoting how ALCL therapeutics are procured and reimbursed across major markets. Pfizer leverages its hospital system partnerships to secure preferred formulary placement for infused lymphoma agents. Takeda Pharmaceutical Company anchors its position through deep integration with academic medical center networks in North America and Europe. Seattle Genetics differentiates via specialized logistics for temperature-sensitive biologics serving transplant-eligible patient populations.
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics comprise pharmaceutical and biologic interventions targeting CD30-positive systemic lymphoproliferative disorders, with brentuximab vedotin representing the antibody-drug conjugate standard and alectinib addressing ALK-rearranged subtypes through kinase inhibition. These agents function primarily to induce remission in relapsed or refractory cases and consolidate responses following stem cell transplantation. Monoclonal antibodies command the largest current revenue pool given established infusion infrastructure and payer familiarity, while immunotherapy segments attract the fastest development velocity as CAR-T constructs and bispecific platforms advance through registrational trials. Intravenous administration dominates hospital throughput, though subcutaneous formulations are gaining formulary interest where outpatient capacity constraints limit chair time.
FDA orphan drug designation and EMA PRIME eligibility criteria shape clinical development priorities and market access timelines for ALCL innovators, with both agencies demanding robust biomarker stratification in registrational protocols. Health Canada and Japan's PMDA maintain aligned but distinct review standards that manufacturers must navigate for simultaneous multi-regional filings. Stakeholders should monitor evolving CD30 expression assay standardization and companion diagnostic co-development requirements as gatekeepers to differentiated reimbursement.
Market Dynamics
CD30-directed antibody-drug conjugate standardization is compressing clinical trial design timelines and reshaping how biopharmaceutical developers allocate R&D capital across the ALCL pipeline.
Growth Catalysts
- FDA Accelerated Approval Pathway:The streamlined review mechanism for rare hematologic malignancies enables earlier market entry for ALK inhibitors and bispecific constructs, reducing development-to-commercialization lag.
- Academic Medical Center Networks:Concentrated referral pathways in the United States, Germany, and Japan aggregate sufficient patient volumes to support adaptive trial designs and real-world evidence generation.
- Companion Diagnostic Co-Development:Standardized CD30 expression assays are integrating into registrational protocols, creating biomarker-defined prescriber confidence and streamlined payer evaluation.
Market Restraints
- Cold Chain Logistics Concentration:Temperature-sensitive biologics for transplant-eligible populations depend on a narrow base of specialized logistics providers, creating single-point vulnerability in distribution.
- Stem Cell Transplant Capacity:Consolidation of transplant centers in major metropolitan hubs limits patient access to consolidation therapy, constraining addressable volume for curative-intent regimens.
- EMA PRIME Eligibility Thresholds:Stringent biomarker stratification requirements for priority medicines status elevate clinical development costs for smaller innovators without established diagnostic partnerships.
Strategic Opportunities
- Subcutaneous Formulation Development:Outpatient capacity constraints in United States hospital systems are creating formulary interest for self-administered alternatives to intravenous infusion.
- CAR-T Construct Advancement:Autologous cell therapy platforms targeting CD30-positive relapsed disease represent registrational trial white space with limited established competition.
- Japan PMDA Sakigake Designation:The pioneer review framework offers expedited consultation and priority review for ALCL-directed innovations, compressing regulatory timelines for first-in-class entrants.
Industry Challenges
- Cell Therapy Manufacturing Scale-Up:Viral vector production and apheresis scheduling complexity constrain batch yield predictability for autologous treatments.
- Cross-Border Diagnostic Harmonization:Divergent CD30 assay validation standards between FDA and EMA create protocol amendment burdens for simultaneous multi-regional filings.
- Specialized Infusion Nursing Shortage:Competency requirements for biologic administration and adverse event management limit hospital throughput expansion for complex lymphoma protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market |
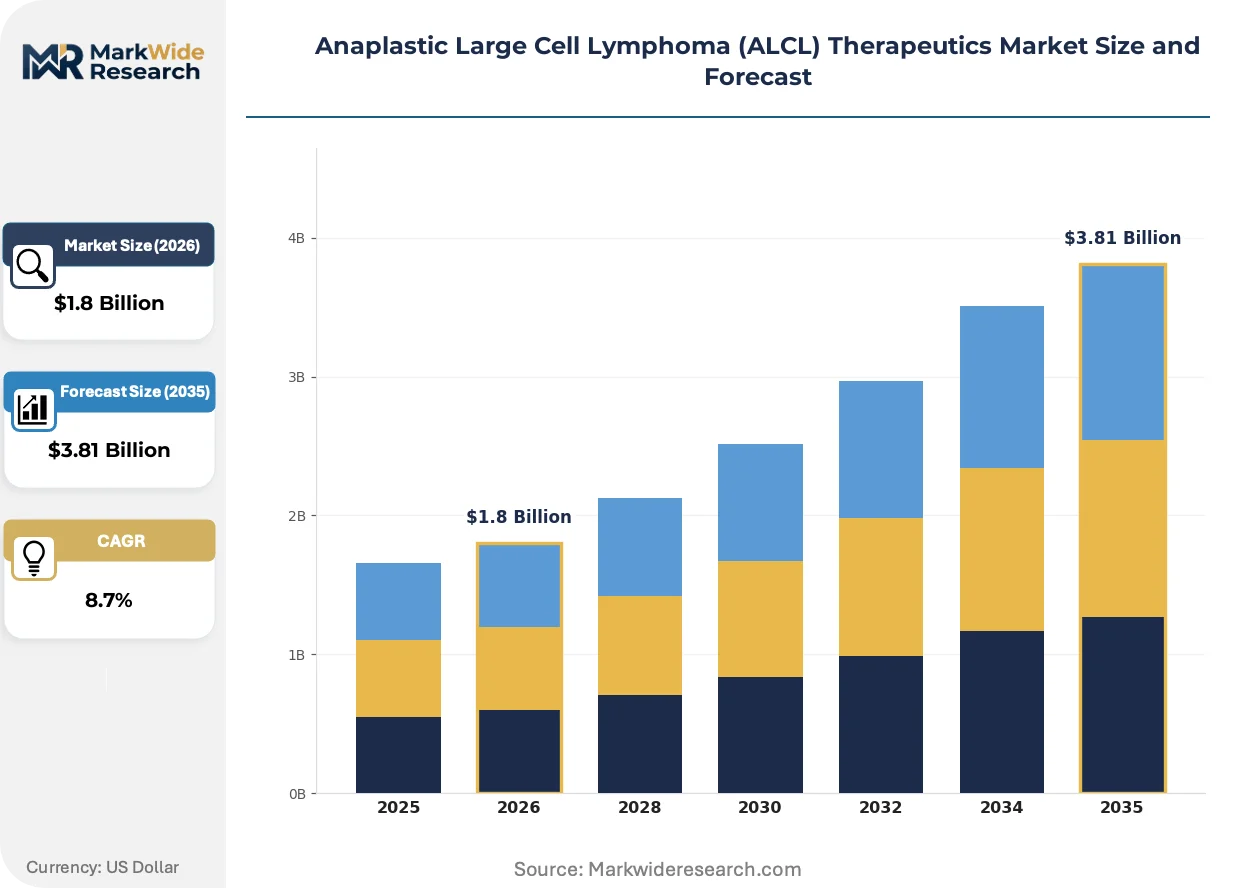
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Immunotherapy, Targeted Therapy End User: Hospitals, Clinics, Research Institutes, Homecare Settings Treatment Stage: First-Line Treatment, Second-Line Treatment, Maintenance Therapy, Palliative Care Route of Administration: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Seattle Genetics, Akron Molecules, AstraZeneca, Pfizer, Takeda Pharmaceutical Company, Teva Pharmaceutical Industries, Sareum Holdings, Bayer AG, Autolus Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market Strategic Shifts
Next-generation sequencing integration and real-world evidence platforms are compressing the feedback loop between clinical observation and protocol adaptation across ALCL development programs.
Bispecific T-cell engager platforms are unifying CD30 targeting with immune checkpoint modulation in single constructs. Academic medical centers in Germany and the United States are advancing these assets through Phase I/II expansion cohorts at accelerated enrollment rates. This convergence is unifying previously separate therapeutic mechanisms, reducing the need for sequential combination protocols and compressing treatment duration expectations.
EMA's PRIME eligibility criteria now mandate robust biomarker stratification in registrational protocols for hematologic malignancies. Manufacturers must demonstrate predefined patient selection algorithms to secure priority medicines status. European sponsors are responding by embedding companion diagnostic development earlier in Phase II, creating parallel regulatory tracks for therapeutic and diagnostic submissions.
Hospital procurement committees are consolidating infused lymphoma agents under outcome-based frameworks that tie reimbursement to measurable response milestones. United States oncology departments are displacing traditional fee-for-service contracts with episode-based arrangements. This restructuring concentrates purchasing authority within integrated delivery networks, favoring suppliers with comprehensive patient support infrastructure.
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market Segmentation
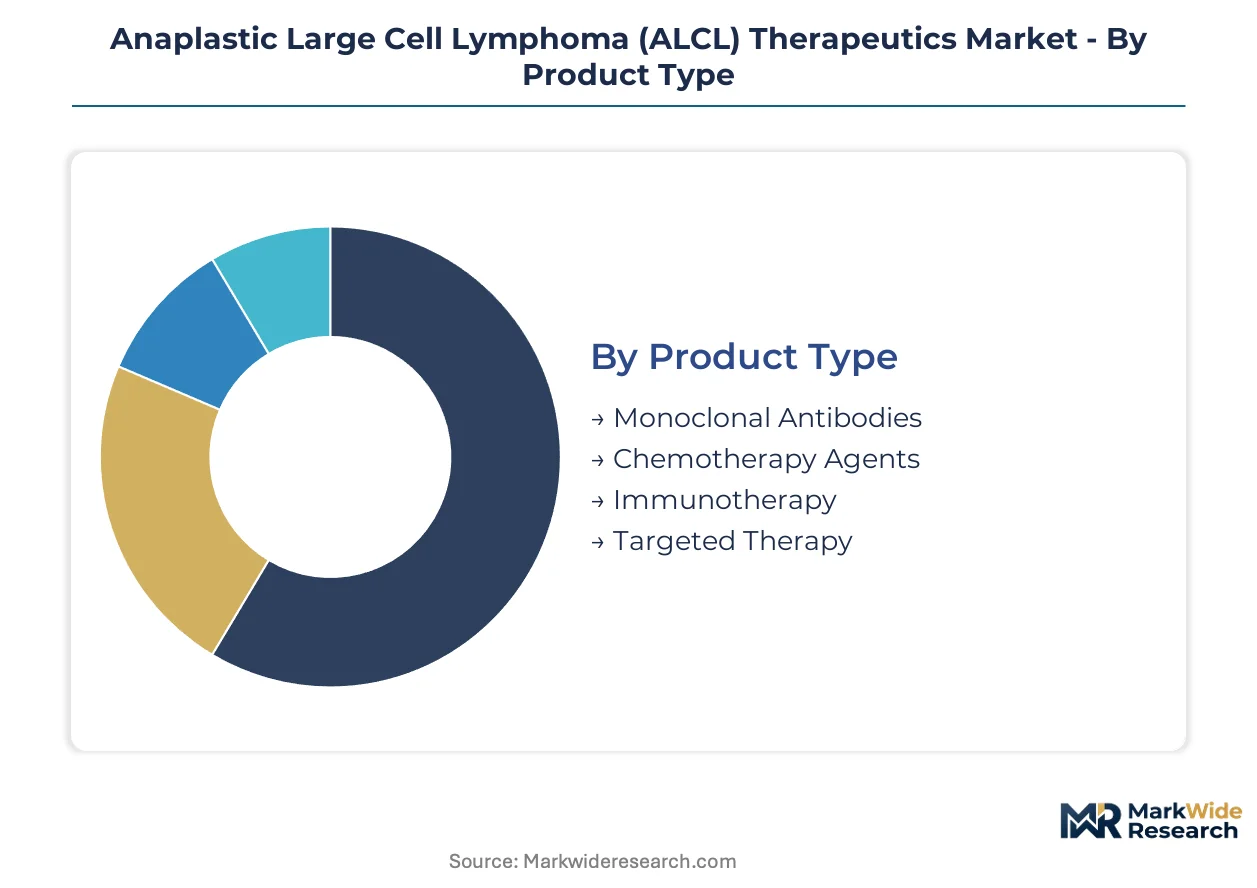
ALCL therapeutics segmentation reflects divergent clinical workflows across academic medical centers and community oncology practices. Treatment stage and administration route determine reimbursement pathways, formulary placement, and patient access corridors in ways that reshape competitive positioning.
Product Type:
Cost tier separates institutional buyers seeking volume contracts from precision oncology programs prioritizing biomarker-driven selection.
- Monoclonal Antibodies:CD30-directed antibody-drug conjugates dominate hospital infusion center throughput. United States academic medical centers concentrate demand for brentuximab vedotin through established oncology pharmacy infrastructure and FDA accelerated approval familiarity.
- Targeted Therapy:ALK inhibitors address molecularly defined subpopulations with oral administration advantages. German referral networks drive adoption of alectinib and brigatinib through centralized pathology review and companion diagnostic integration.
- Immunotherapy:CAR-T constructs and bispecific platforms target relapsed disease with manufacturing complexity.
- Chemotherapy Agents:CHOP backbone regimens retain first-line utility in resource-constrained settings.
Monoclonal antibodies lead volumes today; immunotherapy is gaining share fastest.
End User:
Patient acuity and transplant eligibility determine whether care concentrates at tertiary centers or disperses to community sites.
- Hospitals:Stem cell transplant-capable institutions consolidate curative-intent therapy. Japan's designated cancer centers aggregate sufficient ALCL volume to support adaptive trial enrollment and real-world evidence generation.
- Research Institutes:Phase I/II expansion cohorts for novel constructs depend on academic medical center infrastructure. United States NCI-designated cancer centers anchor investigator-initiated studies for bispecific T-cell engagers.
- Clinics:Community oncology practices manage stable maintenance therapy.
- Homecare Settings:Subcutaneous formulation interest is expanding outpatient capacity.
Hospitals capture the largest patient share; research institutes are expanding their therapeutic role most rapidly.
Treatment Stage:
Reimbursement intensity and duration expectations vary sharply between curative-intent and salvage protocols.
- Second-Line Treatment:Relapsed or refractory disease commands premium pricing for approved agents. FDA breakthrough therapy designation pathways compress development timelines for constructs targeting this population.
- First-Line Treatment:Frontline CHOP-based regimens establish standard-of-care benchmarks. EMA marketing authorization requirements for combination approvals shape how sponsors design registrational trials against this comparator.
- Maintenance Therapy:Consolidation approaches post-transplant vary by center volume.
- Palliative Care:Symptom-directed protocols prioritize quality-of-life endpoints.
Second-line treatment absorbs the highest per-patient investment; first-line protocols are broadening access most substantially.
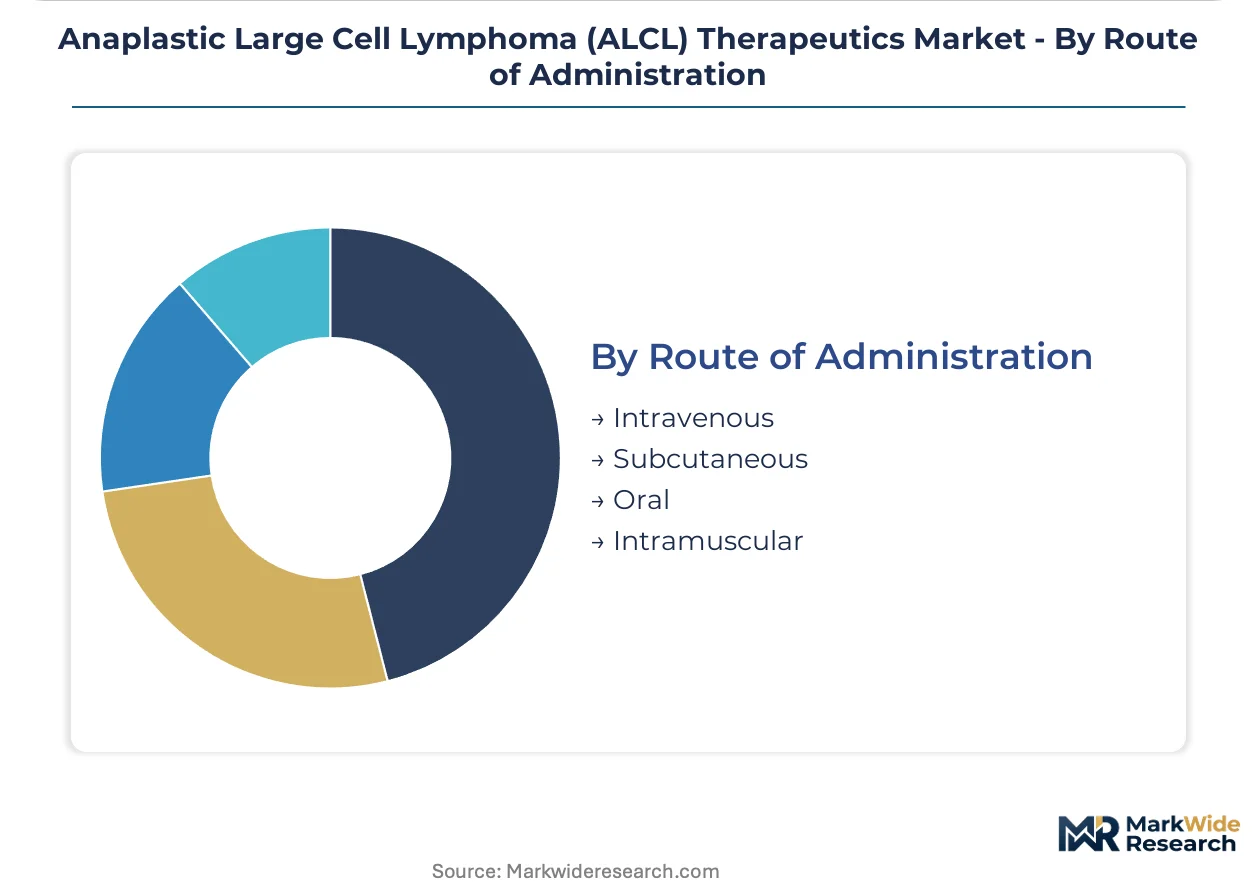
Route of Administration:
Chair time constraints and nursing competency requirements reshape formulary preferences across delivery settings.
- Intravenous:Infusion-dependent biologics require specialized pharmacy infrastructure and adverse event monitoring. Hospital-based oncology departments in Germany and the United States maintain competency certification programs for CD30-directed therapy administration.
- Subcutaneous:Self-administered alternatives reduce outpatient burden. United States integrated delivery networks are evaluating formulary placement for subcutaneous formulations where capacity constraints limit intravenous expansion.
- Oral:ALK inhibitors enable outpatient management of molecularly selected patients.
- Intramuscular:Limited current application in ALCL protocols.
Intravenous administration dominates current throughput; subcutaneous delivery is climbing the fastest as capacity pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States referral networks concentrate more ALCL-directed therapy volume than German academic medical centers, though both markets command premium pricing for CD30-positive lymphoproliferative interventions.
United States
FDA accelerated approval pathways and NCI-designated cancer center density drive therapeutic innovation velocity. The agency's breakthrough therapy designation compresses development timelines for relapsed disease constructs. Boston and Houston transplant hubs anchor adaptive trial enrollment for bispecific T-cell engagers.
Germany
Centralized pathology review networks and companion diagnostic integration standardize biomarker-driven patient selection. EMA PRIME eligibility criteria mandate robust stratification protocols for priority medicines status. Heidelberg and Munich academic clusters coordinate Phase I/II expansion cohorts for next-generation sequencing-guided protocols.
Japan
PMDA Sakigake designation offers expedited consultation for first-in-class ALCL entrants, compressing regulatory timelines against standard review. Designated cancer center aggregation supports real-world evidence generation post-approval. Tokyo and Osaka metropolitan hubs concentrate stem cell transplant capacity for consolidation therapy.
United Kingdom
NHS specialized commissioning frameworks concentrate rare hematologic malignancy care within designated tertiary centers. MHRA alignment with EMA standards streamlines parallel regulatory submissions for multi-regional trials. London and Manchester academic networks anchor investigator-initiated studies for novel immunotherapy platforms.
Switzerland
Swissmedic maintains distinct but harmonized review standards that manufacturers navigate for early European market entry. Basel and Zurich pharmaceutical clusters host translational research infrastructure bridging academic and commercial development. The country's precision medicine initiatives support biomarker co-development partnerships.
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with antibody-drug conjugate developers commanding hospital formulary preference through established infusion infrastructure. The market structure concentrates around large-cap biopharmaceuticals with oncology portfolios and emerging cell therapy platforms. Three archetypes dominate: CD30-directed specialists, ALK inhibitor manufacturers, and autologous cell therapy developers. Competitive moves center on academic medical center network partnerships and companion diagnostic co-development alliances.
Within the large-cap biopharmaceutical tier, Pfizer and Takeda Pharmaceutical Company occupy positions anchored by hospital system integration and transplant center network density. Seattle Genetics exemplifies the CD30-directed specialist archetype through logistics infrastructure for temperature-sensitive biologics. These three entities represent distinct competitive vectors: formulary consolidation, academic partnership depth, and specialized cold chain distribution.
| Leading Market Players |
|---|
| Seattle Genetics |
| Akron Molecules |
| AstraZeneca |
| Pfizer |
| Takeda Pharmaceutical Company |
| Teva Pharmaceutical Industries |
| Sareum Holdings |
| Bayer AG |
| Autolus Therapeutics |
| Others |
Value Chain & Pricing Dynamics
FDA orphan drug sustainability mandates for rare hematologic malignancies gate qualified supply of temperature-sensitive biologics and premium-tier pricing access for transplant-eligible ALCL therapies. EMA PRIME eligibility criteria further stratify reimbursement corridors by biomarker validation standards, compressing price differentiation between certified and non-certified diagnostic partnerships.
Pricing Analysis
Capacity additions in United States hospital systems are reshaping price floors for infused lymphoma agents as integrated delivery networks consolidate purchasing authority under outcome-based contracts. Three-tier pricing structure across premium antibody-drug conjugates, standard ALK inhibitors, and economy chemotherapy backbones dominates procurement negotiations. Price differentiation hinges on companion diagnostic co-development status and cold chain logistics certification. Pricing pressure stems from biosimilar entry timelines in CD30-directed therapy. Community oncology practices exhibit highest price sensitivity; academic medical centers with transplant capacity demonstrate lowest.
Supply Chain Analysis
Specialized infusion nursing shortages in Germany and Japan constrain manufacturing throughput for viral vector production and autologous cell therapy batch scheduling. Supply concentration centers on United States, Switzerland, and Singapore for biologics fill-finish and apheresis kit manufacturing. Raw material dependencies include monoclonal antibody cell lines, linker-payload chemistries for antibody-drug conjugates, and cryopreservation media for CAR-T constructs. Single-source vulnerability in qualified viral vector suppliers represents the dominant structural risk. Distribution runs through hospital-based specialty pharmacy channels with temperature-controlled last-mile logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ALCL therapeutics represent a late-cycle quality story as demand shifts toward biomarker-stratified premium protocols requiring companion diagnostic integration and transplant-center referral density.
For Market Incumbents: Deploy formulary consolidation through outcome-based contracting with integrated delivery networks. Secure preferred status by embedding patient support infrastructure and adverse event management protocols. Threat from bispecific T-cell engager entrants demands accelerated Phase I/II expansion cohort investment. Leverage vertical integration into companion diagnostic development to defend biomarker-gated prescribing. For New Entrants and Emerging Players: CAR-T construct differentiation offers technology-first wedge into relapsed disease white space with limited established competition. Target Japan's PMDA Sakigake designation pathway for expedited regulatory entry. Subcutaneous formulation development in United States outpatient capacity-constrained markets represents the most penetrable segment angle. Pursue academic medical center network partnerships as primary go-to-market channel. For Investors and Strategic Acquirers: Roll-up economics work for CD30-directed specialist platforms because transplant-center network density and cold chain logistics certification create defensible moats. Five-to-ten year viability frames around regulatory exclusivity windows and diagnostic co-development lock-in. Acquisition target archetype: mid-cap biopharmaceuticals with Phase II bispecific assets and established hospital system relationships. Signal to watch: FDA breakthrough therapy designation velocity for relapsed disease constructs.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | EMA PRIME eligibility now mandates biomarker stratification for priority medicines status. |
| Subcutaneous Formulation Advancement | United States integrated delivery networks evaluate self-administered alternatives to address chair time constraints. |
| Academic Medical Center Network Partnership | Germany's Heidelberg and Munich clusters anchor Phase I/II expansion cohorts for novel constructs. |
| Cold Chain Logistics Certification | Temperature-sensitive biologics for transplant-eligible populations require specialized distribution infrastructure. |
| Japan PMDA Sakigake Designation Pursuit | Pioneer review framework compresses regulatory timelines for first-in-class ALCL entrants. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down biopharmaceutical pipeline tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Cross-referencing bottom-up demand estimates with top-down manufacturer capacity disclosures ensures segmentation integrity.
Historical trendline analysis of treatment adoption curves and pricing evolution across administration routes established baseline growth patterns. Segmentation dimensions modeled include treatment line, product type, route of administration, end-user facility type, and regional regulatory cluster. CAGRs derive from slope analysis of volume and value trajectories across the projection horizon. Forecast inputs incorporate biomarker prevalence rates and stem cell transplant center capacity expansion plans.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory approval timelines and manufacturing scale-up success for cell therapy platforms. Forecasts reflect assumptions regarding biomarker assay standardization and payer reimbursement policy continuity. Material deviation in FDA accelerated approval criteria or viral vector supply constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Intraductal Papilloma Market