
 High Speed Rail Coating Market | 2026-2036
High Speed Rail Coating Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Rail Coating Market Foresight
Modular coating system bundling is realigning procurement patterns for high-speed rail operators seeking integrated corrosion and wear protection. Akzo Nobel N.V. leverages its marine and industrial heritage to anchor premium protective coating portfolios for rolling stock applications. PPG Industries, Inc. competes through technology leadership in solvent-based formulations, while Axalta Coating Systems specializes in powder coating platforms that reduce application complexity for track infrastructure projects.
High speed rail coatings comprise engineered polymer and ceramic-based surface treatments applied to steel, aluminum, and concrete substrates to resist abrasion, chemical corrosion, and ultraviolet degradation under sustained operational loads exceeding 300 km/h. These formulations typically incorporate zinc-rich primers, epoxy intermediates, and polyurethane topcoats to achieve service lives of 15-25 years in open-track environments. Protective coatings and epoxy coatings dominate current volume, though polyurethane coatings are capturing margin pools in premium rolling stock refinishing where aesthetic durability and chemical resistance command pricing premiums. Water-based technology is displacing solvent-based systems in European and North American procurement channels as environmental compliance tightens, while powder coating retains cost advantages in high-volume track infrastructure deployments.
The European Chemicals Agency enforces REACH compliance on coating raw materials, restricting hazardous substance content and reshaping supplier qualification requirements for rail OEMs and maintenance providers. China's Ministry of Ecology and Environment applies GB standards on volatile organic compound limits for infrastructure coatings, directly influencing formulation decisions by domestic and foreign manufacturers operating in that market. Japan's METI coordinates industrial standards through JIS specifications that govern coating adhesion and weathering performance for Shinkansen fleet refurbishment cycles. Stakeholders must monitor evolving substance restriction timelines and certification reciprocity agreements to secure long-term supply positions across diverging regulatory jurisdictions.
Market Dynamics
The transition from solvent-based to water-borne coating chemistries constitutes the dominant structural force reshaping competitive positioning, as regulatory pressure on volatile organic compound emissions compresses formulation flexibility while opening premium pricing tiers for compliant suppliers.
Growth Catalysts
- Asia-Pacific track infrastructure investment:China's Ministry of Transport coordinates corridor buildouts exceeding 40,000 route-kilometers, generating sustained procurement volume for protective coating systems applied to rails, sleepers, and electrification structures.
- REACH substance restrictions:The European Chemicals Agency's expanding candidate list of restricted raw materials accelerates reformulation cycles, creating qualification advantages for suppliers with pre-registered alternative chemistries.
- Ceramic nanoparticle reinforcement:Advanced ceramic additives in epoxy intermediates extend service intervals for rolling stock operating above 300 km/h, reducing lifecycle maintenance costs for fleet operators.
Market Restraints
- Zinc feedstock volatility:Zinc-rich primers depend on concentrate supplies concentrated in Australia and Peru, exposing coating manufacturers to London Metal Exchange price swings that compress margin predictability.
- Application equipment lock-in:Solvent-based spray infrastructure at maintenance depots creates technical friction against water-borne system adoption, delaying technology transitions at refurbishment facilities.
- Concrete substrate limitations:Track infrastructure coatings face adhesion failures on weathered concrete surfaces in high-humidity environments, restricting performance guarantees and warranty terms.
Strategic Opportunities
- India's dedicated freight corridors:The Dedicated Freight Corridor Corporation's electrification projects create first-mover positioning for suppliers offering integrated steel and concrete protection systems.
- Digital coating specification platforms:Cloud-based technical documentation and automated compliance verification streamline procurement workflows for multinational rail operators managing multi-country fleets.
- Japan's Shinkansen refurbishment cycles:METI-coordinated JIS specification updates for weathering performance create demand for premium polyurethane topcoats with extended color retention warranties.
Industry Challenges
- Cross-jurisdiction certification complexity:Divergent testing protocols between China's GB standards, Japan's JIS specifications, and EU REACH compliance create documentation burdens that extend supplier qualification timelines.
- Specialized applicator workforce scarcity:Powder coating and ceramic spray application require certified technicians, and training pipeline gaps at maintenance depots constrain deployment velocity for advanced systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Rail Coating Market |
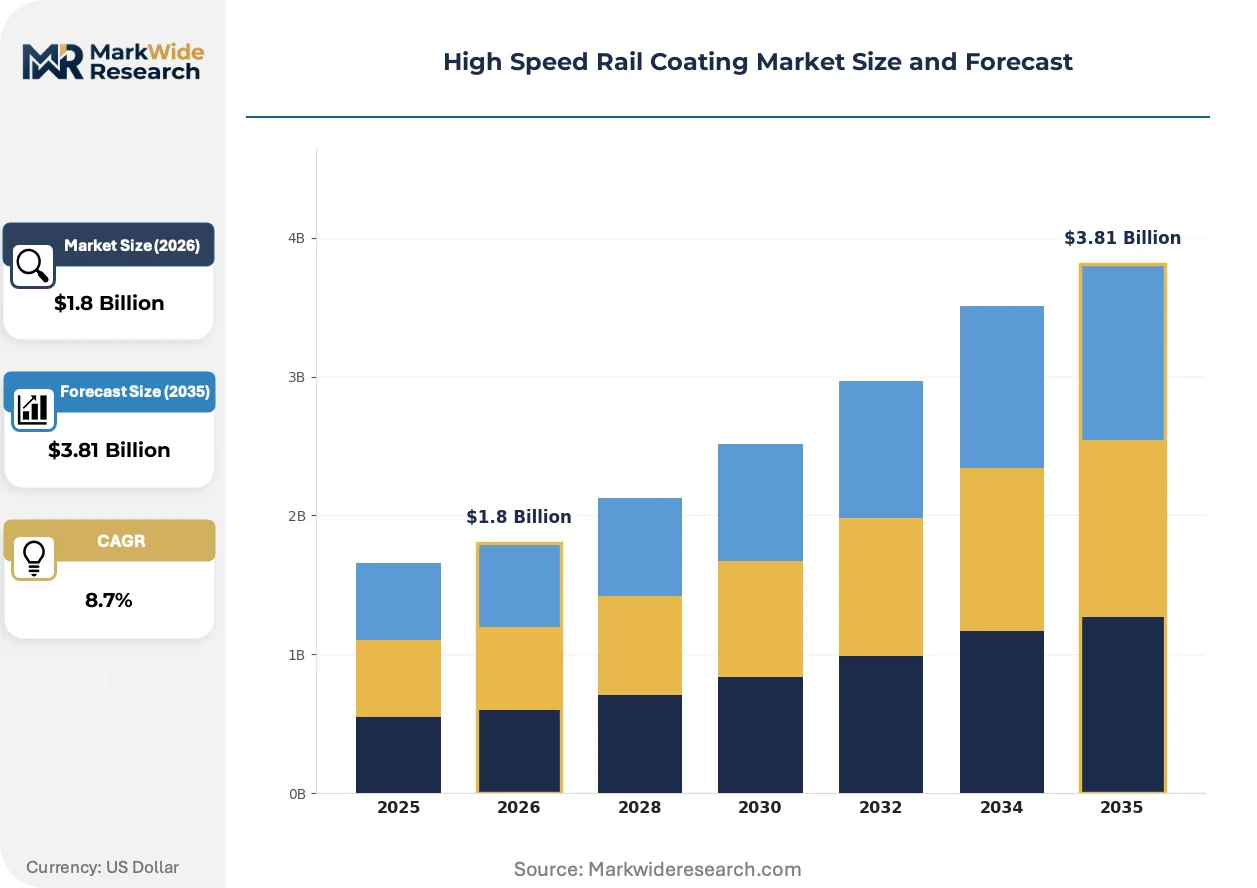
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Coatings, Epoxy Coatings, Polyurethane Coatings, Thermoplastic Coatings Application: Track Infrastructure, Rolling Stock, Bridges, Signal Equipment Technology: Water-Based, Solvent-Based, UV-Cured, Powder Coating End User: Government Agencies, Private Operators, Contractors, Maintenance Providers |
| Companies Covered | Akzo Nobel N.V., BASF SE, PPG Industries, Inc., Axalta Coating Systems, The Sherwin-Williams Company, Nippon Paint Holdings Co. Ltd., Kansai Paint Co. Ltd., GLS Coatings Ltd, PSG Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Rail Coating Market Shifts & Advancements
Coating chemistry convergence with digital quality assurance systems is compressing specification cycles while elevating performance verification standards across procurement channels. Three developments dominate current market evolution.
Self-healing polymer networks are integrating microcapsule-based repair mechanisms that autonomously seal microcracks in polyurethane topcoats exposed to thermal cycling and aerodynamic stress. European rolling stock OEMs are piloting these formulations on premium fleet segments. The technology is integrating predictive maintenance data streams, enabling condition-based recoating schedules rather than calendar-driven interventions.
China's GB 30981 standard on volatile organic compound limits for infrastructure coatings tightens emission thresholds for trackside applications, forcing domestic and foreign manufacturers to accelerate water-borne platform development. The regulation compresses solvent-based volume in coastal provinces first. Suppliers are responding with hybrid formulations that meet MEE enforcement timelines while preserving application efficiency.
Modular service bundling is consolidating specification authority at fewer procurement desks, as rail operators seek single-source accountability for corrosion protection across rolling stock and fixed infrastructure. Integrated coating-plus-inspection contracts displace discrete material purchases. This concentration is most visible in China's state-owned railway groups and Germany's Deutsche Bahn maintenance divisions.
High Speed Rail Coating Market Segmentation
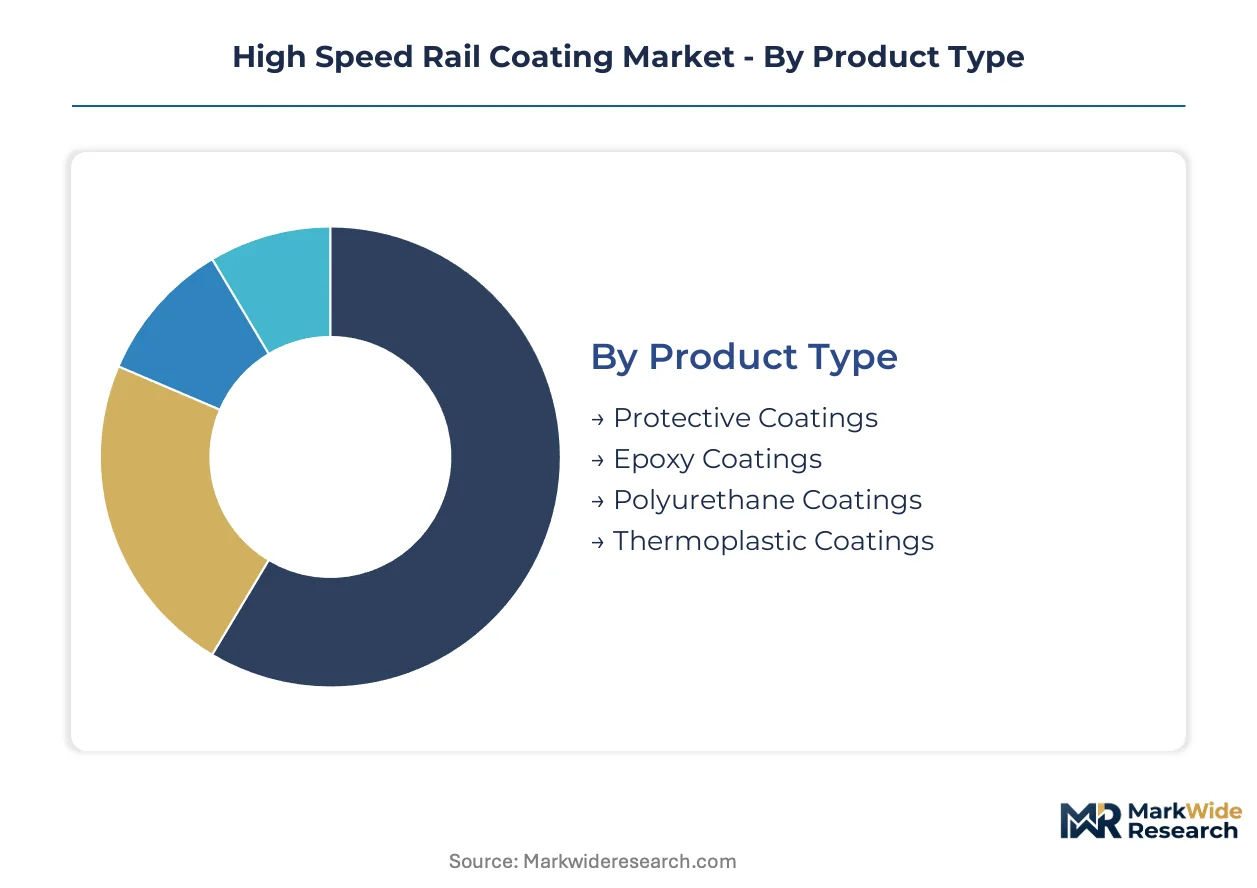
Segmentation in high-speed rail coatings reveals how formulation chemistry, substrate requirements, and procurement authority intersect. Suppliers configure R&D and distribution assets around specific technology-application pairings rather than pursuing horizontal coverage.
Product Type:
Supply concentration in zinc-rich primers and epoxy intermediates anchors procurement relationships with mining-adjacent chemical processors.
- Protective Coatings:Zinc-rich primers dominate volume through sacrificial corrosion protection of steel rails and electrification masts. China's state railway procurement concentrates here for coastal corridor buildouts exposed to salt-laden atmospheres.
- Epoxy Coatings:Ceramic-reinforced intermediates extend service intervals on rolling stock undercarriages facing stone-chip impact at 300+ km/h. Fleet operators in Japan's Shinkansen network specify these for refurbishment cycles.
- Polyurethane Coatings:Premium topcoats deliver color retention and UV stability for passenger-visible surfaces.
- Thermoplastic Coatings:Heat-reactivated systems enable field repair of signal equipment housings.
Today's leader: Protective Coatings. Tomorrow's challenger: Polyurethane Coatings.
Application:
Cost tier separation between track infrastructure volume contracts and rolling stock premium specifications shapes go-to-market economics.
- Track Infrastructure:High-volume steel rail, sleeper, and catenary protection consumes solvent-based and water-borne systems at scale. China's Ministry of Transport corridor buildouts drive procurement concentration here.
- Rolling Stock:Exterior refinishing demands polyurethane topcoats with 15-25 year warranties. European OEMs specify these for premium fleet segments requiring aesthetic durability.
- Bridges:Concrete and steel superstructure protection faces adhesion challenges in humid environments.
- Signal Equipment:Electronics housings require EMI-shielding formulations with weathering resistance.
Infrastructure volume sustains current margins. Rolling stock premiumization offers steepest expansion trajectory.
Technology:
Regulatory enforcement timelines across multiple jurisdictions are compressing solvent-based capacity while elevating water-borne qualification requirements.
- Water-Based:Low-VOC formulations meet tightening MEE and REACH thresholds. European and Chinese procurement channels are shifting specification authority toward compliant suppliers.
- Solvent-Based:Legacy spray infrastructure at maintenance depots creates technical friction against transition. PPG Industries retains technology leadership here as reformulation cycles accelerate.
- UV-Cured:Rapid cure times suit signal equipment and depot-applied components.
- Powder Coating:Zero-VOC application reduces waste for high-volume track infrastructure projects.
Water-Based commands regulatory tailwinds. Powder Coating offers cost advantages in volume deployments.
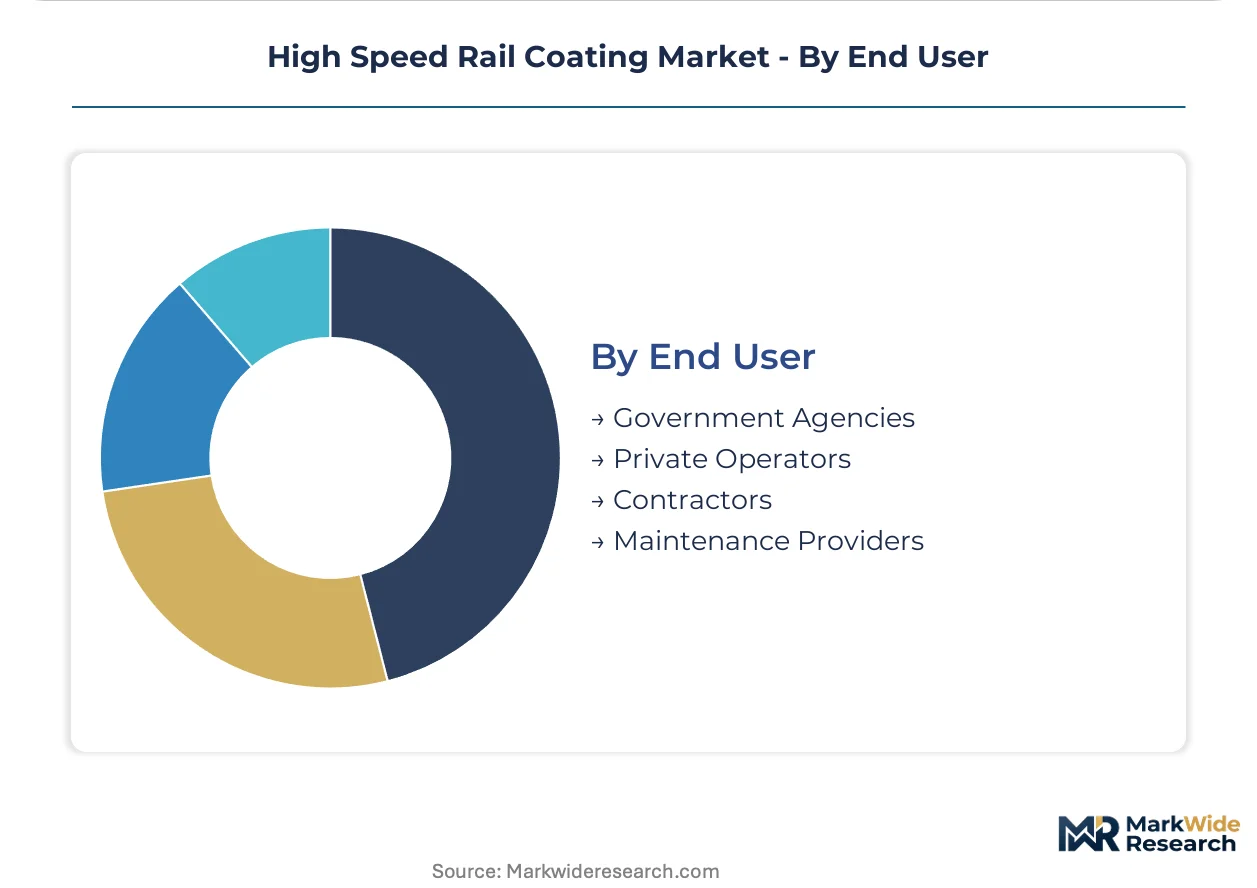
End User:
Procurement authority concentration at government agencies and multinational operators is displacing fragmented contractor purchasing.
- Government Agencies:China's Ministry of Transport and India's Dedicated Freight Corridor Corporation consolidate specification authority for corridor-scale coating procurement. Integrated coating-plus-inspection contracts displace discrete material purchases.
- Private Operators:Deutsche Bahn and Japan Railways specify premium polyurethane systems with extended warranty terms for fleet refurbishment.
- Contractors:Project-based purchasing faces margin compression from consolidated procurement desks.
- Maintenance Providers:Depot-level application requires certified technician pipelines for advanced ceramic and powder systems.
Government Agencies anchor volume concentration. Private Operators drive premium specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-speed rail coating technology originated in Japan's Shinkansen development during the 1960s, then scaled through European corridor modernization and China's explosive network expansion since 2008.
China
Ministry of Transport corridor buildouts exceeding 40,000 route-kilometers sustain procurement volume for protective coating systems applied to rails, sleepers, and catenary structures. MEE enforces GB 30981 VOC limits that compress solvent-based formulation windows. Yangtze River Delta manufacturing clusters near Shanghai host domestic coating production scaling water-borne platform capacity.
Japan
Shinkansen fleet refurbishment cycles generate demand for premium polyurethane topcoats with extended weathering warranties. METI coordinates JIS specification updates governing coating adhesion and color retention performance. Kansai region maintenance depots concentrate ceramic-reinforced epoxy application for undercarriage protection on 300 km/h rolling stock.
Germany
Deutsche Bahn maintenance divisions consolidate specification authority through integrated coating-plus-inspection contracts displacing discrete material purchases. ECHA REACH substance restrictions accelerate reformulation cycles for suppliers serving cross-border fleet operations. Bavaria's industrial corridor anchors powder coating deployment for high-volume track infrastructure projects.
United States
Federal Railroad Administration infrastructure grants support corridor development generating procurement for steel rail protection systems. EPA emission standards influence formulation decisions for maintenance depots in coastal humidity zones. Texas Triangle and Northeast Corridor electrification projects concentrate demand for zinc-rich primer applications.
India
Dedicated Freight Corridor Corporation electrification projects create positioning for suppliers offering integrated steel and concrete protection systems. BIS certification requirements shape qualification timelines for foreign manufacturers entering procurement channels. Gujarat and Maharashtra industrial zones concentrate domestic coating formulation capacity serving western corridor buildouts.
High Speed Rail Coating Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology certification tiers, with compliant water-borne specialists commanding pricing advantages over legacy solvent-based operators. The vendor base organizes into three archetypes: integrated chemical conglomerates with marine-industrial heritage, coating specialists with powder or UV-cured technology platforms, and regional formulators serving domestic procurement channels. Consolidation pressure is intensifying through M&A activity targeting water-borne technology assets and strategic partnerships securing raw material supply positions.
Within the integrated chemical tier, Akzo Nobel N.V. and BASF SE occupy positions leveraging broad industrial coating portfolios, while PPG Industries, Inc. anchors solvent-based technology leadership amid reformulation pressures. Axalta Coating Systems exemplifies the specialist archetype through powder coating platform concentration. These three represent distinct competitive vectors: diversified chemical scale, legacy technology transition, and application-specific efficiency.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| BASF SE |
| PPG Industries, Inc. |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Nippon Paint Holdings Co. Ltd. |
| Kansai Paint Co. Ltd. |
| GLS Coatings Ltd |
| PSG Limited |
| Others |
Supply & Pricing Matrix
China's GB 30981 volatile organic compound emission mandates gate qualified supply access and premium-tier pricing power for compliant water-borne coating suppliers, while locking solvent-based operators into cost-compression cycles at infrastructure procurement desks.
Pricing Analysis
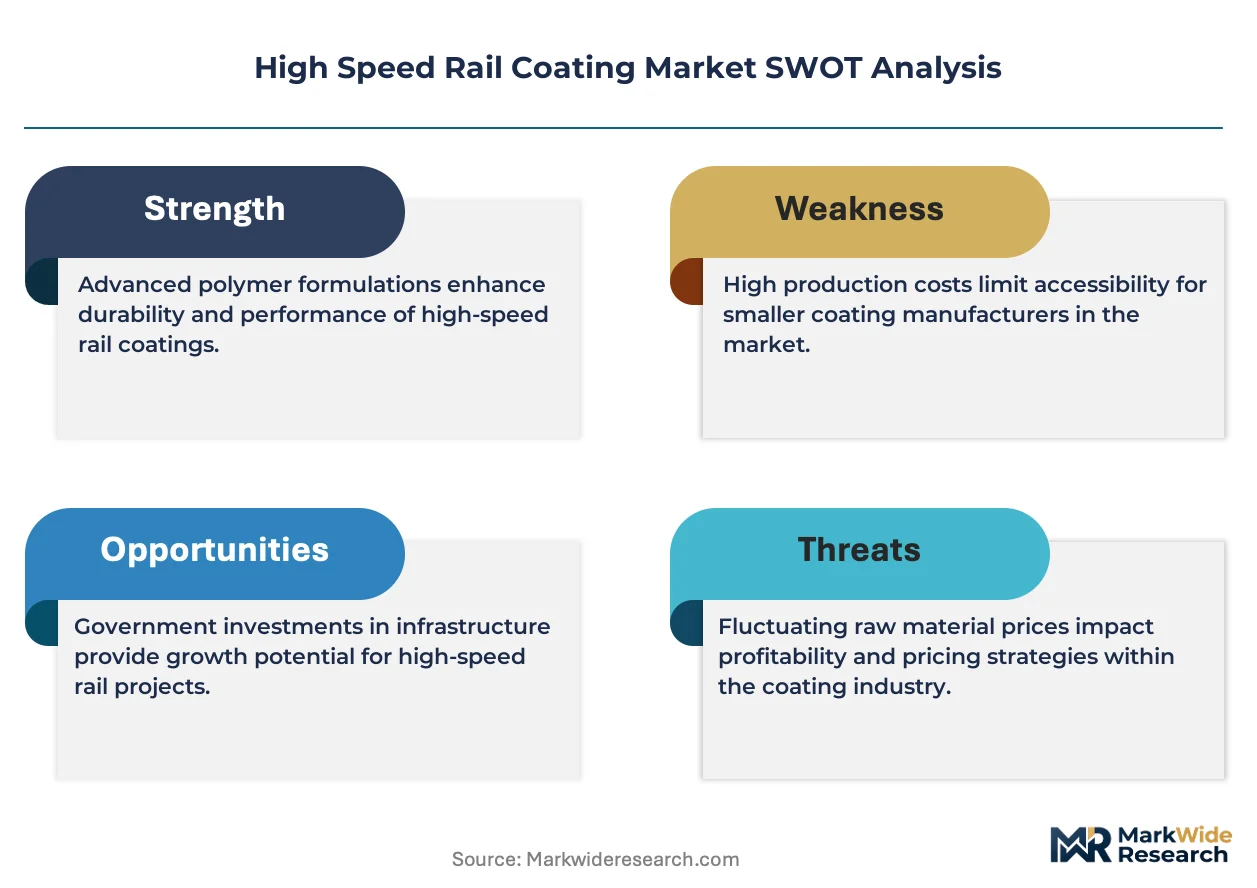
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified water-borne systems from legacy solvent-based formulations and commodity zinc-rich primers. Price differentiation hinges on certification tier and volume scale, with European OEMs paying premiums for JIS-compliant polyurethane topcoats. Pricing pressure stems from zinc feedstock volatility on the London Metal Exchange, compressing margin predictability for primer manufacturers. Government agencies in China and India exhibit lowest price sensitivity through integrated coating-plus-inspection contracts, while maintenance contractors face acute cost compression.
Supply Chain Analysis
Freight costs from Australian and Peruvian zinc concentrate ports to Yangtze River Delta manufacturing clusters feed raw material pricing volatility for sacrificial primer production. Supply concentrates in China, Germany, and Japan, with ceramic nanoparticle additives sourcing from specialized Japanese chemical processors. The chain rests on zinc concentrate, epoxy resin, and polyurethane polymer feedstocks. Single-source vulnerability runs through Australian zinc mining concentration. Distribution runs through state railway procurement desks and Deutsche Bahn maintenance divisions consolidating specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through water-borne technology premiums displacing solvent-based volume, while ceramic-reinforced formulations capture lifecycle cost savings from extended service intervals.
For Market Incumbents: Anchor technology transition momentum by accelerating water-borne platform R&D ahead of MEE enforcement timelines in coastal Chinese provinces. Backward integration into zinc oxide processing mitigates London Metal Exchange price exposure threatening primer margins. Certification investment in JIS specification updates secures Shinkansen refurbishment positioning against emerging Asian competitors. For New Entrants and Emerging Players: Enter via India's Dedicated Freight Corridor Corporation procurement channels, where BIS certification requirements create qualification barriers but first-mover positioning remains available for integrated steel-concrete protection systems. Target signal equipment EMI-shielding formulations as the most penetrable application segment, leveraging UV-cured technology platforms for rapid cure advantages in depot environments. For Investors and Strategic Acquirers: Roll-up economics work for water-borne technology specialists because regulatory enforcement timelines across REACH, GB 30981, and evolving JIS standards consolidate procurement authority at compliant suppliers. Long-term viability favors acquisition targets with pre-registered alternative chemistries and established railway OEM qualification relationships. Watch ceramic nanoparticle patent filings as the inflection indicator for next-generation service interval extension.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Borne Platform Expansion | GB 30981 compliance secures access to China's Ministry of Transport corridor procurement. |
| Ceramic Nanoparticle R&D Partnership | Shinkansen 300 km/h operating loads demand reinforced epoxy intermediates for undercarriage protection. |
| Backward Integration into Zinc Processing | London Metal Exchange volatility threatens primer margins for non-integrated suppliers. |
| Digital Specification Platform Development | Deutsche Bahn's integrated coating-plus-inspection contracts favor cloud-based compliance verification. |
| JIS Certification Investment | METI-coordinated specification updates create premium pricing tiers for qualified polyurethane suppliers. |
Research Methodology
Multiple input streams — primary interviews with coating R&D directors, railway procurement managers, and maintenance depot supervisors; secondary validation through customs trade data, SEC filings from listed chemical conglomerates, and ECHA REACH substance restriction databases — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, substrate application, technology platform, and end-user procurement authority. CAGRs were derived from elasticity-adjusted volume projections incorporating railway infrastructure investment pipelines and fleet refurbishment cycle timing. Industry-specific forecast inputs captured MEE enforcement phase-ins and JIS specification revision schedules.
Inputs from railway operator procurement desks and coating manufacturer technical directors were available through the study window; gaps in depot-level application cost data introduce uncertainty bands around water-borne transition velocity assumptions. Forecasts reflect documented assumptions about regulatory enforcement timing and raw material price trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Digital Railway Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Train Transformer Market
Railway Transportation
Global Autonomous Trains Market