
 Train Transformer Market | 2026-2036
Train Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Train Transformer Market Analysis
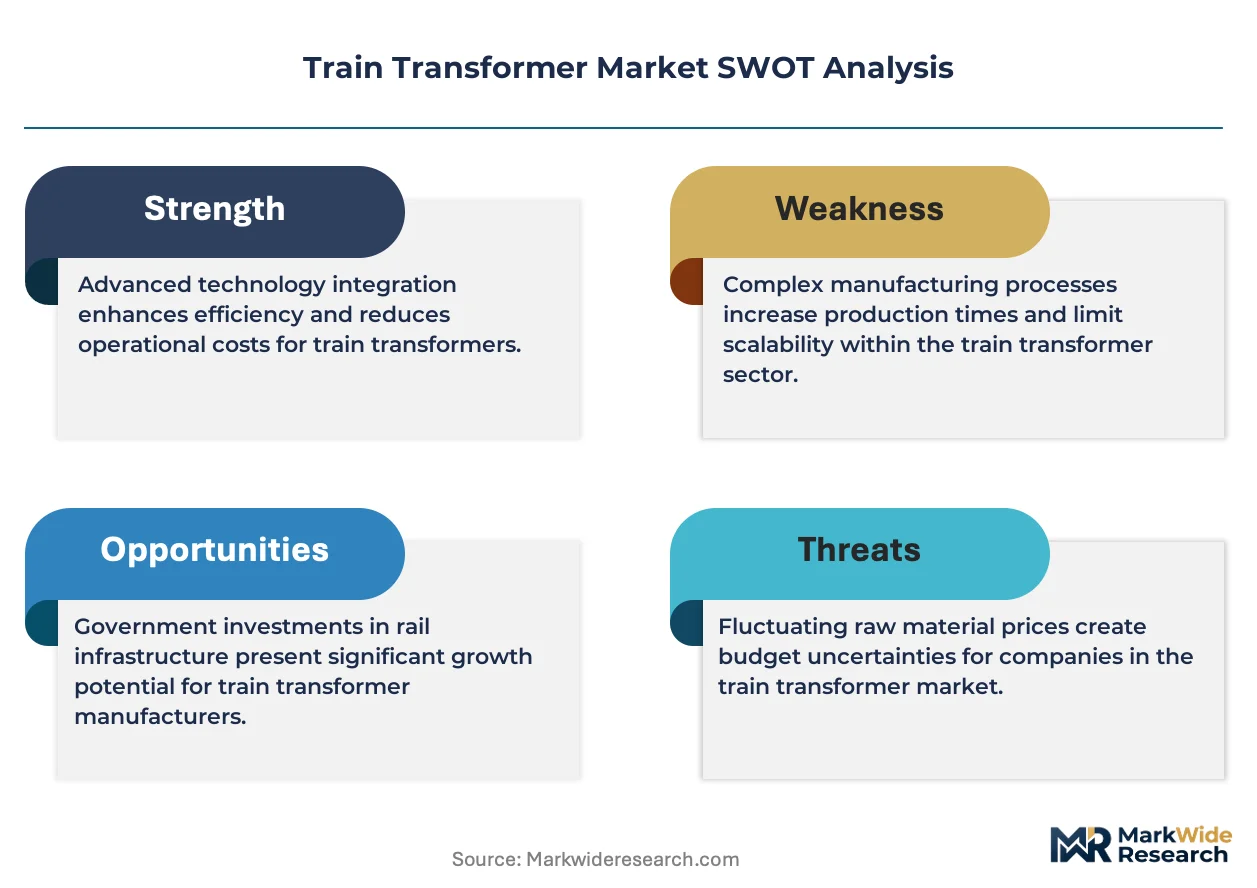
Aftermarket service revenue is rewriting profitability expectations across the train transformer value chain. ABB leverages its installed base across European rail networks to capture recurring maintenance contracts. Siemens anchors its position through digital transformer monitoring systems that reduce downtime for railway operators. Toshiba Energy Systems & Solutions specializes in compact onboard designs for high-speed rail applications in East Asia.
A train transformer is a static electromagnetic device that transfers electrical energy between circuits through inductive coupling, typically operating at 15 kV or 25 kV AC for overhead catenary systems and stepping voltages to levels suitable for traction motors. Its core function is to ensure reliable power conversion for locomotives and multiple units under varying load conditions. Autotransformers dominate installed capacity due to their lighter weight and lower material cost for medium-voltage corridors, while phase-shifting transformers command premium positioning in congested grid interconnections where load flow control matters. Very high power ratings above 20 MVA represent the fastest-expanding category as freight electrification and heavy-haul routes demand greater single-unit capacity.
The EU Green Deal and F-Gas Regulation shape product design by restricting insulating fluids and mandating lifecycle emissions transparency for traction infrastructure. The US Federal Railroad Administration and EPA jointly influence transformer specifications through safety standards and environmental compliance for domestic manufacturing. Stakeholders must monitor how evolving interoperability standards between national rail networks affect transformer procurement specifications and supplier qualification timelines.
Market Dynamics
Freight electrification mandates across Europe and North America are forcing railway operators to replace diesel fleets with electric traction systems, creating sustained demand for high-capacity autotransformers and phase-shifting units that manage grid interconnection loads.
Growth Catalysts
- EU Green Deal decarbonization timelines:The regulation mandates complete diesel phase-out for freight corridors by 2040, compelling operators in Germany, France, and Poland to accelerate transformer procurement for newly electrified routes.
- Silicon carbide traction inverters:This semiconductor technology reduces transformer size and cooling requirements, enabling compact onboard designs that expand application scope for high-speed multiple units.
- Cross-border freight integration:Deutsche Bahn's network modernization and interoperability upgrades with neighboring Czech and Austrian rail systems require standardized 15 kV and 25 kV transformer specifications.
Market Restraints
- Grain-oriented electrical steel supply concentration:Production of this core material concentrates in China and Japan, exposing transformer manufacturers to price volatility and export restriction risks.
- F-Gas Regulation compliance costs:The EU framework restricts sulfur hexafluoride and synthetic ester insulating fluids, forcing reformulation of proven designs and extending qualification timelines.
- Onboard battery-electric hybrid traction:This substitute technology eliminates overhead catenary dependency for low-density routes, reducing addressable transformer demand in rural corridors.
Strategic Opportunities
- India's Dedicated Freight Corridor expansion:The 2,800-kilometer electrified network under construction requires thousands of traction substation transformers, with procurement windows opening through 2028.
- Digital twin predictive maintenance:Convergence of IoT sensors and physics-based modeling enables remote monitoring services that transform one-time equipment sales into recurring revenue streams.
- US Inflation Reduction Act rail incentives:Tax credits for clean freight infrastructure are stimulating electrification projects in California and Texas corridor developments previously dependent on diesel.
Industry Challenges
- Specialized winding technician scarcity:The precision craft required for high-voltage coil assembly faces generational attrition, constraining production scaling for orders above 20 MVA ratings.
- IEC 61373 shock and vibration certification:Railway-specific testing protocols add 12-18 months to product qualification, compressing margin windows against faster industrial transformer alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Transformer Market |
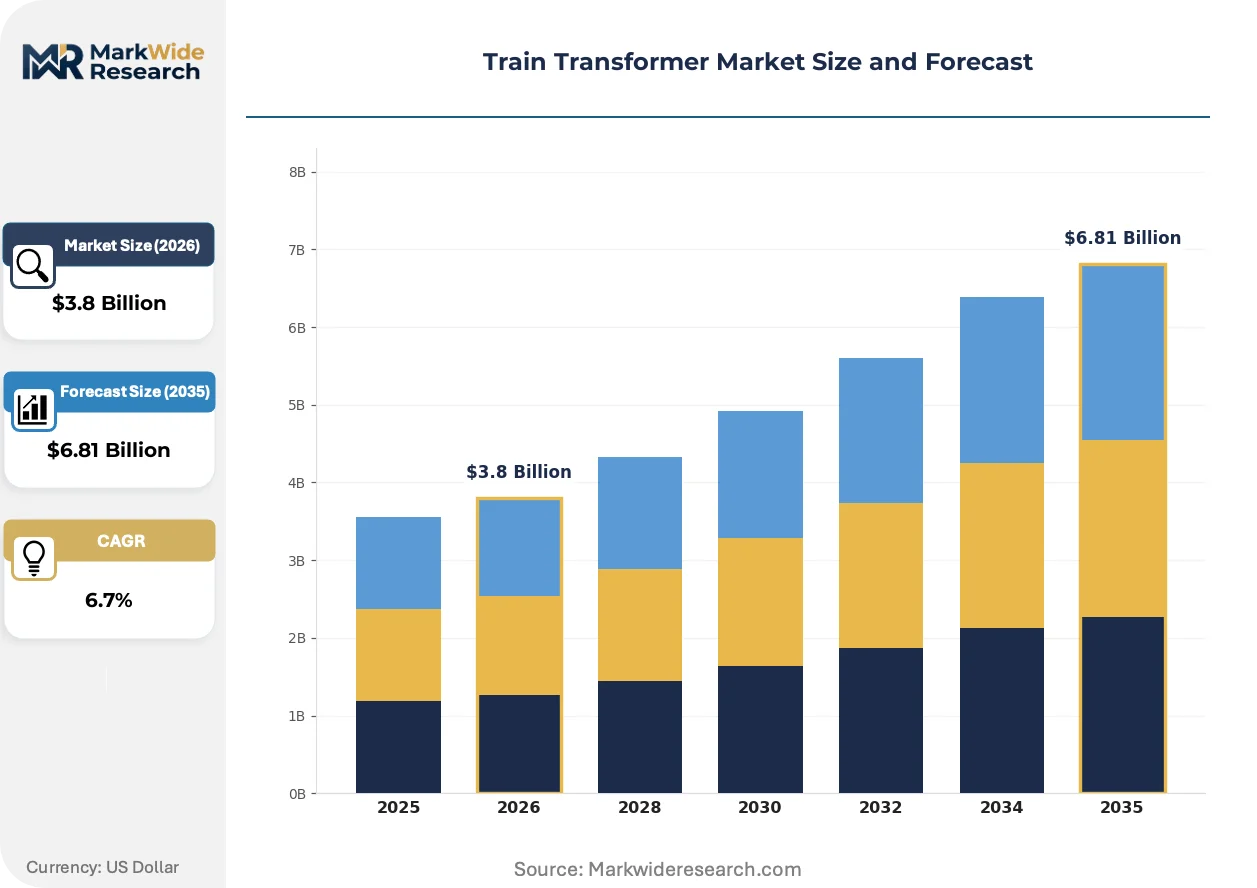
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolation Transformer, Autotransformer, Series Transformer, Phase-Shifting Transformer End User: Railway Operators, Freight Companies, Public Transport Authorities, Private Rail Networks Power Rating: Low Power (<1 MVA), Medium Power (1-5 MVA), High Power (5-20 MVA), Very High Power (>20 MVA) Installation: Onboard, Stationary, Portable, Underfloor |
| Companies Covered | ABB, Siemens, Alstom SA, Hitachi Energy, Mitsubishi Electric, Schneider Electric, Toshiba Energy Systems & Solutions, CRRC Corporation Limited, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Transformer Market Emerging Trajectories
Active cooling architectures and solid-state insulation systems are compressing transformer footprints while elevating thermal performance thresholds. These advances intersect with tightening environmental regulations and evolving procurement expectations.
Amorphous metal core technology replaces conventional silicon steel laminations with thin ribbons of iron-boron-silicon alloys that exhibit near-zero hysteresis loss. European freight operators adopting this material for wayside substations report 30-40% core loss reduction compared to grain-oriented alternatives. The efficiency gain is rendering obsolete traditional core designs in applications where energy recovery justifies premium material costs.
REACH and the EU F-Gas Regulation now classify mineral oil insulating fluids as substances of very high concern, triggering mandatory substitution timelines. Manufacturers are reformulating with natural esters derived from rapeseed and sunflower feedstocks that offer comparable dielectric strength with biodegradability advantages. Traction transformer suppliers serving German and Austrian state railways are accelerating bio-based fluid qualification to maintain eligibility for public procurement frameworks.
Performance-based maintenance contracts are displacing traditional time-interval service agreements as railway operators seek to transfer operational risk to equipment suppliers. Under these arrangements, transformer OEMs guarantee availability metrics and absorb downtime costs, incentivizing predictive analytics investment. This model is most visible in British and Dutch freight corridors where infrastructure managers lack in-house diagnostic expertise.
Train Transformer Market Segmentation
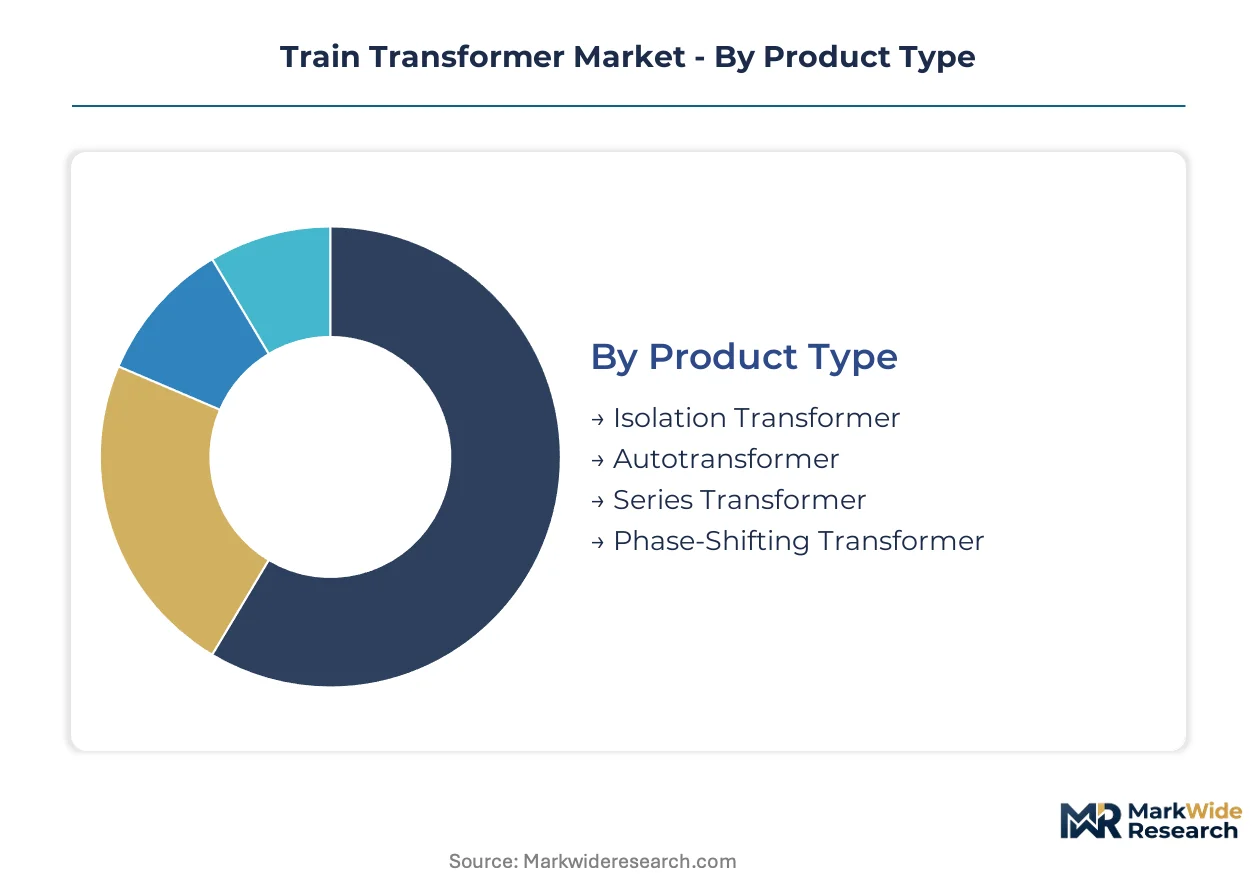
Train transformer procurement diverges sharply across product architectures and deployment contexts. Railway infrastructure planners weight efficiency, footprint, and grid integration differently depending on corridor electrification status and rolling stock specifications.
Product Type:
Mature designs dominate installed base while emerging configurations capture new-build electrification projects.
- Isolation Transformer:Full galvanic separation between primary and secondary windings delivers maximum protection against fault propagation in high-reliability corridors. Deutsche Bahn's 25 kV network modernization in Bavaria specifies these units for critical junction substations where grid stability concerns override cost optimization.
- Autotransformer:Single-winding architecture with tapped intermediate connections reduces copper and core material requirements by 30-50% compared to isolation equivalents. French and Polish freight operators favor these for 15 kV corridor electrification where weight and procurement cost drive selection criteria.
- Series Transformer:Inserted in catenary sections to compensate voltage drop over long feeder distances.
- Phase-Shifting Transformer:Enables active power flow control between interconnected national grids at border crossings.
Autotransformer handles the majority of throughput; Phase-Shifting Transformer is the fastest mover on share.
End User:
Volume concentration tilts toward freight electrification mandates while public procurement frameworks reshape supplier qualification requirements.
- Railway Operators:Integrated infrastructure managers like Deutsche Bahn and Austrian Federal Railways specify transformer fleets for both traction substations and rolling stock refurbishment programs, bundling procurement through multi-year framework agreements that lock in maintenance service tiers.
- Freight Companies:Private operators including DB Cargo and greenfield entrants in Texas and California corridor developments drive demand for high-capacity stationary units as diesel phase-out deadlines approach.
- Public Transport Authorities:Urban and regional networks in Stuttgart, Lyon, and Vienna prioritize compact onboard designs for commuter multiple units.
- Private Rail Networks:Industrial mining and port shuttle operators in Western Australia and South Africa specify ruggedized portable configurations for temporary electrification of heavy-haul spurs.
Railway Operators command the largest procurement volumes; Freight Companies are expanding most quickly as regulatory deadlines compress.
Power Rating:
Unit economics shift dramatically above 5 MVA where specialized winding labor and core material quality requirements escalate.
- Low Power (<1 MVA):Compact units for light-rail and tram applications where space constraints dominate design trade-offs. Czech and Hungarian urban networks specify these for legacy infrastructure retrofitting where tunnel clearances prohibit larger enclosures.
- Medium Power (1-5 MVA):Standard range for regional passenger services and medium-density freight corridors. Austrian Federal Railways standardized on this tier for cross-border routes into Slovakia and Hungary, balancing initial capital outlay against 30-year operational efficiency targets.
- High Power (5-20 MVA):Required for heavy-haul freight and high-speed passenger corridors with continuous high-current demand.
- Very High Power (>20 MVA):Single-unit configurations for dedicated freight corridors and mountain-grade routes where substation spacing must maximize.
Medium Power (1-5 MVA) accounts for the broadest installed base; Very High Power (>20 MVA) is climbing the fastest as corridor electrification intensifies.
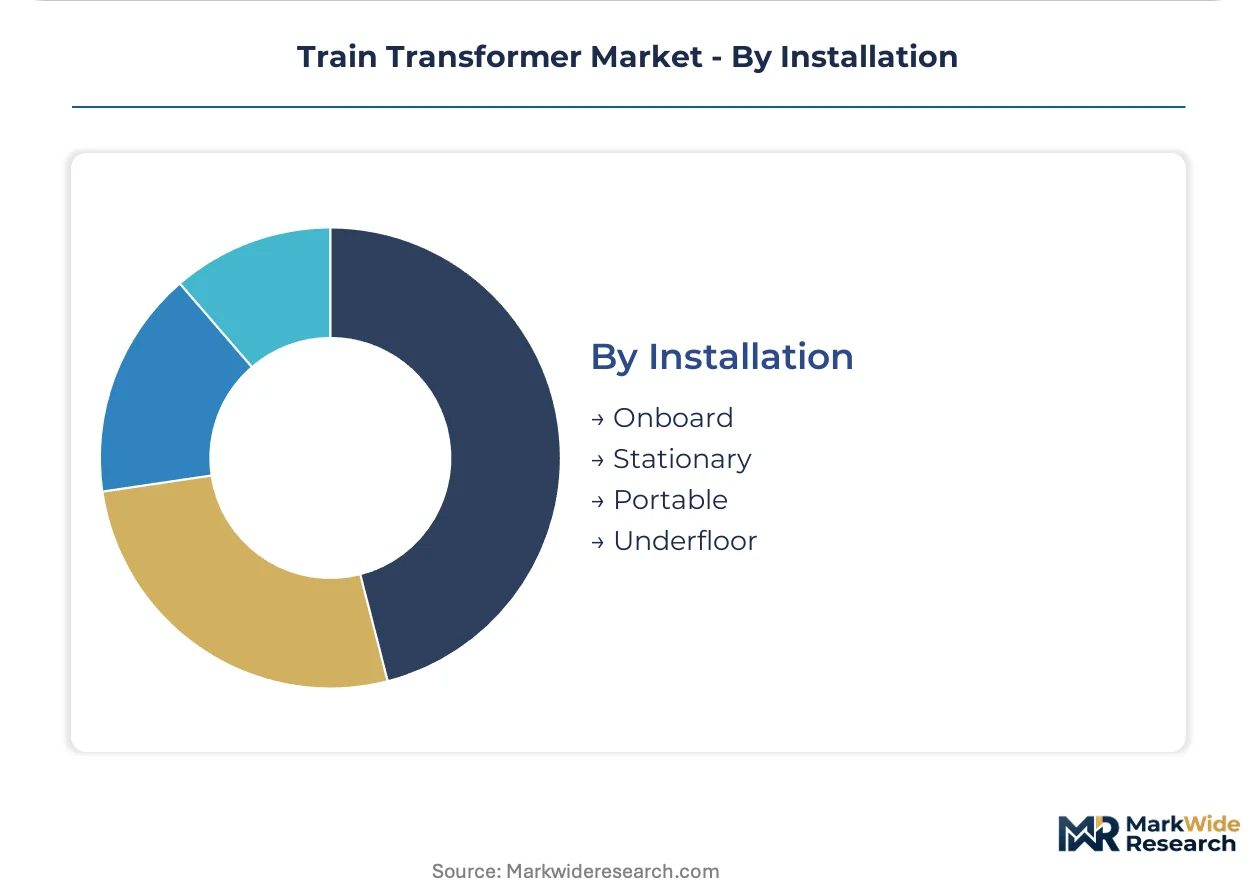
Installation:
Deployment architecture determines thermal management strategy and maintenance access protocols.
- Onboard:Integrated within locomotive or multiple-unit carbody, subject to IEC 61373 shock and vibration certification. Siemens and Alstom specify these for high-speed platforms where catenary voltage must step to traction motor requirements without wayside infrastructure dependency.
- Stationary:Wayside substation installations with active cooling and remote monitoring capability. Indian Dedicated Freight Corridor and German Rastatt base tunnel projects procure these in volume for new-build electrification.
- Portable:Skid-mounted or containerized units for temporary construction power and emergency substitution.
- Underfloor:Space-optimized configurations for low-floor trams and regional trains with restricted roof clearance.
Stationary installations absorb the dominant share of capital expenditure; Underfloor configurations are gaining share fastest as low-floor rolling stock proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Core material fabrication for traction transformers concentrates in East Asian steel mills, while final assembly and system integration cluster near electrified rail corridors in Western Europe and South Asia. Procurement patterns diverge sharply between established networks undergoing modernization and greenfield freight corridors.
Germany
Deutsche Bahn's network modernization and cross-border freight integration with Czech and Austrian systems drive sustained demand for 15 kV and 25 kV transformer specifications. The EU Green Deal mandates complete diesel phase-out for freight corridors by 2040, compressing procurement timelines. Bavaria hosts concentrated substation deployment for the Rastatt base tunnel and adjacent corridor upgrades.
United States
Freight electrification projects in California and Texas corridor developments stimulate demand previously served by diesel locomotives. The US Federal Railroad Administration and EPA jointly influence transformer specifications through safety standards and environmental compliance. Texas rail infrastructure expansion targets heavy-haul routes connecting port facilities to inland distribution centers.
India
The Dedicated Freight Corridor expansion requires thousands of traction substation transformers across 2,800 kilometers of electrified network under construction. The Central Electricity Authority oversees grid interconnection standards for corridor electrification. Procurement concentrates in the Delhi-Mumbai and Ludhiana-Kolkata industrial corridors with installation windows extending through 2028.
Japan
High-speed rail network refurbishment and Shinkansen fleet renewal sustain demand for compact onboard transformer designs. METI efficiency standards and domestic content requirements shape supplier qualification. Osaka and Nagoya manufacturing clusters specialize in precision winding for very high power ratings above 20 MVA.
France
SNCF freight electrification and interoperability upgrades with neighboring Belgian and Italian networks require standardized transformer procurement. The EU F-Gas Regulation restricts insulating fluids, forcing reformulation of proven designs. Lyon and Paris basin infrastructure managers prioritize performance-based maintenance contracts over traditional time-interval agreements.
Train Transformer Market Vendor Landscape
Integrated electrical conglomerates and specialized traction equipment suppliers split the market between turnkey infrastructure solutions and component-level customization. The vendor base organizes around three strategic archetypes: full-service infrastructure providers with digital monitoring capabilities, compact onboard design specialists for high-speed applications, and regional fabricators serving domestic procurement frameworks. Competitive positioning depends on installed base maintenance capture and qualification speed for emerging bio-based insulating fluid formulations.
Within the integrated infrastructure tier, ABB and Siemens exemplify archetypes combining broad electrical portfolios with recurring service revenue models. Toshiba Energy Systems & Solutions occupies a position among compact onboard specialists targeting high-speed rail applications in East Asian markets. These three anchors represent distinct strategic postures: scale-driven maintenance capture, digital monitoring integration, and space-optimized thermal performance respectively.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Alstom SA |
| Hitachi Energy |
| Mitsubishi Electric |
| Schneider Electric |
| Toshiba Energy Systems & Solutions |
| CRRC Corporation Limited |
| GE Vernova |
| Others |
Supply Flow & Price Mechanics
East Asian steel mill clusters in Nippon Steel's Nagoya and Baoshan's Shanghai facilities concentrate grain-oriented electrical steel production, granting core material suppliers substantial leverage over transformer OEM pricing. This geographic concentration feeds directly into procurement cost structures for European and North American rail electrification projects, where freight operators face compressed margin windows on high-MVA units.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across the train transformer market by mandating bio-based insulating fluid reformulation and extending qualification timelines for premium-certified units. Pricing stratifies across premium, standard, and economy tiers based on IEC 61373 shock certification level and after-sales service bundling. Cost compression in standard-tier autotransformers is intensifying because freight companies in Poland and Texas prioritize procurement cost over lifecycle efficiency. Public transport authorities in Stuttgart and Lyon exhibit lowest price sensitivity due to performance-based maintenance contract structures.
Supply Chain Analysis
Export control regimes on advanced electrical steel laminations and silicon carbide semiconductor components limit technology flows from Japan and South Korea to third-country fabricators. Manufacturing draws from China, Japan, and Germany for precision winding equipment and core material processing. Supply chain risk centers on single-source vulnerability for amorphous metal ribbon feedstock. Distribution runs through turnkey infrastructure providers with captive installation and commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The train transformer market functions as a defensive-moat industry where regulatory entrenchment through IEC certification and national procurement frameworks protects qualified incumbents from rapid displacement. Switching costs for railway operators escalate with each installed base unit due to maintenance contract interdependencies and spare parts standardization.
For Market Incumbents: Harden market position through backward integration into grain-oriented electrical steel distribution networks and accelerated bio-based fluid qualification pipelines. Onboard battery-electric hybrid traction from CRRC and emerging Chinese suppliers threatens stationary transformer demand in rural corridors. Capacity addition in India's Gujarat and Maharashtra industrial clusters captures Dedicated Freight Corridor procurement windows. For New Entrants and Emerging Players: Portable transformer configurations for Australian mining spurs and South African port shuttles represent the most penetrable entry point for non-qualified suppliers seeking traction outside EU procurement frameworks. Underfloor designs for low-floor tram retrofits in Czech and Hungarian urban networks offer secondary white-space with reduced certification burden. Direct engagement with private freight operators in Texas bypasses incumbent-dominated public tender processes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized winding houses with IEC 61373 certification and established maintenance contract books over pure-play component suppliers. Long-term viability hinges on digital twin predictive maintenance capability migration from pilot to scaled deployment. The signal to watch is Deutsche Bahn framework agreement renewal timing and bio-based fluid qualification completion rates among second-tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Insulating Fluid Qualification | EU F-Gas Regulation compliance secures eligibility for Deutsche Bahn and SNCF procurement frameworks. |
| Digital Twin Predictive Maintenance Deployment | IoT sensor integration transforms equipment sales into recurring revenue with Austrian Federal Railways. |
| Amorphous Metal Core Manufacturing Scale-Up | 30-40% core loss reduction justifies premium positioning in German freight corridor electrification. |
| Cross-Border Interoperability Certification | Standardized 15 kV and 25 kV specifications unlock Czech-Austrian-German integrated freight networks. |
| Compact Onboard Design Miniaturization | Silicon carbide traction inverter compatibility expands addressable market for Shinkansen fleet renewal. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with railway procurement directors, transformer OEM product managers, and infrastructure planning officers at Deutsche Bahn, SNCF, and Indian Railways; and secondary validation through IEC certification databases, EU TSI compliance registries, and national electrification project disclosures. Customs records for grain-oriented electrical steel trade flows and Central Electricity Authority corridor electrification schedules provided import and deployment volume cross-checks. Bottom-up unit deployment counts and top-down infrastructure investment allocations were triangulated against manufacturer capacity disclosures.
Forecast inputs considered traction substation installation timelines, rolling stock refurbishment cycles, and regulatory mandate enforcement schedules across the projection horizon. Segmentation modeling incorporated product architecture, power rating tier, installation type, and end-user procurement framework. CAGRs were derived from corridor electrification investment trajectories and transformer replacement cycle analysis. Silicon carbide traction inverter adoption curves and bio-based fluid substitution rates provided technology transition inputs.
Practitioners should monitor EU Green Deal diesel phase-out enforcement pace and Indian Dedicated Freight Corridor procurement schedule adherence for early signals of demand trajectory revision. Forecasts reflect documented assumptions regarding grain-oriented electrical steel price stability and IEC 61373 certification timeline consistency. Material shifts in export control regime stringency or amorphous metal core material availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Rail Fasteners Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Digital Railway Market