
 Monorail System Market | 2026-2036
Monorail System Market Size, Share, and Industry Trends Forecast 2026-2036
Monorail System Market Analysis
Buyer concentration among airport authorities and municipal transit agencies is hardening as procurement scales shift toward billion-dollar corridor packages. Alstom leverages its integrated signaling and rolling-stock portfolio to dominate turnkey bids in the Middle East and Southeast Asia. CRRC Corporation Limited anchors cost-competitive manufacturing through captive supply of aluminum car bodies and propulsion assemblies. Hitachi Rail competes on digital maintenance platforms that reduce lifecycle operating expenditure for concession operators.
A monorail system is a guided transit technology running on a single elevated beam or straddle-type guideway, typically employing rubber-tired or steel-wheel bogies with electric propulsion at operating speeds of 80–100 km/h, designed to move passengers through dense urban corridors or closed campuses with minimal ground footprint. Automated people mover installations at airports and mixed-use elevated corridors in resort districts represent the fastest-expanding application pools, while mechanical-grip technology segments face margin compression from electromagnetic and hybrid alternatives. Light rail monorail configurations retain mature demand in Japanese and Chinese urban networks where legacy infrastructure standards persist.
The Federal Transit Administration in the United States enforces Buy America content thresholds for federally funded guideway projects, shaping supplier qualification and domestic sourcing obligations. EMA safety certification and CE marking requirements in Europe restrict market access for non-compliant propulsion and control subsystems. China's NMPA and GB standards for urban rail equipment impose type-testing regimes that foreign entrants must navigate through joint-venture structures. Stakeholders must monitor how evolving national-content rules and cross-border certification reciprocity reshape vendor eligibility before committing to regional manufacturing footprints.
Market Dynamics
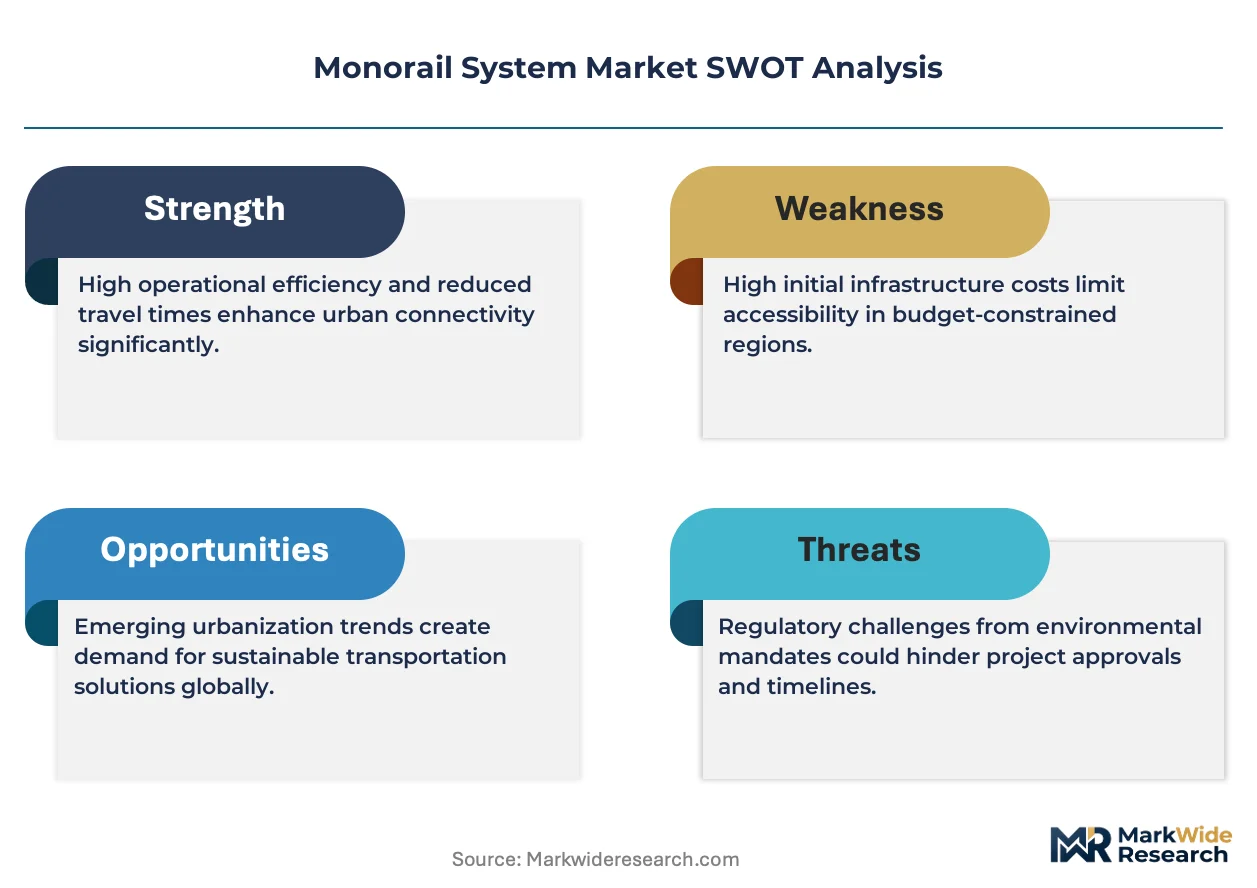
Airport authorities and municipal transit agencies are consolidating procurement into billion-dollar corridor packages, hardening buyer concentration and favoring turnkey suppliers with integrated signaling and rolling-stock capabilities over component vendors.
Growth Catalysts
- Urban emissions mandates:The European Union's tightening urban emissions frameworks and parallel regulations in Asian megacities redirect transit budgets toward elevated electric systems that eliminate ground-level congestion and particulate pollution.
- Greenfield smart-city integration:Saudi Arabia's Neom project and Vietnam's emerging urban corridors embed monorail corridors into master planning from inception, creating captive demand for automated guideway transit.
- Airport APM expansion:Changi Airport, Dubai International, and Delhi's Indira Gandhi International are extending automated people mover networks to decongest apron and terminal access zones.
Market Restraints
- Aluminum input volatility:Car body manufacturing depends on aluminum extrusion supply chains concentrated in Chinese smelter networks, exposing project budgets to commodity price swings and export quota disruptions.
- Guideway construction cost escalation:Elevated concrete beam fabrication and precision alignment require specialized formwork and seismic engineering that inflate capital intensity relative to at-grade alternatives.
- Substitution by light rail:Tram-train and metro extensions in established European and Japanese networks absorb corridor funding that might otherwise flow to monorail installations.
Strategic Opportunities
- Resort and entertainment campus verticals:Integrated resort developers in Macau, Orlando, and Singapore are specifying straddle-type systems for guest circulation between hotel towers and convention facilities.
- Hybrid propulsion convergence:Battery-tethered and wireless power transfer technologies enable guideway segments without continuous conductor rails, reducing infrastructure complexity in heritage-sensitive districts.
- India's urban rail expansion:The Ministry of Housing and Urban Affairs has elevated monorail eligibility in metro-rail project financing, opening corridors in Tier-2 cities lacking heavy-rail legacy infrastructure.
Industry Challenges
- Bogies and propulsion system certification:Type-approval timelines for rubber-tired running gear under China's GB standards and Europe's CE machinery directives extend bid-to-revenue cycles by 18-24 months.
- Legacy transit interoperability:Mixed-traffic corridors requiring interface with existing metro signaling protocols demand custom integration engineering that strains project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monorail System Market |
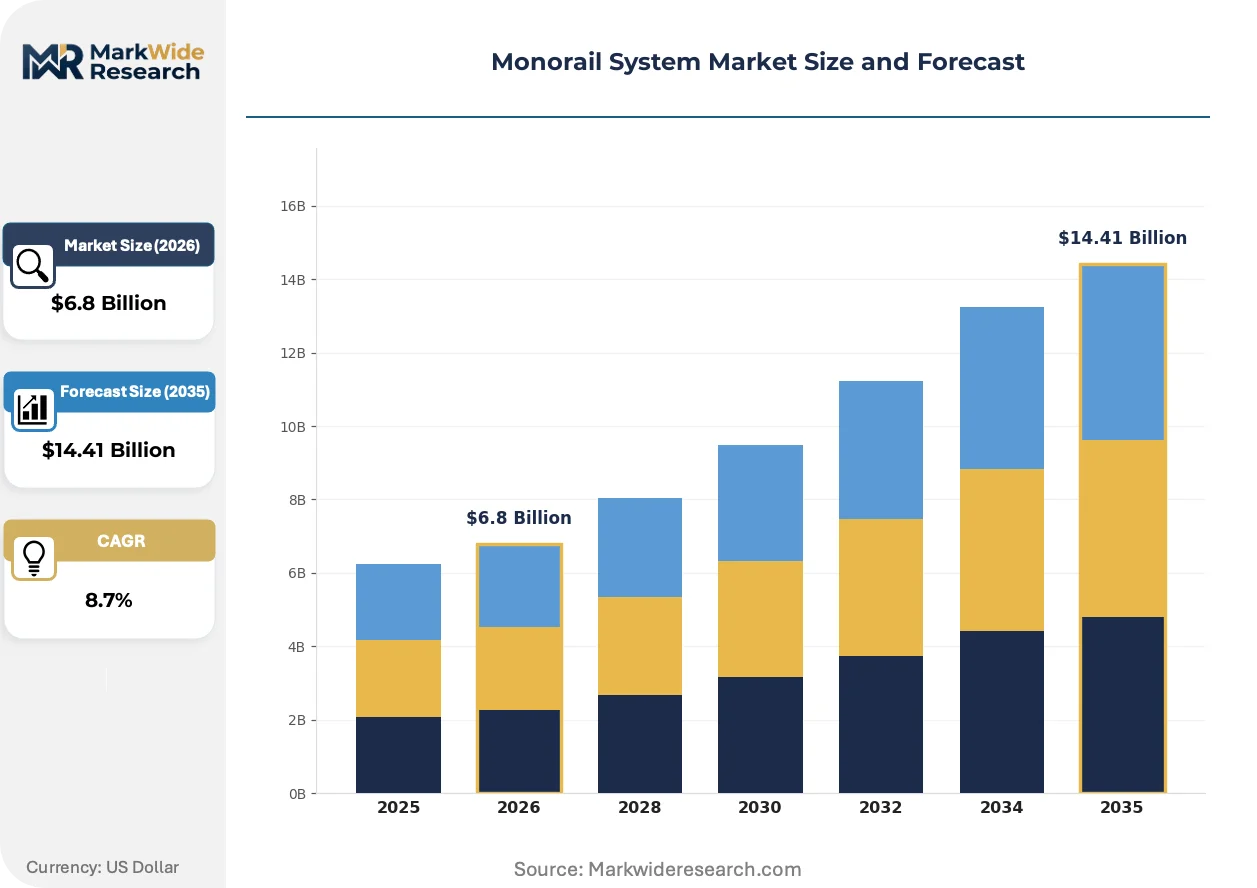
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Monorail, Outdoor Monorail, Automated People Mover, Light Rail Monorail Technology: Electromagnetic, Mechanical, Hybrid, Cable End User: Public Transportation, Airports, Theme Parks, Resorts Installation: Elevated, At-Grade, Underground, Mixed-Use |
| Companies Covered | Alstom, BYD Company Ltd, Bombardier Transportation, Ansaldo STS, Mitsubishi Electric, CRRC Corporation Limited, Siemens AG, Intamin Transportation, Hitachi Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monorail System Market Emerging Trajectories
Digital maintenance platforms and electromagnetic propulsion variants are compressing lifecycle cost structures while automated people mover specifications migrate toward higher-capacity configurations.
Linear induction motor propulsion is integrating permanent-magnet synchronous motor technology to improve energy efficiency and reduce guideway wear. Airport operators in the Middle East and Southeast Asia are specifying these hybrid drive systems for 24-hour continuous operations. The technology is integrating predictive torque control algorithms that cut maintenance intervals by enabling condition-based rather than schedule-based component replacement.
The European Union's F-Gas Regulation and accompanying CE machinery directives are mandating lower-global-warming-potential refrigerants in HVAC subsystems for enclosed guideway environments. Rolling-stock suppliers must redesign climate control architectures to comply with phasedown schedules for hydrofluorocarbons. Asian export manufacturers targeting European concession bids are accelerating refrigerant transition programs to maintain qualification eligibility.
Concession operators are unbundling lifecycle maintenance from initial capital procurement, creating standalone service contracts that favor suppliers with native digital twins and remote diagnostic infrastructure. Turnkey vendors with captive maintenance platforms capture extended revenue streams that pure equipment manufacturers cannot match. This restructuring is most visible in Saudi Arabia and UAE airport authority tenders where 30-year operating concessions dominate procurement design.
Monorail System Market Segmentation
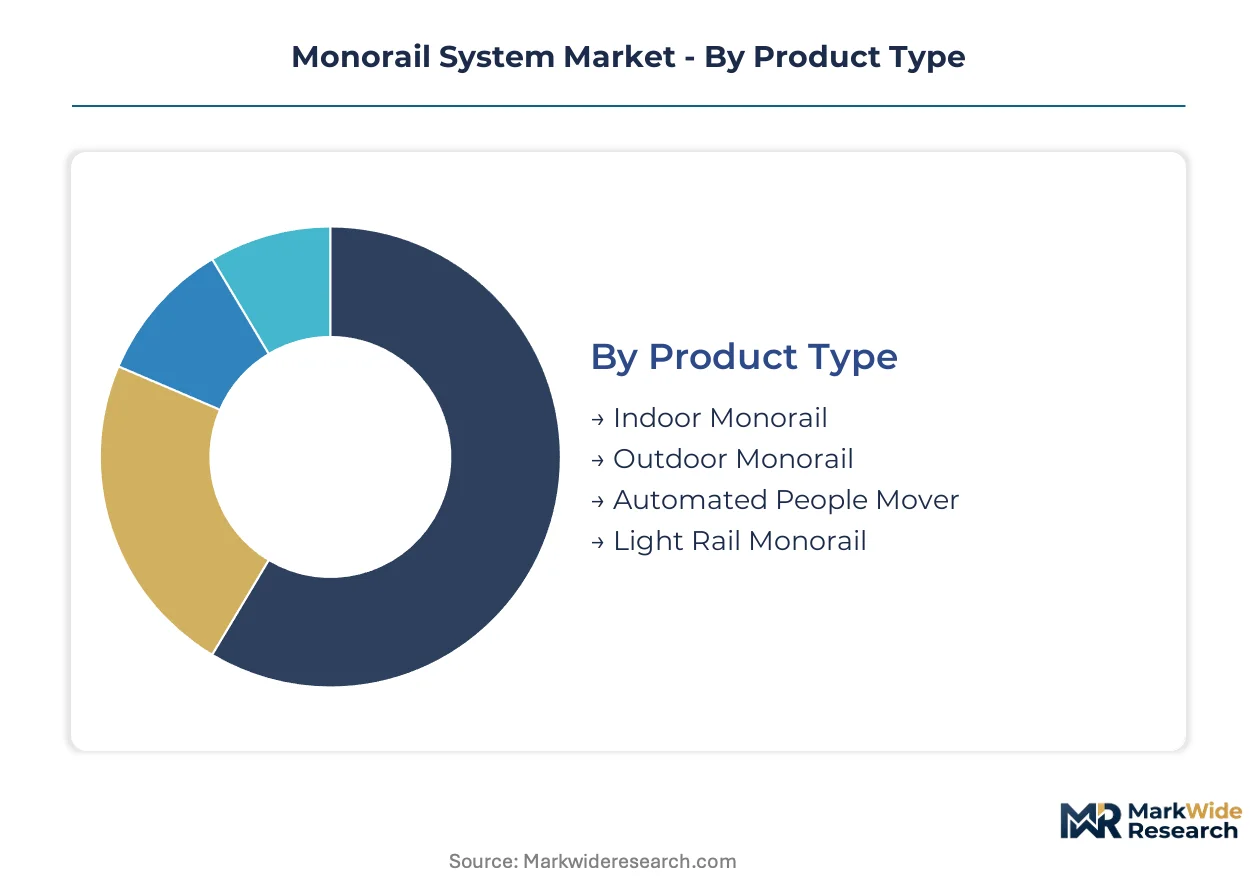
Monorail procurement patterns diverge sharply across installation environments and propulsion architectures. Technology selection and end-use application determine capital intensity, maintenance protocols, and regulatory compliance pathways for corridor developers.
Product Type:
Replacement cycles for aging guideway infrastructure favor systems with modular car-body designs and standardized bogie interfaces.
- Indoor Monorail:Enclosed beam configurations with climate-controlled running gear serve airport terminals and convention centers. Singapore's Changi and Dubai International specify these for passenger circulation between concourses, driven by 24-hour operational reliability requirements.
- Outdoor Monorail:Weather-sealed propulsion and corrosion-resistant aluminum extrusions withstand tropical humidity and coastal salt exposure. Vietnam's emerging urban corridors and Saudi Arabia's Neom project embed these into master planning from inception.
- Automated People Mover:Driverless operation with centralized traffic management reduces labor costs for closed-campus networks.
- Light Rail Monorail:Steel-wheel configurations compatible with legacy Japanese and Chinese infrastructure standards.
Volume placements concentrate in Outdoor Monorail; the faster expansion belongs to Automated People Mover.
Technology:
Cost tiering separates premium electromagnetic systems from mechanical alternatives facing margin compression.
- Electromagnetic:Linear induction motors with permanent-magnet synchronous integration deliver higher energy efficiency and reduced guideway wear. Middle Eastern airport authorities specify these for continuous operations, leveraging predictive torque control algorithms that enable condition-based maintenance.
- Mechanical:Rubber-tired bogies with friction drives dominate legacy installations in Japan and China where infrastructure standards persist unchanged.
- Hybrid:Battery-tethered and wireless power transfer configurations reduce conductor rail complexity in heritage-sensitive districts.
- Cable:Traction rope systems for short-haul resort and entertainment applications with limited extension capability.
Mechanical systems retain installed base dominance; hybrid configurations are climbing the fastest as wireless power matures.
End User:
Customer type determines procurement scale, concession length, and lifecycle service bundling.
- Public Transportation:Municipal transit agencies consolidate billion-dollar corridor packages with 30-year operating concessions. India's Ministry of Housing and Urban Affairs has elevated monorail eligibility in metro-rail project financing for Tier-2 cities.
- Airports:Automated people mover networks at Delhi's Indira Gandhi International and Dubai International extend to decongest apron access zones.
- Theme Parks:Straddle-type systems for guest circulation with themed car-body designs.
- Resorts:Integrated developers in Macau and Orlando specify these for hotel-to-convention connectivity.
Public Transportation commands procurement volume; Airports show the steepest expansion trajectory as APM networks proliferate.
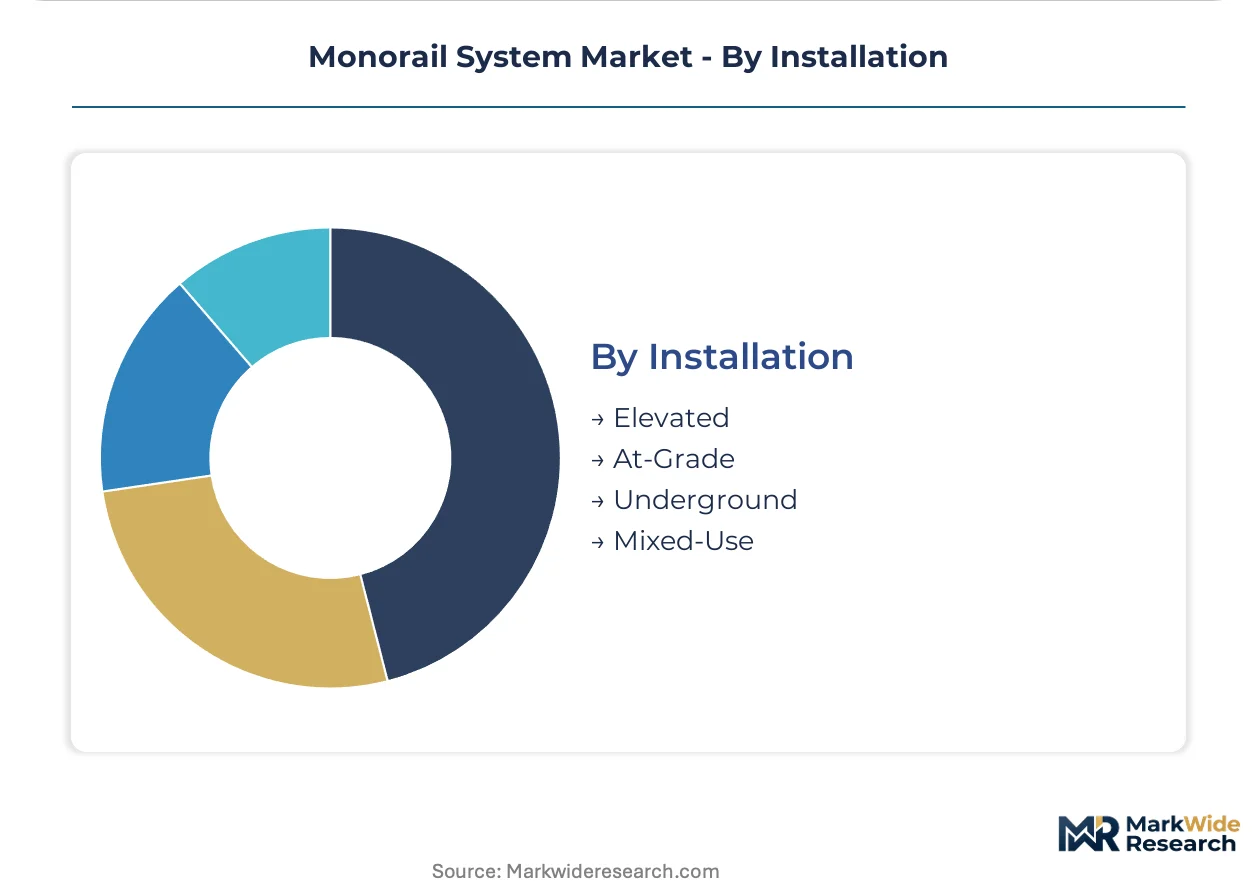
Installation:
Application constraints dictate elevation choice based on land availability, seismic conditions, and visual impact thresholds.
- Elevated:Concrete beam guideways with precision alignment and specialized formwork dominate urban deployments. Stricter emissions mandates in the European Union and Asian megacities redirect budgets toward these ground-footprint-minimal configurations.
- At-Grade:Surface-level installations with grade-separated crossings for resort and campus environments.
- Underground:Tunnel-bored segments for heritage-sensitive city centers with high land values.
- Mixed-Use:Hybrid elevation profiles combining elevated, at-grade, and underground segments within single corridors.
Elevated installations absorb the majority of capital deployment; Mixed-Use configurations are gaining share fastest as corridor designs adapt to varied urban topography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airport authorities in Saudi Arabia, India, and Vietnam are consolidating procurement into billion-dollar corridor packages, redirecting transit budgets toward elevated electric systems that eliminate ground-level congestion and particulate pollution.
Saudi Arabia
NEOM's smart-city master planning embeds monorail corridors from inception, creating captive demand for automated guideway transit. The Saudi national urban rail program prioritizes elevated electric systems under Vision 2030 sustainability targets. Riyadh and the Red Sea coastal zone concentrate greenfield project development.
India
Tier-2 cities lacking heavy-rail legacy infrastructure are elevating monorail eligibility in metro-rail project financing. The Ministry of Housing and Urban Affairs directs transit budgets toward elevated systems under Smart Cities Mission mandates. Maharashtra and Karnataka cluster corridor development in Mumbai, Pune, and Bangalore.
China
GB standards for urban rail equipment impose type-testing regimes that foreign entrants navigate through joint-venture structures. NMPA certification requirements shape propulsion system qualification pathways. The Yangtze River Delta and Pearl River Delta concentrate manufacturing capacity and domestic deployment.
United Arab Emirates
Dubai International Airport extends automated people mover networks to decongest apron access zones. The UAE's federal procurement frameworks favor turnkey suppliers with integrated signaling capabilities. Dubai and Abu Dhabi anchor Gulf region demand concentration.
Vietnam
Emerging urban corridors embed monorail infrastructure into master planning from inception, driven by Ho Chi Minh City and Hanoi metro expansion programs. National transport development strategies prioritize elevated guideway transit for dense corridor penetration. The Red River Delta and Southeast economic region concentrate project pipelines.
Monorail System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid propulsion and digital maintenance platforms. The vendor base organizes around three strategic archetypes: integrated turnkey suppliers with captive signaling portfolios, cost-competitive manufacturers with aluminum supply chain control, and digital service specialists with predictive maintenance infrastructure. Dominant competitive moves include geographic expansion through concession partnerships and backward integration into aluminum extrusion supply.
Among European integrated suppliers, Alstom and Siemens AG exemplify the turnkey archetype with signaling and rolling-stock bundling. Hitachi Rail occupies a position within the digital maintenance tier, anchoring lifecycle service contracts through remote diagnostic platforms. CRRC Corporation Limited represents the manufacturing-scale archetype, leveraging captive supply of aluminum car bodies and propulsion assemblies.
| Leading Market Players |
|---|
| Alstom |
| BYD Company Ltd |
| Bombardier Transportation |
| Ansaldo STS |
| Mitsubishi Electric |
| CRRC Corporation Limited |
| Siemens AG |
| Intamin Transportation |
| Hitachi Rail |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum pricing cascades through monorail supply chains into three-tier cost structures across premium electromagnetic, standard mechanical, and economy cable-hauled configurations. Chinese smelter concentration transmits commodity volatility directly into rolling-stock procurement budgets, while European CE certification tiers add compliance premiums that separate qualified from non-qualified vendor pools.
Pricing Analysis
High-volume mechanical-system corridors in India and Vietnam trade margin for placement, while low-volume electromagnetic installations in Saudi Arabia and UAE airports command premium pricing through 30-year service bundling. Price differentiation rests on GB/CE certification tier and captive aluminum extrusion capability. Cost compression in standard mechanical tiers is intensifying because CRRC's integrated supply chain undercuts component vendors. Municipal transit agencies in Tier-2 Indian cities exhibit highest price sensitivity; Middle Eastern airport authorities with concession financing show least.
Supply Chain Analysis
Regional distribution centers in Shanghai, Düsseldorf, and Dubai anchor hub-and-spoke patterns for propulsion assemblies and signaling subsystems. Manufacturing concentrates in China, Germany, and Japan for aluminum car bodies, linear induction motors, and rubber-tired bogies respectively. Raw material dependencies draw from Chinese aluminum smelters, Japanese permanent-magnet rare earth processing, and German precision electronics. Single-source vulnerability in Chinese aluminum extrusion networks threatens project delivery timelines. Distribution runs through turnkey vendor logistics rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation into billion-dollar corridor packages is squeezing component vendors, positioning integrated turnkey suppliers to absorb weaker players lacking captive signaling or maintenance platforms.
For Market Incumbents: Cement dominance in Saudi Arabia and UAE by anchoring 30-year operating concessions with native digital-twin infrastructure. Deepen backward integration into aluminum extrusion supply to offset Chinese smelter price volatility. Defend against CRRC's cost position through CE/GB certification moats that disqualify non-compliant entrants from European and Chinese tenders.
For New Entrants and Emerging Players: Capture white space in India's Tier-2 monorail corridors where heavy-rail legacy infrastructure is absent and financing eligibility has expanded. Target Vietnam's emerging urban corridors before master planning locks in vendor selections. Enter through hybrid propulsion specialization, offering battery-tethered systems that reduce guideway complexity in heritage-sensitive districts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor digital maintenance specialists with remote diagnostic platforms in European and Middle Eastern markets where concession operators unbundle lifecycle service. Long-term viability over a 5-10 year window hinges on recurring revenue share versus one-time equipment margins. Monitor Saudi Arabia's NEOM procurement waves as inflection indicator for turnkey vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of car bodies insulates CRRC and Alstom from Chinese smelter price volatility. |
| Digital Maintenance Platform Deployment | Hitachi Rail's remote diagnostic infrastructure captures 30-year UAE and Saudi concession revenue. |
| Hybrid Propulsion Development | Battery-tethered systems enable wireless segments in Macau and Orlando heritage-sensitive districts. |
| CE/GB Certification Investment | EMA machinery directives and China's type-testing regimes erect qualification barriers against unqualified entrants. |
| Turnkey Concession Partnership | Integrated signaling-rolling-stock bundling dominates Saudi NEOM and Indian Smart Cities Mission tenders. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this monorail system analysis. Primary interviews with transit agency procurement directors, airport authority engineering leads, rolling-stock plant managers, and concession operator maintenance heads combined with bottom-up corridor pipeline tracking and top-down macroeconomic triangulation. Secondary sources included Federal Transit Administration Buy America compliance databases, EMA safety certification registries, China's NMPA type-approval records, and UNIFE European rail supply statistics.
Segment-level granularity modeled propulsion technology, installation elevation, and end-use application dimensions across the projection horizon. Geographic splits tracked country-specific regulatory clusters including EU F-Gas refrigerant phasedown schedules and India's Smart Cities Mission financing eligibility. CAGRs derived from corridor commissioning timelines, replacement cycle analysis, and greenfield smart-city integration rates. Forecast inputs incorporated aluminum price trajectory assumptions and airport APM expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese export quota policies and EU emissions mandate enforcement. Forecasts reflect documented assumptions around commodity price stability and certification reciprocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
E-Bike Rental Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Global IoT in Transportation Market