
 Automotive Washer System Market | 2026-2036
Automotive Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Washer System Market Analysis
EU headlight washer mandates for adaptive driving beam systems is pivoting the cost-of-entry calculus for component suppliers. Robert Bosch GmbH leverages its mechatronics portfolio to dominate integrated pump-nozzle assemblies. Continental AG anchors European OEM supply through captive washer fluid reservoir production. Denso Corporation specializes in compact electric pump modules for Japanese and Southeast Asian vehicle platforms.
Automotive washer systems deliver pressurized cleaning fluid to windshields, headlamps, and rear glass through electric diaphragm or centrifugal pumps operating at 45–90 psi, ensuring optical clarity for cameras and LiDAR. Windshield washers occupy the mature volume base while headlight washers capture expanding margin pools as beam-assist regulations proliferate. Electric pump technology leads unit growth, displacing mechanical systems in new vehicle architectures across OEM and factory-fitted installation channels.
NHTSA visibility standards, EU General Safety Regulation requirements, and China's GB/T automotive lighting norms collectively tighten performance thresholds for washer system duty cycles and fluid dispersion patterns. ECE R48 headlamp cleaning provisions directly shape European product specifications, while EPA VOC limits on washer fluid formulations constrain North American chemical composition. Stakeholders must monitor pending camera-cleaning mandates as autonomous sensor suites proliferate beyond traditional glass surfaces.
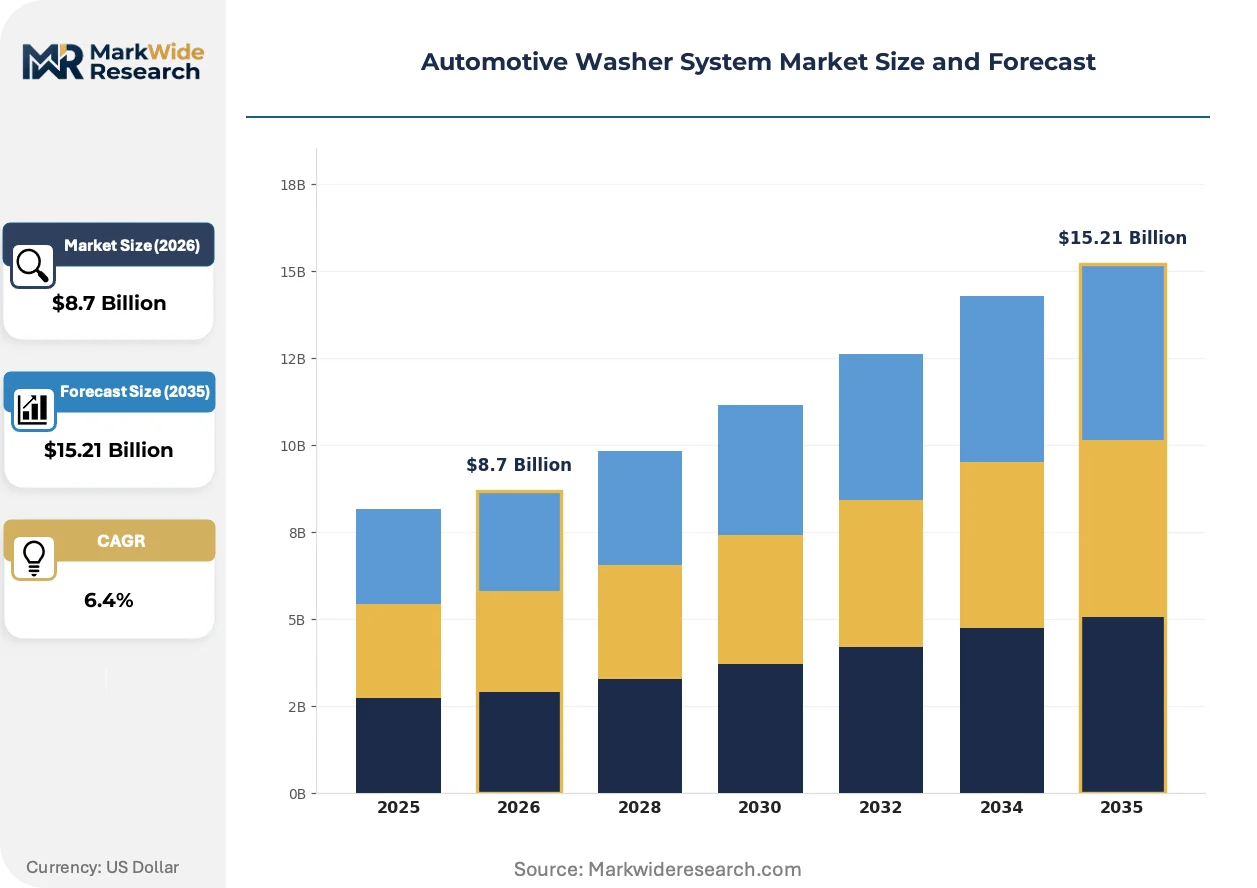
Market Dynamics
The automotive washer system market is restructuring around sensor-cleaning mandates for autonomous driving architectures, as optical clarity requirements for cameras and LiDAR units extend washer duty cycles beyond traditional glass surfaces.
Growth Catalysts
- ECE R48 Headlamp Cleaning Mandates:European beam-assist regulations now require active washer systems for adaptive driving beam headlamps, forcing OEM integration across mid-range vehicle segments.
- Heated Washer Fluid Technologies:Premium German automakers are specifying thermally managed fluid delivery to prevent freezing in cold-climate operation, expanding component value per vehicle.
- China:Domestic EV manufacturers are equipping advanced sensor cleaning architectures as standard fitment, concentrating demand for multi-nozzle pump modules with integrated level sensing.
Market Restraints
- EPA VOC Limits:Volatile organic compound restrictions on methanol-based washer fluid formulations constrain chemical composition flexibility in North American aftermarket channels.
- Electric Pump Cost Premium:Centrifugal and diaphragm pump modules carry 15-25% higher unit economics versus legacy mechanical systems, compressing margin at entry vehicle price points.
- Fluid Reservoir Consolidation:Captive production by tier-integrated suppliers limits independent component sourcing options for mid-volume OEM programs.
Strategic Opportunities
- Camera-Cleaning Mandates:Pending NHTSA visibility standards for surround-view and forward-facing camera systems will extend washer architecture to non-glass vehicle surfaces.
- Southeast Asia:Japanese platform exports and local assembly growth create demand for compact electric pump modules optimized for tropical humidity and dust exposure.
- Predictive Fluid Monitoring:Integration of IoT-enabled level sensors with connected vehicle platforms enables outcome-based consumables replenishment through dealer service channels.
Industry Challenges
- Multi-Sensor Integration Complexity:Washer nozzle positioning must avoid interference with embedded heating elements, antenna arrays, and aerodynamic surfaces in flush-mounted designs.
- Fluid Compatibility Certification:OEM validation cycles for biodegradable and low-VOC formulations extend supplier qualification timelines by 18-24 months.
- Legacy Mechanical System Phase-Out:Service network retraining and inventory transition create friction in aftermarket distribution during electric pump technology migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Washer System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield Washers, Headlight Washers, Rear Washers, Washer Pumps Technology: Mechanical, Electric, Pneumatic, Hybrid End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Installation: Factory-Fitted, Retrofitted, DIY Kits, Professional Installation |
| Companies Covered | Robert Bosch GmbH, Trico Products Corporation, Continental AG, Magna International, HELLA GmbH & Co. KGaA, Denso Corporation, Mitsuba Corporation, Kautex Textron GmbH, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Washer System Market Emerging Trajectories
Active cleaning architectures are automating optical maintenance for sensor-dependent driving systems, compressing the boundary between traditional washer hardware and autonomous vehicle infrastructure.
Heated washer fluid delivery systems are automating cold-weather operational reliability by integrating PTC heating elements directly into pump housings and reservoir modules. Scandinavian and Alpine market specifications now require guaranteed fluid flow at minus 40 degrees Celsius, forcing thermal management into baseline component design rather than optional cold-climate packages. This thermal integration is automating the shift from passive fluid storage to active temperature-conditioned supply systems.
REACH chemical restrictions and EU Green Deal sustainability frameworks are tightening formulation disclosure requirements for washer fluid concentrates sold in European aftermarket channels. Suppliers must now document biodegradability profiles and aquatic toxicity metrics alongside traditional performance specifications. German KBA type-approval processes are extending validation scope to include full lifecycle chemical assessments, compressing time-to-market for reformulated products.
Fleet operators and mobility service providers are unbundling washer system maintenance from traditional dealer service models, specifying direct fluid replenishment contracts with chemical suppliers. This channel disintermediation is visible most acutely in ride-hail and last-mile delivery vehicle segments where uptime metrics prioritize consumables availability over brand-authorized service. Urban logistics hubs in the Netherlands and California are piloting automated fluid top-off stations integrated with vehicle telematics.
Automotive Washer System Market Segmentation
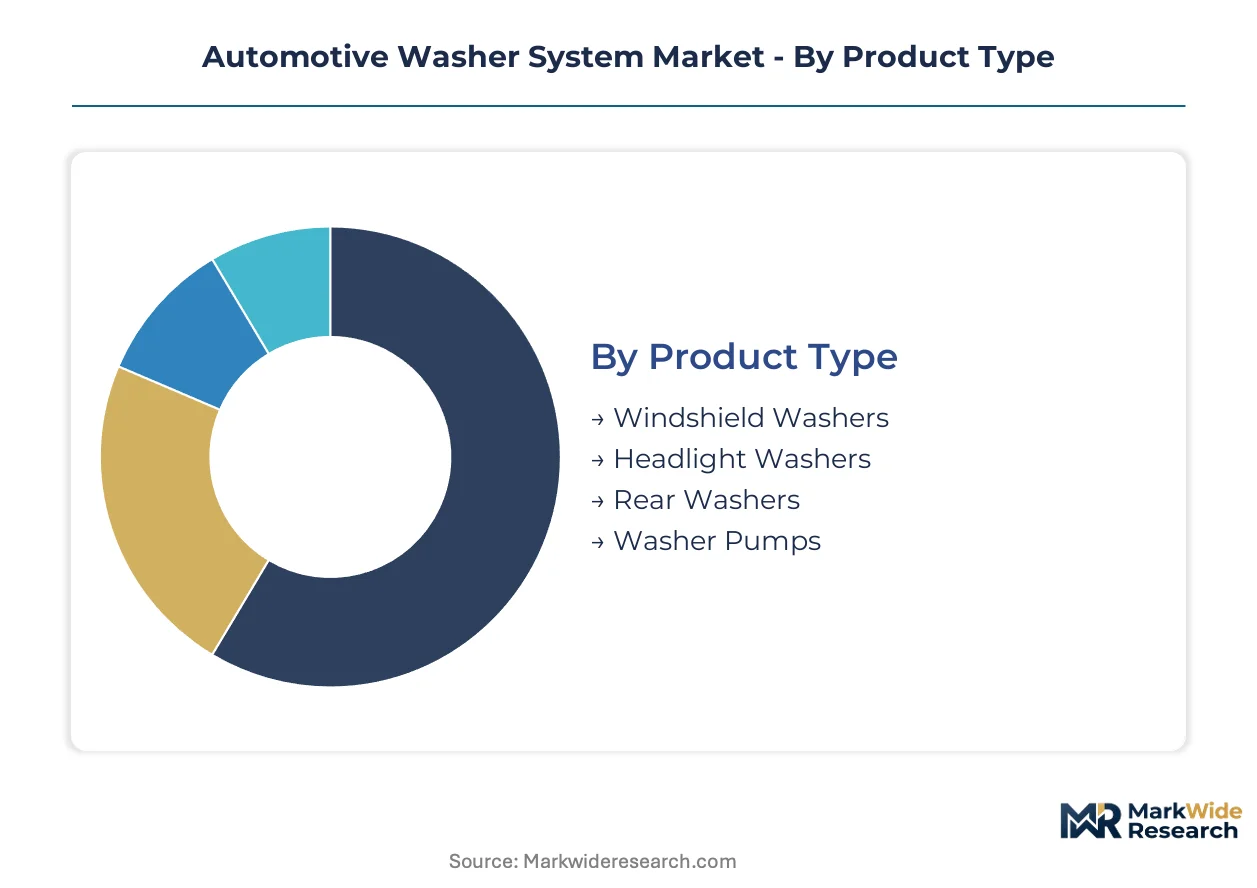
Washer system architectures fragment across pressure specifications, thermal requirements, and sensor integration complexity. Each segment category carries distinct supplier qualification barriers and margin profiles that reshape competitive positioning across OEM and aftermarket channels.
Product Type:
Supply concentration clusters around integrated pump-nozzle assemblies where tier-one suppliers control reservoir molding and fluid delivery subsystems.
- Windshield Washers:Diaphragm pumps operating at 45–60 psi dominate this mature volume base, with fluid reservoirs molded from high-density polyethylene. Demand concentrates in entry and mid-range vehicle platforms across China and India where cost optimization drives specification. OEMs in these markets prioritize single-pump architectures with basic level sensing over multi-nozzle configurations.
- Headlight Washers:High-pressure centrifugal systems deliver 70–90 psi pulses to clear adaptive driving beam lenses per ECE R48 mandates. German automakers specify these as standard fitment across premium and mid-range segments, expanding margin pools as beam-assist regulations proliferate beyond Europe into South Korea and Japan. Thermal management integration adds component value per vehicle.
- Rear Washers:Compact electric pumps with reduced flow rates serve hatchback and SUV rear glass cleaning. Southeast Asian platform exports drive volume for these cost-optimized modules.
- Washer Pumps:Modular pump units sold separately for replacement and upgrade applications. North American aftermarket channels source these for legacy mechanical system retrofits.
Today's leader: Windshield Washers. Tomorrow's challenger: Headlight Washers.
Technology:
Cost tier stratification separates legacy mechanical systems from electrically actuated architectures with embedded control electronics.
- Mechanical:Cam-driven diaphragm pumps tethered to engine accessory belts persist in commercial vehicle and emerging market applications. Brazilian and Indian OEMs specify these for price-sensitive truck platforms where electrical system upgrades remain capital-constrained.
- Electric:Brushless DC centrifugal and diaphragm pumps with pulse-width modulation control displace mechanical alternatives in new vehicle architectures. Chinese EV manufacturers specify compact electric modules with integrated level sensing as standard across domestic brand lineups, accelerating technology migration.
- Pneumatic:Compressed air-actuated systems for heavy-duty applications requiring explosion-resistant operation. Mining and agricultural equipment OEMs in Australia and Canada specify these for hazardous environment compliance.
- Hybrid:Dual-mode pumps combining electric priming with mechanical backup for cold-climate reliability. Scandinavian fleet operators pilot these for guaranteed minus 40 degrees Celsius operation.
Electric modules are gaining share fastest as OEM electrical architectures standardize on 48-volt subsystems.
End User:
Application requirements diverge between serialized production programs and distributed service networks with distinct inventory and technical support demands.
- OEMs:Tier-one suppliers manage just-in-sequence delivery of complete washer system modules to vehicle assembly plants. German KBA type-approval processes extend validation timelines for new fluid formulations and nozzle geometries.
- Aftermarket Providers:Independent distributors stock replacement pumps, nozzles, and reservoir assemblies for service bay installation. EPA VOC limits on methanol-based concentrates constrain chemical composition flexibility in North American channels.
- Vehicle Assemblers:Contract manufacturers and local assembly operations sourcing washer systems for knock-down kit production. Thai and Indonesian facilities serving Japanese platform exports specify tropical-optimized pump modules.
- Fleet Operators:Ride-hail and logistics companies negotiating direct fluid replenishment contracts bypassing dealer service networks. Dutch urban logistics hubs pilot automated top-off stations integrated with vehicle telematics.
OEMs anchor current volume. Fleet operators represent the steepest expansion trajectory as mobility-as-a-service models proliferate.
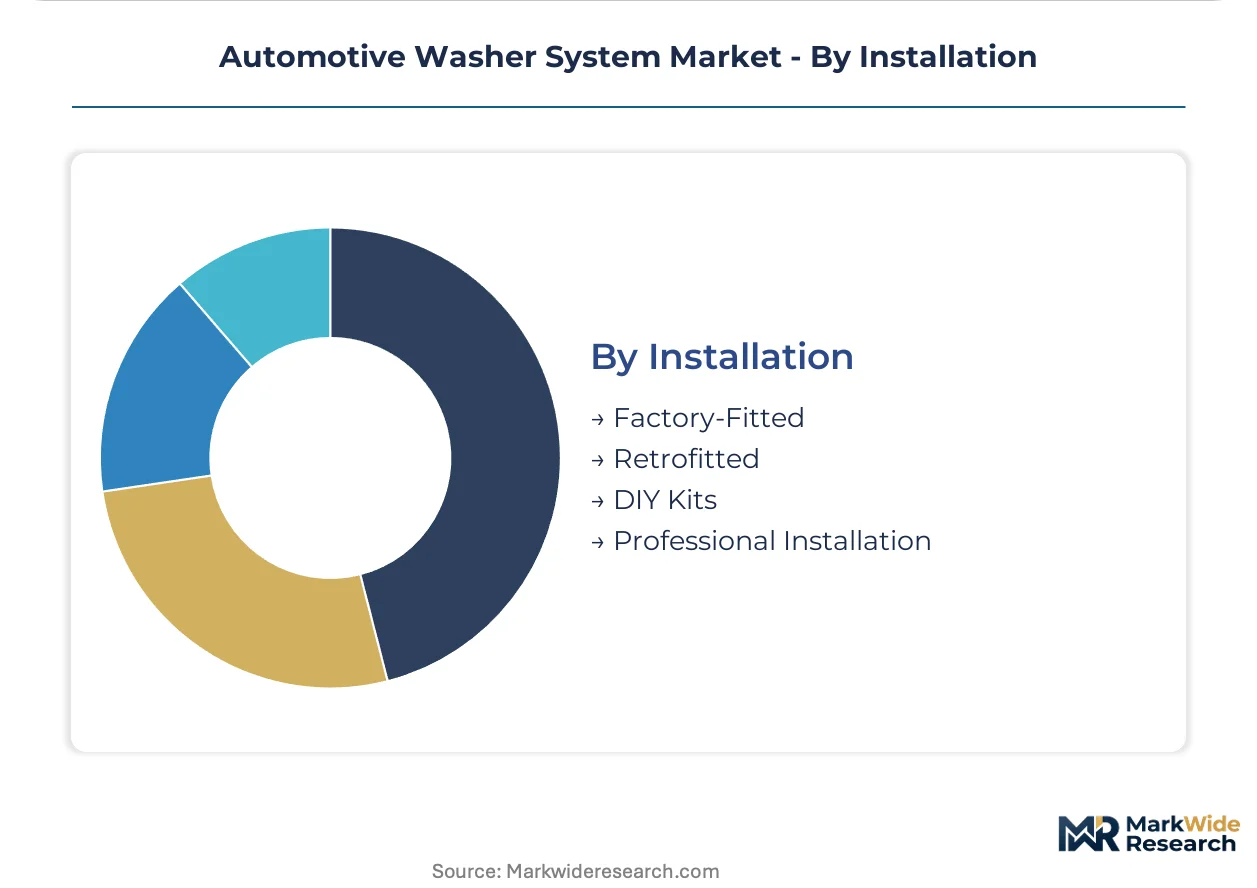
Installation:
Channel configuration shapes warranty terms, technical documentation requirements, and supplier liability exposure.
- Factory-Fitted:Washer systems integrated during vehicle assembly with full OEM warranty coverage. ECE R48 compliance verification occurs at this stage for European market certification.
- Retrofitted:Aftermarket headlight washer kits installed post-purchase to meet regulatory requirements in jurisdictions with phased mandate implementation. South Korean independent installers specialize in adaptive beam system upgrades.
- DIY Kits:Consumer-packaged pump and nozzle assemblies for home installation. Online retail channels in the United States and United Kingdom drive volume for these price-positioned offerings.
- Professional Installation:Dealer and authorized service center fitting with diagnostic calibration. German premium brands require this channel for heated washer fluid system activation and warranty registration.
Factory-fitted installation commands the revenue base. Professional installation channels are climbing the fastest as sensor-cleaning architectures demand calibration expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive washer system integration during the 1970s headlamp cleaning mandate era, establishing technical standards that shaped global component architecture. European beam-assist regulations and Chinese EV sensor-cleaning specifications now drive regional demand divergence.
Germany
Premium automakers specify heated washer fluid systems as standard fitment across mid-range and luxury segments. KBA type-approval processes extend validation timelines for new fluid formulations and nozzle geometries. Stuttgart and Munich industrial corridors concentrate tier-one supplier engineering centers for integrated pump-nozzle assemblies.
China
Domestic EV manufacturers equip multi-nozzle pump modules with integrated level sensing as baseline specification across brand lineups. GB/T automotive lighting norms tighten performance thresholds for washer system duty cycles and fluid dispersion patterns. Shanghai and Shenzhen production hubs scale compact electric pump architectures for export and domestic consumption.
United States
NHTSA visibility standards for forward-facing camera systems will extend washer architecture to non-glass vehicle surfaces pending regulatory finalization. EPA VOC limits on methanol-based washer fluid formulations constrain aftermarket chemical composition flexibility. Detroit and Southeast Michigan anchor OEM supply chain integration for factory-fitted installation channels.
Japan
Platform exports to Southeast Asian assembly operations drive demand for tropical-optimized compact electric pump modules. METI industrial standards shape durability specifications for humidity and dust exposure conditions. Nagoya and Osaka manufacturing belts specialize in brushless DC centrifugal pump production for regional vehicle architectures.
South Korea
Independent installers specialize in adaptive beam system retrofits as ECE R48-equivalent mandates phase in for domestic market certification. MFDS chemical oversight extends to automotive fluid concentrate safety assessments. Seoul metropolitan area hosts R&D facilities for hybrid pump architectures combining electric priming with mechanical backup systems.
Automotive Washer System Market Vendor Landscape
The competitive structure tilts toward tier-integrated mechatronics specialists with captive reservoir production and pump-module integration capabilities. Consolidation pressure concentrates around OEMs demanding just-in-sequence delivery of complete washer system modules. Three archetypes dominate: diversified automotive suppliers with full-system integration, specialized pump-technology fabricators, and regional component assemblers serving knock-down kit production. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrification timelines compress supplier qualification windows.
Among diversified German-based suppliers, Robert Bosch GmbH exemplifies the integrated mechatronics archetype through its pump-nozzle assembly portfolio. Continental AG occupies a position within the tier-integrated tier with captive washer fluid reservoir production anchoring European OEM supply relationships. Denso Corporation represents the compact electric pump specialization vector for Japanese and Southeast Asian platform requirements. Valeo SA and HELLA GmbH & Co. KGaA sit within the European premium-tier supplier cluster serving beam-assist mandate compliance.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Trico Products Corporation |
| Continental AG |
| Magna International |
| HELLA GmbH & Co. KGaA |
| Denso Corporation |
| Mitsuba Corporation |
| Kautex Textron GmbH |
| Valeo SA |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap German pump specialists anchor tier-two supply positions, disciplining pricing through captive mold operations and just-in-sequence delivery contracts that compress margin leakage at entry vehicle tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the automotive washer system market by certification grade and thermal integration depth. German KBA type-approval processes extend validation timelines for heated fluid systems, widening price spreads between compliant and non-compliant tiers. Pricing pressure stems from Chinese EV OEMs specifying compact electric modules at volume scale, forcing cost compression in mid-range diaphragm pump configurations. Aftermarket channels exhibit highest price sensitivity due to EPA VOC formulation constraints, while factory-fitted OEM installations absorb premium positioning for sensor-cleaning architectures.
Supply Chain Analysis
High-density polyethylene resin supply rests on petrochemical producers in Germany, China, and Saudi Arabia, with specialized grades for fluid reservoirs concentrated among European compounders. Brushless DC motor components and PTC heating elements constitute critical input dependencies alongside precision-molded nozzle assemblies. Single-source vulnerability concentrates in mechatronics-integrated pump modules where Robert Bosch GmbH and Continental AG control captive reservoir production. Distribution runs through tier-one supplier direct-to-OEM channels for factory-fitted installation, with aftermarket flow through independent distributors serving service bay networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive washer systems derives from heated fluid technology penetration and sensor-cleaning mandate compliance, compressing cost-down timelines for electric pump module standardization.
For Market Incumbents: To counter Chinese EV OEM vertical integration into compact pump production, deepen backward integration into PTC heating element supply and expand capacity in Southeast Asian assembly corridors serving Japanese platform exports. Certification investment in GB/T and ECE R48 compliance preserves pricing power in regulated segments. For New Entrants and Emerging Players: Enter via fleet operator direct fluid replenishment contracts in Dutch and Californian urban logistics hubs, where outcome-based service models bypass dealer network capture. Target professional installation channels for camera-cleaning retrofit architectures as NHTSA visibility standards extend washer duty cycles beyond glass surfaces. For Investors and Strategic Acquirers: Valuations sit cheapest among regional component assemblers serving Thai and Indonesian knock-down kit production, where platform export growth outpaces local supply sophistication. Long-term viability hinges on electrification timeline compression and autonomous sensor suite proliferation. Watch for pending camera-cleaning mandate finalization as inflection trigger for multi-sensor architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Heated Fluid System Integration | PTC heating element embedding raises component value per vehicle for German premium OEMs. |
| Sensor-Cleaning Architecture Development | Multi-nozzle positioning for LiDAR and camera units extends washer duty cycles beyond traditional glass. |
| Southeast Asian Manufacturing Footprint | Compact electric pump production in Thailand serves Japanese platform exports to tropical humidity markets. |
| Fluid Replenishment Service Contracts | Direct chemical supplier agreements with Dutch logistics fleets disintermediate dealer service channels. |
| Biodegradable Formulation Certification | REACH compliance and KBA lifecycle assessments extend validation scope for European aftermarket concentrates. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers combined with secondary validation from IHS Markit vehicle registration databases, customs trade records, SEC supplier filings, and ECE regulatory documentation. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped washer system content per vehicle across propulsion architecture, vehicle class, and regional production cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against macro automotive production forecasts and electrification penetration assumptions. Forecast inputs included ECE R48 mandate phase-in schedules, Chinese EV sensor-cleaning specification adoption curves, and heated fluid technology cost-down trajectories.
Inputs from OEM production planning disclosures and supplier order backlogs were available through the study window; gaps in fleet operator contract terms and aftermarket channel inventory positions introduce uncertainty bands around service-based revenue forecasts. Assumptions underlying projections reflect documented regulatory timelines and technology adoption patterns. Material deviation in NHTSA camera-cleaning mandate finalization or Chinese EV export trajectory warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Mobile Emission Catalysts Market
Automotive Parts
North America Gear Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Crankcase Additives Market