
 Global Inductive Loop Vehicle Detector Market | 2026-2036
Global Inductive Loop Vehicle Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inductive Loop Vehicle Detector Market Outlook
FCC electromagnetic compatibility rules for roadside equipment is rebalancing the cost-of-entry calculus for North American suppliers. SWARCO AG leverages its European channel density to sustain embedded installation contracts across German autobahn networks. Eberle Design Inc. anchors its position through in-house production of loop amplifier modules for US municipal traffic departments. Iteris, Inc. competes by integrating inductive loop data with video analytics platforms for hybrid detection systems.
An inductive loop vehicle detector consists of one or more loops of insulated wire embedded in pavement, connected to a tuned electronic unit that detects metallic mass disturbance via resonant frequency shift, typically operating between 10 kHz and 200 kHz. The device serves primarily to register vehicle presence, passage, and occupancy for signal timing optimization and traffic flow measurement. Traffic sensors occupy the largest volume share given their deployment at every signalized intersection requiring actuation. Parking sensors represent the fastest-growing product category as operators automate entry-exit revenue collection. Embedded installations command premium positioning due to trenching complexity and longer service intervals versus surface-mounted alternatives.
US DOT Federal Highway Administration signal timing guidelines shape municipal procurement specifications for detector sensitivity and fail-safe operation. EU Intelligent Transport Systems Directive mandates interoperable data formats that influence product architecture decisions for cross-border equipment vendors. Japan's METI road traffic safety standards impose electromagnetic immunity thresholds that filter out non-compliant amplifier designs. Stakeholders must monitor evolving frequency allocation rules and pavement material shifts that could degrade loop sensitivity or accelerate alternative sensor substitution.
Market Dynamics
Legacy inductive loop infrastructure faces accelerated replacement cycles as EU Intelligent Transport Systems Directive mandates force interoperability upgrades across signalized intersection networks, compressing equipment lifespans and redirecting municipal capital toward embedded detection systems with standardized data outputs.
Growth Catalysts
- Smart City Infrastructure Mandates:Singapore's Land Transport Authority is expanding detector deployment at signalized intersections as part of centralized traffic management digitization, creating sustained procurement volume for embedded loop systems.
- EU Directive Compliance Windows:The revised Intelligent Transport Systems Directive is accelerating replacement of legacy detection infrastructure across member states, forcing interoperability upgrades that favor modern inductive loop architectures with standardized data formats.
- Urban Corridor Modernization:Germany's autobahn and municipal road upgrade programs are concentrating demand for high-reliability vehicle detection at toll plazas and signalized junctions, anchoring European installation volumes.
Market Restraints
- Copper and Insulation Material Volatility:Loop wire production depends on copper pricing and specialized pavement-grade insulation compounds, exposing embedded installation contractors to input cost swings that compress project margins.
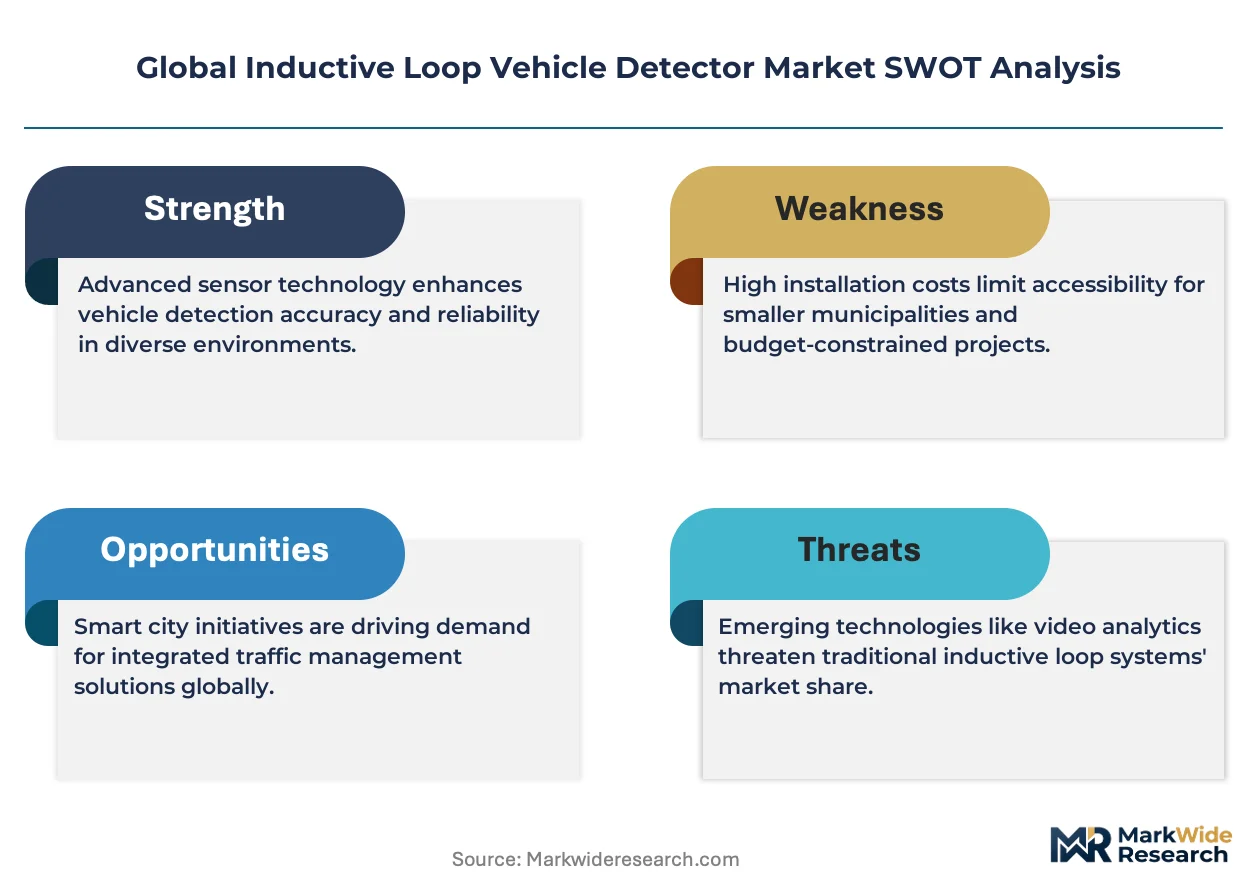
- Alternative Sensor Substitution:Video detection, radar, and LiDAR systems are capturing greenfield intersection projects where trenching costs or pavement preservation concerns outweigh inductive loop reliability advantages.
- Installation Labor Bottlenecks:Skilled trenching and pavement restoration crews concentrate in established urban markets, limiting deployment velocity in secondary cities and extending project timelines.
Strategic Opportunities
- Parking Automation Expansion:Revenue-controlled parking facilities represent underpenetrated demand for entry-exit detection, with operators automating payment validation through loop-integrated barrier systems.
- Hybrid Detection Convergence:Integration of inductive loop presence data with video analytics platforms creates bundled offerings for municipal traffic departments seeking redundant vehicle classification capabilities.
- US Municipal Replacement Cycles:FHWA signal timing guideline updates are reshaping procurement specifications for detector sensitivity and fail-safe operation, opening specification windows for compliant amplifier module suppliers.
Industry Challenges
- Electromagnetic Compatibility Certification:FCC Part 15 rules for roadside equipment impose testing timelines and redesign costs on North American suppliers seeking municipal approval, extending product launch cycles.
- Pavement Material Sensitivity:Open-graded friction courses and polymer-modified asphalt mixes alter electromagnetic coupling efficiency, requiring loop geometry recalibration that complicates standardized product offerings.
- Legacy System Integration:Municipal traffic signal controllers operate on proprietary communication protocols, forcing detector manufacturers to maintain multiple interface variants and fragmenting firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inductive Loop Vehicle Detector Market |
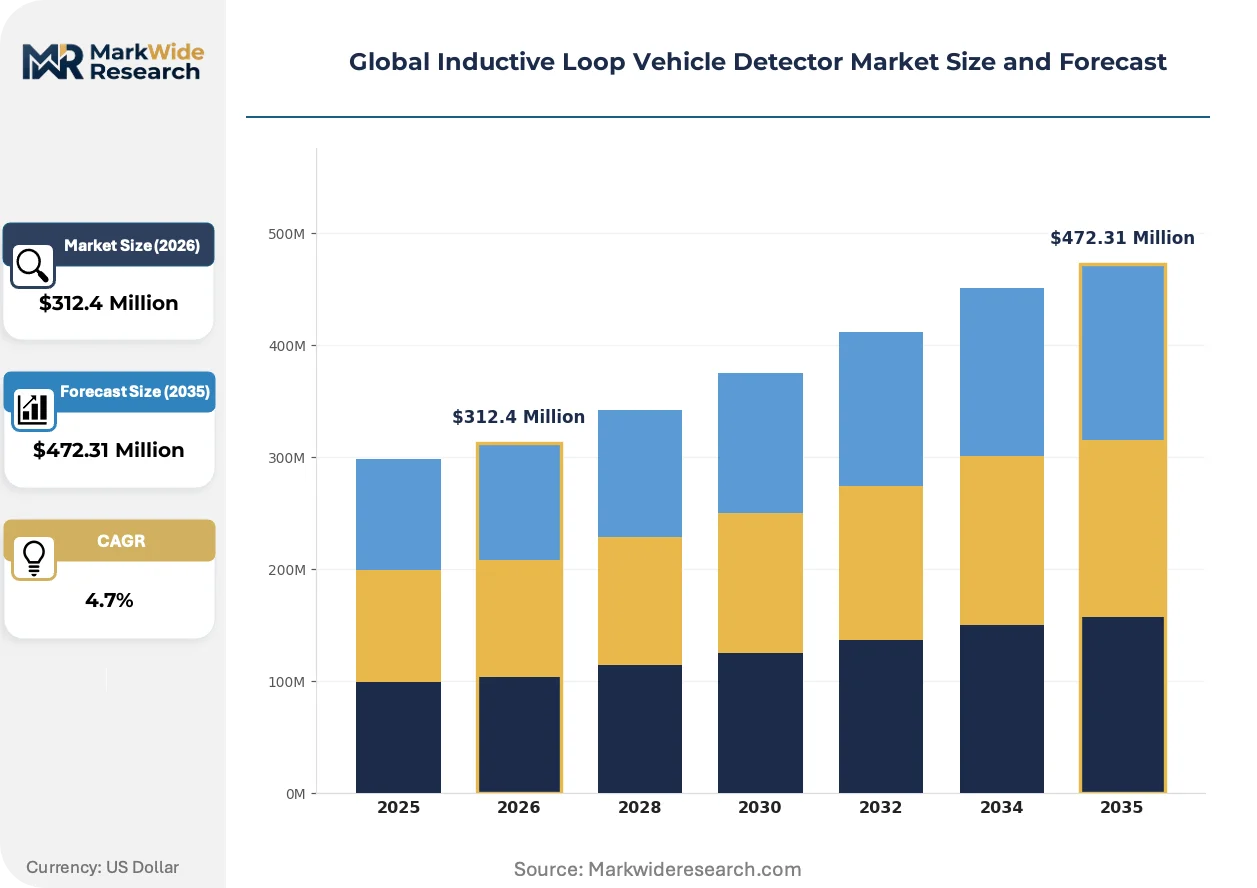
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Sensors, Parking Sensors, Speed Sensors, Automated Vehicle Identification Application: Traffic Management, Parking Management, Toll Collection, Public Transport End User: Government Agencies, Transportation Companies, Parking Operators, OEMs Installation Type: Surface Mounted, Embedded, Portable, Fixed |
| Companies Covered | PROCON, Eberle Design Inc., SWARCO AG, Iteris, Inc., Siemens Mobility, Marsh Products, Reno A&E, Econolite, Nortech Access Control Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inductive Loop Vehicle Detector Market Strategic Shifts
Detection architecture is fragmenting as edge computing capabilities and wireless communication protocols enable distributed processing at the roadside, reducing dependency on centralized traffic management systems while creating new competitive battlegrounds around data interoperability and cybersecurity certification.
Digital loop amplifier technology is decentralizing vehicle detection processing by embedding microprocessor-based frequency analysis directly at the roadside cabinet, eliminating analog signal transmission vulnerabilities. German autobahn operators are adopting these units for remote diagnostic capabilities that reduce maintenance truck rolls. This shift is compressing the addressable market for standalone traffic signal controller cards while expanding recurring firmware licensing revenue streams.
Japan's METI road traffic safety standards are tightening electromagnetic immunity thresholds for roadside equipment, filtering out non-compliant amplifier designs from procurement-eligible supplier pools. The revised technical criteria mandate conducted and radiated immunity testing that smaller module producers struggle to resource. Detector manufacturers serving Japanese municipal markets are responding by redesigning power supply filtering and shielding architectures to meet the elevated certification bar.
Municipal procurement patterns are fragmenting as traffic engineering departments unbundle detector supply from signal controller maintenance contracts, enabling direct sourcing of loop amplifier modules and specialized installation services. This disintermediation is compressing pricing power for vertically integrated signal system vendors while creating procurement volume for component specialists. US state DOTs and large municipal traffic departments are most visibly adopting this unbundled sourcing model, driven by federal highway funding accountability requirements.
Global Inductive Loop Vehicle Detector Market Segmentation
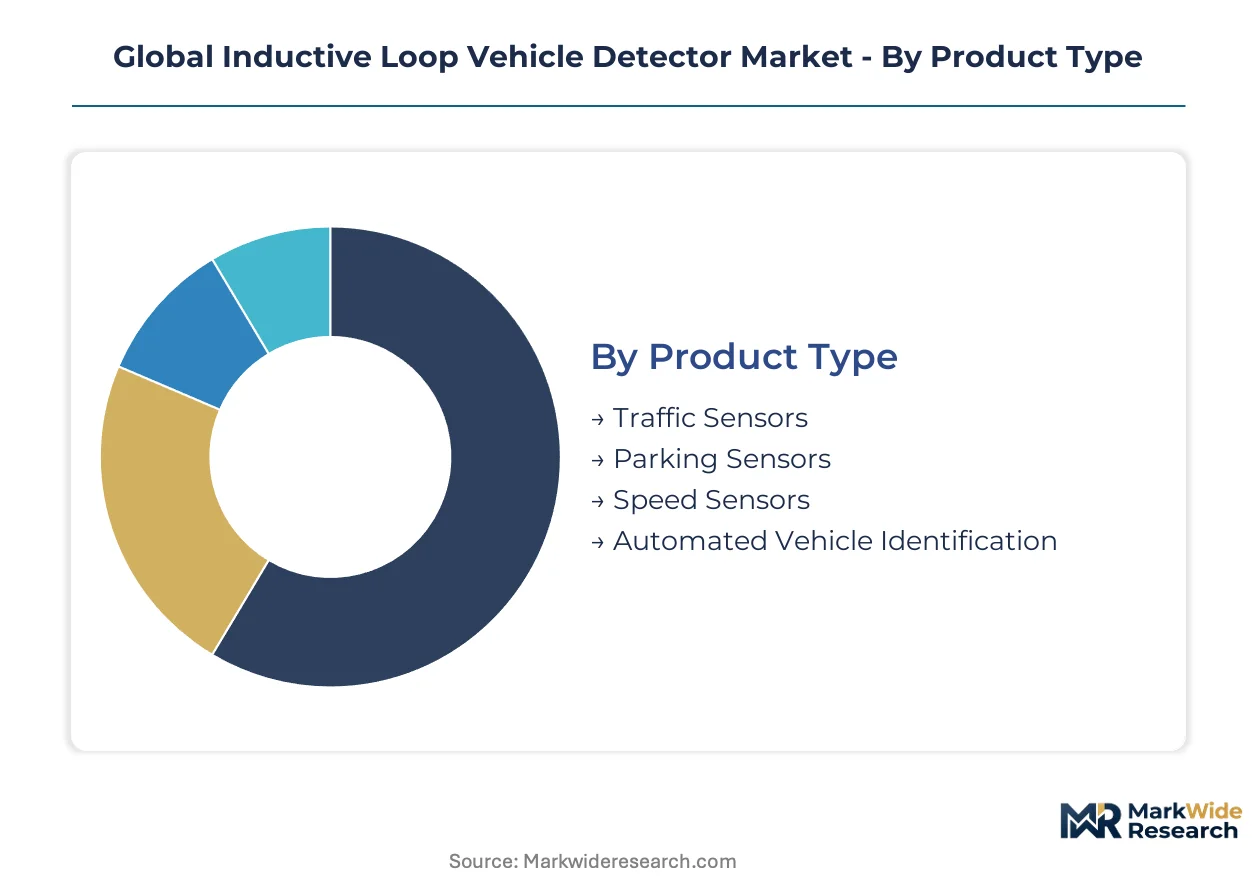
Inductive loop vehicle detector procurement varies sharply across deployment contexts, with specification requirements diverging based on pavement preservation constraints, signal controller compatibility, and data interoperability mandates. Understanding these segment boundaries clarifies where component suppliers can unbundle amplifier modules from full system contracts.
Product Type:
Buyer priorities split between high-volume intersection actuation and specialized revenue-control applications, with sensitivity thresholds and communication protocols driving specification divergence.
- Traffic Sensors:These units detect vehicle presence, passage, and occupancy at signalized intersections through resonant frequency shift analysis, typically operating between 10 kHz and 200 kHz. Demand concentrates in Germany's autobahn and municipal corridor upgrade programs, where high-reliability detection anchors European installation volumes amid EU Intelligent Transport Systems Directive compliance windows.
- Parking Sensors:Entry-exit detection systems automate barrier actuation and payment validation in revenue-controlled facilities. Operators in Singapore's Land Transport Authority smart city digitization programs are expanding deployment fastest, creating procurement volume for loop-integrated access control systems.
- Speed Sensors:Specialized units measure vehicle velocity through dual-loop spacing calculations for enforcement and traffic flow analysis.
- Automated Vehicle Identification:Systems integrate loop detection with classification algorithms for toll plaza and border crossing applications.
Volume sits with Traffic Sensors; growth tilts toward Parking Sensors.
Application:
Deployment complexity escalates from single-point detection to networked corridor management, with data format standardization requirements determining vendor qualification.
- Traffic Management:Signal timing optimization and flow measurement at urban intersections represents the foundational use case, with US DOT Federal Highway Administration guidelines shaping municipal procurement specifications for detector sensitivity and fail-safe operation.
- Toll Collection:High-speed vehicle classification and axle counting at plaza approaches demands ruggedized amplifier designs with electromagnetic immunity certification. Japan's METI road traffic safety standards filter non-compliant designs from procurement pools through tightened conducted and radiated immunity thresholds.
- Parking Management:Automated entry-exit systems for payment validation and space occupancy tracking.
- Public Transport:Bus priority signal preemption and transit lane enforcement applications.
Revenue concentrates in Traffic Management; Toll Collection shows the steepest specification escalation.
End User:
Procurement authority fragmentation creates diverging contract structures, from federal funding accountability requirements to private operator unbundled sourcing.
- Government Agencies:State DOTs and municipal traffic departments dominate intersection deployment, with US federal highway funding rules driving unbundled detector sourcing separate from signal controller maintenance contracts.
- Parking Operators:Private and municipal garage operators automate revenue collection through loop-integrated barrier systems, representing underpenetrated demand expansion.
- Transportation Companies:Transit authorities and logistics operators deploy detection for priority signaling and yard management.
- OEMs:Original equipment manufacturers integrate detector modules into complete traffic signal system offerings.
Contract value aggregates with Government Agencies; margin opportunity clusters with Parking Operators.
Installation Type:
Site constraints and pavement preservation priorities determine trenching depth, loop geometry, and service accessibility tradeoffs.
- Embedded:Loops of insulated wire trenched into pavement structure command premium positioning due to installation complexity and longer service intervals, with skilled crew availability limiting deployment velocity in secondary markets.
- Surface Mounted:Above-ground alternatives avoid trenching disruption where pavement preservation concerns outweigh reliability advantages, though electromagnetic coupling efficiency varies with pavement material shifts.
- Portable:Temporary deployment units for construction zone traffic management and special event routing.
- Fixed:Permanent cabinet-mounted installations with hardwired power and data connections.
Project margin peaks with Embedded; Surface Mounted gains share where trenching costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong Innovation District and German industrial zones concentrate embedded detector manufacturing capacity, with specialized economic development incentives attracting precision electronics producers serving traffic infrastructure markets.
United States
FHWA signal timing guideline updates are reshaping municipal procurement specifications for detector sensitivity and fail-safe operation. FCC Part 15 electromagnetic compatibility rules impose testing timelines on roadside equipment suppliers. California's urban corridor modernization programs and Texas DOT infrastructure upgrades anchor North American installation volumes.
Germany
Autobahn and municipal road upgrade programs concentrate demand for high-reliability vehicle detection at toll plazas and signalized junctions. The EU Intelligent Transport Systems Directive mandates interoperability upgrades that favor modern inductive loop architectures. Bavaria's traffic management digitization and North Rhine-Westphalia's industrial corridor anchor European equipment deployment.
Singapore
Land Transport Authority smart city digitization programs are expanding detector deployment at signalized intersections as part of centralized traffic management systems. The country's national standards body imposes electromagnetic immunity thresholds that filter non-compliant amplifier designs. Jurong Innovation District clustering supports precision electronics manufacturing for regional export markets.
Japan
METI road traffic safety standards tighten electromagnetic immunity thresholds for roadside equipment, mandating conducted and radiated immunity testing. Kanto region metropolitan traffic authorities deploy detection systems for signal preemption and flow measurement. Nagoya's industrial corridor hosts amplifier module producers serving municipal procurement pools.
United Kingdom
Department for Transport signal controller replacement programs create specification windows for compliant detector suppliers. CE marking requirements under EU-UK trade arrangements influence product architecture decisions for cross-border equipment vendors. Greater London's congestion management zone and Midlands urban corridor upgrades concentrate installation demand.
Global Inductive Loop Vehicle Detector Market Competitive Environment
German producers anchor one tier of the embedded detection market; North American specialists hold municipal procurement channels through proximity to state DOT specification processes. The vendor structure fragments across three tiers: vertically integrated signal system vendors, component-focused amplifier module suppliers, and regional installation contractors. Two strategic archetypes dominate competitive positioning: channel-dense European equipment houses and specification-savvy North American component specialists. M&A activity concentrates on acquiring installation service capabilities; technology licensing agreements proliferate around digital amplifier firmware.
Among the established equipment houses, SWARCO AG and Siemens Mobility exemplify the vertically integrated archetype with embedded installation contracts across European autobahn networks. Eberle Design Inc. occupies a position within the North American component specialist tier, with Iteris, Inc. representing the hybrid detection convergence strategy integrating multiple sensor modalities. These three anchors illustrate how geographic origin and strategic focus determine competitive positioning without requiring uniform product portfolios or overlapping customer relationships.
| Leading Market Players |
|---|
| PROCON |
| Eberle Design Inc. |
| SWARCO AG |
| Iteris, Inc. |
| Siemens Mobility |
| Marsh Products |
| Reno A&E |
| Econolite |
| Nortech Access Control Ltd |
| Others |
Value Chain & Pricing Dynamics
Family-owned German mid-caps and municipal-contractor roll-ups anchor embedded installation capacity across European autobahn networks, concentrating supply-side pricing discipline while copper and specialized insulation compound volatility compresses project margins for trenching crews in secondary markets.
Pricing Analysis
Short lead-time premiums for FCC Part 15 certified amplifier modules run 15-25 percent above standard procurement cycles, while spot inventory of legacy analog units trades at distressed levels. Three-tier pricing structure across premium, standard, and economy levels separates digital loop amplifiers with remote diagnostic firmware from basic presence-detection units and refurbished legacy cards. Cost compression in the embedded installation tier is intensifying because skilled trenching crew scarcity extends project timelines and inflates labor pass-throughs. Municipal traffic departments exhibit highest price sensitivity due to federal highway funding accountability requirements, while German autobahn operators prioritize fail-safe certification over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from US state DOTs and EU directive-compliant procurement pools require amplifier module qualification across at least two fabrication facilities, fragmenting volume concentration. Manufacturing gravity centers on Germany, Singapore, and Japan, with Jurong Innovation District precision electronics clusters feeding regional export markets. Copper wire drawing and pavement-grade insulation compound production draws from established petrochemical and base metals supply bases. Single-source vulnerability concentrates in specialized loop geometry calibration equipment. Distribution runs through vertically integrated signal system vendors, unbundled component specialists, and regional installation contractors serving municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inductive loop vehicle detector market sits in a protracted technology-transition phase as digital loop amplifiers with edge-computing firmware displace analog signal processing architectures, compressing addressable volume for standalone controller cards while expanding recurring software licensing revenue streams.
For Market Incumbents: To counter video detection and radar substitution at greenfield intersections, anchor position through backward integration into copper wire and insulation compound supply, and accelerate firmware certification for Japan's METI electromagnetic immunity thresholds to filter non-compliant competitors from procurement pools. For New Entrants and Emerging Players: Begin with parking automation white space in Singapore's Land Transport Authority digitization programs and German municipal garage operator unbundled sourcing, where barrier-integrated loop systems face limited entrenched competition and specification windows favor compliant amplifier module suppliers over full-system vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-focused amplifier module specialists with FCC and CE marking certification infrastructure in North American and European geographies, where municipal procurement fragmentation creates rollup opportunities. Long-term viability hinges on firmware recurring revenue attachment rates displacing hardware transactional value. Monitor video-analytics hybrid detection convergence as the signal indicating inductive loop addressable market compression versus embedded sensor coexistence stability.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Amplifier Firmware Licensing | Recurring revenue streams from remote diagnostic capabilities reduce maintenance truck rolls for German autobahn operators. |
| Hybrid Detection Platform Integration | Loop presence data fusion with video analytics creates bundled offerings for US municipal traffic departments seeking redundancy. |
| EU Directive Compliance Certification | Interoperable data format validation opens specification windows across member state signalized intersection upgrade programs. |
| Parking Automation Channel Expansion | Revenue-controlled facility entry-exit systems represent underpenetrated demand for loop-integrated barrier actuation. |
| Electromagnetic Immunity Redesign | Power supply filtering and shielding architecture upgrades meet Japan's METI tightened conducted and radiated immunity thresholds. |
Study Parameters
Document review covered municipal traffic department procurement specifications, FCC Part 15 electromagnetic compatibility filings, and EU Intelligent Transport Systems Directive implementation guidance, complemented by interviews with traffic engineering directors, signal controller maintenance contractors, parking facility operators, and amplifier module procurement leads at state DOTs. Secondary validation drew from US DOT Federal Highway Administration signal timing guideline updates, Japan's METI road traffic safety standard revisions, and customs data on copper wire and insulation compound trade flows. Bottom-up installation volume estimates and top-down equipment spend triangulation anchored market sizing.
Historical deployment patterns across traffic management, toll collection, and parking management applications were cross-referenced against panel input from municipal procurement officers and autobahn network operators. Segmentation modeling captured product type, installation configuration, and end-user authority fragmentation across the projection horizon. CAGRs were derived from equipment replacement cycle compression, smart city infrastructure mandate pacing, and alternative sensor substitution elasticity. Industry-specific forecast inputs included pavement material electromagnetic coupling efficiency shifts and frequency allocation rule evolution.
Copper and insulation material price volatility, alternative sensor technology cost curves, and electromagnetic compatibility certification timeline delays are the dominant revision risks to modeled outcomes. Deviation in municipal unbundled sourcing adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Power Steering Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Automotive Trailing Arm Bushing Market