
 Automotive Ventilated Seats Market | 2026-2036
Automotive Ventilated Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ventilated Seats Market Analysis
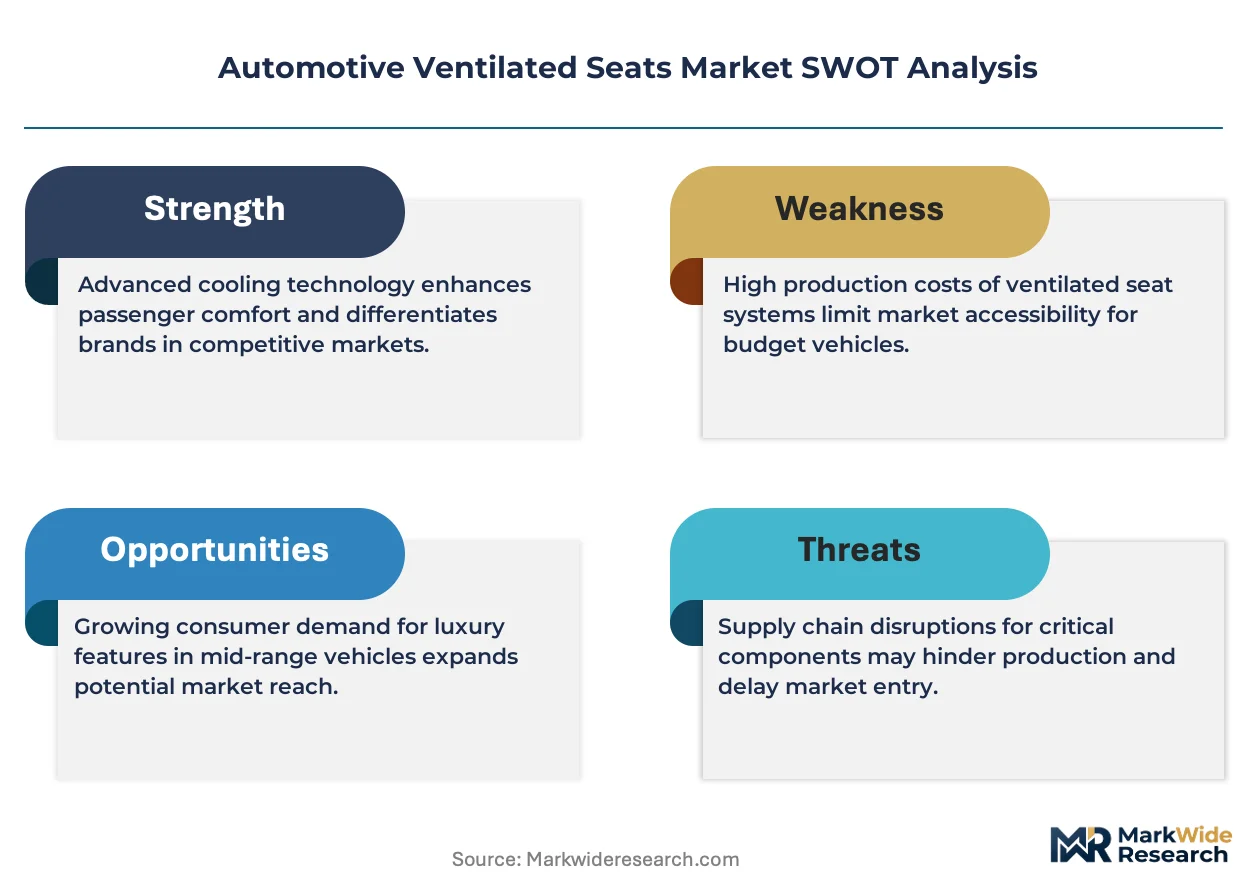
ISO 26262 functional safety qualification is collapsing the supplier base for electronic seat climate modules. Magna International leverages its integrated seat structure and electronics capability to capture programs requiring ASIL-rated blower control. Gentherm Incorporated anchors its position through proprietary thermal management IP spanning convection and Peltier architectures. Toyota Boshoku Corporation dominates Asian OEM supply chains with vertically controlled foam, trim, and fan module production.
Automotive ventilated seats employ perforated trim surfaces coupled with forced-air distribution systems, typically using axial or centrifugal blowers rated between 5W and 25W to draw conditioned cabin air through foam substrates and upholstery layers. The primary purpose is thermoregulatory comfort, reducing occupant back and thigh perspiration in ambient temperatures above 25°C while extending perceived leather and synthetic surface durability. Cooling seats and ventilated seats lead volume, though Peltier-based thermoelectric modules command higher per-unit value due to active temperature modulation capability. OEM channels sustain the dominant revenue share, while aftermarket providers compete on replacement cycle timing as vehicle fleets age beyond warranty periods.
NHTSA guidelines on occupant thermal stress inform blower performance baselines in the United States, while ECE R14 and EU REACH restrictions on foam blowing agents shape material selection across European supply chains. China's GB standards for automotive electrical subsystems govern fan motor efficiency and electromagnetic compatibility for locally produced modules. Stakeholders must monitor evolving multi-domain compliance requirements spanning safety, chemical, and energy regulations as thermal comfort becomes standard rather than premium equipment.
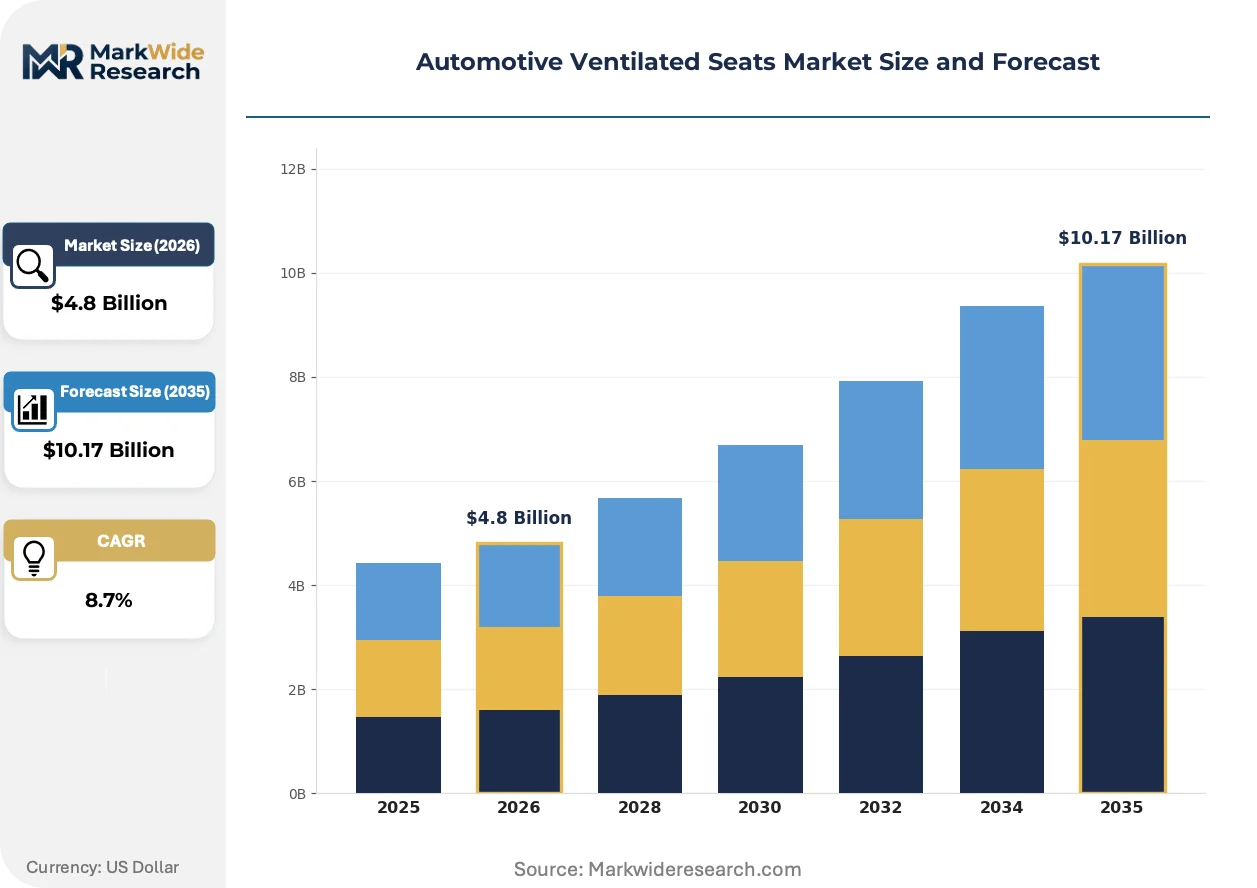
Market Dynamics
ISO 26262 functional safety mandates are compressing the supplier base for electronic seat climate modules, forcing tier-1 integrators to absorb blower control electronics into ASIL-rated architectures while mid-tier foam converters exit the market.
Growth Catalysts
- EPA fuel-efficiency standards:Lower-draw blower architectures under 15W are displacing legacy 25W systems as OEMs seek to protect vehicle range and thermal load budgets.
- Mid-tier nameplate expansion:Luxury and premium vehicle manufacturers are extending ventilated seat fitment downward into volume segments, broadening addressable vehicle platforms.
- Leather durability expectations:Forced-air thermoregulation extends perceived upholstery lifespan by reducing perspiration-induced surface degradation in high-humidity climates.
Market Restraints
- Foam substrate cost volatility:Polyurethane foam pricing fluctuates with petrochemical feedstock exposure, compressing module margins for trim-integrated suppliers.
- ISO 26262 certification barriers:Functional safety qualification timelines exceed 18 months, freezing out electronics-naive seating specialists from blower control procurement.
- Peltier thermoelectric substitution:Active cooling modules command higher per-unit economics, threatening pure ventilation architectures in premium configurations.
Strategic Opportunities
- China GB standard alignment:Local fan motor efficiency and electromagnetic compatibility mandates favor domestic production scale for Asian OEM supply chains.
- Aftermarket replacement cycles:Aging vehicle fleets beyond warranty periods create service-channel demand for retrofit blower modules and trim replacement.
- Convection-Peltier hybrid convergence:Dual-architecture seats combining forced-air distribution with thermoelectric modulation capture price premiums in executive vehicle segments.
Industry Challenges
- ASIL-D blower control firmware:Functional safety software development requires embedded systems talent scarce among traditional seating suppliers.
- Multi-domain compliance timelines:Simultaneous NHTSA thermal stress, EU REACH foam agent, and GB electrical subsystem certifications extend program validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ventilated Seats Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Seats, Heated Seats, Ventilated Seats, Massage Seats End User: OEMs, Aftermarket Providers, Distributors, Dealerships Material: Leather, Fabric, Synthetic, Mesh Technology: Conduction, Convection, Peltier, Air Blower |
| Companies Covered | Toyota Boshoku Corporation, Magna International Inc., Lear Corporation, NHK Spring Co. Ltd., TS Tech Co. Ltd., Adient PLC, Gentherm Incorporated, Brose Fahrzeugteile GmbH, Faurecia SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ventilated Seats Market Emerging Trajectories
Active thermal management architectures are fragmenting into specialized subsystems as OEMs decouple seat climate from centralized HVAC control, creating openings for electronics-native suppliers.
Centrifugal blower designs are decomposing the legacy axial fan monopoly in seat ventilation modules. Tier-1 seating integrators specify compact centrifugal architectures for improved pressure head in multi-layer foam substrates. This decomposing shift enables thinner seat profiles while maintaining airflow velocity, compressing packaging constraints that previously limited fitment to full-size luxury platforms.
EU REACH restrictions on methylene diphenyl diisocyanate foam blowing agents are forcing polyurethane formulation changes across European supply chains. Seating manufacturers reformulate foam substrates to maintain permeability rates without restricted chemical catalysts. German and French OEM programs are most affected, with trim suppliers accelerating water-blown foam qualification timelines to maintain program compliance.
Fleet procurement of ventilated seats as standalone options rather than bundled luxury packages is disrupting traditional equipment-group economics. Commercial and rental vehicle operators specify climate seating à la carte to differentiate driver retention in high-turnover segments. This unbundling is most visible in United States commercial light-truck configurations, where upfitters now source blower modules directly from tier-1 integrators bypassing OEM captive supply.
Automotive Ventilated Seats Market Segmentation
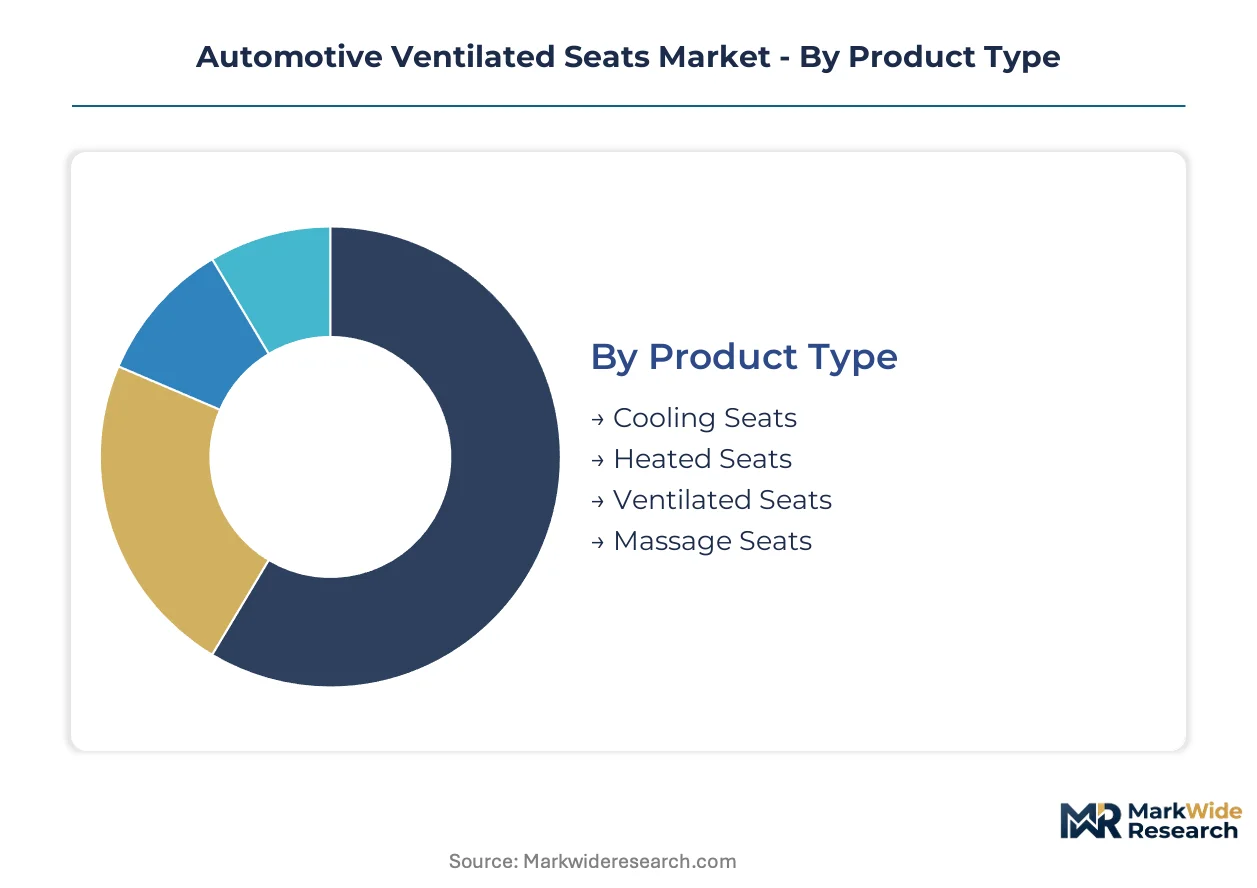
Segmentation in automotive ventilated seats reveals how thermal comfort technologies fragment across price-performance tiers, with substitution dynamics between active and passive cooling architectures reshaping supplier priorities. Understanding these divisions exposes where module economics compress and where premium capture endures.
Product Type:
Peltier thermoelectric modules exert the strongest substitution pressure on pure ventilation architectures, forcing segment positioning around active versus passive thermal management trade-offs.
- Ventilated Seats:Perforated trim surfaces coupled with axial or centrifugal blowers draw conditioned cabin air through foam substrates. United States luxury and mid-tier nameplates concentrate demand here as NHTSA thermal stress guidelines establish baseline performance requirements without mandating active cooling.
- Cooling Seats:Convection-based forced-air systems dominate volume production for their 5W-15W power draw, protecting vehicle range budgets under EPA fuel-efficiency standards while delivering adequate thermoregulation in ambient conditions below 30°C.
- Heated Seats:Resistive wire or carbon fiber heating elements embedded in seat cushions and backrests serve cold-climate markets with simpler electronics and lower functional safety certification burdens than blower modules.
- Massage Seats:Pneumatic bladder systems with compressor-driven lumbar and thigh pressure cycles command price premiums in executive vehicle configurations where wellness positioning justifies higher per-unit economics.
Ventilated seats retain volume leadership; cooling seats hold the steepest expansion curve as mid-tier OEM fitment accelerates.
End User:
Channel economics diverge sharply between captive OEM supply and aftermarket replacement, with margin structures reflecting warranty coverage and installation complexity.
- OEMs:Original equipment manufacturers specify blower modules through tier-1 seating integrators, with program volumes tied to vehicle platform lifecycle commitments spanning 6-8 years. ASIL-rated blower control firmware requirements favor electronics-capable suppliers.
- Aftermarket Providers:Independent distributors and retrofit specialists target aging vehicle fleets beyond warranty periods, sourcing blower modules and trim replacement kits directly from component manufacturers.
- Distributors:Regional parts wholesalers aggregate demand across multiple service channels, competing on inventory velocity and technical support for blower module installation.
- Dealerships:Authorized service networks capture warranty-period repairs and factory-option upgrades, maintaining OEM-specified module sourcing and diagnostic equipment.
OEMs dominate revenue concentration; aftermarket providers are expanding most quickly as fleet age extends replacement cycles.
Material:
Surface permeability and durability expectations drive material selection, with regulatory constraints on chemical catalysts reshaping foam substrate formulations.
- Leather:Perforated genuine hides command premium positioning in luxury configurations, with forced-air distribution extending surface lifespan by reducing perspiration-induced degradation in high-humidity climates.
- Synthetic:Polyurethane and PVC alternatives offer cost-adjusted permeability with consistent perforation quality, gaining share in mid-tier nameplates where leather economics compress.
- Mesh:Open-weave textile structures maximize airflow velocity with minimal blower power draw, appearing in performance-oriented seating where weight reduction parallels thermal efficiency.
- Fabric:Woven textile surfaces with laser-perforated patterns serve economy segments, though foam substrate integration challenges limit airflow uniformity compared to dedicated mesh constructions.
Leather maintains price-premium leadership; synthetic materials are gaining share fastest as mid-tier fitment broadens.
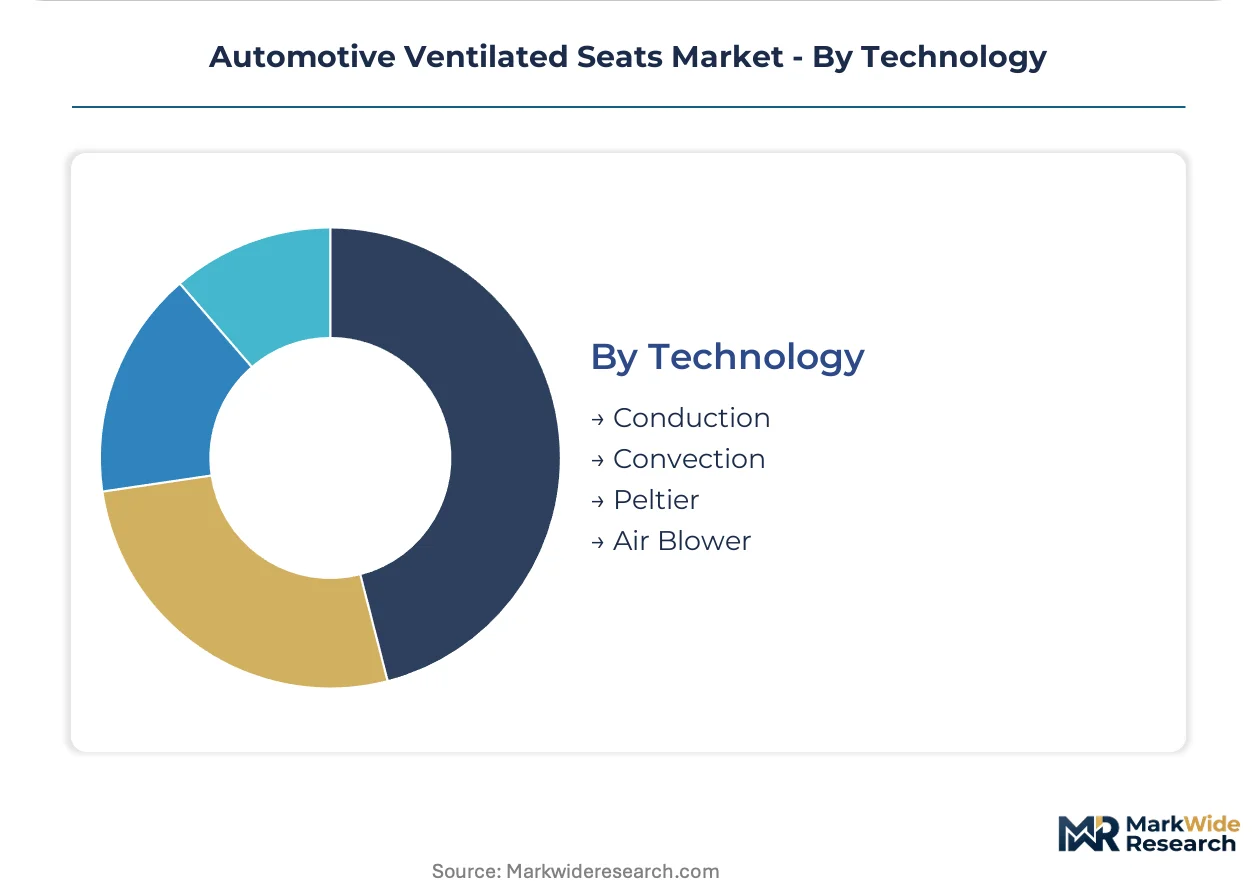
Technology:
Thermal transfer mechanisms segment by energy consumption, response latency, and functional safety certification intensity.
- Air Blower:Centrifugal and axial fan architectures displace legacy systems, with compact pressure-head designs enabling thinner seat profiles while maintaining airflow through multi-layer foam substrates.
- Peltier:Thermoelectric modules enable active temperature modulation below ambient conditions, commanding higher per-unit value in executive vehicle segments where thermoelectric substitution threatens pure ventilation.
- Convection:Passive air circulation through perforated trim relies on cabin HVAC conditioning, limiting independent thermal control but minimizing electrical load and certification complexity.
- Conduction:Direct contact cooling through gel or phase-change materials appears in niche applications, constrained by response latency and seating position sensitivity.
Air blower systems retain volume leadership; Peltier modules command the steepest value expansion as active cooling penetrates premium configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA fuel-efficiency standards and NHTSA thermal comfort guidelines are accelerating blower module adoption across the United States, while EU REACH foam regulations and China's GB electrical standards reshape supplier compliance requirements in their respective jurisdictions.
United States
Commercial fleet operators specify ventilated seats à la carte for driver retention in high-turnover segments, particularly in light-truck upfit configurations. NHTSA guidelines on occupant thermal stress establish baseline blower performance requirements without mandating active cooling. Detroit-area seating integrators absorb ASIL-rated blower control electronics into module architectures to meet functional safety mandates.
Germany
Luxury OEMs extend ventilated seat fitment into mid-tier nameplates, broadening addressable platforms beyond executive vehicle segments. EU REACH restrictions on methylene diphenyl diisocyanate foam blowing agents force polyurethane formulation changes across supply chains. Stuttgart and Munich clusters accelerate water-blown foam qualification timelines to maintain program compliance.
China
Domestic OEM supply chains favor locally produced fan modules meeting GB standards for automotive electrical subsystems, including motor efficiency and electromagnetic compatibility requirements. MIIT industrial policy supports component localization for climate seating systems. Yangtze River Delta manufacturing bases scale centrifugal blower production for Asian platform fitment.
Japan
OEMs integrate seat climate modules into platform lifecycle commitments spanning 6-8 years, favoring vertically controlled supply chains. METI energy efficiency guidelines influence blower power draw specifications below 15W. Nagoya-area seating specialists maintain captive foam, trim, and fan module production for just-in-time delivery.
South Korea
Hyundai-Kia platform expansion drives tier-1 seating integrator procurement for ventilated seat modules across volume and premium nameplates. MFDS automotive component standards align with international functional safety frameworks. Seoul Capital Area electronics suppliers develop blower control firmware for ASIL-rated architectures.
Automotive Ventilated Seats Market Vendor Landscape
Player mix skews toward integrated seating systems specialists with captive electronics capability, compressing the addressable market for component-only suppliers. Three archetypes dominate: tier-1 seating integrators controlling foam-through-fan vertical production, thermal management specialists with proprietary blower and Peltier IP, and diversified automotive suppliers leveraging seat structure integration. Competitive moves concentrate on ASIL-D firmware development partnerships and centrifugal blower architecture transitions displacing legacy axial systems.
Within the tier-1 integrator tier, Toyota Boshoku Corporation and Magna International exemplify divergent geographic anchoring strategies. Toyota Boshoku represents Asian OEM supply chain dominance through vertically controlled production ecosystems. Magna International occupies a position bridging North American and European platform requirements with integrated seat structure and electronics capability. Gentherm Incorporated sits within the thermal management specialist archetype, anchoring premium-tier positioning through proprietary IP spanning convection and thermoelectric architectures.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Magna International Inc. |
| Lear Corporation |
| NHK Spring Co. Ltd. |
| TS Tech Co. Ltd. |
| Adient PLC |
| Gentherm Incorporated |
| Brose Fahrzeugteile GmbH |
| Faurecia SE |
| Others |
Supply Flow & Price Mechanics
Long-term program contracts with tier-1 seating integrators lock in blower module allocation and cost visibility across multi-year vehicle platform lifecycles, insulating OEMs from polyurethane foam feedstock volatility while embedding ASIL-rated electronics premiums into fixed pricing schedules.
Pricing Analysis
Certification level creates the primary spread between module tiers, with ASIL-D qualified blower control systems commanding substantial premiums over unrated alternatives in OEM procurement. Three-tier pricing structure separates executive vehicle Peltier-hybrid configurations from mid-tier pure ventilation systems and economy-grade heated-only alternatives. Cost compression in mid-tier ventilation modules is intensifying as centrifugal blower architectures displace legacy axial systems and Chinese GB-standard fan motors enter Asian supply chains. Fleet operators and commercial upfitters exhibit the highest price sensitivity, while luxury OEMs prioritize thermal performance over per-unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for European seating manufacturers sourcing fan motors and control electronics from Yangtze River Delta production bases. Module assembly concentrates in China, Germany, and Japan, with each hub serving distinct regional OEM clusters through localized GB, REACH, and METI compliance pathways. Critical dependencies include rare-earth elements for Peltier thermoelectric modules, petrochemical-derived polyurethane foam substrates, and semiconductor components for blower control firmware. Single-source vulnerability in ASIL-rated microcontroller supply creates qualification bottlenecks. Distribution runs through captive tier-1 integrator channels for OEM fitment, with aftermarket modules bypassing to independent distributors and fleet upfitters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket blower module replacement and trim refurbishment services are expanding faster than original equipment hardware as vehicle fleets age beyond warranty coverage, creating recurring revenue attach opportunities for service-channel operators.
For Market Incumbents: Compound defensive positioning through backward integration into ASIL-rated blower control firmware development and captive centrifugal blower manufacturing capacity in Yangtze River Delta clusters. Peltier thermoelectric substitution threatens pure ventilation architectures in premium configurations; counter by accelerating hybrid convection-thermoelectric qualification timelines for executive vehicle programs. Prioritize long-term platform commitments with Detroit and Stuttgart OEMs to lock out electronics-native entrants. For New Entrants and Emerging Players: Differentiate on aftermarket retrofit specialization targeting aging United States commercial light-truck fleets beyond warranty periods, where upfitters source modules directly and bypass OEM captive supply. Target distributor relationships in high-turnover fleet segments where driver retention justifies standalone climate seating procurement. Pursue white-label blower module supply agreements with regional parts wholesalers lacking technical integration capability. For Investors and Strategic Acquirers: Electronics-capable tier-2 seating specialists with ASIL-D firmware development teams and established Asian OEM relationships represent the most defensible acquisition archetype for platform standardization cycles. Long-term viability hinges on convergence toward active thermal management modules displacing passive ventilation. Watch for centrifugal blower architecture transitions displacing legacy axial systems as the inflection signal for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Firmware Development Partnership | Functional safety qualification collapses supplier base, favoring electronics-native integrators over traditional seating specialists. |
| Centrifugal Blower Architecture Transition | Compact pressure-head designs enable thinner seat profiles, expanding fitment from full-size luxury to mid-tier vehicle platforms. |
| Water-Blown Foam Formulation Qualification | EU REACH methylene diphenyl diisocyanate restrictions force polyurethane substrate changes across German and French supply chains. |
| Aftermarket Retrofit Channel Expansion | Fleet operators specify climate seating à la carte, creating direct procurement relationships bypassing OEM captive supply. |
| Hybrid Convection-Peltier Module Convergence | Dual-architecture seats capture price premiums in executive segments where active cooling displaces pure ventilation. |
Methodological Framework
Initial hypotheses were tested against primary input from tier-1 seating integrator procurement directors, OEM platform engineers, aftermarket distributor operations managers, and blower module firmware developers, then refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC supplier filings, and NHTSA thermal stress guideline documentation. Bottom-up module shipment estimates were triangulated with top-down OEM platform fitment assumptions across the analysis window.
Variance decomposition across product type, vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions informed segment-level growth trajectories. CAGRs were derived from fitted trend lines applied to historical fitment rates and projected platform volumes. Forecast inputs incorporated EPA fuel-efficiency standard stringency trajectories, ISO 26262 functional safety adoption curves, and regional thermal comfort regulation enforcement patterns without specifying implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained mid-tier nameplate expansion, stable petrochemical feedstock pricing, and continued NHTSA guideline adherence would require recalibration. Forecasts reflect documented assumptions regarding blower power draw reduction targets, Peltier thermoelectric cost curves, and aftermarket channel development velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market