
 Automotive Solar Film Market | 2026-2036
Automotive Solar Film Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Solar Film Market Analysis
Ceramic nanoparticle formulations is consolidating market share against traditional dyed and metalized alternatives in premium automotive glazing applications. Eastman Chemical Company leverages its polyester substrate expertise to sustain supply relationships with major OEM tinting programs. Saint-Gobain anchors European production capacity through its specialized glass and film manufacturing footprint. Johnson Window Films competes aggressively in the North American aftermarket channel with broad installer network coverage.
Automotive solar film constitutes a multi-layered polymer laminate engineered to reject infrared radiation, block ultraviolet transmission below 400 nanometers, and reduce visible light penetration while preserving optical clarity for driver visibility. Ceramic variants embed non-conductive titanium nitride or indium tin oxide nanoparticles within adhesive interlayers to achieve thermal rejection without electromagnetic interference. Ceramic film commands the fastest expansion trajectory across passenger vehicle applications due to superior heat rejection performance and compatibility with embedded antenna systems. Aftermarket providers represent the most fragmented end-user channel with distributed margin pools, while OEM direct supply agreements concentrate volume among a narrower supplier base with stricter qualification protocols.
The US EPA oversees volatile organic compound emissions from solvent-based adhesive processes used in film manufacturing, while Europe's REACH framework restricts certain phthalate plasticizers and heavy metal pigments in automotive interior materials. Japan's METI promotes energy-efficient vehicle standards that incentivize solar heat load reduction through certified glazing treatments. Stakeholders must monitor evolving chemical substance restrictions and OEM certification timelines to secure positioning in increasingly regulated supply chains.
Market Dynamics
Ceramic nanoparticle formulations are compressing traditional dyed and metalized film margins as OEMs prioritize thermal rejection performance compatible with embedded antenna systems and advanced driver assistance sensors.
Growth Catalysts
- Electric vehicle thermal management:Battery thermal load reduction requirements in EV manufacturing are expanding factory-applied tinting programs. OEM procurement volumes concentrate among qualified suppliers with validated adhesive chemistries.
- REACH chemical compliance:Europe's tightened restrictions on phthalate plasticizers and heavy metal pigments are accelerating formulation upgrades toward compliant ceramic interlayers. Manufacturers with pre-certified material stacks capture preferred supplier status.
- Stuttgart-Munich supplier corridor:Germany's automotive engineering density creates concentrated demand for high-performance glazing treatments. Regional film converters benefit from proximity to major OEM technical centers.
Market Restraints
- Polyester substrate concentration:Specialized biaxially-oriented polyester film supply concentrates among limited chemical conglomerates with film-grade resin capacity. Input cost volatility transmits directly to laminate converters.
- Solvent emission compliance:US EPA volatile organic compound regulations on adhesive drying processes impose capital-intensive abatement equipment requirements. Smaller coating operations face facility upgrade thresholds.
- Metalized film electromagnetic interference:Conductive aluminum layers in legacy metalized films disrupt GPS, cellular, and toll transponder signals. This technical limitation constrains retrofit penetration in sensor-dense vehicle architectures.
Strategic Opportunities
- India vehicle parc expansion:Rising passenger vehicle ownership in high-ambient-temperature climates creates aftermarket white space for heat-rejection films. Distribution partnerships with domestic automotive accessory chains enable channel access.
- Photovoltaic-integrated glazing:Convergence of solar film thermal rejection with transparent photovoltaic cell interlayers enables dual-function automotive glass. Early development partnerships with glass laminators secure positioning.
- METI energy efficiency certification:Japan's vehicle thermal load reduction incentives create regulatory tailwind for certified glazing treatments. Compliance documentation supports OEM specification and consumer subsidy eligibility.
Industry Challenges
- OEM qualification timelines:Automotive supplier certification protocols require 18-36 month validation cycles for adhesive outgassing, optical clarity retention, and weathering performance. Extended approval windows strain working capital for film manufacturers.
- Skilled coating technicians:Precision slot-die and gravure coating operations for nanoscale ceramic dispersion require specialized process engineering expertise. Talent scarcity in thin-film manufacturing regions elevates labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Solar Film Market |
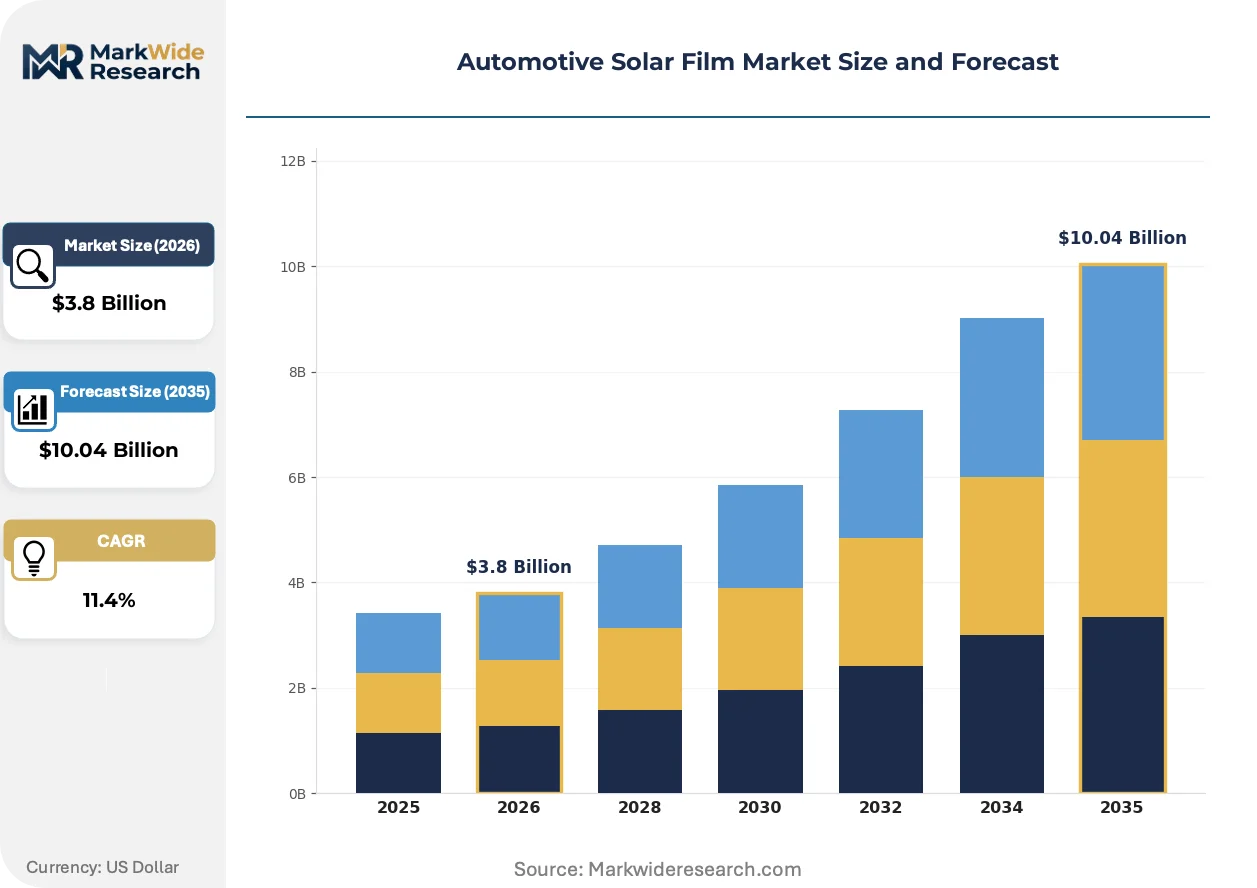
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Dyed Film, Metalized Film, Ceramic Film, Clear Film Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Automotive Dealers Features: UV Protection, Heat Rejection, Privacy, Fade Resistance |
| Companies Covered | 3M, Eastman Chemical Company, Saint-Gobain, Avery Dennison Corporation, Johnson Window Films, Toray Industries, Lintec Corporation, Honeywell International, XPEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Solar Film Market Emerging Trajectories
Formulation chemistry and application methods are advancing simultaneously as manufacturers respond to stricter material regulations and OEM performance specifications. Three developments are restructuring competitive positioning.
Sputtered ceramic nanoparticle films embed non-conductive titanium nitride or indium tin oxide within adhesive interlayers to achieve infrared rejection without signal attenuation. Premium passenger vehicle segments are adopting these formulations fastest, particularly for panoramic roof and windshield applications where metalized alternatives fail. The technology is expanding into mid-range vehicle trims as coating scale economies reduce unit costs.
Europe's F-Gas Regulation restricts fluorinated greenhouse gases used in certain film manufacturing solvent recovery systems, forcing process reengineering toward aqueous or supercritical carbon dioxide alternatives. Industrial consequence includes accelerated capital expenditure cycles for coating facilities serving EU automotive supply chains. German and French film converters are responding fastest with abated production lines to maintain OEM supply eligibility.
Fleet operators and lease management companies are consolidating aftermarket purchasing through direct national distribution agreements, bypassing traditional installer networks. This channel compression squeezes margin pools for regional tint shops while concentrating volume with large-format film distributors. The pattern is most visible in North American commercial vehicle and rental fleet segments where standardized specification reduces procurement complexity.
Automotive Solar Film Market Segmentation
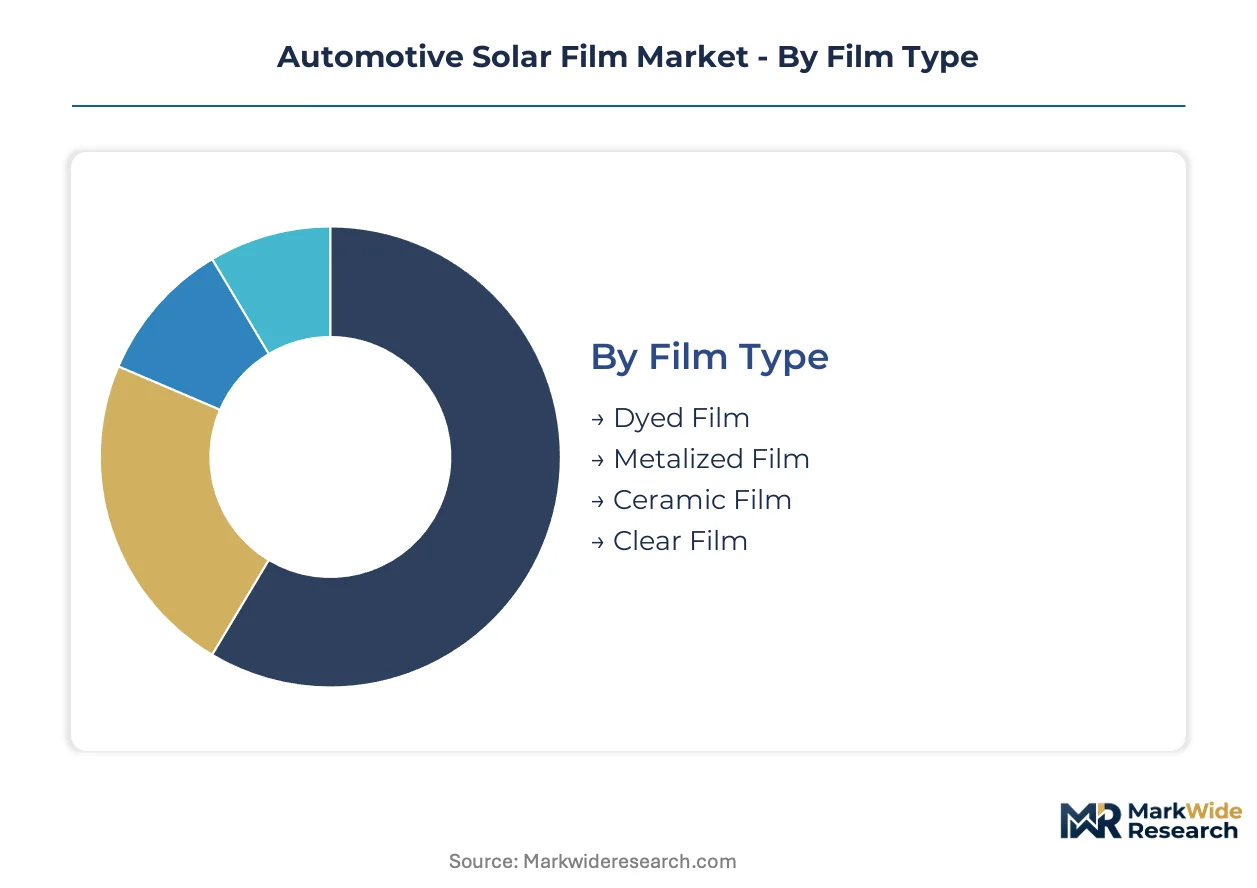
Automotive solar film segments diverge sharply across thermal performance specifications, installation channels, and regulatory compliance tiers. Understanding these divides reveals where formulation investments concentrate and which customer relationships command premium positioning.
Film Type:
Ceramic nanoparticle engineering now defines the performance frontier against legacy metallization and dye-based alternatives.
- Ceramic Film:Non-conductive titanium nitride or indium tin oxide nanoparticles embedded in adhesive interlayers achieve infrared rejection without electromagnetic interference. OEM tinting programs for electric vehicles in Germany's Stuttgart-Munich corridor specify ceramic formulations to preserve embedded antenna and sensor functionality.
- Metalized Film:Vacuum-deposited aluminum layers provide cost-efficient thermal rejection but disrupt GPS, cellular, and toll transponder signals. Demand concentrates in price-sensitive aftermarket channels where vehicle sensor density remains lower.
- Dyed Film:Organic colorants absorb solar energy without metallic conductivity, offering basic glare reduction at entry price points. UV degradation limits lifespan in high-ambient-temperature climates.
- Clear Film:UV-blocking transparent laminates preserve factory glass appearance while meeting regulatory transparency minimums. Japan's METI energy efficiency certification incentivizes clear-film specifications for windshield applications.
Mature deployment sits with dyed and metalized films in legacy aftermarket channels. Newer deployment is concentrated in ceramic formulations for OEM electric vehicle programs.
Application:
Vehicle architecture determines glazing surface area and thermal load management requirements.
- Passenger Vehicles:Panoramic roof expansions and larger windshield geometries multiply film surface requirements per unit. Ceramic specifications climb fastest in premium and mid-range electric vehicle trims.
- Commercial Vehicles:Fleet operators consolidate procurement through national distribution agreements, bypassing traditional installer networks. Standardized specifications reduce procurement complexity across rental and logistics segments.
- Motorcycles:Limited windshield and visor surface area constrains revenue per unit. Aftermarket accessory chains in high-temperature Asian markets drive regional volume.
- Heavy-Duty Vehicles:Extended cab configurations and sleeper compartments create multi-zone tinting requirements. Operator comfort regulations in certain jurisdictions mandate heat-load reduction for long-haul configurations.
Volume concentration aligns with passenger vehicle production scale. Margin expansion concentrates in commercial fleet direct agreements.
End User:
Channel structure fragments between concentrated OEM supply and distributed aftermarket installation.
- OEMs:Factory-applied tinting programs require 18-36 month adhesive validation cycles for outgassing, optical clarity retention, and weathering performance. Qualified supplier status concentrates volume among narrow certified bases.
- Aftermarket Providers:Regional tint shops and mobile installers compete on installation speed and warranty terms. Margin pools compress as fleet operators consolidate purchasing through direct distribution.
- Vehicle Assemblers:Contract manufacturing arrangements for specialty and low-volume vehicle configurations create secondary OEM-like demand with modified qualification protocols.
- Automotive Dealers:Pre-delivery tinting packages generate accessory revenue with higher margin capture than factory-installed alternatives. Dealer network coverage determines regional market penetration.
Procurement leverage concentrates with OEMs and fleet aggregators. Aftermarket providers compete on installation density and customer acquisition cost efficiency.
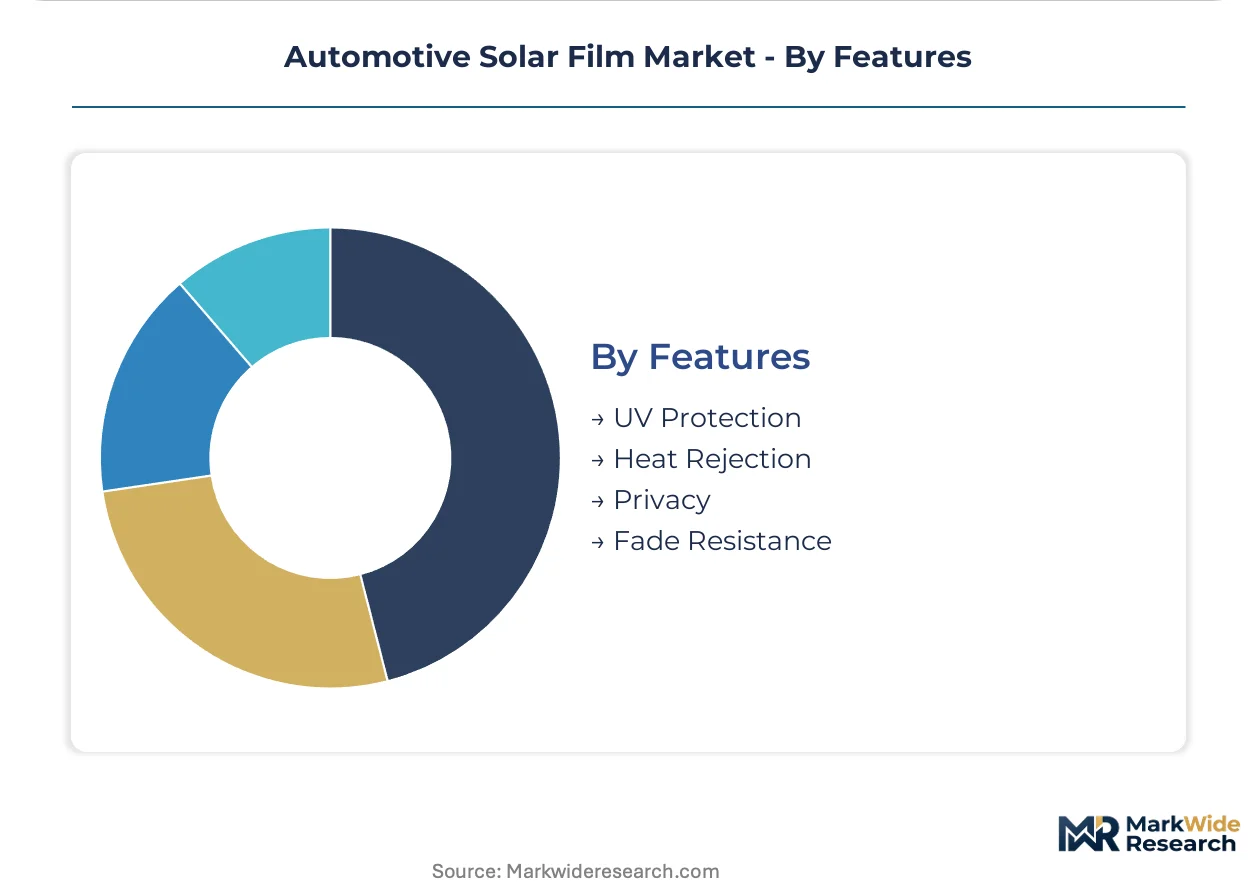
Features:
Performance specifications segment across thermal, optical, and durability axes.
- Heat Rejection:Infrared blocking above 900 nanometers defines premium tiering. Ceramic nanoparticle density correlates directly with thermal performance ratings and price positioning.
- UV Protection:Sub-400 nanometer blocking is now baseline across all film categories. Differentiation shifts to UV-A spectrum coverage and degradation resistance.
- Privacy:Visible light transmission below 20% creates occupant concealment but triggers regulatory compliance thresholds for front-side and windshield applications.
- Fade Resistance:Organic dye stabilization and adhesive UV absorbers extend optical clarity retention. Warranty terms differentiate premium from economy positioning.
Heat rejection commands the steepest expansion trajectory as electric vehicle thermal management requirements intensify. UV protection has commoditized across price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive solar film concentrates in manufacturing corridors where electric vehicle assembly and premium glazing specifications intersect. Germany's Stuttgart-Munich corridor anchors European volume, while regulatory pressure across multiple jurisdictions reshapes supplier qualification requirements.
Germany
OEM tinting programs for electric vehicles at Porsche, Mercedes-Benz, and BMW assembly plants drive procurement concentration. ECHA's REACH framework restricts phthalate plasticizers and heavy metal pigments in automotive interior materials. The Stuttgart-Munich supplier corridor hosts specialized film converters with direct technical center access.
United States
Fleet operator consolidation in commercial vehicle and rental segments compresses aftermarket channel margins. EPA volatile organic compound regulations on adhesive drying processes impose capital-intensive abatement equipment requirements. Southeast manufacturing zones attract coating operations seeking lower facility upgrade thresholds.
China
Domestic electric vehicle production scale multiplies factory-applied tinting program volumes. MIIT energy-efficient vehicle standards incentivize solar heat load reduction through certified glazing treatments. Yangtze River Delta automotive clusters concentrate demand for ceramic nanoparticle formulations.
Japan
METI energy efficiency certification creates regulatory tailwind for thermal load reduction technologies. Premium passenger vehicle segments adopt ceramic formulations fastest for panoramic roof applications. Kanto region technical centers validate adhesive outgassing and optical clarity retention protocols.
India
Rising passenger vehicle ownership in high-ambient-temperature climates creates aftermarket white space. BIS standards for automotive glazing materials establish baseline compliance requirements. Maharashtra and Gujarat automotive manufacturing zones concentrate distribution partnerships with domestic accessory chains.
Automotive Solar Film Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM direct supply agreements concentrating volume among narrow certified bases while aftermarket channels fragment across regional installer networks. The vendor base organizes into three archetypes: polyester substrate specialists with resin-grade capacity, ceramic formulation innovators, and broad-line coating converters serving mixed channels. M&A activity targets adhesive chemistry capabilities, while capacity expansion concentrates in abated coating facilities serving EU automotive supply chains.
Within the substrate-specialist tier, Eastman Chemical Company leverages polyester film expertise to sustain OEM supply relationships. Saint-Gobain anchors European production capacity through specialized manufacturing footprints. Johnson Window Films occupies a position in North American aftermarket channels with installer network coverage. These three exemplify how material science depth, geographic production positioning, and channel access differentiation separate sustainable competitive positions from commodity coating operations.
| Leading Market Players |
|---|
| 3M |
| Eastman Chemical Company |
| Saint-Gobain |
| Avery Dennison Corporation |
| Johnson Window Films |
| Toray Industries |
| Lintec Corporation |
| Honeywell International |
| XPEL |
| Others |
Supply Flow & Price Mechanics
Biaxially-oriented polyester resin costs transmit directly from Eastman Chemical and Toray Industries through to laminate converters, with film-grade capacity concentration in the US, Japan, and South Korea determining input pricing power across premium, standard, and economy ceramic and metalized film tiers.
Pricing Analysis
Volume concentrates in OEM direct supply agreements with compressed margins and 18-36 month qualification cycles, while aftermarket channels fragment margin pools across regional installer networks. Price differentiation hinges on ceramic nanoparticle density and REACH pre-certification status, with OEM-specified thermal rejection grades commanding premium positioning. Cost compression in metalized and dyed tiers intensifies as fleet operators consolidate national purchasing agreements. Aftermarket providers show highest price sensitivity; OEM procurement teams prioritize performance compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart-Munich electric vehicle assembly plants, while aftermarket distribution runs through domestic accessory chains and mobile installer networks in India and Southeast Asia. Raw material supply draws from biaxially-oriented polyester resin producers in the US, Japan, and South Korea, plus ceramic nanoparticle specialists in Germany and China. Solvent-based adhesive chemistry rests on petrochemical feedstocks vulnerable to volatility. Single-source vulnerability concentrates in film-grade polyester substrate capacity. Regional converter operations in Germany, China, and the US dominate downstream laminate production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive solar film is consolidating toward REACH-compliant ceramic specialists as ECHA chemical restrictions and OEM qualification barriers force undifferentiated metalized and dyed film producers toward exit or acquisition.
For Market Incumbents: Acquire ceramic nanoparticle formulation capabilities and REACH-certified adhesive chemistry to defend against sputtered film specialists displacing legacy metalized supply relationships. Backward integration into polyester substrate sourcing reduces exposure to Eastman-Toray pricing power. Prioritize abated coating capacity expansion in Germany to maintain OEM eligibility under F-Gas Regulation solvent recovery mandates. For New Entrants and Emerging Players: Enter via distribution partnerships with domestic automotive accessory chains in Maharashtra and Gujarat, where rising passenger vehicle ownership in high-ambient-temperature climates creates aftermarket white space for heat-rejection films. Target commercial fleet direct agreements in North America, where procurement consolidation bypasses traditional installer networks and rewards standardized specification capability. For Investors and Strategic Acquirers: OEM qualification timeline compression is the leading indicator that working capital-efficient ceramic formulation specialists will outcompete capital-constrained coating operations. The 5-10 year viability window favors targets with pre-certified material stacks and existing technical center relationships in Germany or Japan. Watch for ECHA substance restriction announcements as inflection signals for formulation upgrade investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Formulation Patent Portfolio Acquisition | Secures non-conductive titanium nitride dispersion IP against sputtered film competitors in OEM channels. |
| REACH Pre-Certified Adhesive Chemistry Investment | Accelerates 18-36 month OEM validation cycles for European electric vehicle tinting programs. |
| Abated Coating Facility Expansion in Germany | Maintains supply eligibility under F-Gas Regulation solvent recovery requirements for Stuttgart-Munich OEM corridor. |
| India Distribution Partnership with Accessory Chains | Captures aftermarket volume in high-ambient-temperature climates with rising passenger vehicle ownership. |
| Fleet Operator Direct Supply Agreement | Bypasses fragmented installer networks and concentrates volume with consolidated commercial vehicle purchasers. |
Methodological Framework
Multi-period observation of OEM tinting program procurement volumes, REACH compliance certification timelines, and ceramic nanoparticle adoption rates anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Secondary validation drew from vehicle production databases, ECHA substance restriction notifications, EPA volatile organic compound regulatory filings, and customs trade data for polyester film imports. Bottom-up triangulation across converter facility capacity and top-down cross-check against electric vehicle assembly forecasts ensured methodological rigor.
Input-output matrix modeling connected biaxially-oriented polyester resin supply constraints, ceramic nanoparticle coating scale economies, and OEM qualification cycle durations to volume and value outputs across the projection horizon. Segmentation dimensions included film type, vehicle architecture, installation channel, and regional regulatory cluster. CAGRs derived from weighted scenario analysis across base, high, and low electric vehicle penetration assumptions. Industry-specific forecast inputs incorporated METI energy efficiency certification adoption curves and F-Gas Regulation compliance cost estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA substance bans or polyester resin supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market