
 Interior Materials for Pet-Friendly Vehicle Cabins Market | 2026-2036
Interior Materials for Pet-Friendly Vehicle Cabins Market Size, Share, and Industry Trends Forecast 2026-2036
Interior Materials for Pet-Friendly Vehicle Cabins Market Insights
NHTSA cabin safety standards for loose-object mitigation is pivoting supplier investment toward tether-integrated seat architectures. FORVIA leverages its seating systems expertise to develop pet-anchoring hardware embedded within factory seat frames. Adient sustains competitive pressure through dedicated R&D on claw-resistant synthetic surfaces. Lear Corporation anchors North American production capacity for odor-neutralizing headliner substrates.
Interior materials for pet-friendly vehicle cabins encompass engineered surfaces and structural components designed to resist abrasion, moisture ingress, and biological contamination while maintaining cabin air quality and crashworthiness parameters. These materials typically incorporate polyurethane-coated fabrics with tear strength exceeding automotive-grade standards, antimicrobial additives, and low-VOC substrates to satisfy cabin environment regulations. Synthetic fiber and thermoplastic olefin formulations lead material type demand due to their balance of cost efficiency and cleanability, while scratch resistance and waterproofing features command premium positioning within OEM specification sheets. Seat covers and cargo liners represent the fastest-growing application channels as manufacturers bundle pet-focused protection into trim packages.
EPA indoor air quality protocols and NHTSA occupant protection frameworks jointly constrain material selection, forcing substitution of legacy vinyl formulations with low-emission alternatives. ISO 12219 vehicle cabin air testing provides voluntary benchmarks that OEMs increasingly mandate for supplier qualification. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as these chemicals underpin existing stain-resistant coatings across multiple supplier portfolios.
Market Dynamics
OEM specification sheets now mandate tether-integrated seat architectures as NHTSA loose-object mitigation rules tighten, forcing material suppliers to redesign substrates around embedded anchoring hardware rather than treating pet protection as an aftermarket add-on.
Growth Catalysts
- EPA indoor air quality protocols:Low-VOC mandates accelerate substitution of legacy vinyl formulations with thermoplastic olefin alternatives that satisfy cabin environment testing.
- Synthetic fiber formulations:Polyurethane-coated fabrics with enhanced tear strength enable factory-fit pet-resistant packages to replace dealer-installed accessories.
- United States pet ownership concentration:Elevated vehicle customization spending in this market pulls OEM investment toward standardized pet-focused trim packages.
Market Restraints
- Per- and polyfluoroalkyl substance restrictions:State-level chemical bans threaten existing stain-resistant coating portfolios across multiple supplier lines.
- Antimicrobial additive costs:Silver-ion and copper-based treatments inflate raw material expenses beyond standard automotive-grade fabric pricing tiers.
- Crashworthiness certification delays:NHTSA occupant protection frameworks extend qualification timelines for novel seat-integrated tether systems.
Strategic Opportunities
- ISO 12219 voluntary benchmarks:OEMs increasingly mandate this vehicle cabin air testing for supplier qualification, creating certification service revenue streams.
- Headliner substrate innovation:Odor-neutralizing materials represent an underdeveloped application channel beyond seat covers and cargo liners.
- Direct-to-fleet partnerships:Rental and commercial vehicle operators seek bulk pet-resistant configurations outside traditional OEM distribution.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise spanning both automotive crashworthiness and pet-specific abrasion resistance remains concentrated among legacy seating suppliers.
- Dual certification timelines:Suppliers must simultaneously satisfy NHTSA occupant safety and EPA emissions testing, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interior Materials for Pet-Friendly Vehicle Cabins Market |
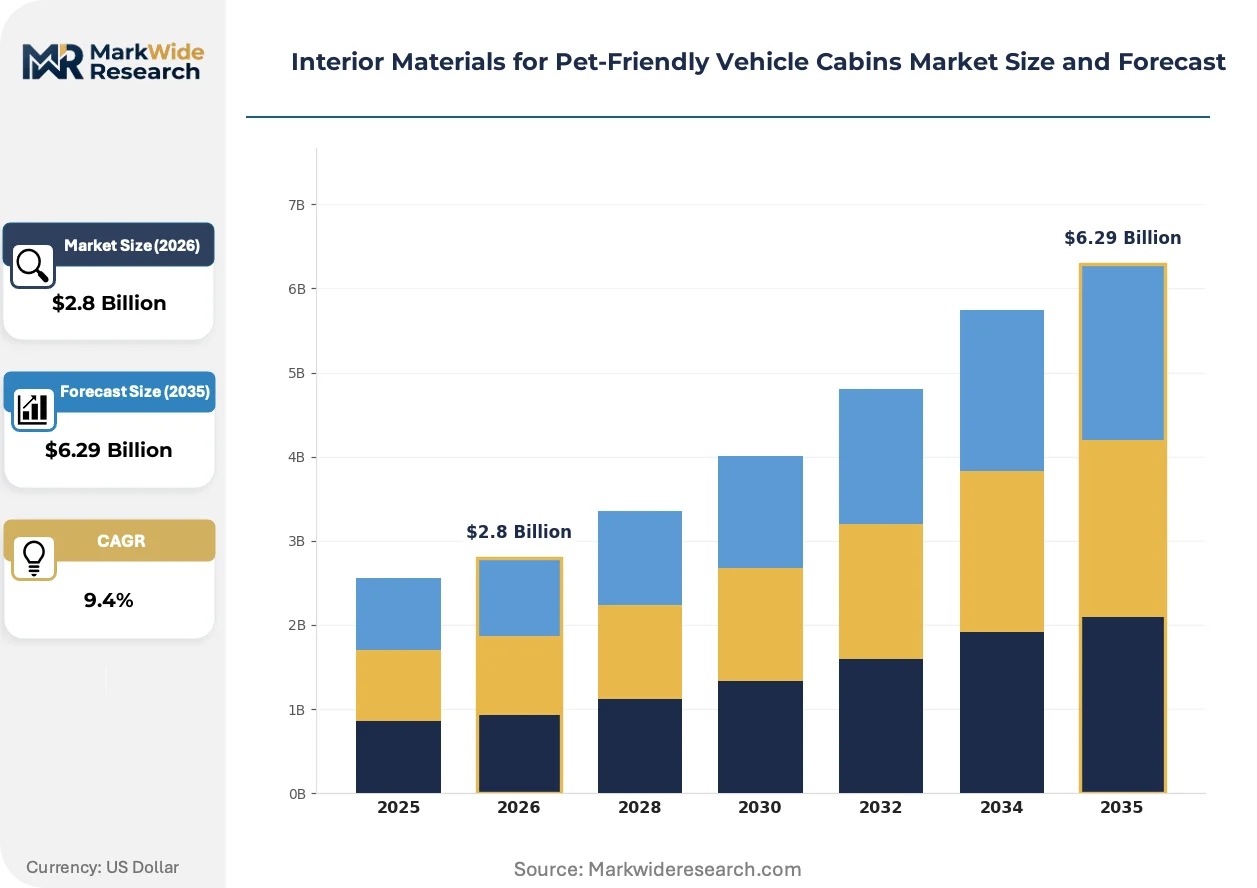
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Synthetic Fiber, Microfiber, Thermoplastic Olefin, Nylon, Polyester Application: Seat Covers, Floor Mats, Door Panels, Headliners, Cargo Liners, Dashboard Covers End User: OEMs, Aftermarket Suppliers, Vehicle Upholsterers, Fleet Operators, Pet Transport Services Feature: Scratch Resistance, Waterproofing, Odor Control, Easy Cleaning, UV Protection, Anti-Slip |
| Companies Covered | FORVIA, Adient, Lear Corporation, Yanfeng Automotive Interiors, Magna International, Grupo Antolin, Toyota Boshoku, Continental AG, Sage Automotive Interiors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interior Materials for Pet-Friendly Vehicle Cabins Market Trends and Innovations
Material science advances are compressing the gap between aftermarket durability and factory-grade aesthetics, with antimicrobial integration and embedded hardware redefining what constitutes standard cabin equipment rather than optional protection.
Self-healing polyurethane coatings are integrating nano-capsule repair mechanisms that activate upon claw-induced micro-tearing. Luxury SUV and electric vehicle segments are adopting these surfaces at the fastest clip as OEMs seek differentiation through warranty-backed durability claims. This technology is integrating factory seat production lines previously reserved for human-occupant-only designs, collapsing the distinction between pet-resistant and standard trim tiers.
REACH restrictions on persistent organic pollutants are forcing European suppliers to reformulate stain-resistant chemistries ahead of anticipated EPA alignment. The industrial consequence is a supplier qualification bottleneck as testing laboratories face backlog for alternative coating validation. Seat cover manufacturers serving export markets are most affected, with many accelerating dual-formulation strategies to maintain cross-border shipment eligibility.
Fleet procurement departments are consolidating vendor relationships around full-cabin protection packages rather than component-level sourcing. Automotive leasing companies now specify pet-resistant materials as residual value protection, displacing the traditional aftermarket accessory channel. This concentration is most visible in the United States, where commercial fleet operators represent the fastest-growing contract volume for factory-installed cargo liner systems.
Interior Materials for Pet-Friendly Vehicle Cabins Market Segmentation
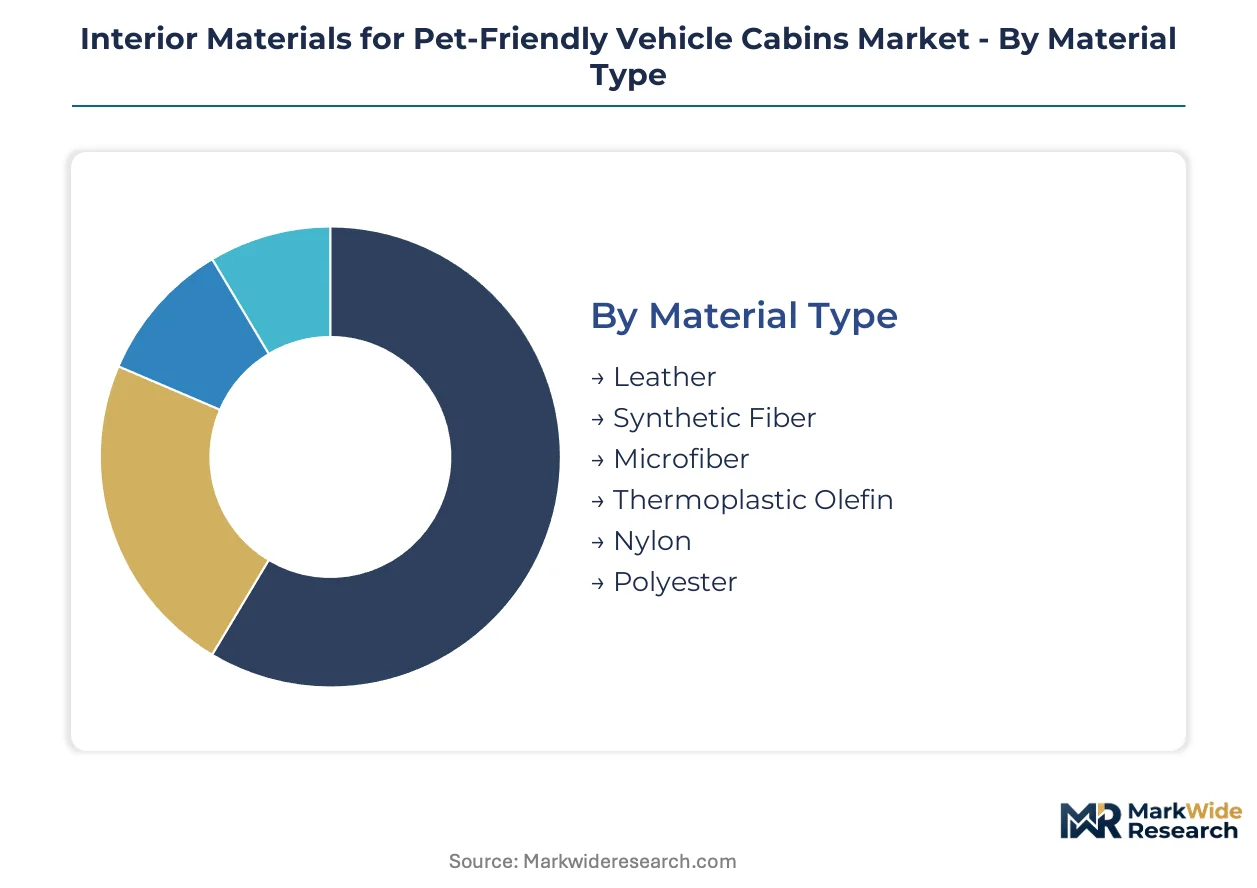
Interior materials for pet-friendly vehicle cabins fragment across four distinct axes that reshape procurement patterns. Material chemistry determines factory qualification timelines. Application placement dictates crashworthiness certification pathways. End-user channel structure governs margin capture and inventory velocity.
Material Type:
Material chemistry separates legacy upholstery from next-generation pet-resistant formulations, with coating architecture and fiber density defining OEM acceptance thresholds.
- Thermoplastic Olefin:Low-VOC thermoplastic olefin substrates satisfy EPA indoor air quality protocols while delivering tear strength exceeding legacy vinyl benchmarks. Demand concentrates among Detroit Three automakers integrating factory-fit pet packages into SUV and truck platforms, constrained by polymer compounding capacity expansion timelines.
- Synthetic Fiber:Polyurethane-coated synthetic fiber formulations enable embedded antimicrobial treatments without compromising abrasion resistance metrics. Adoption is accelerating fastest among electric vehicle manufacturers seeking differentiation through warranty-backed durability claims.
- Leather:Full-grain and corrected-grain leather variants with ceramic-infused topcoats resist claw penetration while maintaining luxury tactile properties.
- Microfiber:Ultra-fine denier polyester-polyamide blends offer cost-efficient cleanability for aftermarket conversion specialists.
- Nylon:High-tenacity nylon 6,6 formulations anchor cargo liner applications requiring puncture resistance.
- Polyester:Recycled-content polyester substrates serve sustainability-mandated fleet procurement specifications.
Mature deployment sits with leather and nylon in premium SUV segments. Newer deployment is concentrated in thermoplastic olefin as OEMs phase out vinyl formulations under tightening emissions testing.
Application:
Application placement determines whether materials face NHTSA occupant safety scrutiny or aftermarket durability standards alone.
- Seat Covers:Tether-integrated seat cover architectures embed anchoring hardware directly into factory seat frames, requiring simultaneous NHTSA crashworthiness and EPA emissions certification. Detroit Three production lines are absorbing these configurations fastest as loose-object mitigation rules tighten.
- Cargo Liners:Thermoformed cargo liner systems with raised edge containment and anti-slip substrates protect residual values for commercial leasing fleets. Fleet procurement departments in the United States are consolidating vendor relationships around full-cabin protection packages.
- Floor Mats:Deep-channel rubberized floor mats with retention clip compatibility address liquid containment without interfering with pedal operation.
- Door Panels:Abrasion-resistant door panel inserts protect high-contact zones from paw scratching and window operation.
- Headliners:Odor-neutralizing headliner substrates represent an underdeveloped channel with concentrated R&D investment from Lear Corporation.
- Dashboard Covers:UV-stabilized dashboard covers prevent material degradation from sun exposure through windshields.
Seat covers command the steepest expansion trajectory as factory integration displaces dealer-installed accessories. Dashboard covers remain predominantly aftermarket due to airbag deployment compatibility testing requirements.
End User:
End-user channel structure fragments between specification authority and installation responsibility, with divergent margin and volume profiles.
- OEMs:Original equipment manufacturers mandate ISO 12219 cabin air testing and tether-integrated architectures, consolidating supplier relationships around full-trim-package qualification. NHTSA rulemaking is accelerating specification sheet revisions.
- Fleet Operators:Commercial vehicle and rental fleet procurement departments specify pet-resistant materials as residual value protection, displacing traditional aftermarket accessory channels with bulk factory orders.
- Aftermarket Suppliers:Independent accessory distributors serve dealer networks and direct consumer channels with universal-fit configurations.
- Vehicle Upholsterers:Custom upholstery shops deliver bespoke conversions for luxury vehicle owners and pet transport service operators.
- Pet Transport Services:Specialized animal relocation companies demand commercial-grade durability with rapid turnaround cleaning protocols.
Volume concentrates with OEMs and fleet operators. Margin capture is climbing fastest among vehicle upholsterers serving bespoke conversion demand.
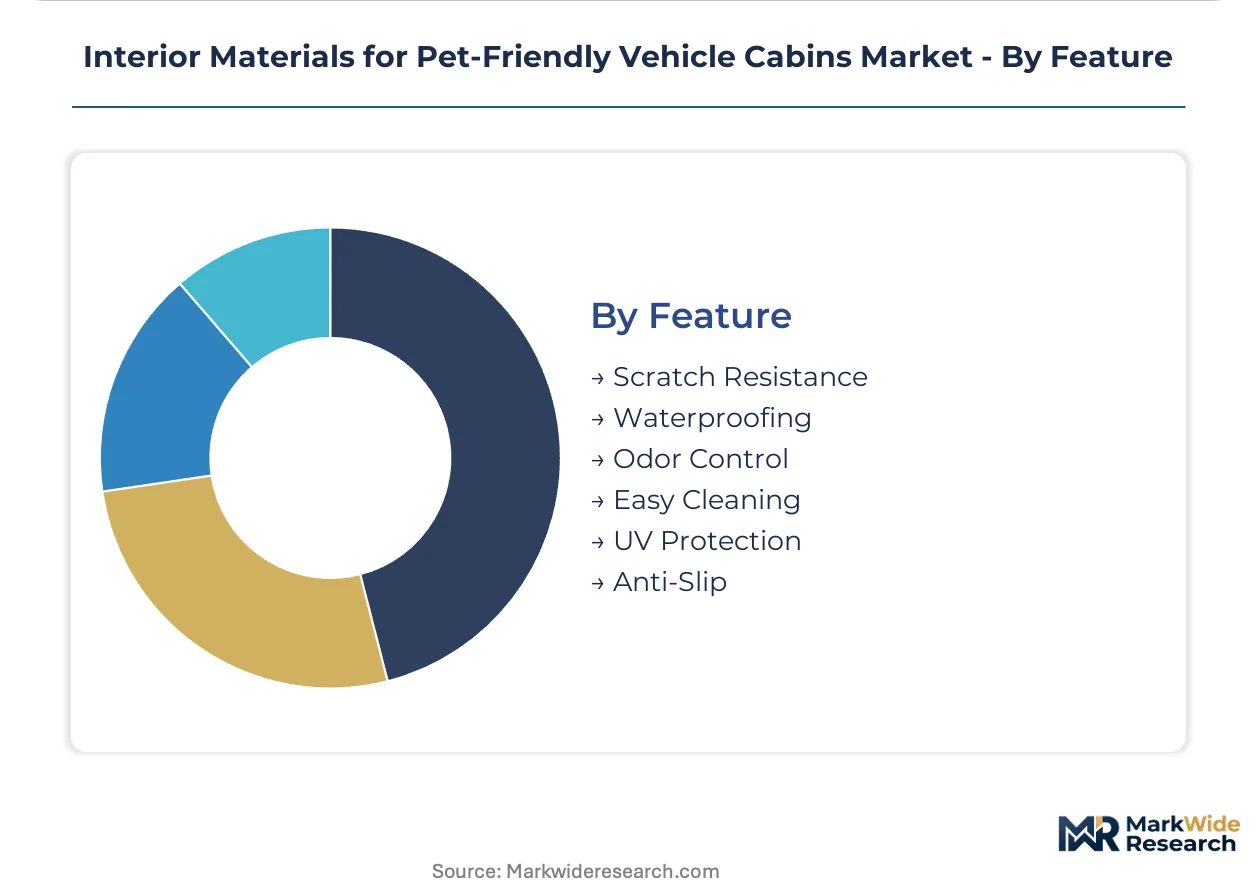
Feature:
Feature bundling determines pricing tier placement and regulatory exposure, with antimicrobial and tether integration commanding premium positioning.
- Scratch Resistance:Self-healing polyurethane coatings with nano-capsule repair mechanisms activate upon claw-induced micro-tearing, with luxury SUV and electric vehicle segments adopting these surfaces fastest for warranty-backed differentiation.
- Waterproofing:Hydrophobic surface treatments and seam-sealed construction prevent moisture ingress to underlying foam and structural substrates.
- Odor Control:Silver-ion and copper-based antimicrobial additives neutralize biological contamination but inflate raw material expenses beyond standard automotive-grade fabric pricing tiers.
- Easy Cleaning:Stain-release chemistries and non-porous surfaces enable rapid remediation of pet accidents.
- UV Protection:UV stabilizers in topcoat formulations prevent photodegradation of color and material integrity.
- Anti-Slip:Textured backing materials and retention systems prevent cargo liner displacement during vehicle operation.
Scratch resistance and waterproofing anchor baseline OEM specifications. Odor control is gaining share fastest as EPA indoor air quality protocols elevate material certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Michigan and South Carolina anchor North American production concentration for pet-resistant cabin materials, with state-level tax abatements pulling supplier co-location alongside OEM assembly plants.
United States
Detroit Three automakers in Michigan and Southeast assembly corridors drive factory-fit pet package standardization. NHTSA loose-object mitigation rules tighten tether-integrated seat architecture mandates. Lear Corporation anchors headliner substrate production in South Carolina's automotive supplier belt.
Germany
Premium SUV manufacturers in Bavaria and Baden-Württemberg integrate self-healing polyurethane coatings for warranty-backed durability claims. REACH restrictions on persistent organic pollutants force reformulation of stain-resistant chemistries ahead of anticipated EPA alignment. Supplier testing laboratories in Stuttgart face qualification backlogs for alternative coating validation.
China
Electric vehicle manufacturers in Yangtze River Delta and Pearl River Delta regions accelerate adoption of antimicrobial-integrated synthetic fibers. MIIT vehicle cabin air quality guidelines elevate material certification requirements for domestic OEM qualification. Zhejiang and Jiangsu province chemical clusters expand thermoplastic olefin compounding capacity for export-grade formulations.
Japan
Keiretsu seating suppliers in Aichi Prefecture leverage existing human-occupant expertise toward pet-anchoring hardware integration. METI industrial standards for interior air quality create voluntary benchmarks that OEMs increasingly mandate. Toyota Boshoku exemplifies this transition within Nagoya's automotive manufacturing corridor.
South Korea
Hyundai-Kia Motor Group procurement in Gyeonggi Province consolidates vendor relationships around full-cabin protection packages. MFDS antimicrobial additive registration requirements extend qualification timelines for silver-ion and copper-based treatments. Busan-Ulsan chemical complexes supply specialized coating intermediates for export markets.
Interior Materials for Pet-Friendly Vehicle Cabins Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold differentiated positions in premium coating and seating integration. The market structure concentrates among legacy automotive seating suppliers with polymer formulation expertise spanning crashworthiness and abrasion resistance. Three archetypes dominate: integrated seating system architects, specialty coating formulators, and synthetic fiber substrate specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs consolidate supplier relationships around full-trim-package qualification.
Among integrated seating system architects, FORVIA and Adient exemplify the tether-embedded hardware approach, while Lear Corporation occupies a position within odor-neutralizing substrate development. These three companies represent the archetype of suppliers redesigning substrates around embedded anchoring hardware rather than treating pet protection as aftermarket accessories. Their geographic distribution across North American and European production clusters reflects the regional concentration of Detroit Three and German premium OEM specification authority.
| Leading Market Players |
|---|
| FORVIA |
| Adient |
| Lear Corporation |
| Yanfeng Automotive Interiors |
| Magna International |
| Grupo Antolin |
| Toyota Boshoku |
| Continental AG |
| Sage Automotive Interiors |
| Others |
Pricing and Supply Chain Analysis
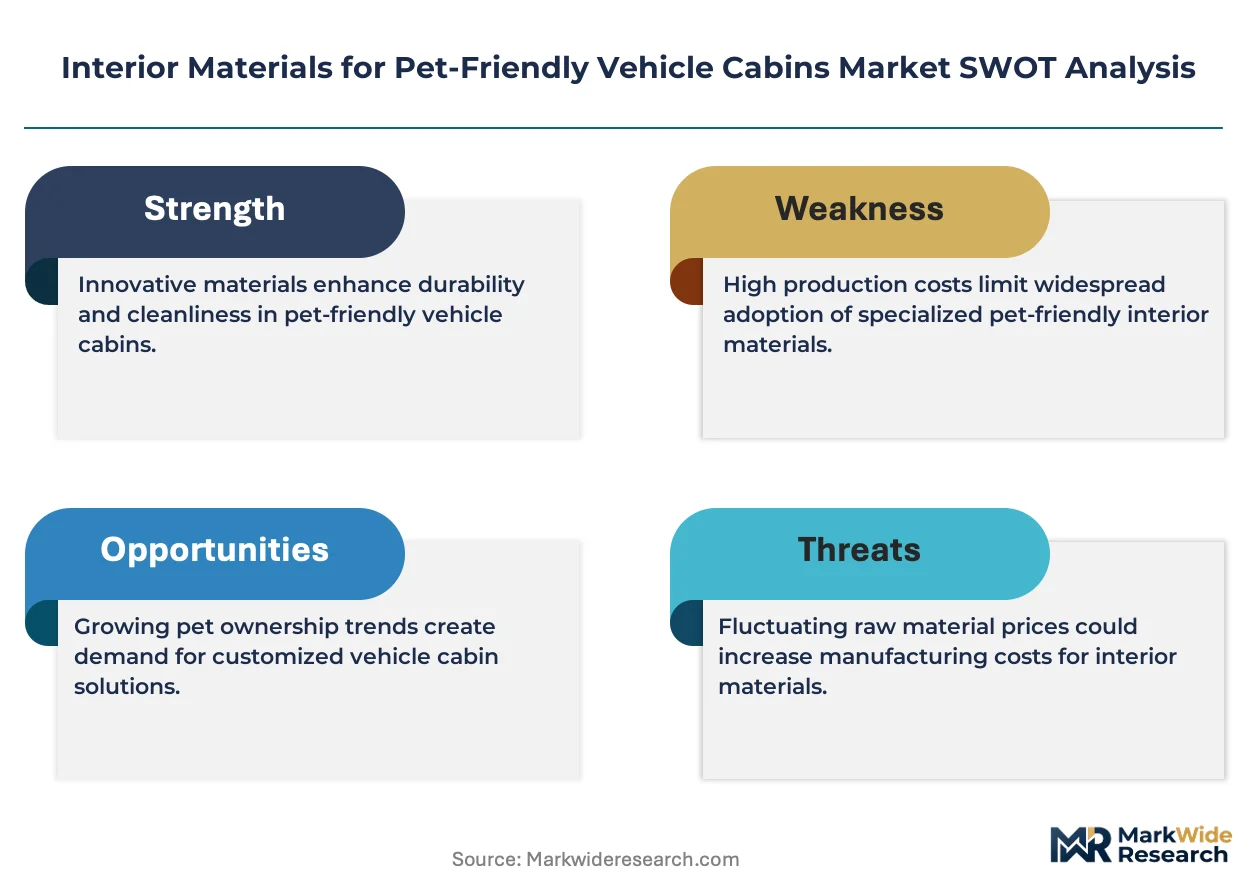
Polypropylene resin indices cascade through thermoplastic olefin compounding costs into three distinct pricing tiers for pet-resistant cabin materials, with OEM contract structures absorbing volatility while aftermarket channels pass through spot-market fluctuations.
Pricing Analysis
Lead-time premiums compress margins for expedited tether-integrated seat architectures, while spot inventory of standard cargo liners trades at discount. Three-tier pricing structure across premium, standard, and economy levels separates ISO 12219-certified formulations from uncertified alternatives. Pricing pressure stems from silver-ion antimicrobial additive cost inflation. Fleet operators exhibit highest price sensitivity; luxury electric vehicle OEMs demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with South Korean coating intermediate suppliers serving self-healing polyurethane production. Manufacturing concentrates in United States, Germany, and China. Raw material dependencies include polypropylene resin, polyurethane precursors, and ceramic nanoparticles. Tariff exposure on Chinese-sourced antimicrobial additives threatens margin stability. Distribution runs through Tier 1 seating suppliers with captive OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where NHTSA loose-object mitigation rules erect regulatory moats favoring incumbent seating suppliers with established crashworthiness certification infrastructure.
For Market Incumbents: Deepen backward integration into thermoplastic olefin compounding to offset polymer price volatility. Expand South Carolina production capacity to capture Detroit Three tether-integrated seat architecture demand. Prioritize ISO 12219 certification investment as emerging coating formulators threaten specification sheet presence. For New Entrants and Emerging Players: EPA indoor air quality protocols in the United States open a window for low-VOC substrate specialists to penetrate OEM qualification pipelines. Target headliner substrate innovation as Lear Corporation's concentrated R&D leaves white space for odor-neutralizing alternatives. Pursue direct-to-fleet partnerships outside traditional OEM distribution channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor synthetic fiber substrate specialists with existing automotive seating relationships in Michigan's supplier corridor. Five-to-ten-year viability hinges on dual-certification capability spanning NHTSA occupant safety and EPA emissions testing. Monitor state-level per- and polyfluoroalkyl substance restriction timelines as inflection signals for coating chemistry obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of thermoplastic olefin resins insulates margin from commodity volatility. |
| ISO 12219 Certification Investment | Mandatory supplier qualification pathway for OEM cabin air quality mandates. |
| Tether-Integrated Seat Architecture Development | NHTSA loose-object mitigation rules embed hardware into factory seat frames. |
| Fleet Partnership Consolidation | Commercial leasing operators displace aftermarket channels with bulk factory orders. |
| Self-Healing Coating Formulation Scale-Up | Nano-capsule repair mechanisms enable warranty-backed durability claims for luxury SUVs. |
Research Methodology
Document review covered SEC filings from seating suppliers, EPA and NHTSA regulatory dockets, and ISO 12219 test protocols, complemented by interviews with OEM platform engineers, Tier 1 procurement managers, and fleet operations directors. Secondary sources included vehicle production databases, customs trade data for polymer imports, and automotive supplier financial disclosures. Bottom-up segment sizing triangulated against top-down OEM specification sheet analysis.
Segment-level value and volume trajectories across the analysis window reflect material chemistry, application placement, and end-user channel structure. The modeling framework incorporated vehicle class, propulsion architecture, and content per vehicle as core dimensions. CAGRs derived from regression against historical OEM trim package adoption curves, with inputs from polymer compounding capacity expansion timelines and regulatory implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for self-healing polyurethane coatings would alter the outlook if nano-capsule repair mechanisms fail durability validation. Forecasts reflect assumptions on NHTSA rulemaking timelines and EPA indoor air quality protocol stringency. Deviation in state-level per- and polyfluoroalkyl substance restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market