
 Automotive Encapsulated Glass Market | 2026-2036
Automotive Encapsulated Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Encapsulated Glass Market Analysis
The EU Green Deal is rebalancing procurement priorities across European automotive supply chains, favoring suppliers with verified low-carbon encapsulation processes. Fuyao Glass leverages integrated float-to-laminate manufacturing to sustain cost leadership in high-volume contracts. Saint-Gobain anchors premium positioning through specialized acoustic and solar-control encapsulated assemblies for luxury platforms. AGC Inc. competes on advanced interlayer chemistry, differentiating its product line across OEM safety specifications.
Automotive encapsulated glass consists of laminated or tempered glazing bonded with thermoplastic or rubber-based edge seals to prevent moisture ingress, reduce NVH, and enable structural adhesion to vehicle frames; typical constructions employ polyvinyl butyral interlayers between soda-lime silica sheets with encapsulation molded from ethylene propylene diene monomer or thermoplastic polyurethane at peripheral edges. Laminated glass technology leads value contribution due to mandatory windshield safety standards and expanding heads-up display integration, while tempered glass dominates side-window volume through cost-efficient breakage patterns. Electric vehicle applications represent the fastest-growing demand pool as battery-electric architectures require optimized thermal management and weight reduction from glazing systems.
Europe's ECHA REACH framework and F-Gas Regulation restrict volatile compounds and high-GWP blowing agents in encapsulation materials, compelling reformulation investments. The U.S. NHTSA Federal Motor Vehicle Safety Standard 205 mandates optical clarity and penetration resistance for laminated windshields, directly shaping product development thresholds. China's SAMR enforces GB standards for automotive glass homologation, creating divergent certification pathways for multinational suppliers. Stakeholders must monitor evolving chemical substance restrictions and vehicle-type approval convergence to align regional production footprints with compliance requirements.
Market Dynamics
Electric vehicle OEMs are forcing laminated acoustic glass into battery-electric platforms at unprecedented scale, compressing traditional tempered-glass supply chains and rewiring encapsulation chemistry requirements toward thermoplastic edge-seal systems.
Growth Catalysts
- EU Green Deal procurement rebalancing:European automotive supply chains now favor suppliers with verified low-carbon encapsulation processes, accelerating thermoplastic adoption over rubber-based alternatives.
- Heads-up display integration:Premium OEMs require specialized laminated constructions with embedded holographic film layers, expanding value per windshield unit.
- Germany's premium manufacturing corridor:Concentrated demand from Stuttgart, Munich, and Wolfsburg assembly plants sustains high-specification contract volumes for acoustic and solar-control encapsulated assemblies.
Market Restraints
- EPDM and TPU input cost volatility:Ethylene propylene diene monomer and thermoplastic polyurethane prices fluctuate with petrochemical feedstock markets, compressing encapsulation margin stability.
- Float-glass supply concentration:Soda-lime silica substrate production clusters in China and Southeast Asia, exposing European and North American laminators to freight-cost spikes and currency exposure.
- Optical clarity thresholds:NHTSA Federal Motor Vehicle Safety Standard 205 mandates penetration resistance and visual distortion limits that disqualify thinner interlayer configurations.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives attract encapsulation material suppliers to establish localized compounding and molding capacity for domestic OEM supply.
- Solar-control glass in Middle East luxury platforms:Infrared-reflective interlayers address extreme thermal loading in Saudi and UAE passenger vehicle segments.
- Recyclable thermoplastic encapsulation:End-of-life vehicle directives under ECHA REACH favor polyurethane and polyolefin edge seals over cured-rubber alternatives in circular-economy roadmaps.
Industry Challenges
- Interlayer chemistry certification timelines:Polyvinyl butyral and ionomer interlayers require extended homologation cycles under divergent GB standards, ECE regulations, and FMVSS protocols.
- Acoustic engineering talent scarcity:NVH optimization for electric vehicle cabins demands rare combinations of materials science and vehicle dynamics expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Encapsulated Glass Market |
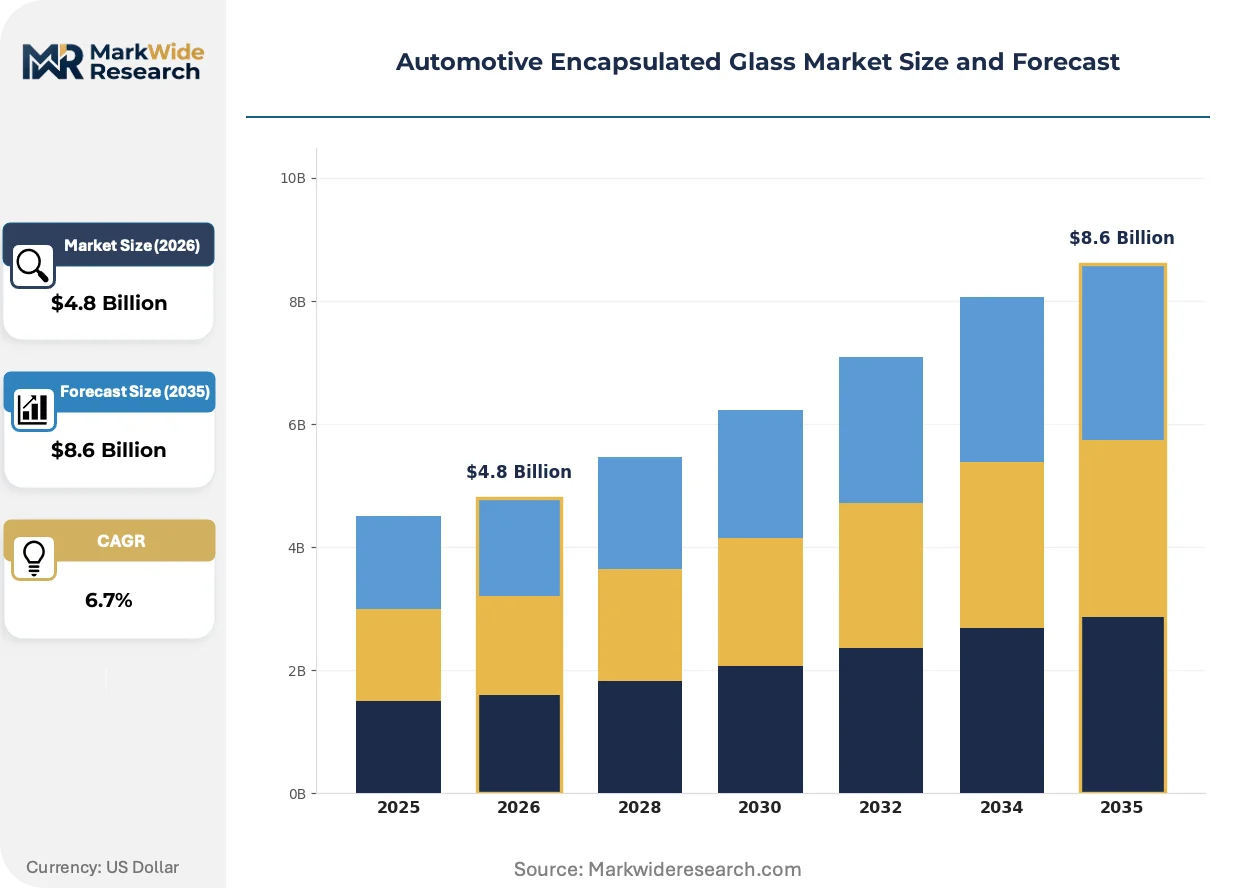
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Windshield, Rear Windshield, Side Windows, Sunroof Technology: Float Glass, Laminated Glass, Tempered Glass, Tinted Glass End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Independent Retailers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | Fuyao Glass, Gentex Corporation, AGC Inc., Pilkington NSG Group, Schott AG, Saint-Gobain, Sika AG, Guardian Glass, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Encapsulated Glass Market Emerging Trajectories
Encapsulation chemistry is pivoting toward recyclable thermoplastic systems as regulatory pressure on fluorinated compounds intensifies, while display integration and thermal management requirements reshape interlayer specifications.
Switchable electrochromic interlayers are converging with laminated windshield architectures to enable real-time tint adjustment. Battery-electric OEMs in the premium segment are specifying these systems for panoramic roof applications. This convergence is compressing development cycles for static solar-control coatings and forcing interlayer suppliers to master transparent conductor deposition.
Europe's F-Gas Regulation is banning high-global-warming-potential blowing agents in encapsulation foam production. Automotive glass laminators must reformulate edge-seal compounds or source alternative expansion chemistries. German and French OEMs are accelerating supplier audits to verify compliance ahead of enforcement deadlines.
Fleet procurement of encapsulated glass is consolidating around multi-year supply agreements with embedded carbon-accounting clauses. Leasing companies and ride-hail operators now specify low-embodied-carbon glazing in tender documents. This pattern is most visible in Nordic markets where corporate sustainability reporting under CSRD mandates Scope 3 disclosure for vehicle assets.
Automotive Encapsulated Glass Market Segmentation
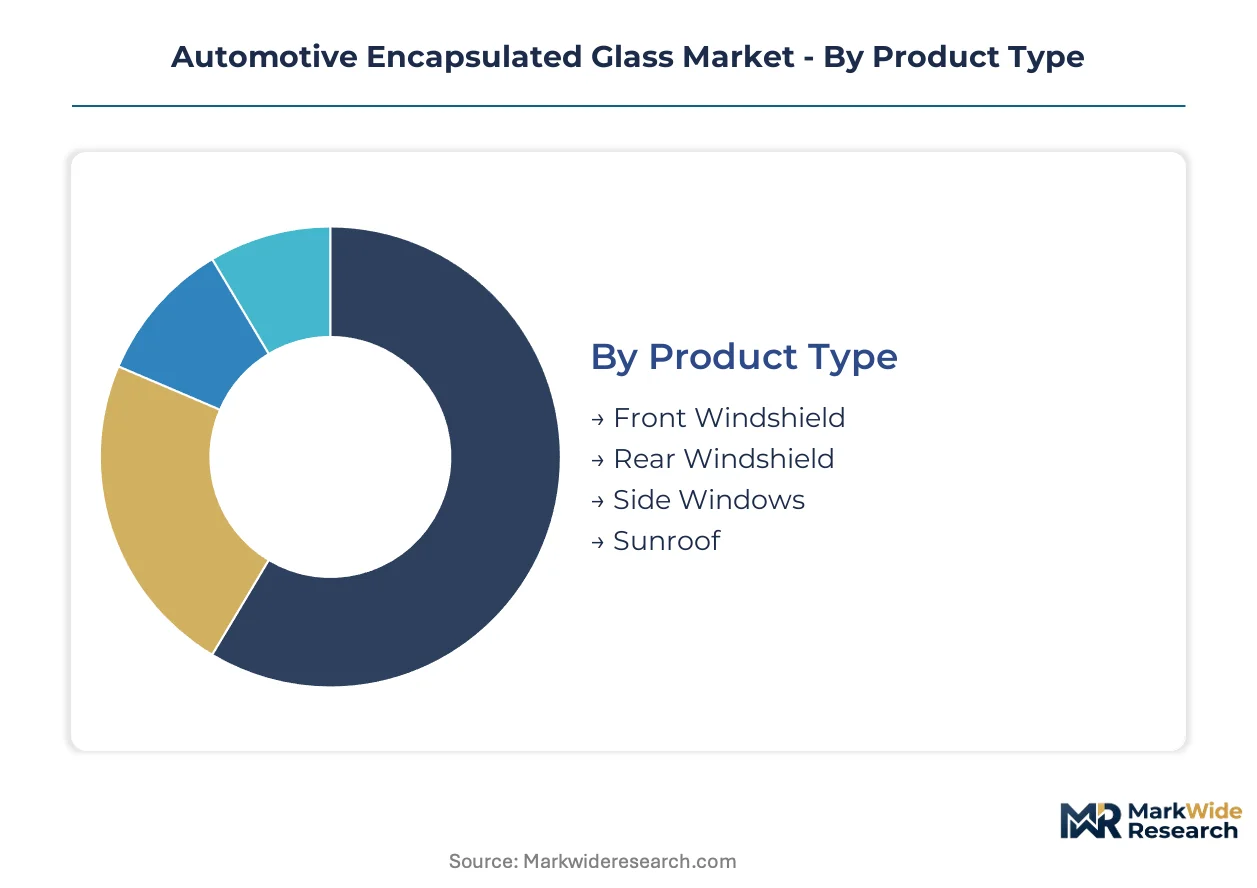
Encapsulated glass procurement varies sharply by integration depth. Standalone replacement demand flows through aftermarket channels with simplified specifications, while embedded systems in new vehicle platforms require synchronized development cycles and tiered supplier qualification.
Product Type:
Integration depth separates structural glazing bonded during assembly from bolt-on components replaced in service operations.
- Front Windshield:Laminated constructions with polyvinyl butyral interlayers dominate due to NHTSA penetration-resistance mandates. Stuttgart and Wolfsburg assembly plants sustain concentrated contract volumes for acoustic-laminated variants with embedded HUD film layers.
- Side Windows:Tempered soda-lime silica configurations achieve cost-efficient breakage patterns for emergency egress. Passenger vehicle OEMs in Germany's premium corridor specify these for weight reduction alongside thermoplastic polyurethane edge seals.
- Rear Windshield:Heated-grid laminations with conductive silver traces address defrosting loads in Nordic markets.
- Sunroof:Panoramic laminated assemblies with switchable electrochromic interlayers serve battery-electric luxury platforms.
Volume placements concentrate in Front Windshield; the faster expansion belongs to Sunroof.
Technology:
Cost tier stratification separates commodity float substrates from value-added laminated and coated configurations.
- Laminated Glass:Polyvinyl butyral or ionomer interlayers between soda-lime sheets enable structural adhesion and acoustic damping. Electric vehicle OEMs specify these for thermal management and heads-up display compatibility in battery-electric architectures.
- Tempered Glass:Rapid thermal strengthening creates predictable fragmentation patterns for side and rear openings. Aftermarket providers favor this technology for inventory efficiency and simplified logistics.
- Float Glass:Unprocessed soda-lime silica substrates feed laminators and tempering lines across Southeast Asian production clusters.
- Tinted Glass:Bulk-dyed or coated substrates address solar loading in Middle East passenger segments.
Revenue concentrates in Laminated Glass; steepest expansion trajectory belongs to Tinted Glass.
End User:
Customer type determines specification authority and contract structure across the value chain.
- OEMs:Direct procurement of encapsulated assemblies for platform integration with multi-year supply agreements. German and French manufacturers now embed carbon-accounting clauses under CSRD Scope 3 disclosure requirements.
- Tier-1 Suppliers:Module integration responsibility for window systems including encapsulation, seals, and actuator hardware. These suppliers manage qualification cycles under divergent GB standards and ECE regulations.
- Aftermarket Providers:Replacement demand through certified glass networks with simplified homologation pathways.
- Independent Retailers:Fragmented distribution for out-of-warranty vehicle populations.
Contract value concentrates in OEMs; aftermarket volume expansion is climbing the fastest.
Application:
Application maturity separates established internal-combustion platforms from emerging battery-electric specifications.
- Electric Vehicles:Battery-electric architectures demand optimized thermal management, weight reduction, and panoramic roof integration. F-Gas Regulation compliance for thermoplastic encapsulation materials is accelerating supplier audits ahead of enforcement deadlines.
- Luxury Vehicles:Acoustic-laminated and solar-control configurations command specification premiums. Saudi and UAE segments drive infrared-reflective interlayer adoption for extreme thermal loading.
- Passenger Vehicles:High-volume standardized specifications across mass-market platforms.
- Commercial Vehicles:Durability-focused tempered configurations for fleet replacement cycles.
Unit volume concentrates in Passenger Vehicles; Electric Vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of float-glass substrates feeding laminators worldwide, while Germany and the United States concentrate demand for high-specification encapsulated assemblies in premium automotive platforms.
Germany
Stuttgart, Munich, and Wolfsburg assembly plants sustain concentrated contract volumes for acoustic-laminated windshields with embedded HUD film layers. The F-Gas Regulation accelerates supplier audits for thermoplastic encapsulation compliance ahead of enforcement deadlines. Baden-Württemberg's automotive engineering corridor anchors development of solar-control and electrochromic interlayer specifications for battery-electric luxury platforms.
China
Domestic battery-electric OEMs specify optimized thermal management glazing at unprecedented scale, compressing traditional supply chains. SAMR enforces GB standards for automotive glass homologation, creating divergent certification pathways for multinational suppliers. The Yangtze River Delta and Pearl River Delta clusters concentrate float-glass production and downstream laminator capacity serving both domestic and export markets.
United States
NHTSA Federal Motor Vehicle Safety Standard 205 mandates optical clarity and penetration resistance thresholds that shape product development for laminated windshields. Michigan and Ohio assembly plants drive demand for tempered side-window configurations with thermoplastic polyurethane edge seals. The Inflation Reduction Act's domestic content provisions influence sourcing decisions for encapsulation materials in electrified platforms.
Japan
METI coordinates industry transitions toward recyclable thermoplastic encapsulation systems aligned with circular-economy roadmaps. Kansai and Chubu regions host specialized interlayer chemistry operations serving premium OEM acoustic specifications. Domestic automakers specify lightweight laminated constructions for hybrid and battery-electric architectures requiring NVH optimization.
India
The PLI scheme for automotive components attracts encapsulation material suppliers to establish localized compounding and molding capacity. Maharashtra and Tamil Nadu manufacturing corridors concentrate emerging demand from domestic OEMs and multinational platform localization. BIS standards enforcement creates parallel certification requirements for imported versus domestically produced glazing systems.
Automotive Encapsulated Glass Market Vendor Landscape
The competitive structure tilts toward integrated glass manufacturers with captive float-to-laminate operations. Tier-1 module integrators and specialized interlayer chemistry suppliers occupy distinct positioning tiers. Three archetypes dominate: Asian-scale float-glass producers with downstream laminator networks, European premium specialists commanding acoustic and solar-control premiums, and diversified materials conglomerates with encapsulation compound portfolios. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers securing multi-year agreements embedding carbon-accounting clauses under CSRD Scope 3 disclosure requirements.
Among Asian-scale producers, Fuyao Glass exemplifies the integrated manufacturing archetype with cost leadership in high-volume contracts. Saint-Gobain occupies a position within the European premium tier, anchoring specialized acoustic and solar-control assembly supply. AGC Inc. represents the diversified materials conglomerate model, competing on advanced interlayer chemistry across divergent OEM safety specifications.
| Leading Market Players |
|---|
| Fuyao Glass |
| Gentex Corporation |
| AGC Inc. |
| Pilkington NSG Group |
| Schott AG |
| Saint-Gobain |
| Sika AG |
| Guardian Glass |
| Corning Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive float-to-laminate integration anchors cost leadership for high-volume suppliers while compressing margin capture for standalone encapsulation compounders dependent on merchant glass feedstock. This structural asymmetry concentrates pricing power among Asian-scale producers with upstream substrate control, leaving European and North American laminators exposed to freight-cost volatility and currency translation effects.
Pricing Analysis
Cost-down pressure on standard-grade tempered configurations accelerates because Chinese float-glass oversupply feeds price erosion in aftermarket channels. Three-tier pricing structure across acoustic-laminated premium, solar-control mid-tier, and economy tempered grades separates OEM contract values, with penetration-resistance certification under NHTSA FMVSS 205 commanding measurable premiums. Fleet procurement departments exhibit highest price sensitivity through multi-year tender processes with embedded carbon-accounting clauses, while luxury OEM platform engineers prioritize HUD-compatible interlayer performance over unit cost.
Supply Chain Analysis
Homologation certification under divergent GB standards, ECE regulations, and FMVSS protocols gates supplier qualification and fragments procurement options across regional production footprints. Float-glass substrate supply draws from concentrated Yangtze River Delta and Pearl River Delta clusters in China, with downstream laminator capacity tethered to ethylene propylene diene monomer and thermoplastic polyurethane compound availability. Single-source vulnerability persists for specialized ionomer interlayer chemistries, with distribution running through Tier-1 module integrators managing synchronized assembly-line delivery to Stuttgart, Munich, and Wolfsburg plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as F-Gas Regulation compliance costs and carbon-accounting disclosure requirements under CSRD force sub-scale compounders toward exit or acquisition.
For Market Incumbents: Anchor premium positioning through captive acoustic interlayer development and backward integration into thermoplastic polyurethane compounding. Defensive moves require securing multi-year supply agreements with German and French OEMs ahead of enforcement deadlines, while expanding float-glass capacity in Southeast Asian hubs to offset freight-cost exposure from Chinese substrate concentration.
For New Entrants and Emerging Players: Tier-1 module integrators represent the most penetrable channel for qualification-light encapsulation materials serving aftermarket replacement demand. White-space targets concentrate in India's PLI scheme corridors for localized compounding capacity, and in solar-control interlayer supply for Middle East luxury platforms. Go-to-market execution should prioritize BIS certification pathways for domestically produced glazing systems.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified materials conglomerates seeking interlayer chemistry capabilities. Long-term viability favors targets with verified low-carbon encapsulation processes and established OEM platform qualifications. Watch for inflection signals in ECHA REACH substance restriction announcements that would trigger accelerated reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Encapsulation Reformulation | F-Gas Regulation compliance secures supply eligibility with German and French OEMs ahead of enforcement deadlines. |
| Float-to-Laminate Capacity Expansion | Integrated manufacturing in Southeast Asian hubs reduces freight-cost exposure and currency translation risk. |
| HUD-Compatible Interlayer Development | Embedded holographic film layers command specification premiums from Stuttgart and Wolfsburg assembly plants. |
| Carbon-Accounting Certification Investment | Verified low-carbon processes unlock CSRD Scope 3 disclosure compliance for European fleet procurement tenders. |
| Localized Compounding in India | PLI scheme qualification enables domestic OEM supply and reduces import dependency for encapsulation materials. |
Methodological Framework
Multi-period observation of vehicle registration data, encapsulation material trade flows, and OEM platform launch schedules anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and interlayer chemistry R&D directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs and trade statistics, and SEC filings of publicly traded glass manufacturers. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting across propulsion architecture, vehicle class, content per vehicle, and regional production cluster shaped the analytical framework. CAGRs were derived through regression analysis of historical shipment data and forward projection of OEM platform mix shifts across the analysis window. Industry-specific inputs included battery-electric vehicle glazing content assumptions and F-Gas Regulation compliance cost trajectories for thermoplastic reformulation.
Caveats apply where ECHA REACH substance restrictions, NHTSA optical clarity threshold revisions, or float-glass supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding OEM platform mix and regulatory enforcement timelines. A model refresh is warranted upon material change in European carbon-border adjustment mechanisms or Chinese export permit policies for soda-lime silica substrates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Glove Compartment Market