
 Automotive Seats Market | 2026-2036
Automotive Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seats Market Analysis
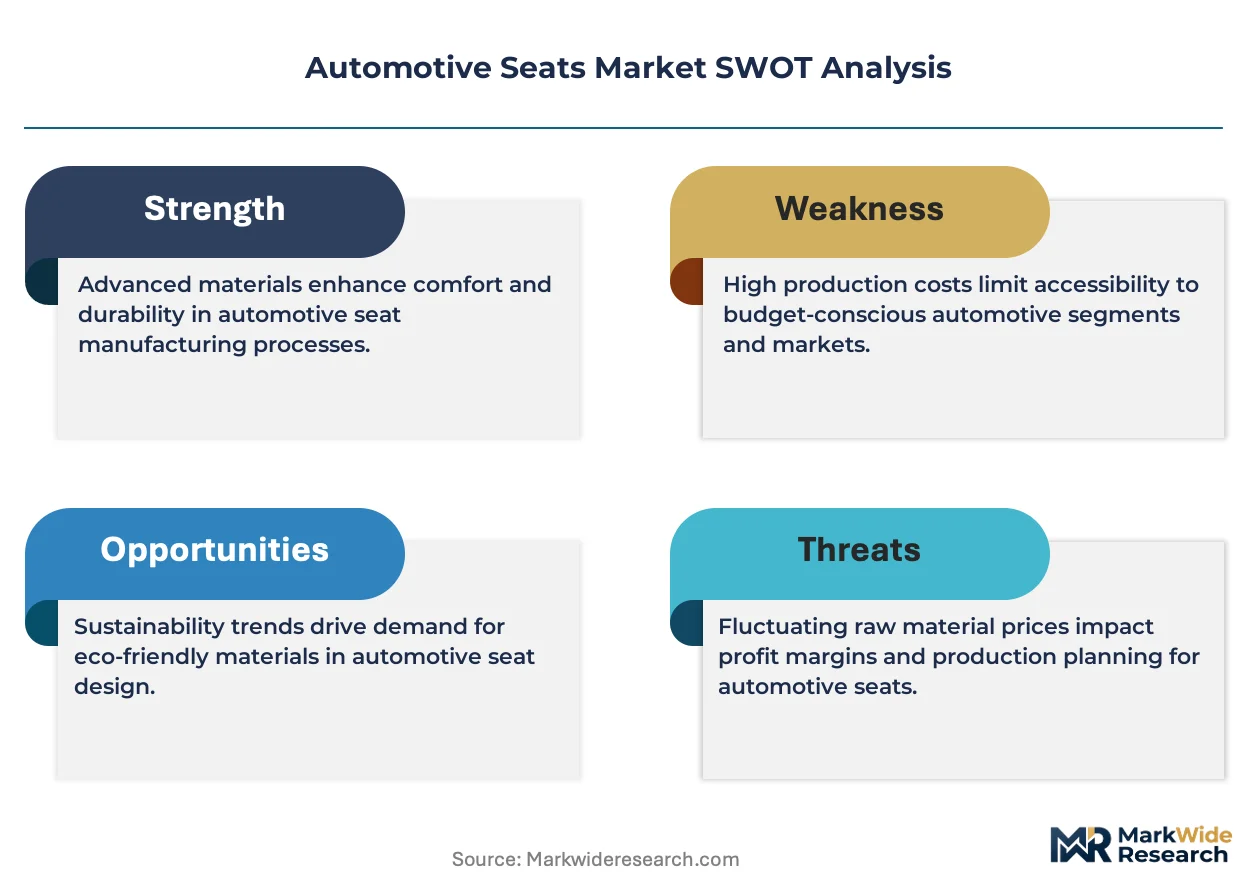
A skilled upholstery technician shortage across Tier-1 manufacturing hubs is unwinding traditional capacity expansion timelines for European and North American suppliers. Lear Corporation leverages vertical integration into foam-in-place manufacturing to sustain margin control across its seating division. Toyota Boshoku anchors its competitive position through captive supply relationships with Toyota Motor Corporation. Forvia SE differentiates via its comprehensive sustainable materials portfolio targeting OEM carbon-neutral roadmaps.
Automotive seats are structural-interior assemblies comprising a metal frame, cushioning foam, trim cover, and adjustment mechanisms engineered to occupant safety and ergonomic specifications. Seat frame designs must achieve specified load-bearing thresholds under ECE R17 and FMVSS 202a whiplash protocols while integrating heating elements and sensor arrays for advanced cabin systems. Bucket seats dominate premium and performance vehicle configurations where lateral support and power adjustability command price premiums. Fabric materials lead volume production for mainstream sedans and hatchbacks, though leather trim concentrates margin pools in luxury SUVs. Powered seats represent the fastest-expanding feature category as OEMs standardize multi-way adjustability across mid-range vehicle classes.
Federal Motor Vehicle Safety Standards administered by NHTSA govern seat strength, head restraint geometry, and flammability resistance for vehicles sold in the United States. ECE Regulations under UNECE WP.29 establish harmonized technical prescriptions adopted across EU member states, Japan, South Korea, and multiple emerging markets. China's GB standards administered by MIIT mandate specific seat anchor strength and child restraint system compatibility testing protocols. Stakeholders must monitor evolving UN Regulation No. 17 revision timelines and assess regional compliance divergence when configuring platform-sharing seat architectures across multiple production geographies.
Market Dynamics
Lightweighting mandates from electric vehicle manufacturers are compressing traditional steel-frame architectures toward aluminum and carbon-fiber-reinforced polymer alternatives, forcing Tier-1 suppliers to retool stamping lines and recalibrate weld-bonding protocols.
Growth Catalysts
- EU ECE R17 Revision:Upcoming amendments to head restraint performance criteria are compelling seat manufacturers to redesign active headrest mechanisms, opening specification windows for advanced actuator suppliers.
- China EV Production Surge:Domestic brands BYD and NIO are expanding manufacturing capacity in Changsha and Hefei, generating concentrated demand for locally integrated seating modules with embedded heating and ventilation.
- Foam-in-Place Manufacturing:This molding process enables complex ergonomic geometries while reducing trim cover stitching labor, allowing suppliers to match Japanese OEM quality benchmarks at lower unit costs.
Market Restraints
- Polyurethane Feedstock Volatility:MDI and TDI pricing fluctuations from BASF and Covestro facilities in Ludwigshafen and Antwerp directly compress foam cushioning margins during crude oil spike periods.
- Steel Tariff Cascades:Section 232 duties on imported high-strength steel from South Korea and Mexico inflate frame component costs for North American seat assembly plants.
- Technical Limitation:Current laser welding protocols for aluminum-to-steel hybrid frames struggle to achieve consistent fatigue life under ECE R14 anchor load cycles, delaying platform adoption.
Strategic Opportunities
- India Passenger Vehicle Expansion:Maruti Suzuki and Hyundai Motor India are localizing seat production in Manesar and Sriperumbudur, creating openings for foam and trim suppliers with BIS-certified manufacturing.
- Bio-Based Polyurethane:Castor oil-derived foam formulations from suppliers like Cargill align with OEM carbon-neutral roadmaps and qualify for EU Green Deal procurement preferences.
- Subscription Seating Features:BMW and Mercedes-Benz are piloting heated and massaging seat functions as over-the-air activated services, transforming hardware into recurring revenue streams.
Industry Challenges
- Upholstery Technician Scarcity:Skilled pattern-cutting and sewing specialists are retiring faster than apprenticeship programs in Stuttgart and Detroit can replenish, stretching prototype development timelines.
- Multi-Protocol Certification Burden:Seats destined for US, EU, and China markets must simultaneously satisfy FMVSS 202a, ECE R17, and GB 11550 testing regimes, multiplying validation costs.
- Sensor Integration Complexity:Occupant classification systems for smart airbag deployment require calibration across 50-plus body-type variables, slowing production ramp rates.
Report Scope
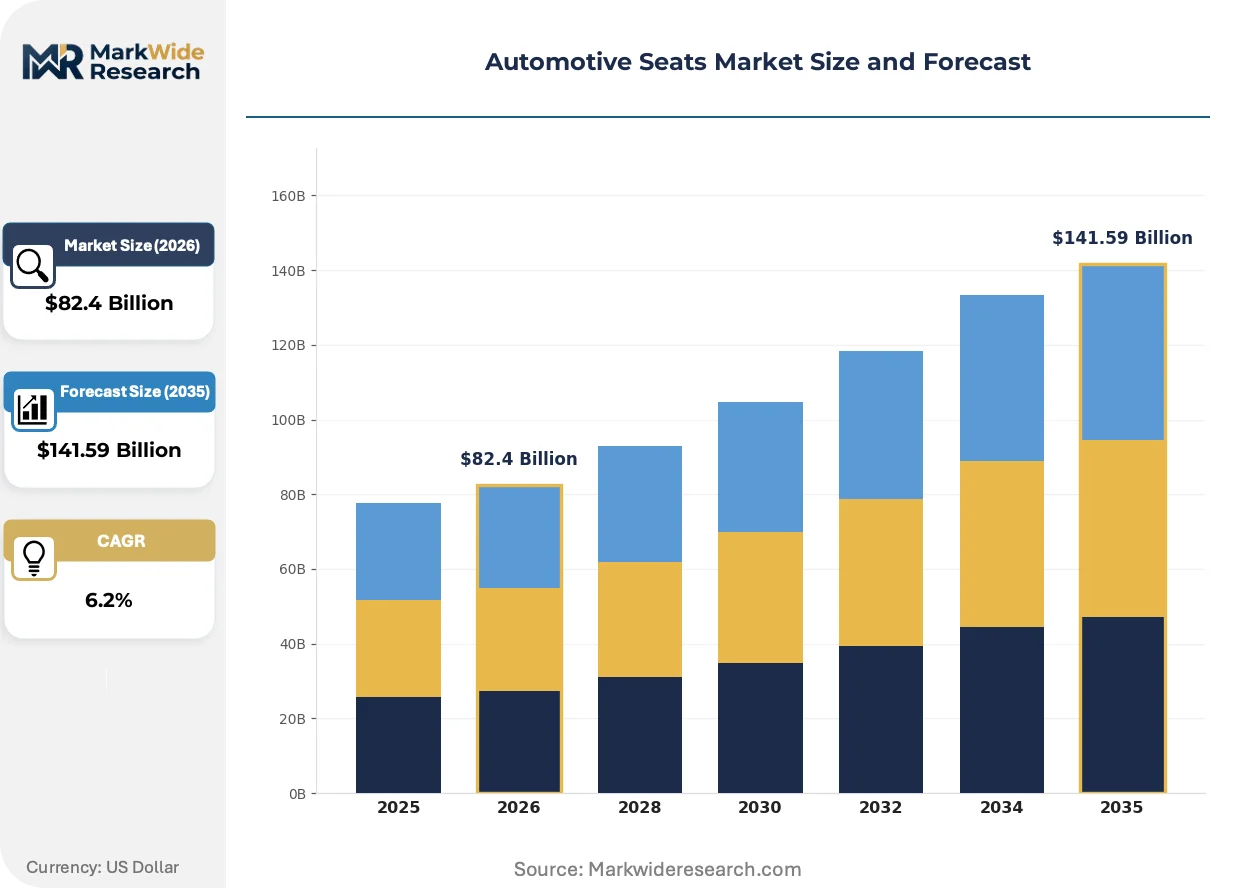
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seats Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $141.59 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Seats, Bench Seats, Captain Seats, Racing Seats Material: Leather, Fabric, Vinyl, Foam Vehicle Type: SUVs, Sedans, Trucks, Hatchbacks Feature: Heated Seats, Reclining Seats, Powered Seats, Ergonomic Design |
| Companies Covered | Adient Plc, Lear Corporation, Forvia SE, Toyota Boshoku Corporation, Magna International, TS Tech Co Ltd, Tachi-S Co Ltd, NHK Spring Co Ltd, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seats Market Emerging Trajectories
Seat architecture is fragmenting into two parallel development tracks: ultra-lightweight structures for battery-electric range optimization versus reinforced frames for autonomous vehicle crashworthiness, with suppliers forced to maintain dual engineering competencies.
Modular seat platforms are bifurcating the supplier base. Standardized floor-mounted rails with interchangeable cushion and backrest modules allow OEMs to mix fabric, leather, and synthetic trim across vehicle grades using identical structural cores. Volkswagen Group and Stellantis are deploying this approach across MQB and STLA platforms, compressing development costs while fragmenting trim supplier relationships into commodity foam and premium cover specialists.
REACH Annex XVII restrictions on flame retardants are forcing polyurethane reformulation across EU-bound production. Suppliers are migrating from halogenated to phosphorus-based additives, with TÜV Rheinland certification timelines extending six to nine months. German seat manufacturers in Böllinghausen and Kaiserslautern report delayed SOP dates for 2026 model year programs as chemical qualification protocols lag material availability.
Fleet procurement of configurable seating is displacing retail-driven option bundling. Rental and mobility-service operators specify standardized manual seats with durable vinyl surfaces, rejecting power-adjustment complexity that elevates maintenance costs. This pattern concentrates volume with Mexican and Romanian assembly plants serving Hertz and Sixt specifications, while premium power-seat production shifts toward captive luxury OEM supply in Germany and Japan.
Automotive Seats Market Segmentation
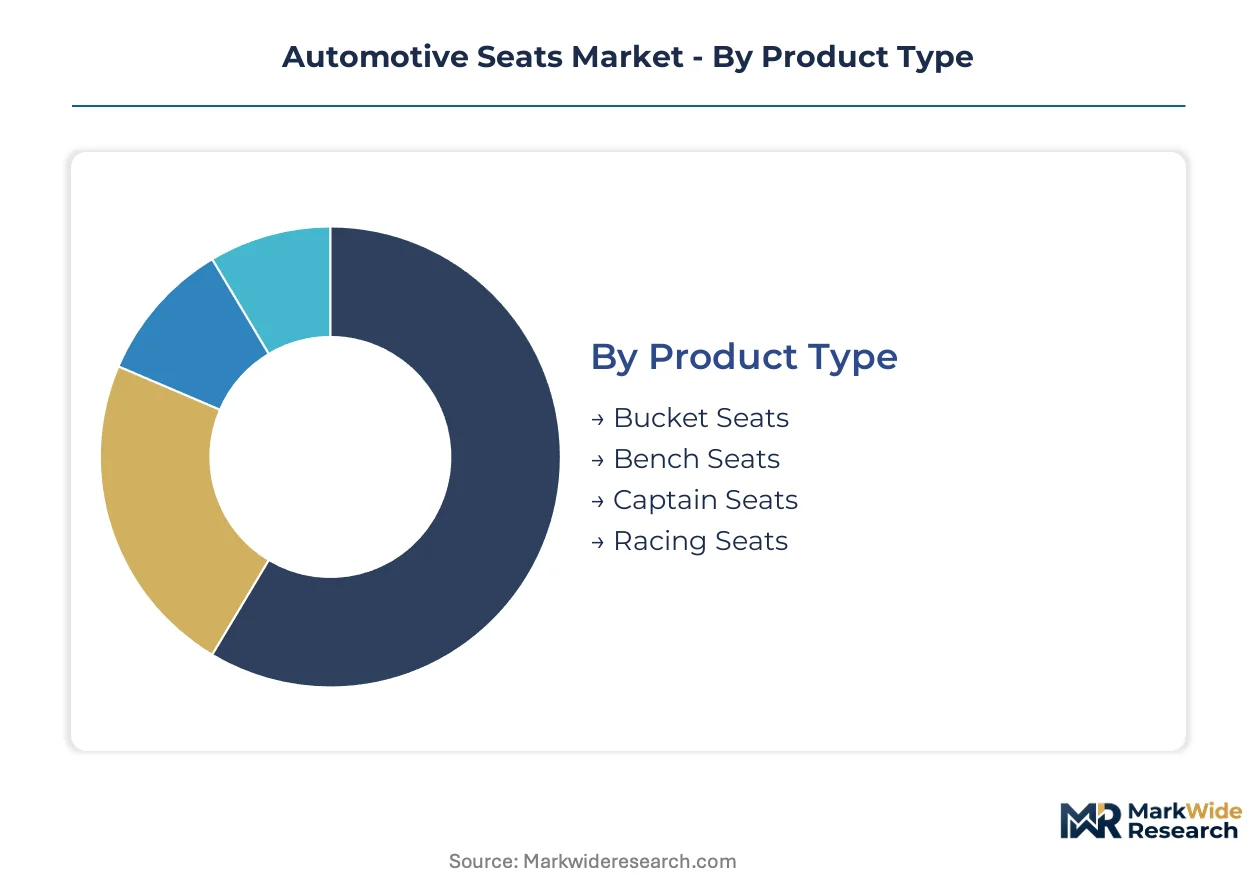
Seat architecture fragmentation demands granular segmentation tracking. OEM procurement teams now specify by vehicle electrification tier and autonomous readiness level rather than traditional trim grades. Suppliers must align production assets to these evolving category boundaries.
Product Type:
Channel mix varies sharply: bucket seats flow through premium OEM direct contracts, bench seats dominate fleet procurement channels, while racing seats concentrate in aftermarket performance distributors.
- Bucket Seats:Individual seating modules with contoured side bolsters and integrated head restraints. Demand concentrates in Germany and Japan where BMW and Toyota specify multi-way power adjustability for luxury SUVs. ECE R17 whiplash compliance adds actuator complexity.
- Bench Seats:Continuous three-passenger configurations with folding center armrests. Fleet operators in the United States and China favor these for rental and ride-hail vehicle pools due to lower maintenance costs and standardized vinyl durability.
- Captain Seats:Second-row individual seats with aisle access gaps. Premium minivan and full-size SUV configurations in South Korea and the United States specify these for family vehicle segments.
- Racing Seats:Fixed-back shells with harness pass-throughs and fire-retardant fabrics. Motorsport homologation requirements from FIA and SFI govern certification for track-day and competition use.
By volume, bench seats lead. By growth pace, bucket seats are climbing the fastest.
Material:
Cost tier stratification drives supplier specialization: leather commands premium OEM direct channels, fabric saturates mass-market assembly lines, vinyl captures fleet maintenance contracts, and foam flows as captive in-house production.
- Leather:Full-grain and corrected-grain hides with perforated ventilation patterns. Nappa leather from Italian tanneries supplies Mercedes-Benz and Audi luxury configurations; Chinese EV brands increasingly specify domestic semi-aniline alternatives.
- Fabric:Woven polyester and nylon blends with stain-resistant treatments. Maruti Suzuki and Hyundai Motor India specify these for compact hatchback production in Manesar and Sriperumbudur.
- Vinyl:PVC and TPU synthetic surfaces with embossed grain patterns. Hertz and Sixt rental specifications in the United States and Romania mandate these for durability and sanitization ease.
- Foam:Molded polyurethane cushioning with variable density zones. Lear Corporation and Toyota Boshoku maintain in-house production to control ergonomic calibration and margin capture.
Fabric dominates unit volume. Leather delivers the steepest margin expansion trajectory.
Vehicle Type:
Application-specific load requirements reshape frame engineering: SUVs demand reinforced anchor structures, sedans prioritize rear-seat packaging efficiency, trucks require severe-duty durability, and hatchbacks emphasize lightweighting for fuel economy.
- SUVs:Higher H-point seating with elevated hip-to-heel dimensions. Ford and Stellantis specifications in the United States and Italy drive demand for power-folding third-row mechanisms.
- Sedans:Low-slung bucket configurations with extended thigh bolsters. BYD and NIO production in Changsha and Hefei concentrates procurement for domestic Chinese market dominance.
- Trucks:Severe-duty frames with 150kg-plus occupant load ratings. Ford F-150 and Ram 1500 programs in Michigan and Mexico specify these for commercial and personal use segments.
- Hatchbacks:Compact dimensions with 60/40 split-folding rear benches. European A-segment vehicles from Volkswagen and Renault prioritize these for urban parking constraints.
SUVs anchor current production volume. Hatchbacks are gaining share fastest in electrified urban mobility.
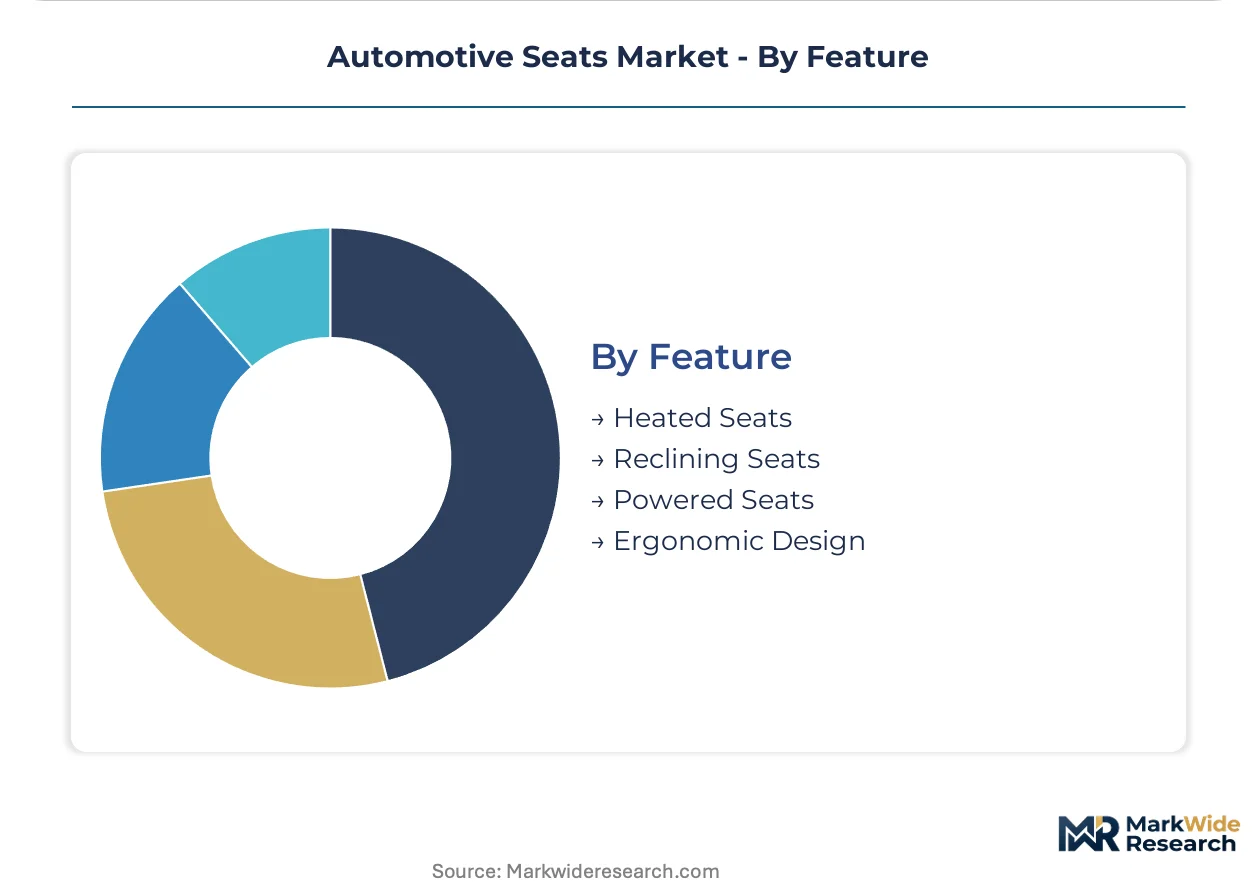
Feature:
Customer type bifurcation is pronounced: powered and heated features concentrate in retail premium channels, reclining and ergonomic designs flow through fleet procurement with durability specifications.
- Heated Seats:Resistive wire or positive temperature coefficient elements embedded in cushion and backrest. BMW and Mercedes-Benz pilot subscription activation models in Germany and the United States.
- Reclining Seats:Articulating backrest mechanisms with locking detents. Long-wheelbase luxury sedans from Lexus and Genesis specify these for rear-seat passenger comfort.
- Powered Seats:Multi-way adjustability with memory positioning and lumbar support. Mid-range vehicle classes now standardize these as competitive necessity across Japanese and Korean OEM lineups.
- Ergonomic Design:Biomechanically optimized contours with pressure-mapping validation. Volvo and Mercedes-Benz lead specification for long-distance driver fatigue reduction.
Powered seats lead by installation rate. Heated seats show the steepest expansion trajectory in subscription monetization pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's FMVSS protocols anchor North American seat engineering requirements, while ECE R14 and R17 revisions in Europe and GB standards under MIIT in China create divergent compliance frameworks that suppliers must navigate across production geographies.
United States
Ford and Stellantis specifications drive demand for severe-duty truck seats and power-folding SUV mechanisms. NHTSA's FMVSS 202a whiplash protocols govern head restraint geometry for all vehicles sold domestically. Michigan assembly plants in Detroit and Lansing concentrate frame stamping and foam molding operations serving F-150 and Ram 1500 programs.
Germany
BMW and Mercedes-Benz subscription seating pilots are reshaping feature monetization models for heated and massaging functions. REACH Annex XVII flame retardant restrictions are forcing polyurethane reformulation with phosphorus-based additives. Böllinghausen and Kaiserslautern clusters report delayed SOP dates as TÜV Rheinland certification timelines extend for 2026 model year programs.
China
BYD and NIO capacity expansion in Changsha and Hefei is generating concentrated procurement for locally integrated seating modules with embedded heating and ventilation. MIIT-administered GB standards mandate specific seat anchor strength and child restraint compatibility testing. Domestic EV brands are specifying locally sourced seating systems to reduce import dependency and align with dual carbon goals.
Japan
Toyota Boshoku's captive supply relationships with Toyota Motor Corporation anchor production planning for hybrid and fuel-cell vehicle platforms. METI industrial policy supports lightweight material development for export competitiveness. Nagoya-area manufacturing clusters concentrate on high-volume bucket seat production with integrated sensor arrays for advanced cabin systems.
India
Maruti Suzuki and Hyundai Motor India are localizing seat production in Manesar and Sriperumbudur to serve compact hatchback and sedan demand. BIS certification requirements govern foam and trim supplier qualification for domestic assembly. Karnataka and Tamil Nadu industrial corridors are attracting tier-1 seating investments as passenger vehicle expansion accelerates.
Automotive Seats Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the automotive seats market. Lear Corporation and Adient Plc command scale advantages through captive foam production and global assembly footprints. The mid-tier fragments into regional specialists serving single OEMs or single geographies. Three archetypes dominate: vertically integrated full-line suppliers, captive affiliates of Japanese and Korean OEMs, and modular component specialists. Competitive moves center on backward integration into polyurethane molding and geographic expansion into China and India EV production clusters.
Among North American-integrated leaders, Lear Corporation exemplifies the full-line archetype with in-house foam production capabilities. Toyota Boshoku Corporation occupies the captive affiliate position within Japanese OEM supply structures. Forvia SE represents the European sustainability-focused tier with materials portfolio alignment to OEM carbon-neutral roadmaps. These three anchors illustrate how competitive positioning diverges across integration strategies and geographic anchoring.
| Leading Market Players |
|---|
| Adient Plc |
| Lear Corporation |
| Forvia SE |
| Toyota Boshoku Corporation |
| Magna International |
| TS Tech Co Ltd |
| Tachi-S Co Ltd |
| NHK Spring Co Ltd |
| Aisin Corporation |
| Others |
Supply Flow & Price Mechanics
Aluminum substitution for high-strength steel in EV seat frames is simultaneously relocating stamping capacity toward China and Mexico while compressing per-unit margins as OEMs negotiate lightweighting cost premiums against traditional steel architectures.
Pricing Analysis
Price spreads between German premium seating exports and Chinese domestic supply exceed 40 percent for equivalent feature content. Three-tier pricing structure across premium, standard, and economy levels separates Nappa leather configurations from fabric-trimmed modules and fleet-spec vinyl benches. Cost compression in mid-range powered seats is intensifying because BYD and NIO procurement teams negotiate module-level sourcing. Fleet operators exhibit highest price sensitivity, while luxury OEM direct contracts tolerate premium positioning for ergonomic certification.
Supply Chain Analysis
Inventory cycles for polyurethane foam precursors now stretch fourteen to eighteen weeks following BASF Ludwigshafen supply disruptions. Concentrated supply rests on Germany, China, and Mexico for frame stamping, with MDI and TDI feedstock anchored in Antwerp and Ludwigshafen. Single-source vulnerability concentrates in Italian tanneries supplying full-grain leather hides. Distribution runs through Tier 1 supplier assembly plants co-located with OEM vehicle production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat industry where ECE R17 certification timelines and REACH chemical compliance create switching costs that protect incumbent positions from rapid displacement.
For Market Incumbents: Fortify backward integration into foam-in-place manufacturing to defend margin structures against polyurethane feedstock volatility. Pursue BIS certification for Indian production capacity before Maruti Suzuki and Hyundai Motor India finalize localized seating contracts. Prioritize active headrest actuator development ahead of ECE R17 revision implementation. For New Entrants and Emerging Players: Aftermarket sensor calibration services represent an underserved layer where incumbent Tier 1 suppliers lack service infrastructure. Target Indian compact hatchback seating supply as the most penetrable volume segment. Pursue castor oil-derived foam formulations as a sustainability-differentiated go-to-market angle aligned with EU Green Deal procurement preferences. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated full-line suppliers with captive chemical production. Five-to-ten year viability hinges on China EV production localization and India passenger vehicle expansion trajectories. Monitor TÜV Rheinland certification backlog duration as an inflection signal for European supplier margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group MQB and Stellantis STLA architectures compress development costs across vehicle grades. |
| Battery Supply Agreement | EV OEM procurement of lightweight seat structures directly anchors range optimization targets. |
| Software-Defined Vehicle Investment | BMW and Mercedes-Benz subscription seating pilots transform hardware into recurring revenue streams. |
| Geographic Manufacturing Footprint | Changsha and Hefei capacity expansion captures BYD and NIO localized seating demand. |
| Charging Infrastructure Partnership | Fleet operator specifications for durable vinyl benches concentrate volume with Mexican and Romanian assembly plants. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, foam chemical R&D directors, and aftermarket distributors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from publicly traded seating suppliers. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled encompass vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression analysis of historical production volumes against projected EV penetration curves and lightweighting content trajectories. Forecast inputs incorporated ECE R17 revision implementation timelines and REACH Annex XVII chemical restriction phase-in schedules.
Underlying assumptions cover sustained EV production growth in China and India, with deviation risk concentrated in polyurethane feedstock price volatility and steel tariff policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Automotive Door Handles Market