
 Automotive Underbody Coatings Market | 2026-2036
Automotive Underbody Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Underbody Coatings Market Analysis
OEM specification channels is reconfiguring how underbody coatings reach vehicle assembly lines. PPG Industries leverages its captive supply relationships with major automakers to sustain formulation continuity across multiple platforms. Henkel competes through specialized adhesive-coating hybrids that extend protection into seam-sealing applications.
Automotive underbody coatings are protective barrier systems applied beneath vehicle floors and chassis components, typically comprising rubberized polymers, wax dispersions, or polyurethane resins at dry-film thicknesses ranging from 500 to 2,000 microns to resist stone-chip impact, moisture ingress, and corrosive de-icing salts. Their primary purpose is extending vehicle structural integrity and warranty life in high-abrasion environments. Rubberized formulations dominate volume due to their acoustic damping properties and cost efficiency in mass-market production, while polyurethane coatings command premium positioning through superior elongation and chemical resistance. Water-based formulations are gaining share fastest as OEM sustainability mandates tighten solvent emissions across assembly plant operations.
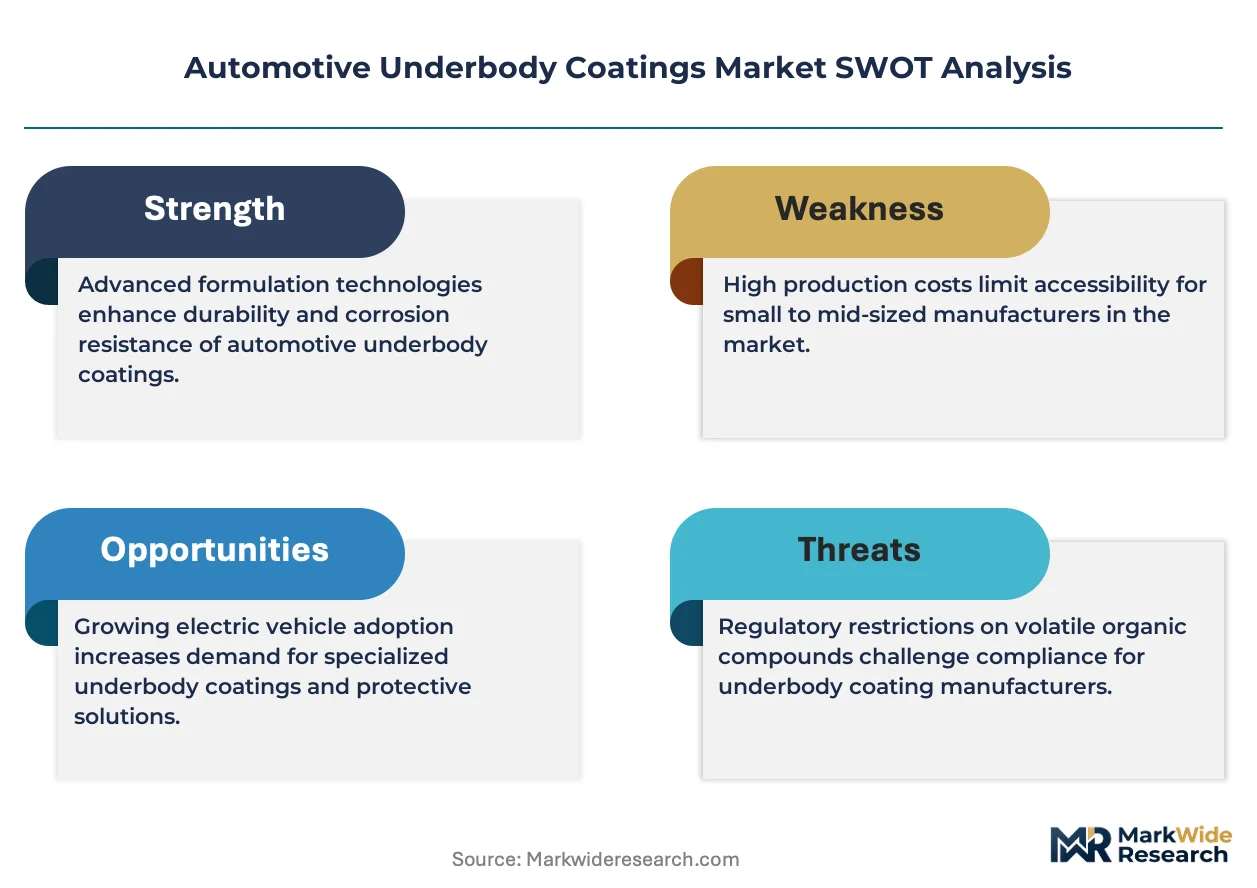
The EPA enforces VOC emission thresholds through National Emission Standards for Hazardous Air Pollutants that directly constrain solvent-based coating use in US manufacturing facilities. REACH registration requirements and the EU Green Deal carbon-border adjustments are forcing European suppliers to document full substance lifecycles and accelerate low-emission transitions. China's MEE implements parallel GB standards on industrial coating VOC content that affect both domestic production and import qualification. Stakeholders must monitor how diverging regional compliance calendars reshape formulation R&D priorities and cross-border product registration strategies.
Market Dynamics
OEM sustainability mandates are compressing solvent-based coating lifecycles while water-based polyurethane systems capture specification share at major assembly plants. REACH VOC limits and China's GB standards are forcing simultaneous reformulation across multiple production geographies.
Growth Catalysts
- EPAs NESHAP thresholds:US manufacturing facilities face tightened hazardous air pollutant limits that accelerate low-emission coating transitions.
- Chassis electrification:Battery-electric vehicle platforms require enhanced underbody protection for high-voltage component housings and thermal management systems.
- Germany's coating innovation clusters:Dense concentrations of automotive R&D and testing infrastructure concentrate formulation advancement.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane resin costs fluctuate with propylene oxide and MDI pricing, compressing margin stability for coating formulators.
- Application equipment lock-in:Existing solvent-optimized spray systems at OEM plants require capital-intensive retooling for water-based viscosity profiles.
- Performance gap in salt-spray testing:Water-based formulations struggle to match 1,000-hour corrosion resistance benchmarks that rubberized solvent systems achieve.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:Production-linked incentives attract new vehicle assembly capacity requiring localized coating supply.
- Seam-sealing hybrid applications:Adhesive-coating convergence extends protection into structural joints previously treated as separate operations.
- EU Green Deal carbon-border adjustments:Import documentation requirements favor European-produced low-emission formulations over imported solvent-based alternatives.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in water-based polymer stabilization and rheology control remains concentrated among senior technical staff.
- Dual certification timelines:OEM qualification protocols require parallel validation across multiple vehicle platforms, extending time-to-revenue for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Underbody Coatings Market |
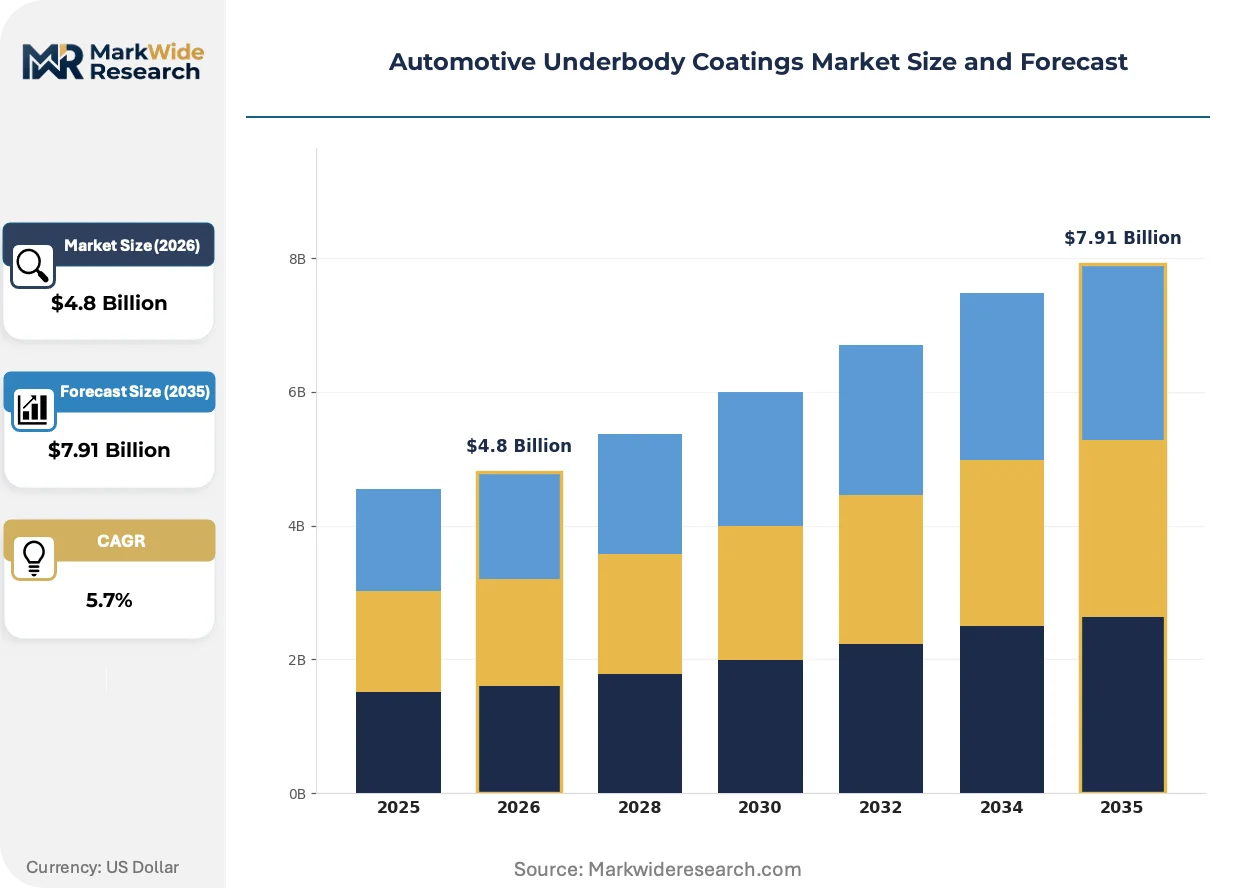
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubberized, Wax-Based, Polyurethane, Asphalt End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Chassis, Wheel Wells, Fuel Tanks, Body Panels Formulation: Water-Based, Solvent-Based, Powder Coatings, Thermal Spraying |
| Companies Covered | 3M, ThreeBond, PPG Industries, Jenolite, Lubrizol, Henkel, Sika, Axalta Coating Systems, Sherwin-Williams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Underbody Coatings Market Emerging Trajectories
Active noise cancellation requirements in electric vehicles are redefining acoustic performance specifications for underbody protection systems. Material scientists and coating applicators are recalibrating around sound-damping coefficients alongside traditional corrosion metrics.
Self-healing polymer networks with microcapsulated repair agents are rendering obsolete conventional static barrier coatings that fail catastrophically upon stone-chip penetration. Luxury electric vehicle manufacturers are specifying these systems for battery enclosure protection. The technology is compressing warranty claim exposure while extending service intervals.
REACH authorization procedures for chromium trioxide in corrosion inhibitors are forcing reformulation toward zirconium-based and silane pretreatment alternatives. European suppliers must submit substitution plans by regulatory deadlines or cease affected product lines. German and Czech coating operations are accelerating qualification of chrome-free conversion coatings for OEM approval.
Fleet operators and leasing companies are consolidating procurement around lifecycle cost models rather than unit price metrics. Large commercial vehicle buyers now specify coating durability guarantees tied to residual value retention. This behavior is most visible in North American heavy-duty truck manufacturing where total cost of ownership frameworks dominate supplier selection.
Automotive Underbody Coatings Market Segmentation
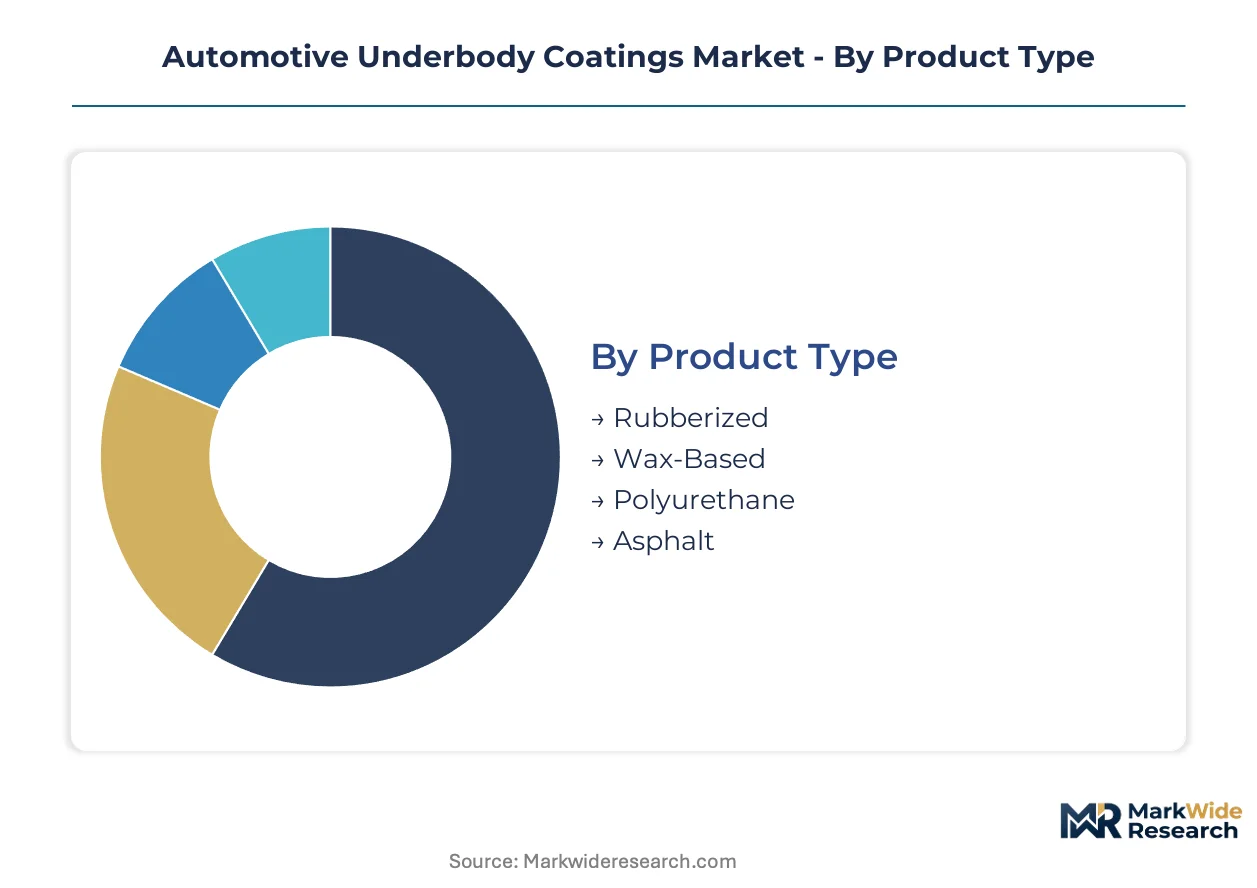
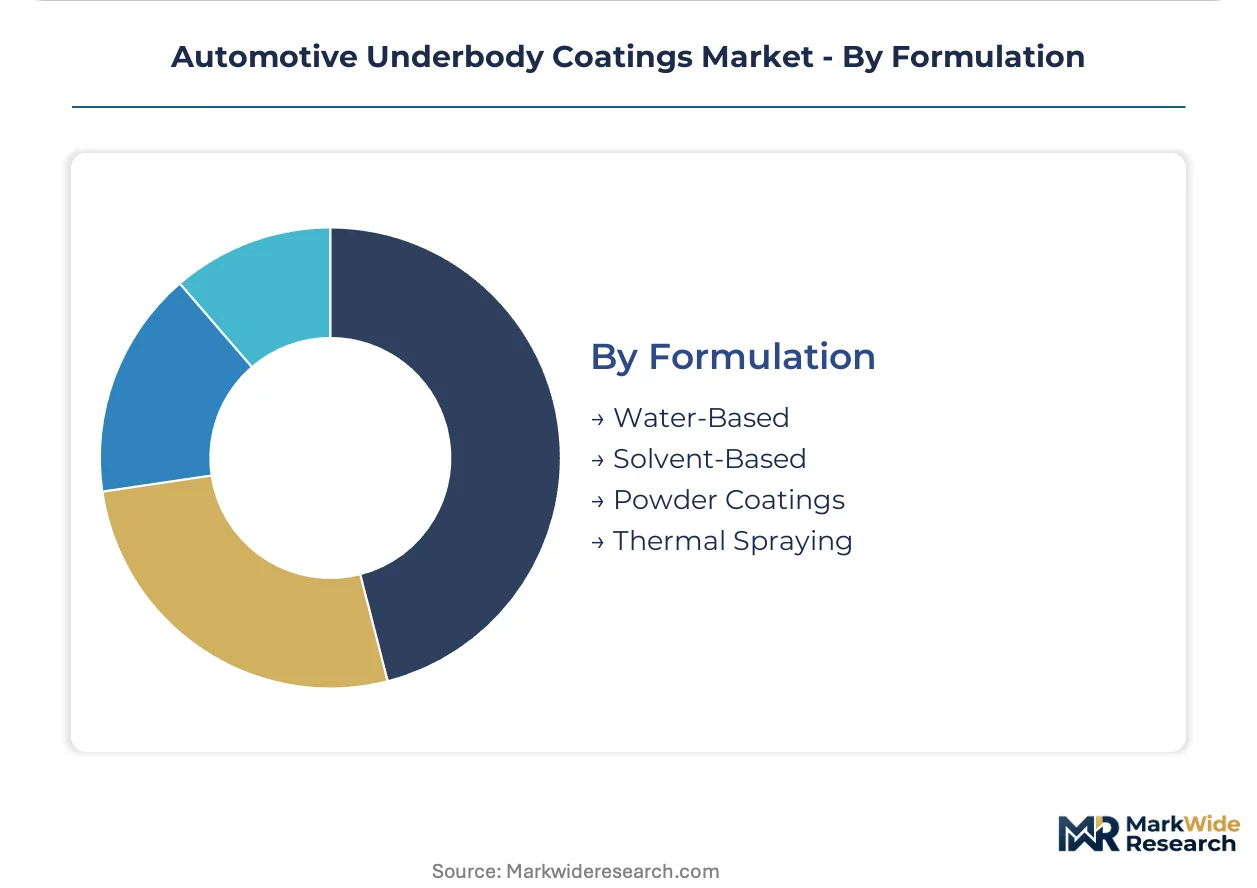
Automotive underbody coatings serve divergent performance requirements across vehicle platforms, from mass-market corrosion protection to premium acoustic management in electric architectures. Segmentation reveals how formulation chemistry, application site, and supply channel each reshape specification priorities and margin structures.
Product Type:
Use-case spectrum spans acoustic damping in passenger vehicles through chemical resistance in commercial chassis systems.
- Rubberized:These coatings combine SBR or NBR polymers with asphalt extenders at 1,000-2,000 micron dry-film thickness, delivering superior stone-chip absorption and NVH reduction. Mass-market OEM assembly lines in Germany and the United States specify rubberized systems for their cost efficiency in high-volume production, though REACH VOC limits are forcing gradual water-based transitions.
- Polyurethane:Two-component aliphatic systems achieve 400% elongation and resist hydraulic fluids, making them essential for battery-electric vehicle underbody protection where thermal management fluid exposure occurs. Premium German EV manufacturers specify polyurethane for high-voltage component housings, prioritizing chemical resistance over acoustic properties.
- Wax-Based:Solvent-dispersed or water-emulsion wax systems provide temporary corrosion protection during vehicle shipping and storage, with lower durability than cured films.
- Asphalt:Bituminous formulations dominate heavy-duty commercial vehicle applications in cost-sensitive markets, offering basic moisture barriers at minimal material cost.
Established volume favors rubberized systems; emerging adoption favors polyurethane formulations.
End User:
Channel economics separate captive supply relationships from spot procurement in aftermarket refurbishment.
- OEMs:Direct specification by Volkswagen, Ford, and BYD locks in multi-year formulation supply agreements with coating manufacturers, creating high switching costs and dedicated technical service teams. OEM sustainability mandates in the European Union and China are accelerating water-based qualification timelines.
- Tier-1 Suppliers:Magna, Benteler, and Gestamp integrate coating application into chassis module assembly, purchasing formulations in bulk for captive application at their manufacturing facilities.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations purchase coatings through distributor channels with less technical support than direct OEM relationships.
- Aftermarket Providers:Independent repair shops and rust-proofing specialists apply spray-on or brushable systems for vehicle life extension, with demand concentrated in salt-belt US states and Canadian provinces.
Direct OEM channels command formulation continuity; aftermarket channels favor application convenience.
Application:
Site-specific performance requirements dictate film thickness, flexibility, and cure speed specifications.
- Chassis:The largest application site by volume, chassis coatings must withstand gravel impact at highway speeds while accommodating frame flex during vehicle operation. German OEMs specify 1,500-micron rubberized films for passenger car chassis, with polyurethane gaining share in battery-electric platforms.
- Wheel Wells:High-abrasion zones require rapid-cure formulations compatible with moving assembly line speeds, favoring solvent-based systems despite tightening EPA NESHAP thresholds.
- Fuel Tanks:Chemical resistance to gasoline and diesel permeation drives specification of specialized polyurethane or epoxy-modified coatings, with demand concentrated in internal combustion vehicle production.
- Body Panels:Lower film thickness requirements (500-800 microns) and cosmetic finish standards distinguish panel applications from structural underbody protection.
Structural protection dominates chassis volume; cosmetic refinement distinguishes panel applications.
Formulation:
Regulatory pressure and application equipment compatibility drive technology transitions across manufacturing geographies.
- Solvent-Based:Conventional systems achieve rapid cure and superior salt-spray resistance exceeding 1,000 hours, but EPA and REACH VOC limits are constraining new specification. Existing US and European OEM plants maintain solvent lines for platform continuity.
- Water-Based:Acrylic and polyurethane dispersions are gaining share fastest as OEM sustainability mandates tighten, though performance gaps in humidity resistance and cure speed persist. Chinese GB standards on industrial coating VOC content are accelerating domestic water-based adoption.
- Powder Coatings:Thermoset epoxy or hybrid powders serve specialized commercial vehicle applications where film thickness uniformity and zero-VOC profiles justify electrostatic application equipment investment.
- Thermal Spraying:Arc-sprayed zinc or aluminum coatings provide sacrificial corrosion protection for heavy-duty trucks and military vehicles, with niche demand in extreme-service environments.
Legacy performance favors solvent-based systems; regulatory compliance favors water-based expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German formulation clusters while Chinese manufacturing scale compresses margins across water-based product lines. Regulatory divergence between EPA NESHAP thresholds and REACH VOC limits creates asymmetric compliance burdens across Atlantic supply chains. Assembly plant location decisions in battery-electric vehicle production are redrawing regional demand maps.
United States
Domestic OEMs specify rubberized underbody coatings for light-truck platforms at Michigan and Tennessee assembly plants. EPA NESHAP hazardous air pollutant thresholds accelerate solvent-to-water formulation transitions at Ohio and Kentucky coating operations. Detroit-Windsor corridor technical centers validate 1,000-hour salt-spray performance for next-generation chassis protection systems.
Germany
Premium EV manufacturers in Bavaria and Baden-Württemberg demand polyurethane systems for battery enclosure protection. REACH authorization timelines for corrosion inhibitors force zirconium-based pretreatment qualification at Stuttgart-area R&D facilities. Wolfsburg and Ingolstadt assembly plants lock in multi-year supply agreements with captive coating formulators.
China
BYD and CATL expansion in Shenzhen and Changzhou drives specification of high-elongation polyurethane for thermal management zones. MEE GB standards on industrial coating VOC content accelerate water-based adoption across Yangtze River Delta manufacturing zones. Shanghai and Suzhou formulation plants serve both domestic OEMs and export qualification requirements.
India
Maruti Suzuki and Tata Motors expansion in Gujarat and Maharashtra creates localized coating demand for compact vehicle platforms. PLI scheme production-linked incentives attract component suppliers to Tamil Nadu and Haryana assembly corridors. Pune and Chennai technical centers adapt water-based formulations for tropical humidity resistance.
Japan
Toyota and Honda maintain specification discipline around acoustic-damping rubberized systems for hybrid platforms. METI carbon-neutral targets pressure Aichi and Shizuoka coating operations toward low-emission process transitions. Nagoya-area suppliers integrate underbody protection with lightweight structural adhesive applications.
Automotive Underbody Coatings Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and application equipment. The supplier base organizes around three archetypes: diversified chemical conglomerates with captive automotive divisions, focused coating formulators with OEM-direct relationships, and adhesive specialists extending into seam-sealing hybrids. Consolidation pressure concentrates among mid-scale European formulators facing dual REACH and carbon-border compliance costs. Strategic moves center on water-based R&D partnerships and regional qualification laboratory investments.
Within the diversified chemical tier, PPG Industries and Henkel occupy positions spanning direct OEM supply and Tier-1 module integration. Axalta Coating Systems represents the focused formulator archetype with concentrated automotive refinish and assembly plant relationships. 3M exemplifies materials science convergence, bridging adhesive technologies into underbody protection specifications. These anchors illustrate how supplier positioning stratifies between formulation ownership and application control.
| Leading Market Players |
|---|
| 3M |
| ThreeBond |
| PPG Industries |
| Jenolite |
| Lubrizol |
| Henkel |
| Sika |
| Axalta Coating Systems |
| Sherwin-Williams |
| Others |
Supply Flow & Price Mechanics
Stuttgart-area formulation clusters concentrate polyurethane resin capacity for premium EV specifications, translating supply scarcity into pricing leverage for German coating manufacturers serving Bavarian battery enclosure programs.
Pricing Analysis
Configured-to-order polyurethane systems for battery-electric platforms command 40-60% premiums over standard rubberized formulations for mass-market chassis protection. Price differentiation hinges on OEM certification tier and volume commitment scale, with direct assembly plant contracts securing locked pricing against spot procurement volatility. Cost compression in water-based product lines is intensifying because Chinese GB standards accelerate domestic manufacturing scale. Aftermarket refurbishment channels exhibit highest price sensitivity; premium German EV manufacturers show lowest sensitivity due to warranty liability considerations.
Supply Chain Analysis
Tier-1 contract manufacturers Magna, Benteler, and Gestamp hold captive application capacity across European and North American chassis module assembly. Geographic supply concentration centers on Germany, China, and the United States for both resin formulation and integrated module production. Raw material dependencies include propylene oxide, MDI isocyanates, and SBR/NBR polymer feedstocks. Single-source vulnerability in MDI supply from Chinese petrochemical complexes creates structural risk exposure. Distribution runs through direct OEM specification channels with dedicated technical service teams rather than merchant distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive underbody coatings track vehicle production cycles, with recovery momentum tied to battery-electric platform ramp schedules at major OEM assembly networks.
For Market Incumbents: Entrench specification continuity through multi-year formulation supply agreements with Volkswagen, Ford, and BYD platform engineering teams. Deepen backward integration into water-based resin production to offset REACH compliance cost burdens and secure margin stability against petrochemical feedstock volatility. For New Entrants and Emerging Players: Pursue India's PLI scheme corridors in Gujarat and Tamil Nadu where localized coating demand outpaces established supplier technical service presence. Target compact vehicle platform aftermarket channels with humidity-adapted water-based formulations as the most penetrable white space, leveraging distributor partnerships for rapid geographic coverage without OEM qualification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dual REACH and carbon-border compliance costs will compress mid-scale European formulator margins below sustainable thresholds. Acquisition targets include specialized adhesive-coating hybrid developers with seam-sealing IP and established OEM technical relationships. Monitor water-based qualification completion rates at Stuttgart and Wolfsburg assembly plants as the critical inflection signal for formulation technology displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Formulation Scale-Up | PPG Industries and Henkel accelerate R&D partnerships to meet EPA NESHAP and REACH VOC thresholds at US and European OEM plants. |
| Battery Enclosure Protection Qualification | Polyurethane system validation for BYD and CATL thermal management zones commands premium positioning in Shenzhen manufacturing corridors. |
| Regional Laboratory Investment | Localized testing infrastructure in Pune and Chennai supports water-based adaptation for tropical humidity resistance in Indian compact vehicle platforms. |
| Seam-Sealing Hybrid Development | Adhesive-coating convergence extends protection into structural joints previously treated as separate operations at German premium EV manufacturers. |
| Chrome-Free Pretreatment Transition | Zirconium-based and silane alternatives replace chromium trioxide corrosion inhibitors under REACH authorization deadlines at Czech coating operations. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, coating formulator R&D directors, and aftermarket distributor operations anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and vehicle production databases. Bottom-up segmentation modeling triangulated with top-down market sizing across formulation chemistry, application site, and supply channel dimensions.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from production volume forecasts, coating content per vehicle trajectories, and price elasticity modeling for solvent-to-water formulation transitions. Industry-specific inputs included EPA NESHAP compliance calendar phasing, REACH authorization timelines for corrosion inhibitors, and Chinese GB standard implementation schedules.
Sensitivities concentrate around battery-electric platform ramp delays, petrochemical feedstock volatility in MDI and propylene oxide markets, and divergent regional compliance calendar synchronization. Forecasts reflect documented assumptions on OEM sustainability mandate enforcement intensity and water-based performance gap closure rates. Quarterly review of qualification completion timelines at German premium EV manufacturers and Indian PLI scheme capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Seat Covers Market