
 Automotive Front Windshield Market | 2026-2036
Automotive Front Windshield Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Front Windshield Market Intelligence
The integration of heads-up display (HUD) and advanced sensor compatibility is rotating the market toward higher-value laminated glass products. Saint-Gobain Sekurit leverages its global manufacturing footprint to supply major European and North American automotive OEMs. Fuyao Glass Industry Group anchors its position through scale in the Chinese market and targeted international expansion. AGC Inc. competes on technology, specializing in high-performance glass with embedded electronic functionalities for advanced vehicles.
An automotive front windshield is a safety glass component designed to provide structural integrity and clear visibility for vehicle occupants. It is typically constructed from laminated glass, which consists of two layers of glass bonded with a polyvinyl butyral (PVB) interlayer to prevent shattering. Laminated glass constitutes the dominant product type, while solar control glass represents a high-margin niche. While sedans form a mature base, demand from the SUV vehicle type is the primary growth engine.
Safety and quality standards are governed by regulations such as the US Federal Motor Vehicle Safety Standard (FMVSS) 205 and Europe's ECE R43. These mandates define requirements for light transmission, impact resistance, and optical clarity, directly influencing material selection and manufacturing processes. Key strategic decisions for suppliers will revolve around investing in production capacity for smart glass and HUD-compatible windshields.
Market Dynamics
The automotive front windshield market's evolution is governed by the technical demands of integrating Advanced Driver-Assistance Systems (ADAS). This shift transforms the windshield from a passive safety item into an active, electronically integrated component, creating new value tiers and manufacturing complexities.
Growth Catalysts
- ADAS Proliferation:The mandatory inclusion of ADAS features in new vehicles, driven by safety ratings, necessitates windshields with precise optical quality and mounting brackets for cameras and sensors, increasing the value per unit.
- SUV and Crossover Demand:Continued consumer preference for larger vehicles like SUVs, particularly in China and North America, directly increases the average size and complexity of windshields, boosting overall material volume and value.
- Stringent Safety Standards:Regulations such as the US FMVSS 205 and Europe's ECE R43 mandate high-impact resistance and optical clarity, reinforcing the dominance of high-performance laminated glass and limiting lower-quality alternatives.
Market Restraints
- Raw Material Cost Volatility:Fluctuations in the price of polyvinyl butyral (PVB) and specialty resins, key interlayer materials, directly impact manufacturer margins and can lead to price instability in the replacement market.
- ADAS Recalibration Complexity:The requirement for precise, equipment-intensive recalibration of ADAS sensors after a windshield replacement creates a significant cost and technical barrier in the automotive aftermarket, slowing replacement cycles.
- High Capital Investment:Manufacturing large, geometrically complex windshields compatible with heads-up displays requires substantial capital expenditure in specialized molding, coating, and laminating equipment, restricting market entry.
Strategic Opportunities
- Smart Glass Integration:Developing windshields with embedded, electronically tintable films or particle-based smart glass offers a new frontier for solar control and privacy, creating a high-margin opportunity beyond basic laminated glass.
- Acoustic Performance Niche:Expanding the use of acoustic PVB interlayers to reduce wind and road noise provides a clear value proposition for the growing electric vehicle segment and luxury models where cabin quietness is a key differentiator.
- Aftermarket Specialization:A specialized aftermarket for certified, ADAS-compatible replacement windshields is emerging, offering higher margins for installers and distributors who invest in the necessary calibration technology and technician training.
Industry Challenges
- Zero-Defect Manufacturing:The integration of fine antennas, heating elements, and sensor brackets into the glass assembly drastically increases manufacturing complexity, making the achievement of zero-defect quality a persistent operational challenge.
- Technician Skill Gap:A shortage of trained technicians in the aftermarket who are qualified to handle both the physical installation and the electronic recalibration of ADAS-equipped windshields creates a service bottleneck.
- Logistical Hurdles:The increasing size, curvature, and fragility of modern windshields for vehicles like SUVs and trucks complicate logistics, raising costs for packaging, shipping, and handling while increasing the risk of damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Front Windshield Market |
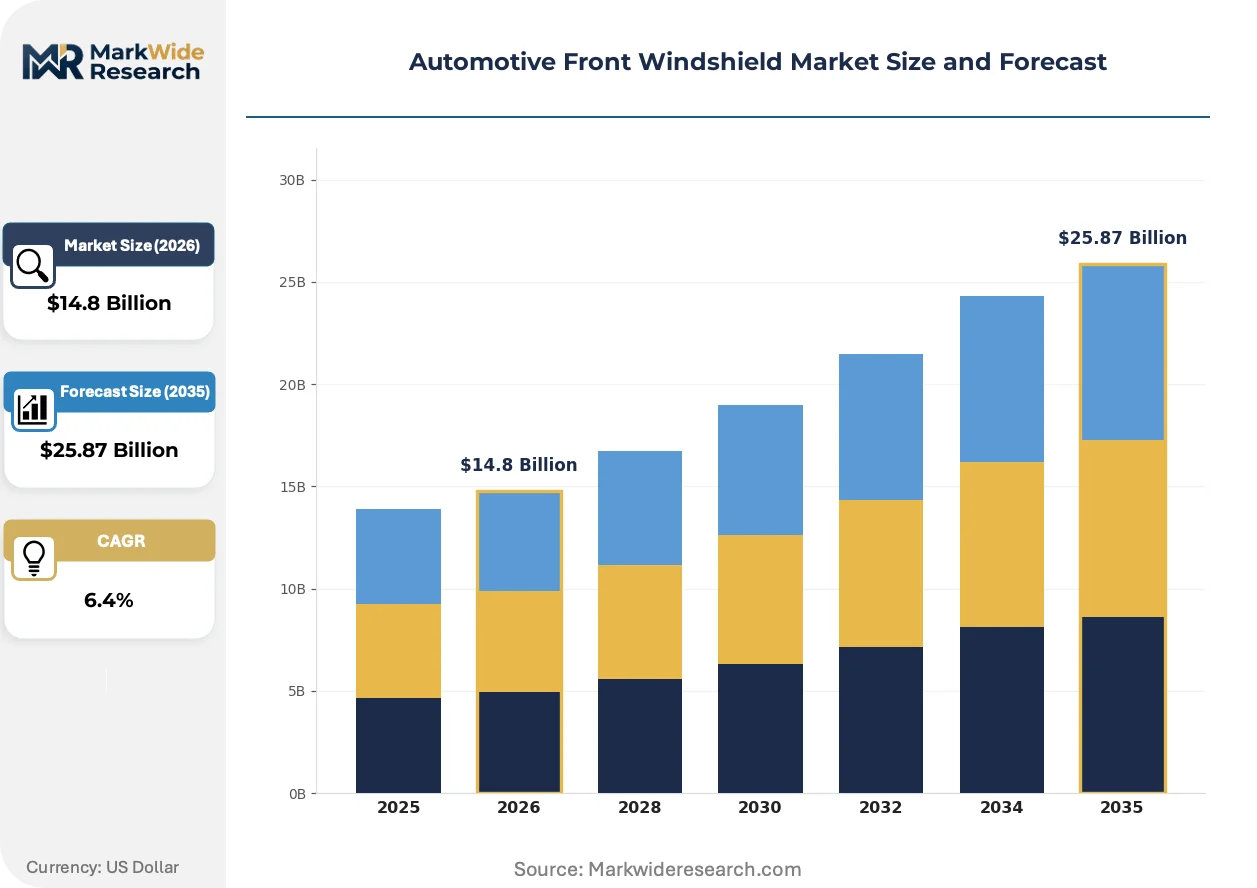
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Polycarbonate, Solar Control Glass Installation Method: OEM Installation, Aftermarket Installation, DIY Kits, Professional Services Vehicle Type: Sedan, SUV, Hatchback, Coupe Safety Standard: FMVSS 205, ECE R43, DOT, ISO 9001 |
| Companies Covered | NSG Group, Xinyi Glass Holdings Limited, AGC Inc., Corning Incorporated, PPG Industries, Saint-Gobain Sekurit, Guardian Industries, Vitro Automotive Glass, Fuyao Glass Industry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Front Windshield Market Strategic Shifts & Innovations
The fundamental role of the windshield is transforming from a passive barrier to an active interface for vehicle data and control. This evolution is driven by the convergence of material science, electronics, and software, creating a new competitive landscape defined by technological capability.
Augmented reality heads-up displays (AR-HUDs) project dynamic navigation and safety information directly onto the driver's field of view. This technology is being adopted rapidly by luxury and premium automotive brands, with a clear roadmap for inclusion in higher-volume segments. The integration of AR-HUDs is bifurcating the product landscape into basic windshields and high-value, optically precise display surfaces that command premium pricing.
European Union's General Safety Regulation (GSR) mandates several ADAS features, including intelligent speed assistance, in all new vehicles. This policy directly forces the integration of forward-facing cameras, which are predominantly mounted on the front windshield assembly. Consequently, the passenger car segment in Europe is seeing a rapid standardization of ADAS-ready windshields, even for entry-level models, compelling suppliers to upgrade their entire product portfolios.
Vehicle buyers increasingly expect a seamless, technology-forward user experience, viewing the windshield as a critical part of the car's digital cockpit. This behavioral shift elevates the importance of windshield features during the vehicle design process, involving software and user interface teams in what was once a purely structural decision. This trend is most pronounced in the electric vehicle market, where minimalist interiors amplify the functional and aesthetic importance of large, feature-rich glass surfaces.
Automotive Front Windshield Market Segmentation
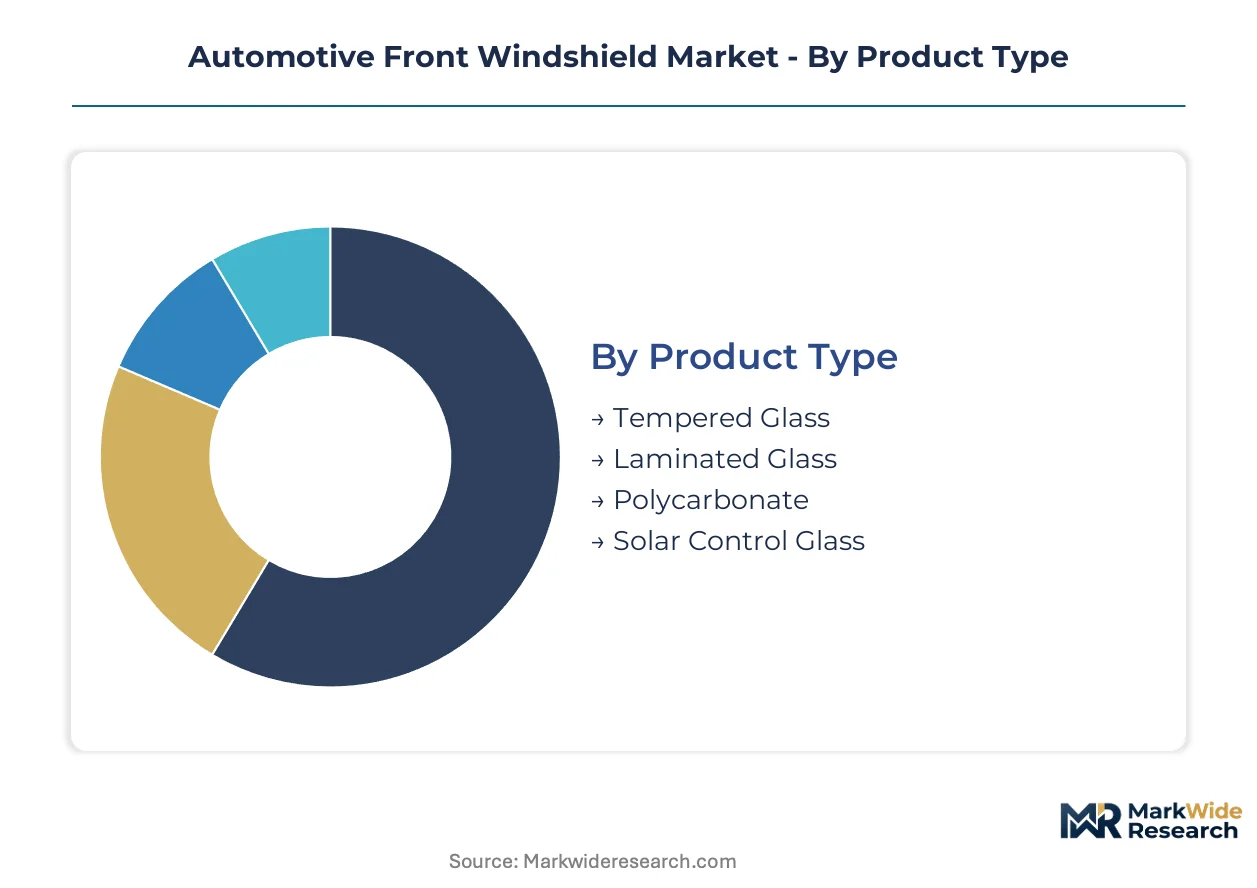
The automotive front windshield market segments reflect the diverse requirements of vehicle manufacturers and end-users, driven by evolving safety standards and technological advancements. Understanding these distinct segments is crucial for suppliers to align their product development and market strategies effectively.
Product Type:
Substitution pressure across product types is forcing manufacturers to innovate beyond traditional offerings.
- Laminated Glass:This product consists of two glass layers bonded by a polyvinyl butyral (PVB) interlayer, crucial for safety by preventing shattering and maintaining structural integrity. Laminated glass dominates new vehicle installations, particularly in regions with stringent safety standards like Europe.
- Solar Control Glass:This type features specialized coatings or interlayers to reduce heat gain and UV radiation within the cabin, enhancing passenger comfort and energy efficiency. Demand for this high-margin niche product concentrates in premium vehicle segments and electric vehicles.
- Tempered Glass:This safety glass is rapidly cooled during manufacturing, increasing its strength and causing it to break into small, blunt pieces upon impact.
- Polycarbonate:This lightweight, impact-resistant thermoplastic offers design flexibility for specialized applications in concept vehicles and niche markets.
Laminated Glass anchors the volume base while Solar Control Glass gains share at the steepest rate.
Installation Method:
Cost structures vary significantly across installation methods, reflecting differences in labor, equipment, and certification requirements.
- OEM Installation:This process integrates windshields directly into new vehicles on the assembly line, ensuring precise fitment and calibration for integrated ADAS components. Initial vehicle production volumes in major automotive hubs like China drive demand for OEM-supplied units.
- Aftermarket Installation:This involves replacing damaged windshields in vehicles already on the road, often requiring specialized tools and recalibration services for ADAS sensors. Demand for aftermarket services is driven by insurance claims and vehicle longevity across North America and Europe.
- DIY Kits:These kits provide basic tools and instructions for individuals to replace windshields, primarily for older vehicles without complex electronic integrations.
- Professional Services:Specialized technicians perform complex installations and ADAS recalibrations, ensuring vehicle safety and compliance with regulatory standards.
OEM Installation accounts for the largest volume of units, while Aftermarket Installation commands higher per-unit service value.
Vehicle Type:
Application-specific design considerations influence windshield dimensions and feature integration across different vehicle types.
- SUV:These vehicles require larger, more complex windshields, often incorporating advanced features for ADAS and heads-up displays due to consumer preference for spacious interiors. Rapid expansion of SUV production in China and North America drives significant volume for this segment.
- Sedan:This mature segment forms a substantial base for windshield demand, focusing on cost-effective solutions and established production processes. Established markets in Europe and Japan continue to produce high volumes of sedan vehicles.
- Hatchback:These compact vehicles often feature steeply raked windshields, influencing optical requirements and material usage.
- Coupe:Windshields for coupes prioritize sleek design and aerodynamic performance, often with unique curvatures and smaller dimensions.
SUV demand acts as the primary growth engine for the market, while Sedans maintain a consistent volume base.
Safety Standard:
Maturity of regulatory frameworks defines baseline requirements and influences material selection across different safety standards.
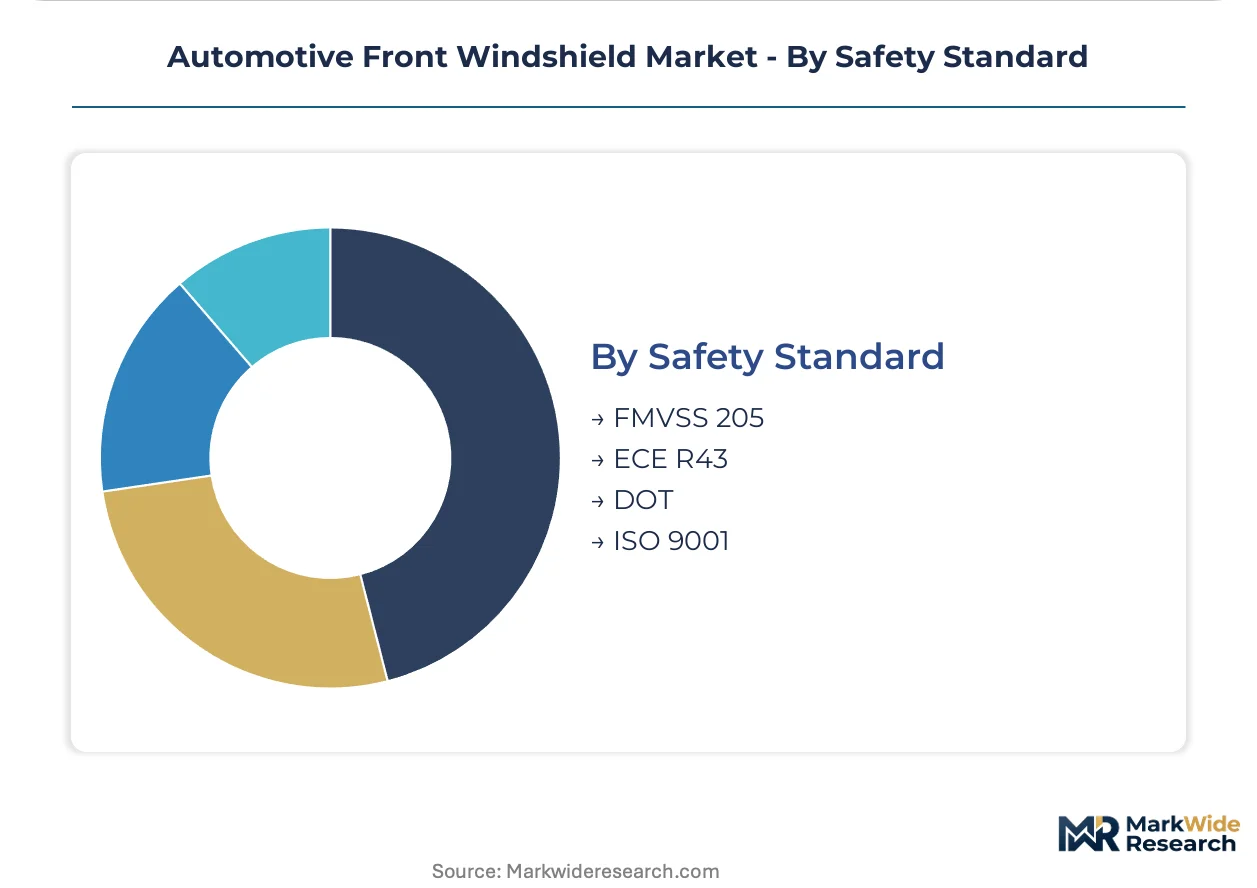
- FMVSS 205:This US Federal Motor Vehicle Safety Standard governs light transmission, impact resistance, and optical clarity for automotive glazing materials. Compliance with FMVSS 205 is mandatory for all vehicles sold in the United States, impacting material choices and manufacturing processes.
- ECE R43:This European regulation establishes uniform provisions concerning the approval of safety glazing materials and their installation on vehicles. European automotive OEMs adhere strictly to ECE R43, ensuring high performance and safety across their product lines.
- DOT:This certification mark indicates compliance with US Department of Transportation safety standards for automotive components.
- ISO 9001:This international standard specifies requirements for a quality management system, ensuring consistent product quality and customer satisfaction in manufacturing processes.
Compliance with FMVSS 205 and ECE R43 is fundamental for market access in major automotive regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive front windshield market's supply chain concentration reflects global vehicle production hubs. Major manufacturing capacity for advanced windshields aligns with regions experiencing high demand for ADAS-equipped vehicles and SUVs. This geographic alignment ensures efficient delivery to large automotive original equipment manufacturers.
China
Demand for larger SUV windshields and ADAS integration drives significant market expansion in China. The MIIT promotes domestic automotive innovation, influencing glass specifications for new energy vehicles. Shanghai's automotive industrial zone sees extensive production of advanced windshields for both local and international brands.
United States
Consumer preference for SUVs and the mandatory inclusion of ADAS features bolster the US market for complex windshields. FMVSS 205 mandates stringent safety and optical clarity standards for all automotive glazing. Michigan's automotive corridor, particularly around Detroit, remains a hub for windshield R&D and OEM supply.
Germany
The premium automotive segment and rapid ADAS adoption in Germany necessitate high-value laminated and HUD-compatible windshields. ECE R43 governs material approval, ensuring superior performance and safety across European vehicles. Bavaria's automotive clusters, including Munich, are centers for advanced glass manufacturing and sensor integration.
Japan
Advanced driver-assistance systems and electric vehicle production propel demand for sophisticated windshields in Japan. METI encourages innovation in automotive components, supporting the development of smart glass technologies. Nagoya's automotive manufacturing region houses key suppliers for high-performance and lightweight windshields.
India
Rising vehicle production, particularly SUVs, and evolving safety regulations stimulate growth in India's windshield market. BIS standards for automotive glass are becoming more rigorous, pushing for higher quality products. Chennai's automotive hub is witnessing increased investment in windshield manufacturing to serve local and export markets.
Automotive Front Windshield Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the automotive front windshield market. The market exhibits a tiered structure, with a few large, globally integrated manufacturers dominating the premium and OEM segments, ensuring precise fitment for new vehicle production. These players often pursue strategic partnerships for ADAS integration and invest heavily in capacity expansion for smart glass and HUD-compatible glass production. Smaller, regional specialists frequently focus on aftermarket services or niche applications, serving replacement demand.
Scale-driven manufacturers like Fuyao Glass Industry Group anchor a significant portion of the global market, particularly in high-volume regions such as China, where its scale supports targeted international expansion. Saint-Gobain Sekurit exemplifies a globally diversified supplier, leveraging its extensive manufacturing footprint to serve major European and North American automotive OEMs with higher-value laminated glass products. AGC Inc. occupies a position among technology-focused companies, specializing in high-performance glass with embedded electronic functionalities for advanced vehicles, including those with augmented reality heads-up displays.
| Leading Market Players |
|---|
| NSG Group |
| Xinyi Glass Holdings Limited |
| AGC Inc. |
| Corning Incorporated |
| PPG Industries |
| Saint-Gobain Sekurit |
| Guardian Industries |
| Vitro Automotive Glass |
| Fuyao Glass Industry Group |
| Others |
Cost & Logistics Intelligence
Massive production scale and capacity utilization across major automotive hubs shape both supply concentration and price floors for automotive front windshields. This dynamic influences material sourcing and manufacturing investment decisions.
Pricing Analysis
US Federal Motor Vehicle Safety Standard (FMVSS) 205 dictates the pricing tier structure for windshields in North America. Pricing is primarily contract-based long-term offtake for original equipment manufacturers, while the aftermarket operates on a transactional model. Price differentiation stems from ADAS compatibility and specialized features like heads-up display integration. Cost compression in the aftermarket is intensifying due to raw material cost volatility. DIY consumers represent the most price-sensitive segment, seeking basic replacements, while OEMs prioritize performance and compliance over cost.
Supply Chain Analysis
Lead times for specialized ADAS-compatible windshields are extending due to manufacturing complexity and integration requirements. Geographic supply concentration centers on China, Germany, and Japan, reflecting major automotive production regions. The supply chain draws from polyvinyl butyral (PVB) and specialty resins as critical raw material dependencies. Single-source vulnerability for advanced sensor brackets represents a structural risk. Distribution channels primarily run direct to OEMs for new vehicles and through specialized aftermarket distributors for replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive front windshield market is undergoing a platform-economics inflection, driven by the integration of ADAS ecosystems and evolving digital cockpit designs.
For Market Incumbents: Secure long-term supply agreements for specialized glass and sensor components to mitigate raw material volatility. Deepen R&D investment in smart glass and augmented reality heads-up display technologies to counter emerging material entrants. Pursue strategic acquisitions of ADAS calibration software firms to control the aftermarket service value chain. Certification investment for ECE R43 and FMVSS 205 remains paramount for market access.
For New Entrants and Emerging Players: A service-layer gap exists in specialized ADAS recalibration services and certified aftermarket installations. Target the growing electric vehicle segment with lightweight polycarbonate or advanced solar control solutions. Focus on technology licensing partnerships with smaller OEMs seeking rapid ADAS integration. Develop niche aftermarket solutions for complex SUV and truck windshield replacements, emphasizing technician training.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors companies with strong intellectual property in smart glass, sensor integration, and advanced lamination processes. Long-term viability is anchored in the sustained proliferation of ADAS features and the growth of electric vehicles. Acquisition targets should include specialized software firms focused on ADAS calibration and advanced material startups. The standardization of AR-HUD interfaces across vehicle segments is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Smart Glass R&D | Develop high-margin products with embedded electronic functionalities for premium and EV segments. |
| Acquire ADAS Calibration Specialists | Control the critical aftermarket service value chain and ensure precise sensor recalibration. |
| Expand Global Manufacturing Footprint | Optimize logistics and reduce delivery times for major automotive original equipment manufacturers. |
| Develop Acoustic PVB Interlayers | Address the growing demand for cabin quietness in electric vehicles and luxury models. |
| Standardize ADAS-Ready Windshields | Meet regulatory mandates and accelerate market penetration across all passenger car segments. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved discussions with automotive OEM engineers, Tier 1 glass manufacturers, aftermarket service providers, and regulatory body representatives. This qualitative input was triangulated with quantitative data from automotive production statistics, government safety standards such as FMVSS 205 and ECE R43, patent filings for smart glass technologies, and industry association reports, ensuring a comprehensive view.
The forecasting boundary extends across the analysis window, modeling market dynamics from a bottom-up and top-down perspective. Segmentation dimensions modeled include product type, installation method, vehicle type, safety standard compliance, and regional demand patterns, alongside ADAS feature integration rates. Compound Annual Growth Rates (CAGRs) were derived by projecting historical trends and anticipated technological shifts. Key forecast inputs included global vehicle production forecasts and projected ADAS penetration rates.
Underlying assumptions cover stable macroeconomic conditions and consistent regulatory enforcement, with deviation risk concentrated in rapid shifts in ADAS technology development or unforeseen raw material supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Car Covers Market