
 Automotive Fridge Market | 2026-2036
Automotive Fridge Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fridge Market Insights
Market Context
The automotive fridge category is rebalancing between premium compressor units and commodity thermoelectric alternatives as price-performance thresholds diverge. Dometic leverages its European manufacturing footprint to sustain margin-rich built-in systems for RV OEMs. Engel anchors the premium portable segment through deep channel control in Australian and North American overlanding markets. Alpicool competes aggressively on cost, dominating Chinese domestic e-commerce platforms with direct-to-consumer compressor models.
Technical Definition and Segment Structure
An automotive fridge is a thermally insulated, vibration-resistant cooling appliance engineered for mobile environments, typically operating on 12V DC vehicle power with compressor or thermoelectric cooling cycles maintaining temperatures between minus 18 degrees Celsius and 10 degrees Celsius for food and beverage preservation during transit. Compressor fridges lead value generation due to superior energy efficiency and freezing capability, while thermoelectric variants occupy the low-capacity, price-sensitive accessory tier. Fleet operators represent the fastest-growing end-user category as refrigerated last-mile delivery expands, and solar power compatibility is emerging as a margin pool in the power source dimension.
Regulatory Frame and Outlook
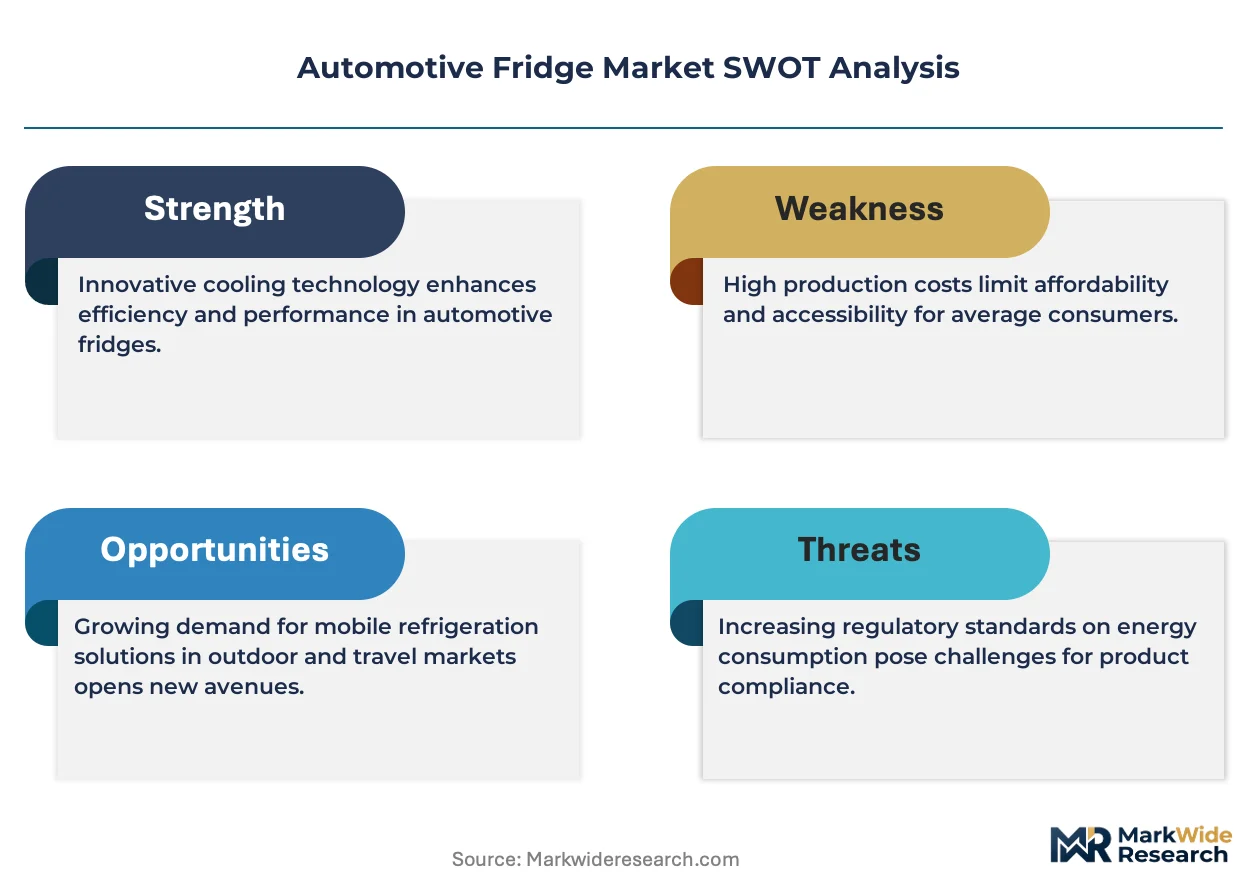
The EU F-Gas Regulation constrains refrigerant selection for compressor units sold in Europe, while NHTSA electrical safety standards govern 12V system integration in the United States. China's GB standards and MIIT vehicle equipment certification shape domestic market access requirements. Stakeholders must monitor evolving energy efficiency mandates and refrigerant phase-down schedules to anticipate product redesign cycles and regional compliance costs.
Market Dynamics
Fleet electrification timelines are compressing product development cycles as compressor efficiency and DC power management become critical specifications for commercial vehicle OEMs.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant constraints are accelerating R&D investment in hydrocarbon and CO2-based cooling systems for European-bound units.
- Last-mile delivery fleet professionalization:Temperature-controlled parcel volume is pulling compressor-based systems into light commercial vehicles at scale previously reserved for heavy trucks.
- Solar-DC compatibility:Photovoltaic integration with 12V vehicle architectures is opening off-grid applications in Australian and South African overlanding segments.
Market Restraints
- Compressor supply concentration:Secop and Danfoss dominate variable-speed DC compressor supply, creating single-source vulnerability for mid-tier assemblers.
- Lithium battery cost volatility:Energy storage requirements for multi-day off-grid operation tie product economics to cell commodity cycles.
- Thermoelectric substitution in price-sensitive tiers:Peltier modules retain share in sub-20-liter personal coolers despite inferior efficiency.
Strategic Opportunities
- India commercial vehicle integration:Cold-chain infrastructure gaps in pharmaceutical and dairy distribution create first-mover positioning for compressor units certified to BIS and AIS standards.
- Vehicle-to-load (V2L) bidirectional power:Electric pickup trucks from Ford, Rivian, and BYD are normalizing external appliance power as a factory feature.
- China MIIT new energy vehicle equipment certification:Domestic OEM integration pathways are formalizing for suppliers meeting GB/T electrical safety and electromagnetic compatibility requirements.
Industry Challenges
- Thermal management engineering scarcity:Cross-functional expertise spanning refrigeration physics, automotive electrical systems, and vibration engineering concentrates in Tier-1 automotive suppliers.
- Multi-jurisdiction certification sequencing:Parallel UL, CE, and CCC approval timelines delay product launches by 8-14 months for global SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fridge Market |
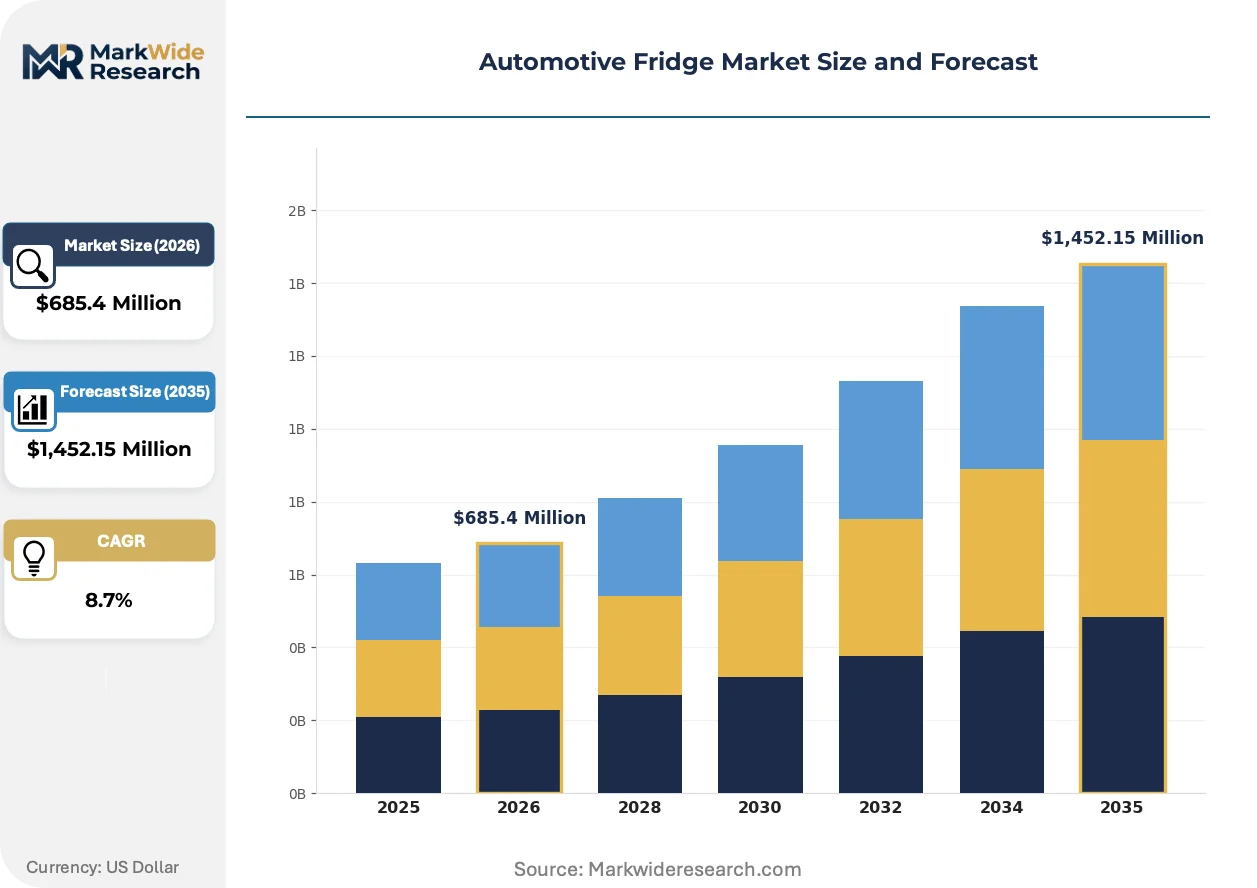
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Fridges, Built-in Fridges, Compressor Fridges, Thermoelectric Fridges Power Source: 12V Power Adapter, 240V AC, Solar Power, Battery Operated End User: Car Owners, Fleet Operators, RV Users, Delivery Services Capacity: 20L, 30L, 40L, 50L |
| Companies Covered | Dometic, Engel, ARB, Mobicool, Whynter, IndelB, Alpicool, Igloo, Koolatron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fridge Market Trends and Innovations
Power electronics miniaturization and refrigerant chemistry evolution are converging to redefine portable cooling performance benchmarks while regulatory pressure on fluorinated gases accelerates hardware redesign.
Variable-speed DC compressors with brushless motor control are absorbing thermal load fluctuations more efficiently than fixed-speed alternatives. Food delivery fleet operators in China and Germany are specifying these units for route profiles with frequent door openings. The technology is absorbing market share from thermoelectric systems in the 25-40 liter capacity band.
The EU F-Gas Regulation mandates an 80% reduction in hydrofluorocarbon consumption by 2030 against 2015 baselines. Compressor manufacturers are qualifying propane and isobutane alternatives with revised safety architectures. European-market automotive fridges face the most aggressive redesign timeline, with 2027 model-year products requiring full refrigerant transition.
Direct-to-fleet procurement is displacing traditional aftermarket distribution for commercial vehicle specifications. Large logistics operators in the United States and Brazil are issuing unified technical requirements to manufacturers, bypassing distributor networks. This pattern concentrates order volume with suppliers capable of API-integrated fleet management system compatibility.
Automotive Fridge Market Segmentation
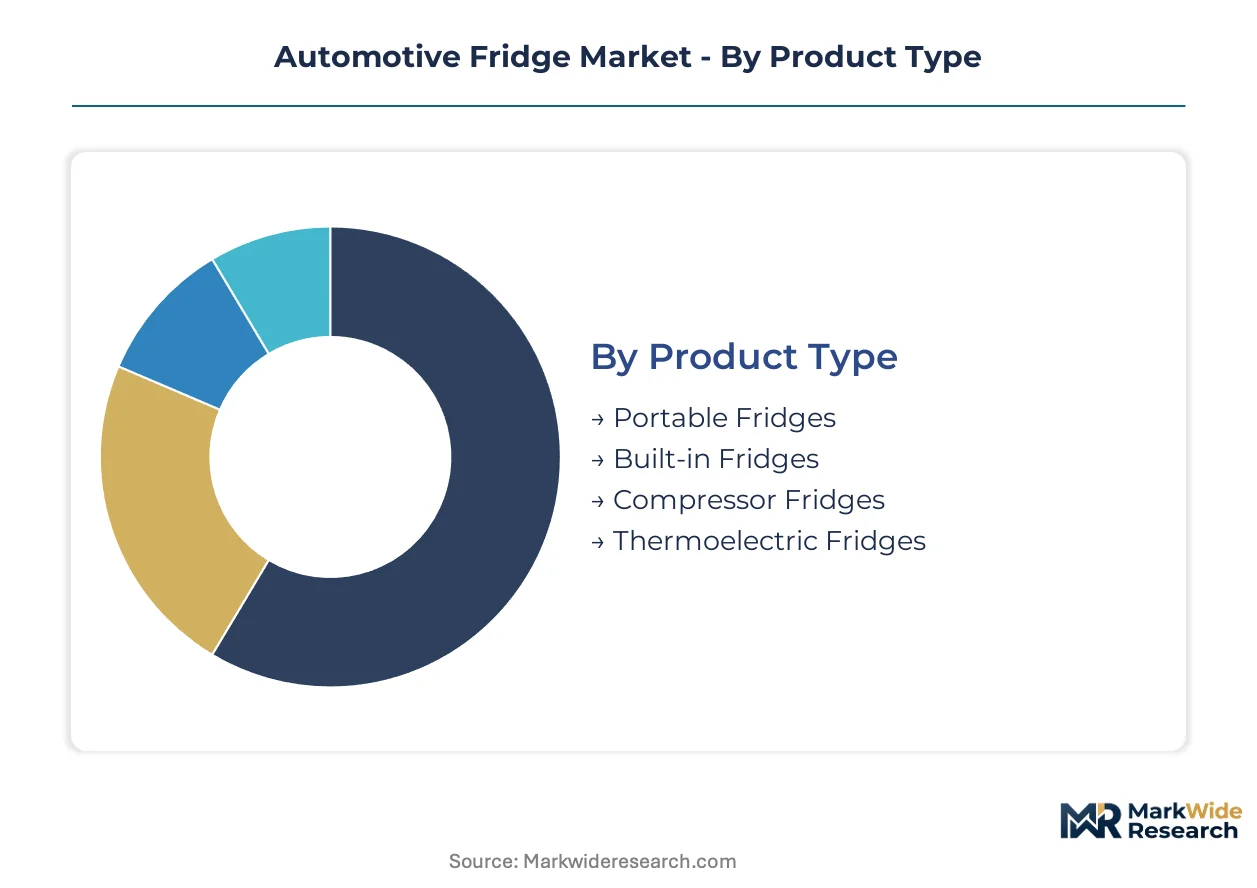
Automotive fridge segmentation reveals divergent engineering priorities across mobility contexts. Product architecture, power integration, and capacity specifications map directly to distinct buyer workflows and vehicle integration requirements.
Product Type:
The customization-vs-standardization spectrum stretches from purpose-built OEM integration to universal aftermarket portability.
- Portable Fridges:Self-contained units with vibration-resistant housings and grab handles for transfer between vehicles. Demand clusters in Australian overlanding and Chinese outdoor recreation markets where dual 12V/240V power flexibility commands premium positioning.
- Built-in Fridges:Fixed-installation units dimensioned for RV galley modules and marine cabinetry. European OEMs specify these through Dometic's manufacturing footprint for factory-fit motorhome configurations.
- Compressor Fridges:Variable-speed DC cooling systems achieving minus 18 degrees Celsius with superior energy efficiency. Fleet operators in Germany and Brazil specify these for pharmaceutical last-mile routes.
- Thermoelectric Fridges:Peltier-based cooling without moving parts, limited to 20 degrees Celsius below ambient. Personal vehicle owners in price-sensitive tiers accept efficiency trade-offs for sub-100 dollar entry points.
Most installed capacity flows through Compressor Fridges. Expansion is steepest in Built-in Fridges.
Power Source:
Electrical architecture choices segment buyers by grid dependency and off-grid autonomy requirements.
- 12V Power Adapter:Direct vehicle battery connection through cigarette lighter or hardwired installation. Dominates light commercial vehicle specifications where engine alternator charging sustains continuous operation.
- 240V AC:Shore power compatibility for RV park hookups and garage storage preconditioning. European campsite infrastructure density supports this as a standard secondary input.
- Solar Power:Photovoltaic panel integration with MPPT charge controllers for multi-day autonomy. Australian and South African overlanding segments specify these for remote track traversal beyond fuel range.
- Battery Operated:Lithium iron phosphate packs enabling portable operation independent of vehicle power. Chinese domestic brands compete on cell cost integration for camping enthusiasts.
Most installed capacity flows through 12V Power Adapter. Expansion is steepest in Solar Power.
End User:
Customer type determines volume scale, technical specification intensity, and procurement channel structure.
- Car Owners:Individual consumers purchasing through automotive aftermarket and e-commerce channels. Personal vehicle integration emphasizes compact footprint and dual-use home-vehicle flexibility.
- Fleet Operators:Logistics companies deploying temperature-controlled units across light commercial vehicle pools. United States and Brazilian operators issue unified technical requirements bypassing traditional distribution.
- RV Users:Recreational vehicle owners requiring galley-integrated food preservation for extended habitation. Factory-fit specifications dominate over aftermarket retrofit.
- Delivery Services:Last-mile pharmaceutical and meal-kit operators with strict temperature compliance mandates. Chinese cold-chain professionalization pulls compressor-based systems into electric van platforms.
Most installed capacity flows through Car Owners. Delivery Services are expanding most quickly.
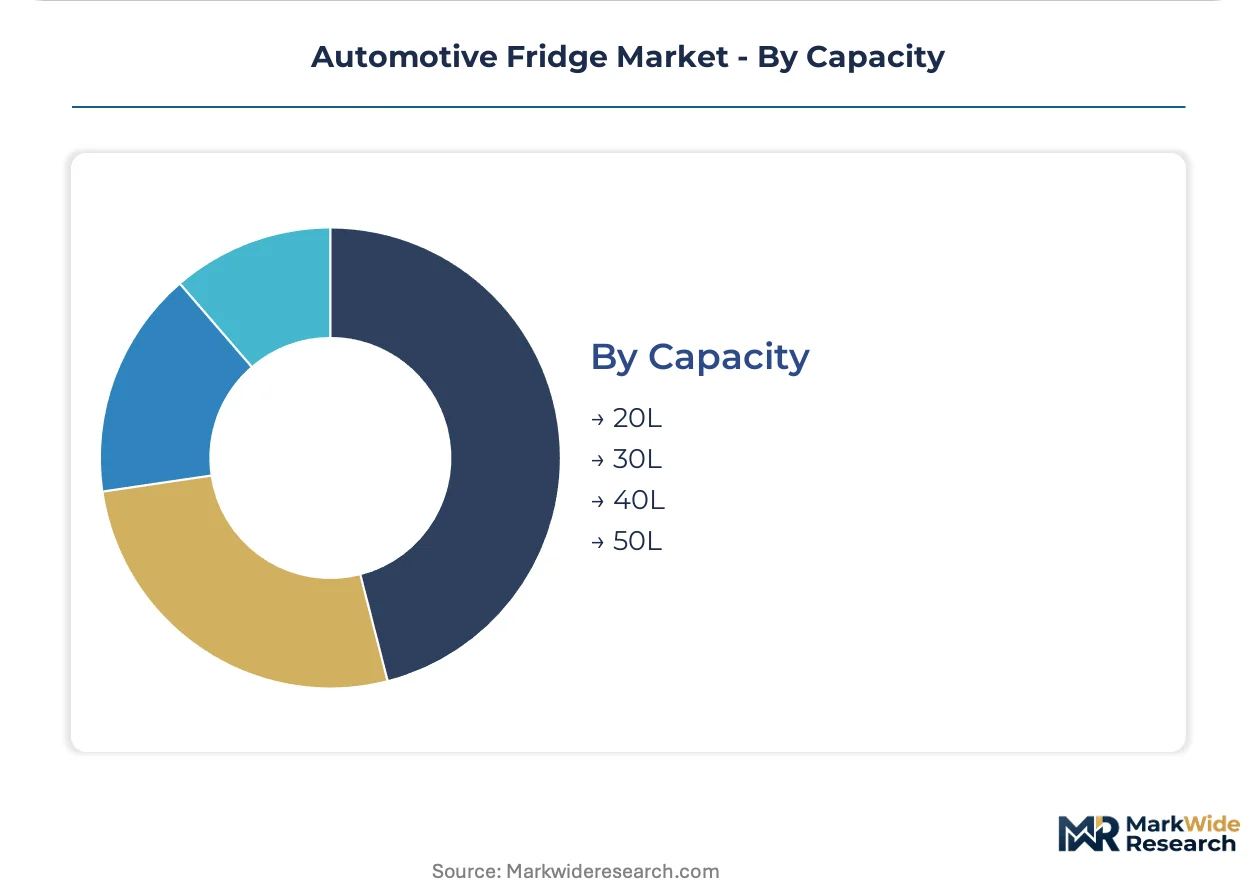
Capacity:
Volume specifications align with trip duration, occupancy count, and cargo space constraints.
- 20L:Compact units fitting passenger footwells or rear seat gaps. Personal commuters and solo overlanders prioritize vehicle interior placement flexibility.
- 30L:Mid-size configuration balancing weekend provisioning with trunk space preservation. Couples and small families dominate this specification tier.
- 40L:Extended-trip capacity for family overlanding and commercial route coverage. Australian market preference reflects multi-week remote travel patterns.
- 50L:Maximum portable volume before fixed-installation economics prevail. Fleet operators and large RV configurations specify this threshold for full-route autonomy.
Most installed capacity flows through 30L. Expansion is steepest in 40L.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in automotive thermal management concentrate in Germany's industrial corridor, China's Pearl River Delta, and the US Midwest, anchoring regional design capabilities for mobile refrigeration systems.
United States
Fleet electrification by Amazon, FedEx, and UPS drives compressor fridge integration into electric delivery vans. NHTSA electrical safety standards govern 12V system certification for commercial vehicle installations. Detroit's automotive supplier cluster hosts thermal management engineering centers serving OEM integration programs.
Germany
Last-mile pharmaceutical logistics operators mandate temperature-controlled cargo compliance for insulin and vaccine distribution. The EU F-Gas Regulation accelerates hydrocarbon refrigerant transition timelines for compressor units. Stuttgart's automotive engineering ecosystem supports Dometic's built-in RV refrigerator development for European motorhome OEMs.
China
Domestic outdoor recreation expansion and cold-chain delivery professionalization pull volume simultaneously through e-commerce and fleet channels. MIIT vehicle equipment certification and GB/T electrical safety standards shape market access requirements. Shenzhen's electronics manufacturing base supplies variable-speed DC compressors and power management components.
Australia
Remote track traversal beyond fuel range drives solar-DC compatible portable fridge demand in overlanding segments. TGA product safety standards align with automotive electrical system certifications. Melbourne and Brisbane distribution hubs serve the mining fly-in-fly-out workforce provisioning market.
Brazil
Pharmaceutical cold-chain gaps in regional distribution create compressor unit opportunities for light commercial vehicle retrofit. ANVISA temperature compliance mandates for biological products extend to transport equipment. São Paulo's logistics corridor concentrates fleet operator procurement decisions for temperature-controlled last-mile expansion.
Automotive Fridge Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the automotive fridge value chain. Integrated manufacturers controlling compressor supply and cabinet fabrication face pressure from assemblers sourcing modular components. Three archetypes dominate: European built-in specialists, Chinese cost-optimized portable producers, and premium overlanding brands. Competitive moves center on refrigerant transition R&D partnerships and direct-to-fleet procurement channel bypass.
Among European integrated manufacturers, Dometic anchors the built-in RV segment through factory-fit OEM relationships. Engel exemplifies the premium portable archetype with deep channel control in Australian and North American overlanding markets. Alpicool occupies the cost-optimized position, dominating Chinese domestic e-commerce with direct-to-consumer compressor models.
| Leading Market Players |
|---|
| Dometic |
| Engel |
| ARB |
| Mobicool |
| Whynter |
| IndelB |
| Alpicool |
| Igloo |
| Koolatron |
| Others |
Pricing and Supply Chain Analysis
Thermal management engineering talent concentrates in Germany's Stuttgart corridor and China's Pearl River Delta, where labor-cost differentials between European and Asian manufacturing sites drive 40-60% pricing spreads between premium compressor units and cost-optimized alternatives.
Pricing Analysis
Bundled fleet-management software subscriptions now separate from hardware-only transactions for commercial vehicle specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UL-listed and CE-marked units command 25-35% premiums over uncertified alternatives. Price erosion runs through thermoelectric tiers as Chinese direct-to-consumer brands compress entry points below 80 dollars. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while personal vehicle owners in emerging markets remain most responsive to absolute price thresholds.
Supply Chain Analysis
Warehouse-distribution layer consolidation concentrates inventory in Melbourne, São Paulo, and Hamburg regional distribution centers serving overlanding, pharmaceutical fleet, and RV OEM channels respectively. Variable-speed DC compressor supply draws from Secop's Danish manufacturing and Danfoss's Chinese joint-venture facilities. Refrigerant chemistry transitions hinge on EU F-Gas Regulation phase-down timelines. Single-source vulnerability in brushless motor controllers creates procurement risk for mid-tier assemblers. Distribution runs through direct-to-fleet procurement portals displacing traditional aftermarket wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European refrigerant compliance costs exceed Chinese manufacturing labor advantages by 3-4x, creating margin capture opportunities for suppliers with dual-hemisphere production footprints.
For Market Incumbents: Anticipate hydrocarbon refrigerant transition deadlines by accelerating R&D partnerships with compressor OEMs for propane-qualified safety architectures. Defend channel position by securing API-integrated fleet management system certifications before logistics operators finalize unified technical requirements. Backward integration into lithium iron phosphate cell sourcing mitigates energy storage cost volatility threatening portable unit margins. For New Entrants and Emerging Players: Enter via India's commercial vehicle cold-chain retrofit segment, where BIS and AIS certification gaps create 18-24 month first-mover windows before domestic compliance requirements formalize. Target pharmaceutical distribution operators in Brazil's regional corridors, where ANVISA temperature mandates exceed local supplier technical capabilities. Pursue direct-to-fleet procurement channel partnerships bypassing established distributor networks. For Investors and Strategic Acquirers: Electric vehicle OEMs represent the most active acquirer category in this space, seeking vehicle-to-load power management capabilities for factory-fit accessory integration. Five-to-ten year viability centers on suppliers controlling refrigerant-transition intellectual property and DC power electronics design. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for European-market product redesign cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Refrigerant Transition | EU F-Gas Regulation mandates propane-based cooling systems for European-market units by 2027. |
| Direct-to-Fleet Procurement Portal | Amazon and UPS unified technical requirements bypass distributor networks concentrating order volume. |
| Vehicle-to-Load Power Integration | Ford and Rivian electric pickups normalize external appliance power as factory feature. |
| Solar-DC Compatibility Certification | Australian overlanding segments specify MPPT charge controller integration for remote track autonomy. |
| MIIT New Energy Vehicle Certification | Domestic OEM integration pathways formalize for suppliers meeting GB/T electromagnetic compatibility standards. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and fleet operations directors at pharmaceutical logistics operators. Secondary validation drew from NHTSA electrical safety filings, EU F-Gas Regulation implementation schedules, MIIT vehicle equipment certification databases, and IHS Markit commercial vehicle production data. Bottom-up segment volume builds and top-down macroeconomic anchor points were cross-referenced for convergence.
Segment-weighting approaches distributed value across compressor versus thermoelectric cooling cycles, 12V versus solar versus battery power architectures, and fleet operator versus personal vehicle end-use categories throughout the projection horizon. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and regulatory mandate timelines. Industry-specific forecast inputs incorporated electric vehicle platform rollout schedules and cold-chain infrastructure investment pipelines across target geographies.
Inputs from OEM procurement databases and fleet operator technical requirement documents were available through the study window; gaps in real-time lithium cell commodity pricing introduce uncertainty bands around portable unit cost assumptions. Forecasts reflect documented assumptions regarding refrigerant transition compliance timelines and electric vehicle adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Ventilated Seats Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market