
 Glass for Electric Vehicle Glass Roof Market | 2026-2036
Glass for Electric Vehicle Glass Roof Market Size, Share, and Industry Trends Forecast 2026-2036
Glass for Electric Vehicle Glass Roof Market Insights
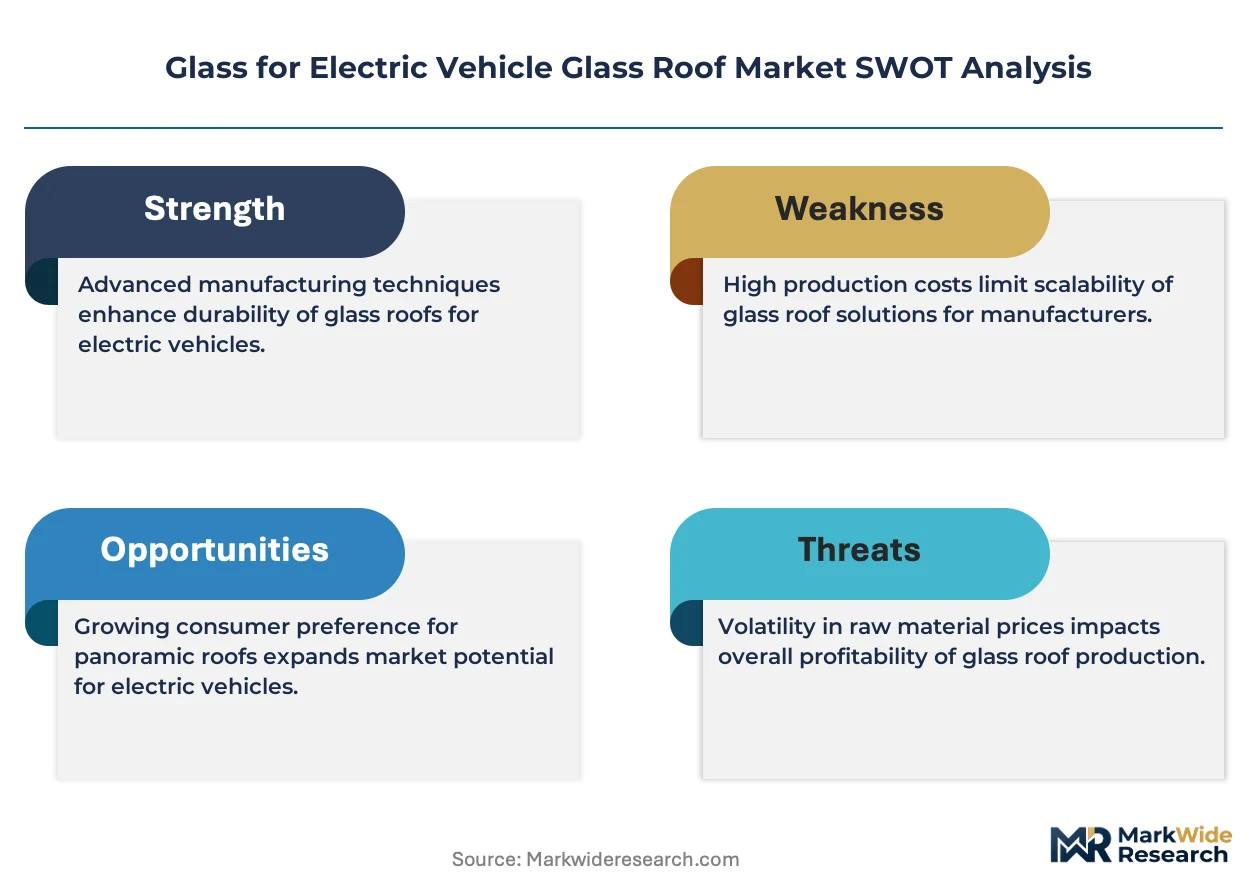
The EU Green Deal's embedded carbon border adjustments is restructuring procurement priorities across European EV glass supply chains. Fuyao Glass Industry Group leverages integrated float-glass furnaces in Germany and the United States to sustain cost advantages for laminated roof assemblies. Saint-Gobain anchors premium positioning through its Sekurit division's specialized automotive glazing R&D centers in France and Germany. AGC Inc. competes on electrochromic smart-glass technology leadership, differentiating against commodity tempered alternatives.
Glass for electric vehicle glass roof denotes laminated or tempered safety glazing, typically 3.5–5.0 mm thick with interlayer PVB or ionoplast compositions, manufactured through thermal tempering or chemical strengthening processes to withstand roof crush loads and stone impact. Its primary purpose spans panoramic visibility, cabin daylighting, and structural load distribution in battery-electric vehicle architectures. Laminated glass commands margin concentration due to acoustic damping and solar-control premiumization, while smart glass technology represents the fastest-expanding segment as electrochromic and SPD layers enable dynamic tint modulation. OEM end users capture the dominant volume share, though Tier-1 suppliers increasingly control specification development through module-level integration contracts.
FDA and NHTSA shape United States market access through FMVSS 205 glazing standards and roof crush resistance mandates, while ECE R43 governs European type approval for optical and mechanical properties. China's SAMR enforces GB 9656 compliance, creating divergent certification pathways that fragment supplier qualification costs. Stakeholders must monitor evolving battery-electric platform skateboard architectures, as flat-floor designs redistribute roof-panel structural loads and redefine glass thickness specifications independent of traditional sedan body-in-white assumptions.
Market Dynamics
Skateboard battery-electric platforms are redistributing roof-panel structural loads, forcing glass thickness specifications to decouple from traditional sedan body-in-white assumptions and triggering recertification cycles across laminated and tempered product lines.
Growth Catalysts
- EU Green Deal carbon border adjustments:European procurement teams now prioritize low-carbon float-glass sourcing, accelerating supplier qualification of integrated furnace operators in Germany and the United States.
- Electrochromic smart-glass adoption:Dynamic tint modulation via SPD and electrochromic layers is capturing specification share in premium SUV and sedan lineups, differentiating against commodity tempered alternatives.
- Yangtze River Delta manufacturing density:BYD, NIO, and Tesla Shanghai coordinate tightly clustered supplier ecosystems, compressing logistics costs and enabling just-in-time laminated roof assembly delivery.
Market Restraints
- Silica and soda ash input volatility:Raw material cost swings for glass batch constituents compress margin predictability for float-glass producers serving automotive laminated segments.
- Supplier concentration in Southeast Asian interlayer production:PVB and ionoplast membrane manufacturing clusters in Thailand and Malaysia create single-source vulnerability for laminated roof assembly lines.
- ECE R43 optical property variance:Divergent national interpretations of European type-approval standards for light transmittance and distortion generate retesting costs for multi-market product platforms.
Strategic Opportunities
- India's PLI scheme for advanced automotive components:Domestic cell manufacturing incentives are attracting glass roof module assembly investments to Tamil Nadu and Gujarat automotive corridors.
- Acoustic-damping premiumization:Laminated configurations with enhanced PVB interlayers command specification preference in luxury EV segments seeking cabin noise reduction.
- GB 9656 compliance arbitrage:China's strengthened automotive glass safety mandates are displacing tempered-only roof configurations, opening substitution volume for laminated suppliers.
Industry Challenges
- Chemical strengthening process engineering scarcity:Ion-exchange tempering expertise for thin-glass roof applications concentrates among Japanese and German equipment specialists, constraining capacity expansion timelines.
- Dual certification pathway complexity:Simultaneous FMVSS 205 and ECE R43 qualification requirements fragment testing budgets and extend product launch cycles for global platform suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass for Electric Vehicle Glass Roof Market |
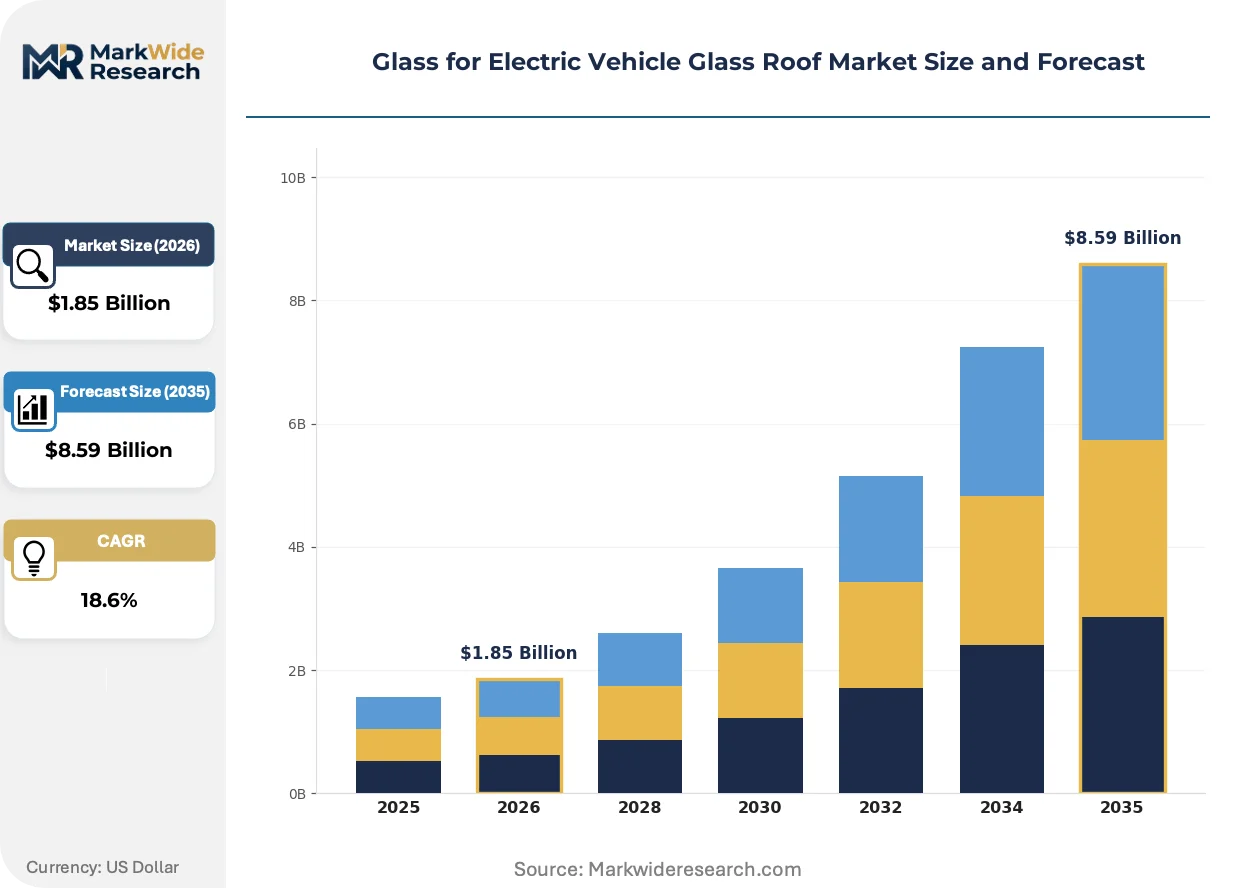
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.59 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
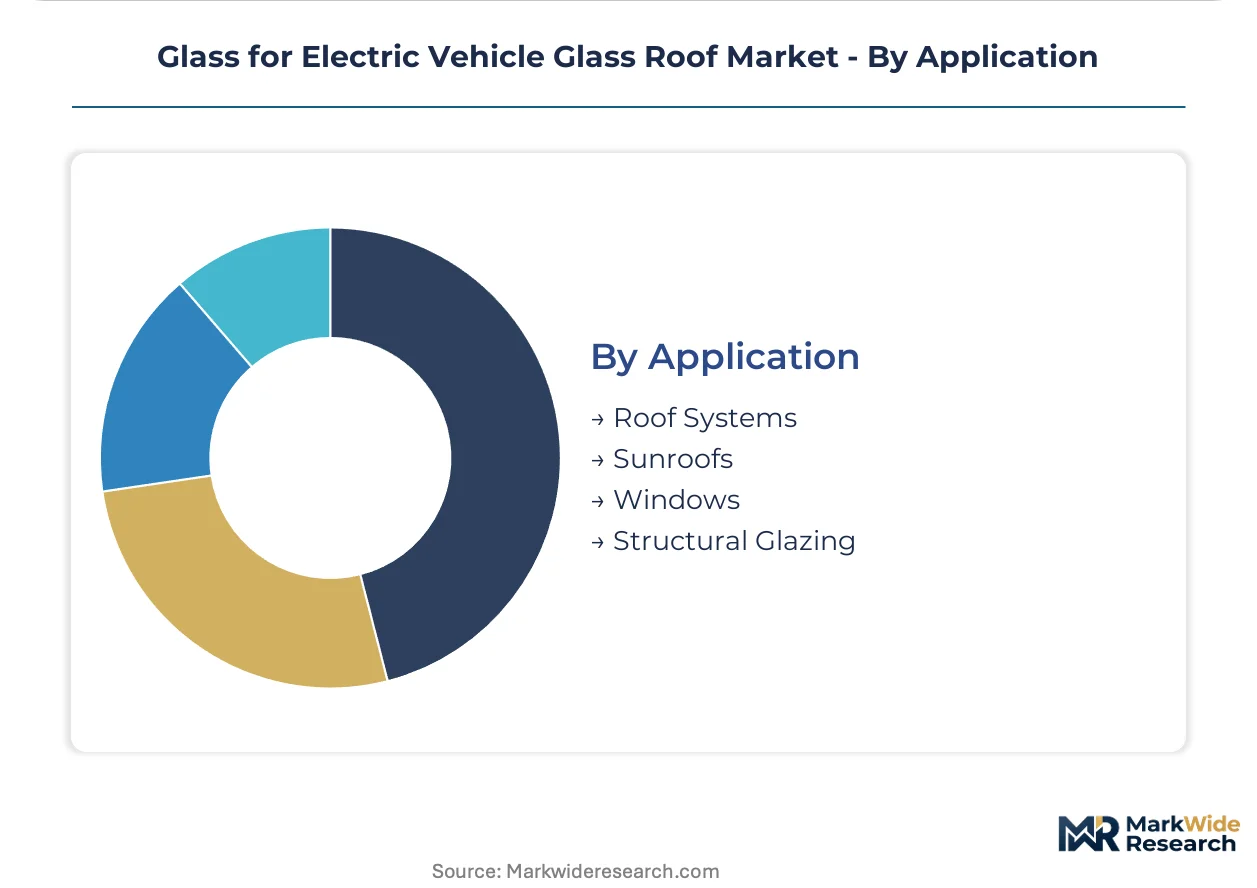
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Solar Control Glass, Insulated Glass End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Smart Glass, UV-Blocking Glass, Self-Healing Glass, Electrochromic Glass Application: Roof Systems, Sunroofs, Windows, Structural Glazing |
| Companies Covered | Fuyao Glass Industry Group, Xinyi Glass Holdings, NSG Group, Asahi Glass, Saint-Gobain, AGC Inc., Changzhou Huayu Automobile Glass, Corning Inc., Saint-Gobain Sekurit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass for Electric Vehicle Glass Roof Market Trends and Innovations
Active glazing technologies and modular roof assembly architectures are compressing traditional supply hierarchies, enabling Tier-1 suppliers to capture specification authority previously held by OEM engineering teams.
Electrochromic and SPD smart-glass layers are rewriting competitive positioning in the premium EV segment. Mercedes-Benz and BMW integrate dynamic tint modulation across flagship sedan and SUV lineups, compressing specification cycles from 36 to 18 months. This acceleration is displacing static solar-control glass in configurations above 75,000 USD price thresholds.
EU Green Deal embedded carbon border mechanisms are restructuring procurement qualification protocols. Laminated roof suppliers must now document Scope 3 emissions from float-glass furnace operations through Sekurit and AGC Inc. certification programs, favoring integrated producers with captive energy assets over merchant glass purchasers.
Module-level integration contracts are concentrating buying power among Tier-1 roof system suppliers. Webasto and Inalfa Roof Systems now specify glass thickness and interlayer composition directly, compressing direct OEM-glassmaker relationships and shifting volume commitments toward assembly-capable partners in China's Yangtze River Delta and Germany's Saxony automotive belt.
Glass for Electric Vehicle Glass Roof Market Segmentation
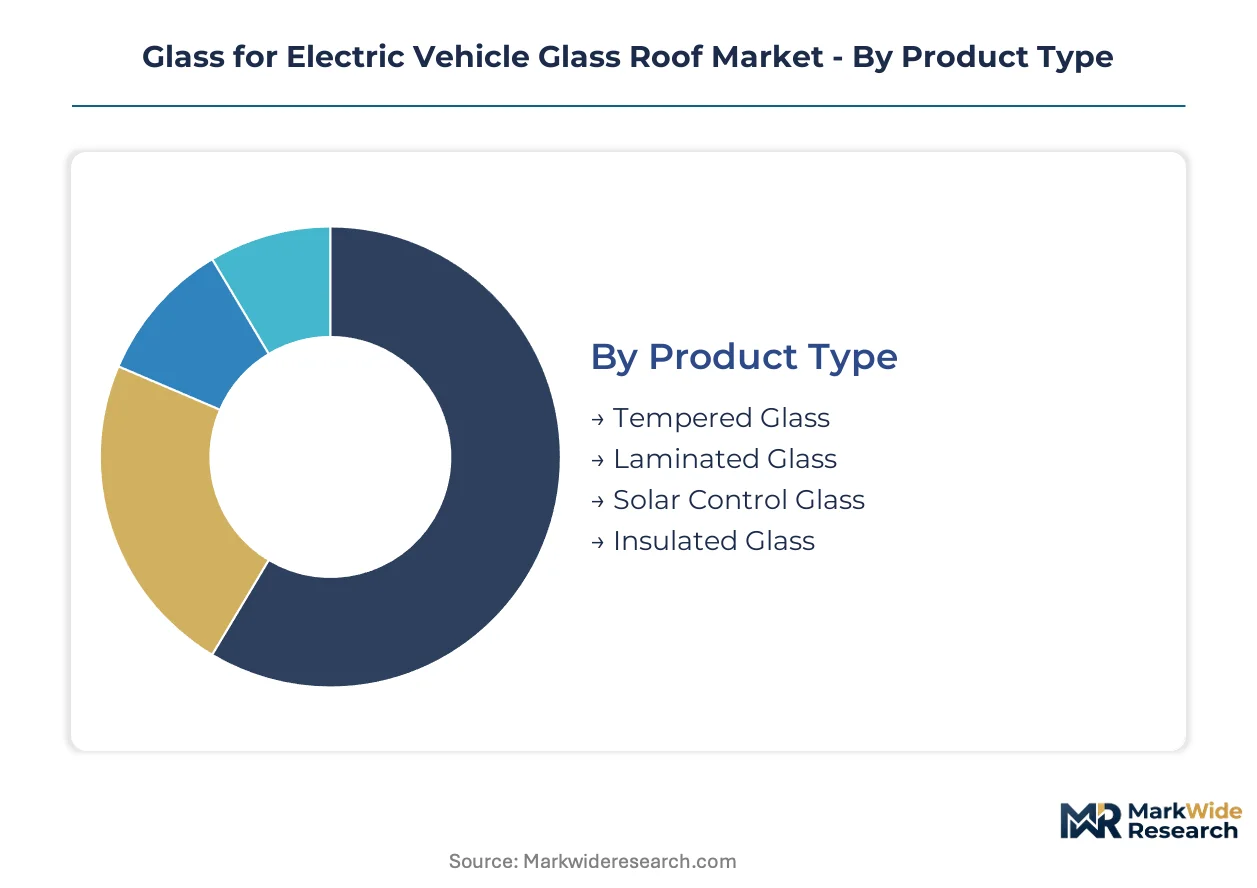
Glass roof specification decisions cascade through multiple buyer lenses: cost engineers prioritize material thickness and interlayer selection, while platform architects weigh structural load redistribution against smart-glass premiumization. Segmentation clarity exposes where laminated configurations command margin concentration versus where tempered alternatives retain specification share.
Product Type:
Cost tier differentiation dominates procurement evaluation, with interlayer composition and thermal processing method determining price positioning across fleet and premium vehicle programs.
- Laminated Glass:PVB or ionoplast interlayers bonded between glass plies deliver acoustic damping and solar-control premiumization. Demand concentrates in Mercedes-Benz and BMW flagship lineups where cabin noise reduction justifies material cost premiums. EU Green Deal carbon border adjustments favor integrated float-glass producers with captive furnace operations.
- Tempered Glass:Thermal or chemical strengthening creates surface compression layers for stone impact resistance. BYD and Tesla Shanghai specify tempered configurations in volume sedan programs where cost discipline outweighs acoustic performance requirements. China's GB 9656 compliance arbitrage is displacing tempered-only roof specifications in domestic market vehicles.
- Solar Control Glass:Metallic oxide coatings filter infrared transmission to reduce HVAC load on battery-electric range.
- Insulated Glass:Dual-pane air-gap construction addresses thermal bridging in extreme climate markets.
Laminated glass leads on scale through premium SUV and sedan penetration; smart-glass integration is gaining share fastest as electrochromic layers capture specification above 75,000 USD price thresholds.
End User:
Volume concentration shifts according to who controls specification authority in roof module assembly contracts.
- Tier-1 Suppliers:Webasto and Inalfa Roof Systems now specify glass thickness and interlayer composition directly, compressing traditional OEM-glassmaker relationships. Module-level integration contracts concentrate buying power among assembly-capable partners in Germany's Saxony automotive belt and China's Yangtze River Delta.
- OEMs:Premium German and Japanese manufacturers retain direct glass procurement for flagship programs where electrochromic technology differentiation matters. Mercedes-Benz integrates dynamic tint modulation across S-Class and EQS lineups with 18-month specification cycles.
- Vehicle Assemblers:Contract manufacturers in emerging EV markets source pre-integrated roof modules rather than discrete glass components.
- Aftermarket Providers:Replacement demand concentrates in collision repair networks for tempered sunroof configurations.
Tier-1 suppliers lead on procurement volume through module integration; OEM direct relationships retain steepest expansion trajectory in smart-glass premium segments.
Technology:
Maturity gradients separate commercially deployed solutions from pilot-stage alternatives.
- Electrochromic Glass:Tungsten-oxide thin-film deposition enables voltage-driven tint modulation with sub-60-second transition times. AGC Inc. anchors technology leadership through proprietary ceramic coating processes, differentiating against SPD alternatives in BMW and Hyundai Motor Group programs.
- Smart Glass:Suspended particle device layers offer faster switching speeds for dynamic solar control. Demand concentrates in premium SUV segments where occupant comfort commands specification priority over material cost.
- UV-Blocking Glass:Cerium-doped compositions filter ultraviolet transmission without electrical activation.
- Self-Healing Glass:Microcapsule-based scratch recovery remains pre-commercial for automotive roof applications.
Electrochromic configurations lead on commercial deployment; smart glass represents the fastest-growing trajectory as SPD layers penetrate mid-premium price bands.
Application:
Structural load requirements and visibility specifications determine glass thickness and edge treatment protocols.
- Roof Systems:Full-surface panoramic configurations demand laminated construction with 3.5–5.0 mm thickness to withstand roof crush loads. Skateboard battery-electric platforms redistribute structural requirements, forcing thickness specifications to decouple from traditional sedan body-in-white assumptions.
- Sunroofs:Retractable and fixed glass panels balance weight reduction against wind noise and water intrusion sealing. Tempered configurations retain share in cost-sensitive compact EV programs.
- Windows:Side and rear glazing specifications diverge from roof requirements in thermal and optical standards.
- Structural Glazing:Adhesive-bonded roof panels integrate directly into unibody architecture without discrete framing members.
Roof systems lead on revenue concentration through panoramic visibility trends; structural glazing climbs fastest as flat-floor EV architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive laminated glass manufacturing for premium OEMs, establishing the technical foundation that Chinese producers later scaled for mass-market EV programs.
China
BYD and NIO drive laminated roof specification across sedan and SUV lineups, displacing tempered-only configurations. SAMR enforces GB 9656 automotive glass regulations, mandating enhanced safety performance for panoramic roof systems. The Yangtze River Delta cluster hosts dense supplier ecosystems where Tesla Shanghai coordinates just-in-time laminated assembly delivery.
Germany
Mercedes-Benz and BMW integrate electrochromic smart-glass across flagship EQS and iX lineups, compressing specification cycles to 18 months. ECE R43 governs European type approval for optical and mechanical properties, creating certification barriers for non-integrated suppliers. Saxony's automotive belt concentrates module-level integration contracts among Tier-1 roof system assemblers.
United States
Tesla and Rivian anchor demand for structural glazing in flat-floor battery-electric platforms, redistributing roof-panel load specifications. NHTSA administers FMVSS 205 glazing standards and roof crush resistance mandates, diverging from European certification pathways. Michigan and Ohio automotive corridors host qualification programs for low-carbon float-glass sourcing under IRA clean manufacturing incentives.
Japan
Toyota and Honda specify acoustic-damping laminated configurations for luxury EV segments prioritizing cabin noise reduction. METI oversees JIS standards alignment with ECE R43 for export market access, streamlining dual certification complexity. Aichi Prefecture's Nagoya-centered automotive cluster concentrates ion-exchange tempering expertise for thin-glass roof applications.
India
Tata Motors and Mahindra & Mahindra expand glass roof configurations across domestic EV platforms, sourcing pre-integrated modules from emerging Tier-1 suppliers. The PLI scheme for advanced automotive components attracts assembly investments to Tamil Nadu and Gujarat automotive corridors. BIS certification requirements for automotive safety glass create qualification pathways for laminated roof suppliers entering the market.
Glass for Electric Vehicle Glass Roof Market Competitive Landscape
Premium-margin players sit above commodity-margin players across interlayer technology and integrated furnace ownership, with laminated acoustic-damping configurations commanding specification preference in luxury segments while tempered alternatives retain share in cost-sensitive volume programs. The vendor base organizes around three archetypes: integrated float-glass producers with captive energy assets, specialized automotive glazing divisions of diversified materials conglomerates, and electrochromic technology specialists. Capacity expansion and module-level integration contracts constitute the dominant competitive moves, with Tier-1 roof system suppliers increasingly controlling glass thickness and interlayer specification authority.
Within the integrated producer tier, Fuyao Glass Industry Group and Xinyi Glass Holdings exemplify scale-driven positioning through float-glass furnace operations spanning multiple geographies. Saint-Gobain occupies a position representing premium-tier specialization through its Sekurit automotive glazing division, while AGC Inc. anchors technology leadership in electrochromic and smart-glass configurations.
| Leading Market Players |
|---|
| Fuyao Glass Industry Group |
| Xinyi Glass Holdings |
| NSG Group |
| Asahi Glass |
| Saint-Gobain |
| AGC Inc. |
| Changzhou Huayu Automobile Glass |
| Corning Inc. |
| Saint-Gobain Sekurit |
| Others |
Pricing and Supply Chain Analysis
Electrochromic smart-glass layer integration is compressing specification cycles from 36 to 18 months while simultaneously redrawing cost curves and supplier power concentration. This acceleration favors integrated float-glass producers with captive furnace assets over merchant glass purchasers, embedding pricing power within vertically consolidated manufacturing footprints across Germany, China, and the United States.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies laminated roof assemblies by interlayer composition and thermal processing method. Premium configurations with acoustic-damping PVB interlayers and electrochromic coatings command specification preference in Mercedes-Benz and BMW flagship lineups, while tempered alternatives retain share in BYD volume sedan programs where cost discipline outweighs performance requirements. Pricing pressure stems from silica and soda ash input volatility compressing margin predictability for float-glass producers. Tier-1 suppliers exhibit least price sensitivity due to module-level integration contracts, whereas emerging EV assemblers in India demonstrate highest sensitivity as they source pre-integrated roof modules.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian interlayer production, where PVB and ionoplast membrane manufacturing clusters in Thailand and Malaysia create concentrated dependency for laminated roof assembly lines. Geographic supply concentration centers on China, Germany, and the United States for float-glass furnace operations, with raw material dependencies drawing from high-purity silica deposits, soda ash, and cerium oxide for UV-blocking formulations. Supply chain risk manifests as tariff exposure on Chinese-manufactured glass components entering European and North American markets under carbon border adjustment mechanisms. Distribution runs through Tier-1 roof system suppliers including Webasto and Inalfa, which now specify glass thickness and interlayer composition directly, compressing traditional OEM-glassmaker relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market hinge on acoustic-damping premiumization and electrochromic technology capture above 75,000 USD price thresholds, with cost-down drivers emerging from Yangtze River Delta manufacturing density compressing logistics and just-in-time assembly economics.
For Market Incumbents: Lock in module-level integration contracts with Tier-1 roof system suppliers before specification authority fully consolidates among assemblers. Defensive moves center on backward integration into ionoplast interlayer production to offset Southeast Asian single-source vulnerability, and capacity expansion in Germany's Saxony automotive belt to secure ECE R43 qualification proximity. Threats include electrochromic technology specialists displacing commodity tempered alternatives, and EU Green Deal carbon border adjustments favoring integrated producers with captive energy assets over merchant purchasers.
For New Entrants and Emerging Players: Smart-glass technology leadership offers entry traction into premium SUV and sedan segments where dynamic tint modulation commands specification priority over material cost. White-space targets include India's Tamil Nadu and Gujarat automotive corridors under PLI scheme incentives, and acoustic-damping laminated configurations for luxury EV segments prioritizing cabin noise reduction. Go-to-market angles should emphasize GB 9656 compliance arbitrage in China, where strengthened safety mandates displace tempered-only roof specifications.
For Investors and Strategic Acquirers: Roll-up economics work for integrated float-glass producers with captive furnace operations because carbon border adjustment mechanisms are restructuring procurement qualification protocols and favoring Scope 3 emissions documentation capabilities. Long-term viability over the 5-10 year window rests on electrochromic and SPD technology deployment trajectories. Acquisition target archetypes include specialized automotive glazing divisions with established OEM relationships and electrochromic coating expertise. The signal to watch is specification cycle compression below 18 months, indicating accelerated smart-glass adoption and premium-tier shift velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Module-Level Integration Contracts | Tier-1 suppliers like Webasto now control glass thickness specifications directly, shifting volume commitments. |
| Backward Integration into Interlayer Production | Captive PVB and ionoplast manufacturing mitigates Southeast Asian single-source vulnerability for laminated assemblies. |
| Electrochromic Technology Licensing | AGC Inc.'s proprietary ceramic coating processes differentiate against SPD alternatives in BMW and Hyundai programs. |
| Low-Carbon Float-Glass Capacity Expansion | Integrated furnace operations in Germany and the United States secure EU Green Deal procurement qualification. |
| Acoustic-Damping Premiumization | Enhanced PVB interlayers command specification preference in Mercedes-Benz flagship lineups seeking cabin noise reduction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and automotive glazing R&D directors with secondary validation. Data sources included vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed glass manufacturers, and customs records tracking float-glass and interlayer trade flows. Bottom-up segment sizing triangulated against top-down market value estimates to reconcile volume and value outputs.
Segment-weighting approaches distributed analytical emphasis across product type, end user, technology, and application dimensions, with additional weighting for regional production cluster dynamics. Modeled variables spanned vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional manufacturing density. CAGRs were derived from regression analysis of historical penetration rates and forward projection of skateboard platform adoption curves, incorporating battery-electric vehicle sales forecasts and glass roof take-rate assumptions.
The model holds under sustained premium SUV and sedan electrification; deviation in raw material cost trajectories or regulatory certification harmonization would shift volume and value estimates. Forecasts reflect documented assumptions regarding electrochromic technology cost curves and carbon border adjustment implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market