
 Automotive Flooring Market | 2026-2036
Automotive Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Flooring Market Analysis
Aftermarket refurbishment revenue is rewriting how suppliers allocate engineering resources across the value chain. Faurecia leverages its seating and interiors integration to bundle flooring with complete cabin modules. Lear Corporation anchors North American production through direct OEM relationships and just-in-sequence delivery networks. Toyota Boshoku dominates Asian supply channels with vertically controlled textile operations from fiber to finished mat.
Automotive flooring comprises layered textile, polymer, or composite substrates engineered to withstand abrasion, moisture ingress, and acoustic transmission while meeting flammability standards such as FMVSS 302. Polypropylene needle-punched carpet dominates OEM volume due to recyclability and cost efficiency, though polyurethane foam-backed composites command premium margins in luxury segments. Application demand splits sharply: passenger vehicles consume standardized roll-goods, while commercial fleets drive replacement-cycle revenue through heavy-duty rubber and vinyl specifications.
EPA tailpipe and cabin air regulations, ECHA REACH restrictions on phthalate plasticizers, and China's GB standards for interior emissions collectively reshape material selection and testing protocols. Suppliers must certify low-VOC formulations to maintain OEM qualification status across multiple jurisdictions. Stakeholders should monitor evolving biobased material certifications and regional carbon-accounting rules that will determine next-generation flooring platform awards.
Market Dynamics
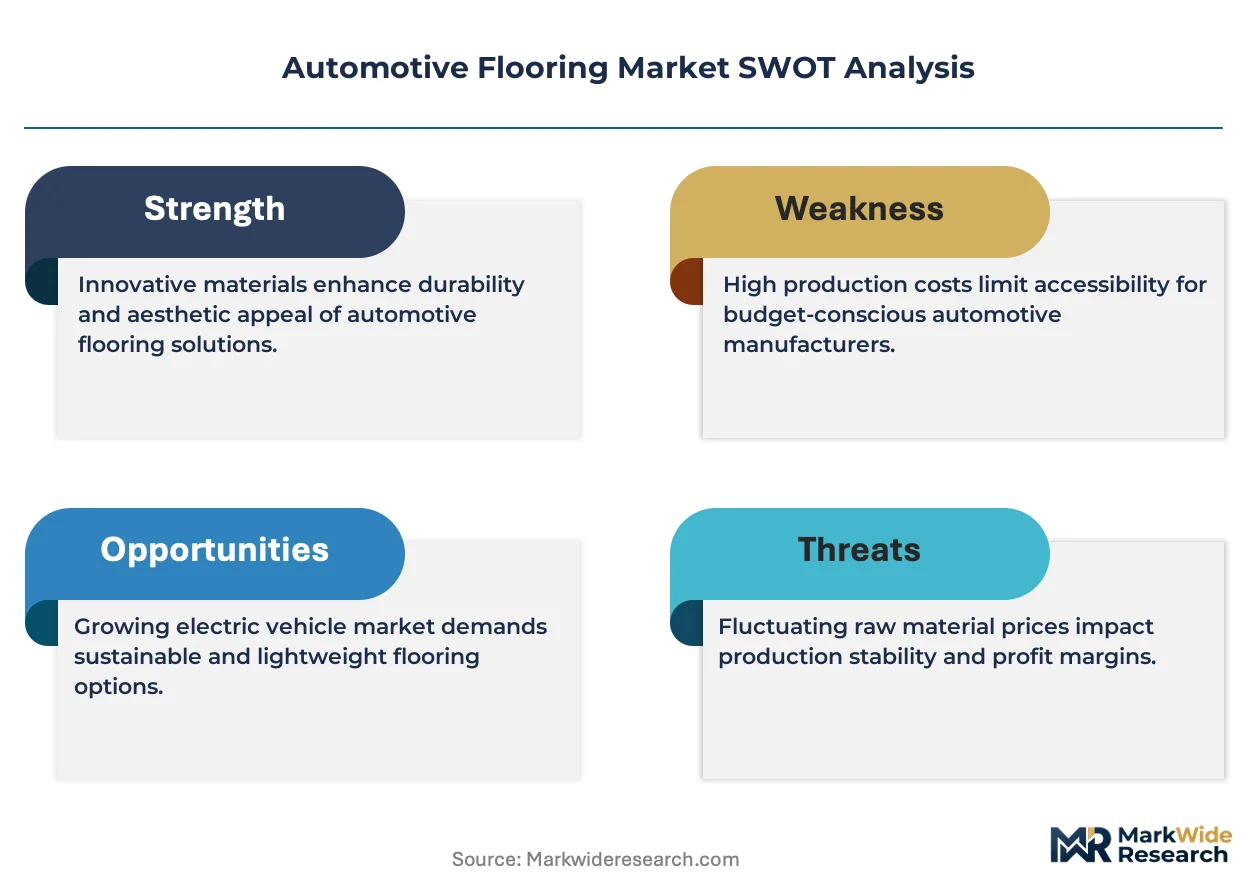
EPA cabin air quality mandates and ECHA REACH restrictions on volatile organic compounds are forcing material substitutions across automotive flooring supply chains, compressing qualification timelines and raising compliance costs for polypropylene and polyurethane formulations.
Growth Catalysts
- EPA Tier 3 cabin air standards:OEMs now require low-emission flooring substrates to meet combined tailpipe and interior air regulations, expanding factory-fit specifications for needle-punched and foam-backed assemblies.
- Extended-range battery platforms:Chinese EV manufacturers demand lightweight carpet modules to offset battery weight, creating specialized engineering contracts for multi-layer composite constructions.
- Aftermarket refurbishment cycles:Commercial fleet operators in North America and Europe are compressing replacement intervals for heavy-duty rubber and vinyl flooring, generating recurring revenue streams independent of new vehicle sales.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin and polyurethane precursor costs fluctuate with crude oil indices, squeezing margins on standardized roll-goods that lack pricing power.
- Asian textile concentration:Vertical fiber-to-finished-mat operations cluster in China and Southeast Asia, exposing supply chains to shipping disruptions and trade policy shifts.
- Recyclability technical limits:Multi-layer bonded constructions with incompatible polymers resist mechanical recycling, conflicting with OEM circularity pledges and extended producer responsibility frameworks.
Strategic Opportunities
- India automotive production expansion:Domestic OEMs and joint ventures under PLI scheme incentives require localized flooring supply, opening greenfield manufacturing positions for needle-punch and tufted carpet operations.
- Biobased material certifications:USDA BioPreferred and EU Ecolabel standards create premium positioning for soy-based polyols and recycled PET fiber substrates in sustainability-focused vehicle programs.
- Direct-to-fleet digital channels:Commercial vehicle operators are bypassing traditional distributor networks through B2B platforms, enabling suppliers to capture aftermarket margin previously allocated to intermediaries.
Industry Challenges
- Cross-jurisdiction VOC testing protocols:Suppliers must maintain parallel certification laboratories for EPA, ECHA, and China GB standards, extending product launch timelines and raising fixed compliance costs.
- Just-in-sequence integration complexity:OEM assembly line synchronization demands real-time inventory visibility and modular packaging systems that legacy ERP infrastructure cannot support without capital-intensive upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Flooring Market |
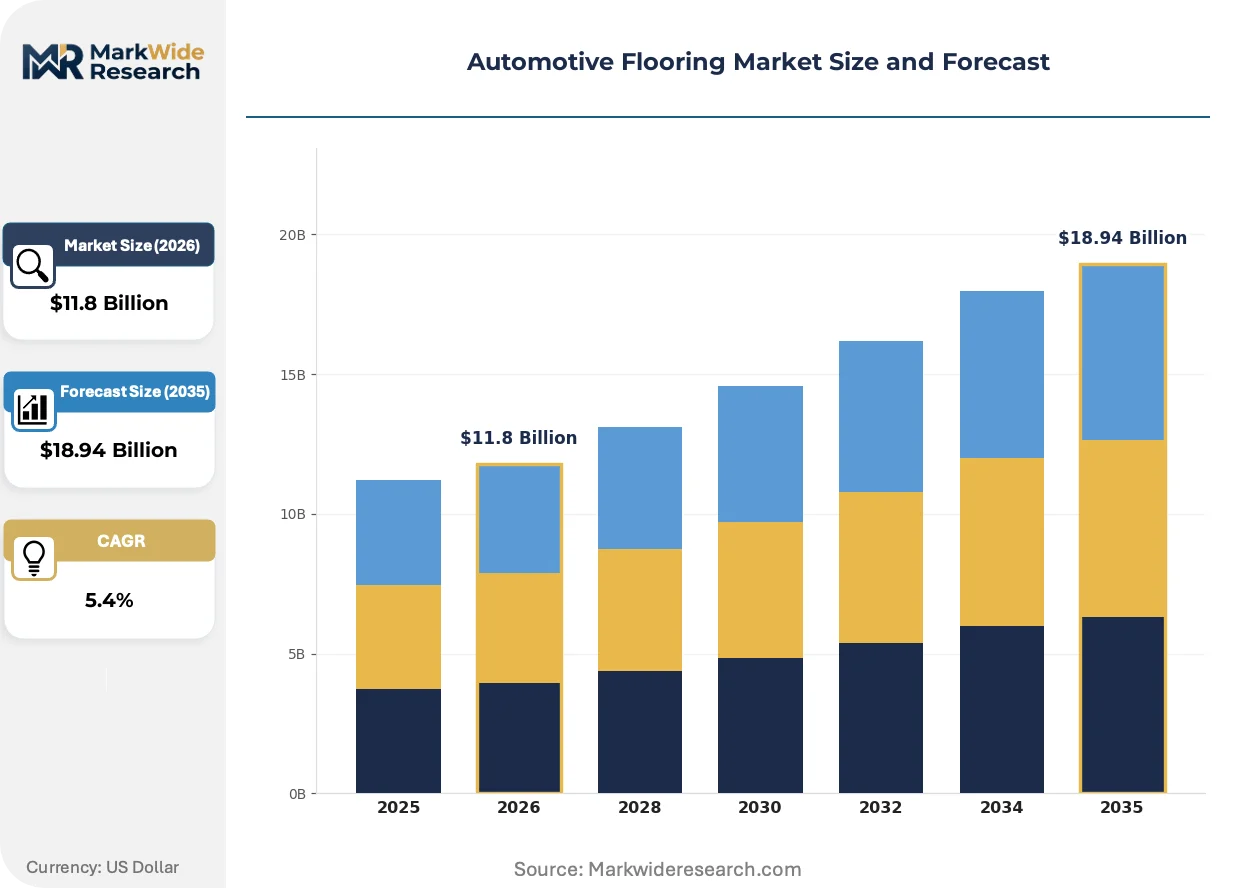
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Vinyl, Rubber, Composite Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, SUVs Material: Polypropylene, PVC, Nylon, Polyurethane End User: OEMs, Aftermarket Consumers, Vehicle Restorers, Commercial Fleets |
| Companies Covered | Faurecia, Hayashi Telempu Corporation, Lear Corporation, IAC Group, IDEAL Automotive GmbH, Magna International, Autoneum Holding, Suminoe Textile Co., Ltd., Toyota Boshoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Flooring Market Emerging Trajectories
Material science advances and regulatory tightening are converging to redefine performance benchmarks for acoustic, thermal, and emissions properties in automotive interior substrates.
Recycled polyethylene terephthalate (rPET) fiber from post-consumer bottle waste is rendering obsolete virgin polyester in carpet face yarns. European premium OEMs have mandated rPET content minimums for 2025 model year vehicles. This shift is compressing demand for petroleum-derived polymers while establishing closed-loop supply partnerships with beverage packaging recyclers.
ECHA REACH Annex XVII restrictions on phthalate plasticizers in soft PVC compounds are accelerating migration to bio-based plasticizers and TPO (thermoplastic olefin) alternatives. Flooring suppliers reformulating vinyl wear layers face eighteen-month requalification cycles with OEMs. German and French vehicle programs are most affected, with TPO sheet specifications now dominant in luxury electric platforms.
Fleet procurement teams are consolidating supplier relationships through multi-year total-cost-of-ownership contracts that bundle flooring with installation and removal services. This behavior is displacing transactional spot purchasing in North American commercial vehicle channels. Municipal transit authorities and rental car operators are driving the shift, with Chicago and Los Angeles transit districts among the early adopters of integrated service agreements.
Automotive Flooring Market Segmentation
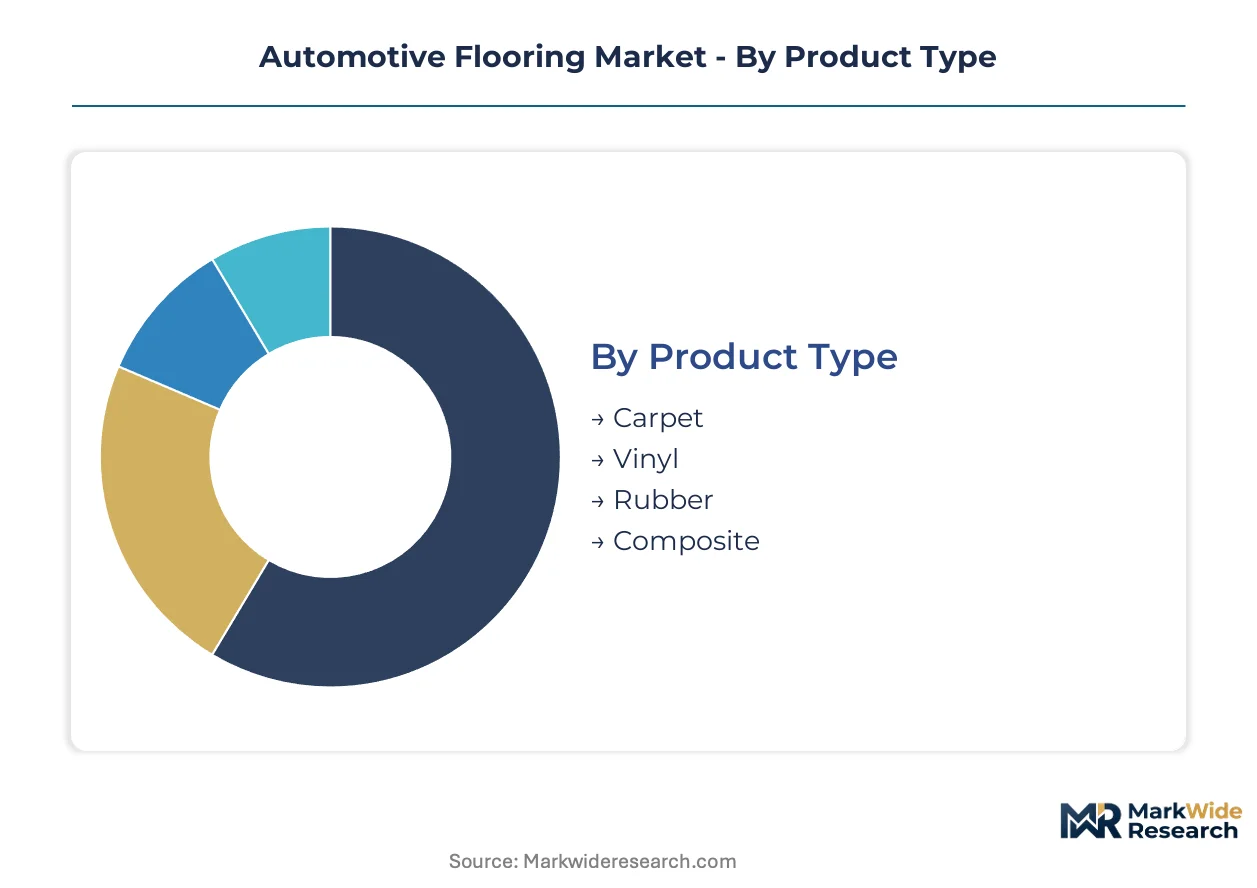
Automotive flooring suppliers engineer distinct specifications across vehicle platforms, balancing weight targets against abrasion resistance and regulatory compliance. Material selection and channel strategy diverge sharply between factory-fit OEM programs and refurbishment-driven aftermarket revenue streams.
Product Type:
Cost tier differentiation separates commodity roll-goods from engineered assemblies commanding premium pricing.
- Carpet:Needle-punched polypropylene face fibers bonded to polyurethane foam backing dominate OEM volume through recyclability and acoustic dampening properties. Chinese EV manufacturers specify lightweight multi-layer carpet constructions to offset battery mass in extended-range platforms.
- Vinyl:Calendered PVC wear layers with embossed textures serve commercial fleet operators requiring moisture resistance and rapid replacement cycles. ECHA REACH Annex XVII phthalate restrictions are accelerating reformulation toward bio-based plasticizers and TPO alternatives in European supply chains.
- Rubber:Heavy-duty vulcanized compounds withstand extreme abrasion in mining and construction vehicle applications.
- Composite:Multi-layer bonded substrates integrate thermal and acoustic barriers for luxury electric platforms.
Carpet commands the established base. The steepest expansion runs through composite constructions.
Application:
Vehicle architecture dictates flooring specifications across weight classes and duty cycles.
- Passenger Vehicles:Standardized roll-good carpet specifications prioritize cost efficiency and rapid assembly line integration. Factory-fit programs consume the majority of polypropylene needle-punch volume under EPA Tier 3 cabin air mandates.
- Commercial Vehicles:Fleet operators compress replacement intervals for rubber and vinyl flooring, generating recurring aftermarket revenue independent of new vehicle production cycles. Municipal transit authorities in Chicago and Los Angeles drive integrated service agreements bundling supply with installation.
- Heavy-Duty Trucks:Severe-duty rubber compounds resist petroleum staining and thermal degradation in long-haul applications.
- SUVs:Premium tufted carpet and composite assemblies address consumer expectations for cabin refinement.
Passenger vehicles anchor volume demand. Commercial vehicles deliver the highest margin aftermarket trajectory.
Material:
Polymer chemistry selection balances regulatory compliance against performance specifications and circularity commitments.
- Polypropylene:Recyclable thermoplastic resin dominates needle-punch carpet backings and face yarns through cost efficiency and compatibility with existing recycling infrastructure. Virgin polypropylene faces margin pressure from petrochemical feedstock volatility.
- PVC:Soft vinyl compounds face eighteen-month OEM requalification cycles under ECHA phthalate restrictions, displacing demand toward TPO alternatives in German and French vehicle programs.
- Nylon:High-tenacity fibers deliver superior abrasion resistance for premium tufted carpet specifications.
- Polyurethane:Foam backings provide acoustic and thermal insulation in luxury segment assemblies.
Polypropylene holds the volume position. Polyurethane climbs fastest on electrification-driven lightweighting priorities.
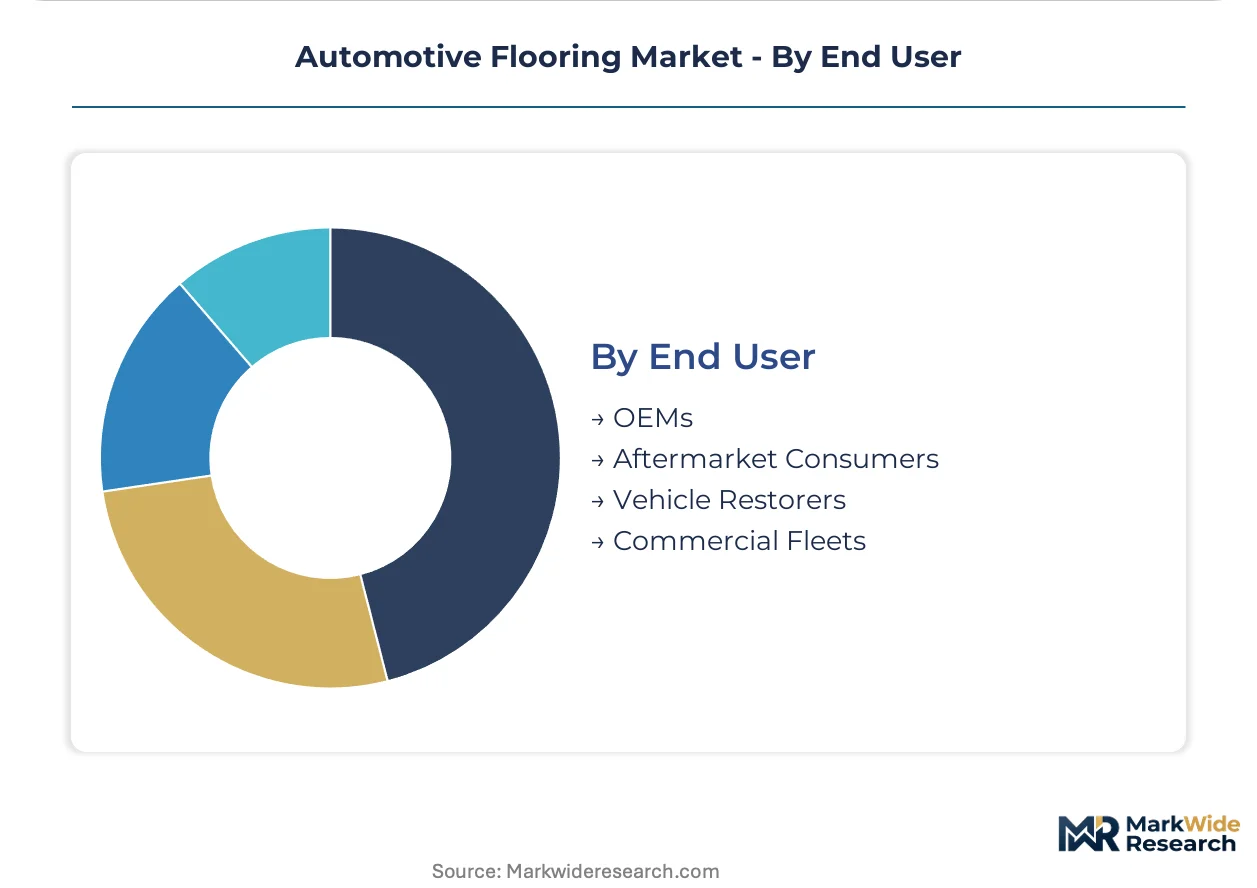
End User:
Channel structure fragments between integrated OEM supply and distributed aftermarket procurement.
- OEMs:Just-in-sequence delivery networks demand real-time inventory visibility and modular packaging systems. Direct relationships with Lear Corporation and Faurecia anchor North American factory-fit specifications.
- Aftermarket Consumers:DIY refurbishment segments concentrate in North American and European markets with aging vehicle fleets.
- Vehicle Restorers:Specialty suppliers serve classic and collector vehicle segments requiring period-correct materials.
- Commercial Fleets:B2B digital platforms enable suppliers to capture margin previously allocated to distributor intermediaries. Total-cost-of-ownership contracts now consolidate multi-year supply relationships.
OEMs dominate factory-fit value. Commercial fleets are gaining share fastest through direct digital procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in the United States demonstrate the lowest price elasticity, absorbing premium specifications for integrated service contracts. Chinese EV manufacturers show intermediate sensitivity, trading margin for lightweighting performance. European buyers face the highest elasticity, with ECHA compliance costs forcing material downgrades.
United States
Commercial fleet procurement teams in Chicago and Los Angeles transit districts now bundle flooring supply with installation services under multi-year agreements. EPA Tier 3 cabin air standards compress qualification timelines for polypropylene needle-punch suppliers seeking OEM factory-fit status. Detroit-Warren-Dearborn automotive cluster anchors Lear Corporation's just-in-sequence delivery networks for North American passenger vehicle programs.
China
Domestic EV brands require specialized lightweight carpet modules to offset battery mass in extended-range platforms. MIIT and GB standards for interior emissions mandate low-VOC formulations that reshape material selection across supplier portfolios. Yangtze River Delta manufacturing belt concentrates vertically integrated textile operations from fiber spinning through finished mat production.
Germany
ECHA REACH Annex XVII phthalate restrictions drive eighteen-month reformulation cycles for vinyl wear layer suppliers serving premium electric platforms. KBA type-approval processes enforce parallel certification protocols that extend product launch timelines. Stuttgart metropolitan region hosts engineering centers developing TPO alternatives for luxury OEM specifications.
Japan
Toyota Boshoku's captive fiber-to-finished-mat operations dominate domestic supply channels through backward integration into textile production. METI carbon-neutrality roadmaps pressure suppliers to certify recycled PET content in carpet face yarns. Nagoya industrial corridor concentrates tufted carpet manufacturing for hybrid and electric vehicle platforms.
India
Domestic OEMs and joint ventures under PLI scheme incentives require localized flooring supply to qualify for production-linked benefits. BIS automotive interior standards create domestic certification requirements separate from EPA or ECHA frameworks. Tamil Nadu automotive belt attracts greenfield needle-punch and tufted carpet investments from multinational suppliers.
Automotive Flooring Market Vendor Landscape
Integrated cabin-system suppliers and specialized textile manufacturers split the market between bundled module contracts and component-level specifications. The vendor base concentrates around three strategic archetypes: seating-and-interiors integrators leveraging cross-product bundling, vertically controlled textile operators commanding fiber-to-finished supply chains, and independent flooring specialists competing on reformulation speed. Dominant competitive moves include capacity expansion into India under PLI incentives and strategic partnerships with beverage packaging recyclers for rPET fiber offtake agreements.
Within the integrated-systems tier, Faurecia and Lear Corporation exemplify archetypes bundling flooring with complete cabin modules versus anchoring production through direct OEM relationships. Among Asia-Pacific textile operators, Toyota Boshoku occupies a position representing vertically controlled operations from fiber spinning through finished mat. These three entities sit within distinct competitive vectors—European-led integration, North American OEM proximity, and Asian supply chain depth—that shape how qualification timelines and compliance costs distribute across the value chain.
| Leading Market Players |
|---|
| Faurecia |
| Hayashi Telempu Corporation |
| Lear Corporation |
| IAC Group |
| IDEAL Automotive GmbH |
| Magna International |
| Autoneum Holding |
| Suminoe Textile Co., Ltd. |
| Toyota Boshoku Corporation |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion transmits directly through automotive flooring supply chains, amplifying cost differentials between captive textile operations and merchant suppliers while compressing margins on standardized roll-goods lacking pricing power.
Pricing Analysis
Aftermarket refurbishment contracts now drive lifetime value capture across automotive flooring supply chains. Three-tier pricing structure across premium, standard, and economy levels separates composite acoustic assemblies for luxury EV platforms from commodity needle-punch carpet and heavy-duty vinyl for fleet operators. Cost compression in polypropylene roll-goods is intensifying because petrochemical feedstock volatility lacks pass-through mechanisms in OEM annual contracts. Commercial fleet buyers in North America demonstrate the lowest price elasticity, while European purchasers facing ECHA compliance cost absorption exhibit the highest sensitivity.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk planning for automotive flooring suppliers. Manufacturing gravity centers on China, Japan, and Germany, with raw material procurement drawing from Saudi Arabian polypropylene resin, South Korean polyurethane precursors, and Indonesian natural rubber. Single-source vulnerability persists in needle-punch textile equipment where German machinery builders control critical spinning-to-bonding lines. Distribution runs through just-in-sequence OEM delivery networks and fragmented aftermarket distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive flooring market fragmentation creates entry niches as EPA and ECHA regulatory divergence splinters qualification requirements, preventing scale economies from consolidating around single global specifications.
For Market Incumbents: Harden qualification timelines against emerging biobased material certifications by investing in parallel EPA and ECHA testing laboratory capacity. Deepen backward integration into rPET fiber sourcing through beverage packaging recycler partnerships to defend margin position against virgin polymer cost volatility. Lock in multi-year total-cost-of-ownership contracts with municipal transit authorities to anchor aftermarket revenue visibility. For New Entrants and Emerging Players: Build out localized needle-punch manufacturing in Tamil Nadu under PLI scheme incentives to capture India domestic OEM demand requiring BIS-certified low-VOC formulations. Target commercial fleet B2B digital procurement channels where integrated service bundling displaces traditional distributor intermediaries. Lead with rapid reformulation capabilities for TPO alternatives to soft PVC compounds facing ECHA phthalate restrictions. For Investors and Strategic Acquirers: Regional specialists with captive textile operations from fiber through finished mat represent the most defensible acquisition archetype in a market where qualification timelines extend competitive moats. Long-term viability hinges on circularity infrastructure for multi-layer bonded construction recycling. Watch for MIIT carbon-neutrality enforcement tightening as the inflection signal triggering accelerated rPET content mandates across Chinese EV platforms.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Fiber Supply Agreement | Secures post-consumer bottle waste streams ahead of European premium OEM 2025 content mandates. |
| India Greenfield Manufacturing | Captures PLI scheme incentives while positioning for domestic OEM localization requirements under BIS standards. |
| TPO Reformulation Investment | Accelerates eighteen-month OEM requalification cycles for vinyl wear layer alternatives under ECHA Annex XVII. |
| Fleet Digital Platform Launch | Disintermediates aftermarket distributors through direct B2B procurement relationships with Chicago and Los Angeles transit authorities. |
| Multi-Jurisdiction VOC Certification | Maintains OEM qualification status across EPA Tier 3, ECHA REACH, and China GB interior emission frameworks. |
Methodological Framework
Initial hypotheses were tested against primary input from Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations managers, and commercial fleet procurement leads and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive suppliers, and customs trade records for polypropylene resin and textile machinery imports. Bottom-up segment sizing triangulated against top-down market reconstruction from OEM factory-fit specifications and aftermarket replacement cycle assumptions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EPA Tier 3 implementation timelines, ECHA REACH restriction phase-in schedules, and China EV platform lightweighting procurement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Asian textile operators would shift outcomes beyond modeled ranges. Material shifts in biobased material certification requirements or carbon-accounting rule adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive Interior Materials Market