
 Global Automotive Roof Systems Market | 2026-2036
Global Automotive Roof Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Roof Systems Market Intelligence
Software-defined features for adjustable tinting and integrated ambient lighting in panoramic roofs is realigning the value proposition beyond simple hardware. Webasto SE specializes in a broad portfolio of convertible and sliding roof systems. Magna International Inc. leverages its vast manufacturing footprint and systems integration expertise. Inalfa Roof Systems competes through its focus on innovative large-format glass roof modules for global automakers.
Automotive roof systems are engineered structural and mechatronic assemblies forming a vehicle's upper enclosure. These modules often incorporate multi-layer safety glass or polycarbonate with high-strength steel frames to ensure occupant protection and torsional rigidity. The panoramic roof product type is a key differentiator in the premium passenger car and electric vehicle segments. Meanwhile, demand from the SUV vehicle type continues to drive volume for both sunroof and solid roof variants.
Federal Motor Vehicle Safety Standards from the US NHTSA, specifically those for roof crush resistance, set critical design constraints. In parallel, regulations under the EU Green Deal and China's dual carbon goals push for lightweight materials to improve efficiency. Supplier success will depend on managing the integration of new technologies while navigating these varied regional safety and environmental mandates.
Market Dynamics
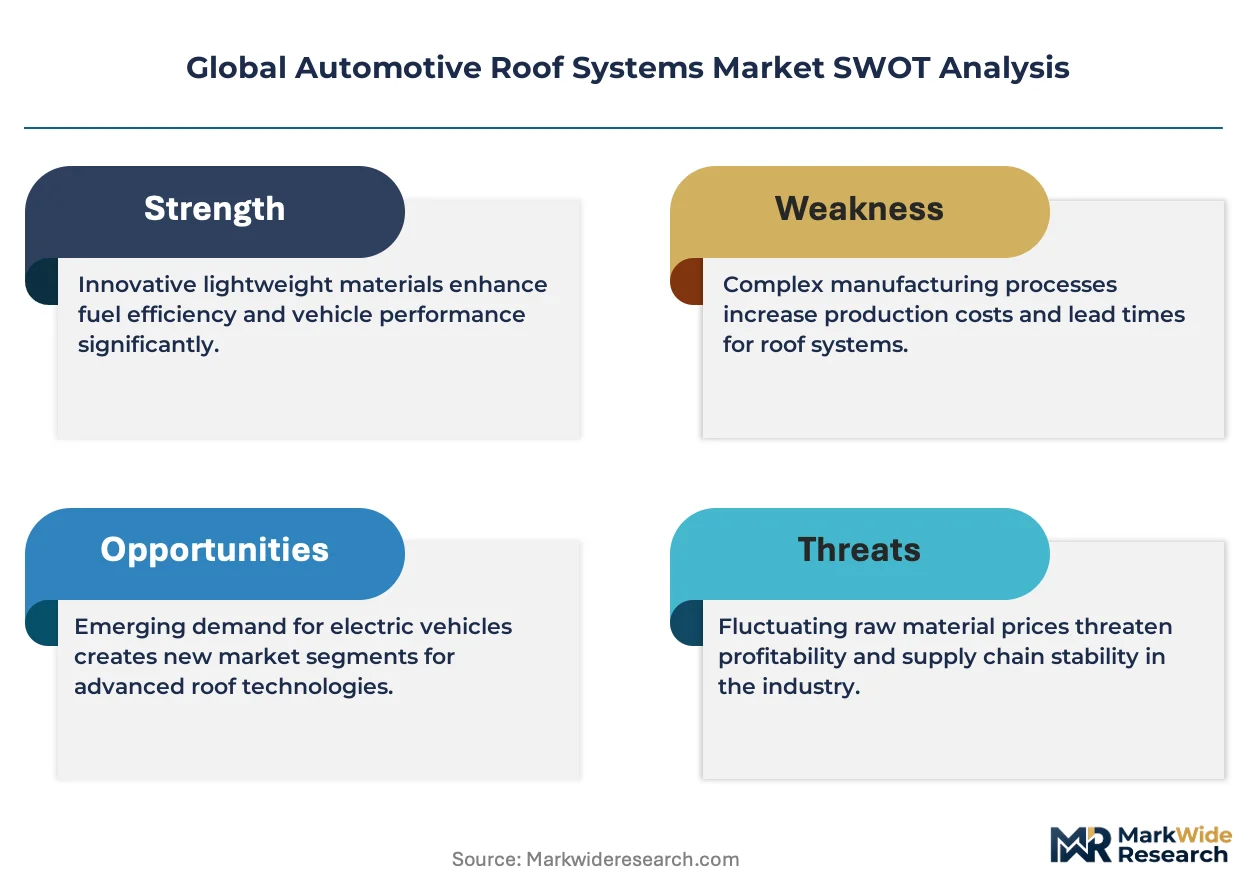
The convergence of electric vehicle design aesthetics, which favor expansive glass surfaces, with stringent emissions regulations from bodies like the EU and China is the central force shaping the automotive roof systems market, compelling innovation in lightweight, high-strength materials.
Growth Catalysts
- Regulatory Mandates:Policies such as the EU Green Deal and China's dual carbon goals compel automakers to reduce vehicle weight for better efficiency, directly spurring demand for roof systems made from lightweight composites and advanced polycarbonates.
- EV Design Preference:The electric vehicle segment's emphasis on futuristic design and open cabin feel drives the specification of large panoramic and full-glass roofs, which are becoming key product differentiators for automakers globally.
- Material Innovation:Advances in carbon fiber reinforced plastics and multi-layer laminated glass enable the production of larger, more complex roof modules that meet safety standards while contributing to overall vehicle lightweighting objectives.
Market Restraints
- High Material Costs:The significant cost premium of carbon fiber composites and large-format electrochromic glass compared to traditional steel and standard sunroof glass confines their use primarily to the luxury and high-end premium vehicle segments.
- Structural Engineering Complexity:Integrating large glass panels into a vehicle's body-in-white without compromising torsional rigidity or failing roof crush resistance tests, like those mandated by the US NHTSA, presents a major technical and cost hurdle.
- Supply Chain Bottlenecks:The supply of specialized raw materials, particularly automotive-grade polycarbonate resins and specific carbon fibers, is concentrated among a few producers, creating vulnerability to price volatility and potential production disruptions for roof system manufacturers.
Strategic Opportunities
- Smart Roof Integration:There is a significant opportunity to integrate smart glass technologies, such as user-controllable tinting and embedded ambient lighting, creating a new value proposition based on software-defined features and user experience.
- Solar Roof Development:Developing and commercializing photovoltaic roof systems for electric and hybrid vehicles offers a pathway to provide auxiliary power for onboard systems or contribute to marginal range extension, appealing to sustainability-focused consumers.
- Cost-Effective Panoramic Systems:Engineering lower-cost, standardized panoramic roof modules for high-volume, non-premium segments like compact SUVs and crossovers represents a major volume growth opportunity for suppliers able to optimize design and manufacturing.
Industry Challenges
- Mechatronic Integration:The complexity of integrating advanced mechatronics, including motors, sensors, and control software for features like retractable sunshades and switchable glass, into a vehicle's central electronics architecture is a persistent challenge.
- Divergent Safety Standards:Suppliers must navigate and engineer for conflicting or differing regional safety regulations, such as roof crush standards in the United States versus other global occupant protection mandates, which complicates platform standardization.
- High Capital Investment:The tooling and manufacturing lines required to produce large, complex, and precisely bonded glass or composite roof modules demand substantial capital expenditure, creating a high barrier to entry and pressuring supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Roof Systems Market |
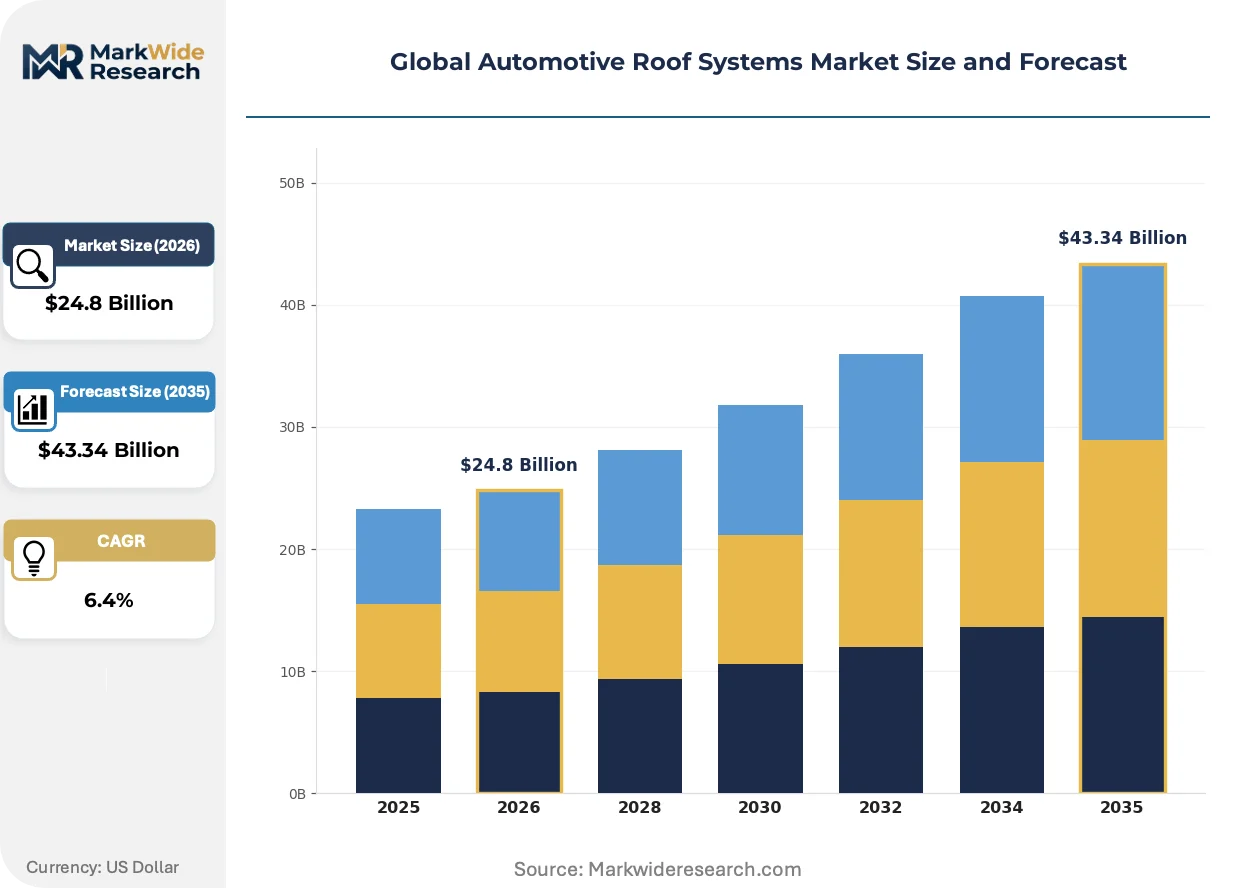
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic Roof, Sunroof, T-top, Convertible Roof, Moonroof Technology: Glass Roof, Fabric Roof, Metal Roof, Carbon Fiber Roof, Composite Roof Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Pickup Trucks, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Auto Dealerships, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Aisin Corporation, Magna International Inc., Webasto SE, Mobitech, Yachiyo Industry, Inalfa Roof Systems, CIE Automotive, Valmet Automotive Inc., Inteva Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Roof Systems Market Strategic Shifts & Innovations
The market's evolution is marked by the transformation of the roof from a passive structural element into an active, multi-functional system. This shift is driven by the integration of advanced electronics and materials that enhance occupant comfort, safety, and vehicle efficiency.
Smart glass technology, which includes electrochromic and suspended particle device (SPD) variants, provides electronically adjustable tinting on demand. Premium electric vehicle and luxury passenger car segments are the primary adopters of this feature as a key differentiator. This technology is consolidating the separate functions of a glass panel and a mechanical sunshade into a single, software-controlled component.
The US NHTSA's Federal Motor Vehicle Safety Standard 216, which governs roof crush resistance, imposes critical design constraints on all vehicles sold in the United States. This standard directly influences material selection and structural design, pushing suppliers toward using high-strength steel frames and composite reinforcements. The SUV and light truck segments are most impacted, as their large roof spans require sophisticated engineering to meet these stringent safety benchmarks.
Automakers are altering their procurement patterns by increasingly sourcing complete, pre-tested, and fully assembled roof modules from Tier 1 suppliers. This model displaces the traditional practice of sourcing individual components like glass, frames, and motors from multiple vendors. The shift is most visible in North American and European manufacturing hubs, where it helps streamline final vehicle assembly and improve quality control.
Global Automotive Roof Systems Market Segmentation
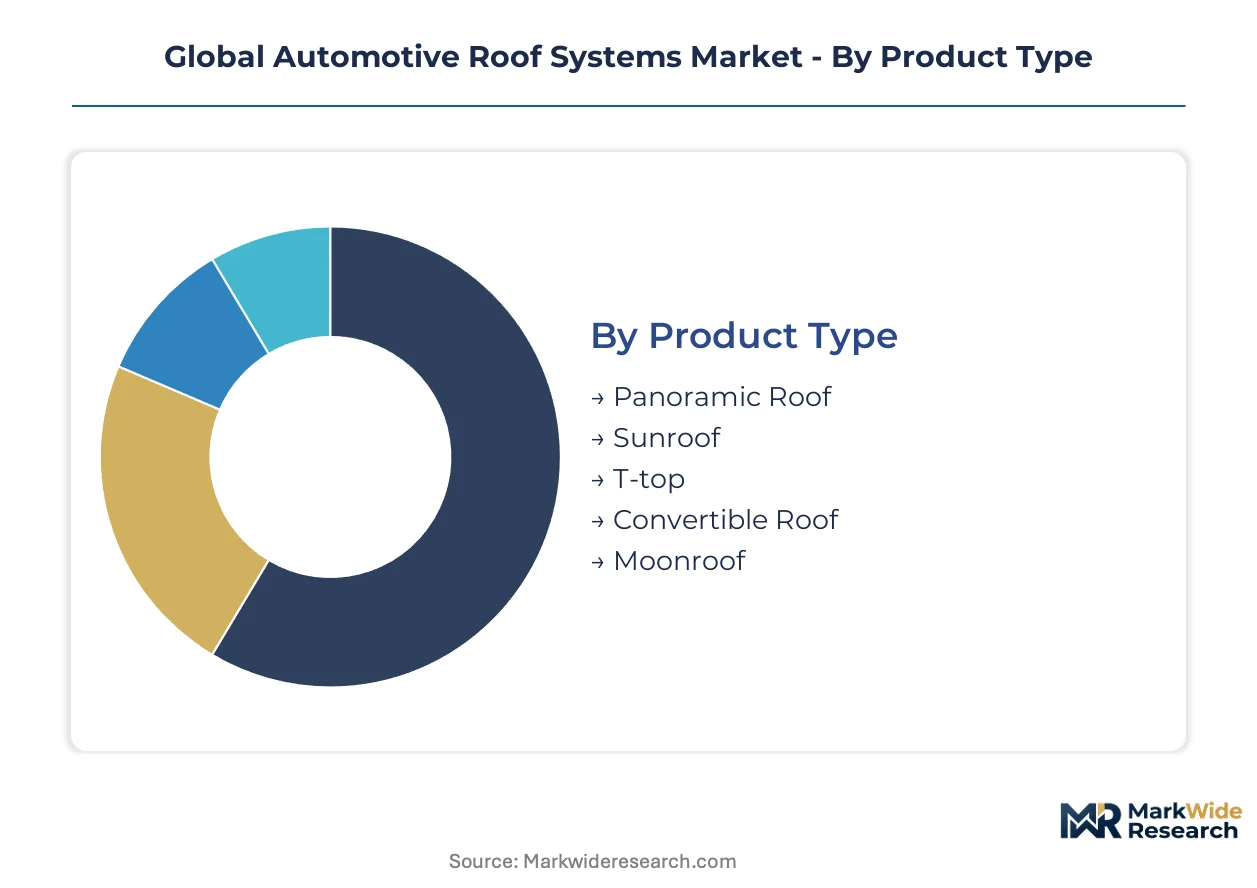
The automotive roof systems market segmentation provides a granular view of product evolution and strategic demand drivers. Understanding these distinct categories helps stakeholders identify areas of innovation, material shifts, and evolving consumer preferences across the global automotive landscape.
Product Type:
The product type segmentation highlights the bifurcation between high-volume standard offerings and premium, feature-rich roof systems.
- Panoramic Roof:These are large, fixed or opening glass panels extending across a significant portion of the vehicle's roof, often providing an expansive view. Demand concentrates in premium passenger cars and electric vehicles, driven by aesthetic appeal and an open-cabin feel.
- Convertible Roof:These complex mechatronic systems allow for the full retraction of the roof structure, frequently incorporating fabric or rigid panels. Adoption is concentrated in luxury and sports car segments, emphasizing open-air driving experiences and distinctive design.
- Sunroof:Traditional smaller glass panels, often with tilt and slide functions, remain common across various vehicle types.
- T-top:Removable roof panels over the front seats offer a semi-open experience, largely a niche retro feature in certain models.
- Moonroof:Typically a glass panel that tilts open, often integrated with a fixed glass roof section, popular in mid-range vehicles for added light.
Mature deployment sits with Sunroofs. Newer deployment is concentrated in Panoramic Roofs.
Technology:
This segment details the diverse material and construction approaches defining modern roof systems.
- Glass Roof:Comprises multi-layer laminated glass or toughened glass, often with integrated tinting or smart features for enhanced occupant comfort. Widespread adoption in electric vehicles and premium cars reflects a preference for expansive views and aesthetic integration.
- Carbon Fiber Roof:Constructed from carbon fiber reinforced plastics (CFRP) for extreme lightweighting and high structural rigidity, crucial for performance. Primarily utilized in high-performance sports cars and luxury electric vehicles to reduce weight and improve handling.
- Fabric Roof:Typically multi-layered textile materials used for convertible systems, prioritizing flexibility and compact storage when retracted.
- Metal Roof:Traditional steel or aluminum panels, forming the structural basis for solid roofs and some retractable systems, valued for durability.
- Composite Roof:Utilizes various fiber-reinforced polymers beyond carbon fiber, balancing weight reduction with cost-effectiveness for broader application.
Glass Roof technology exhibits the steepest expansion trajectory, driven by design trends and functional integration.
Vehicle Type:
The vehicle type segmentation illustrates how roof system specifications vary across different automotive platforms and consumer needs.
- SUVs:Characterized by large roof spans and often accommodating panoramic or large sunroofs for family-oriented designs. This segment drives significant volume for both fixed and opening roof systems, meeting consumer demand for versatility.
- Electric Vehicles:Frequently incorporate large glass roofs or solar-integrated panels, emphasizing futuristic aesthetics and energy efficiency. This segment is a primary catalyst for innovation in lightweight materials and smart glass technologies.
- Passenger Cars:Includes sedans and hatchbacks, where sunroofs and panoramic roofs enhance comfort and market appeal for daily driving.
- Commercial Vehicles:Primarily utilize solid roofs or basic hatches, focusing on durability and utility rather than aesthetic features.
- Pickup Trucks:Often feature solid roofs, with some higher trims offering sunroofs, balancing ruggedness with comfort and utility.
SUVs and Electric Vehicles collectively account for the largest share of advanced roof system installations.
End User:
This segmentation delineates the primary recipients and integrators of automotive roof systems across the value chain.
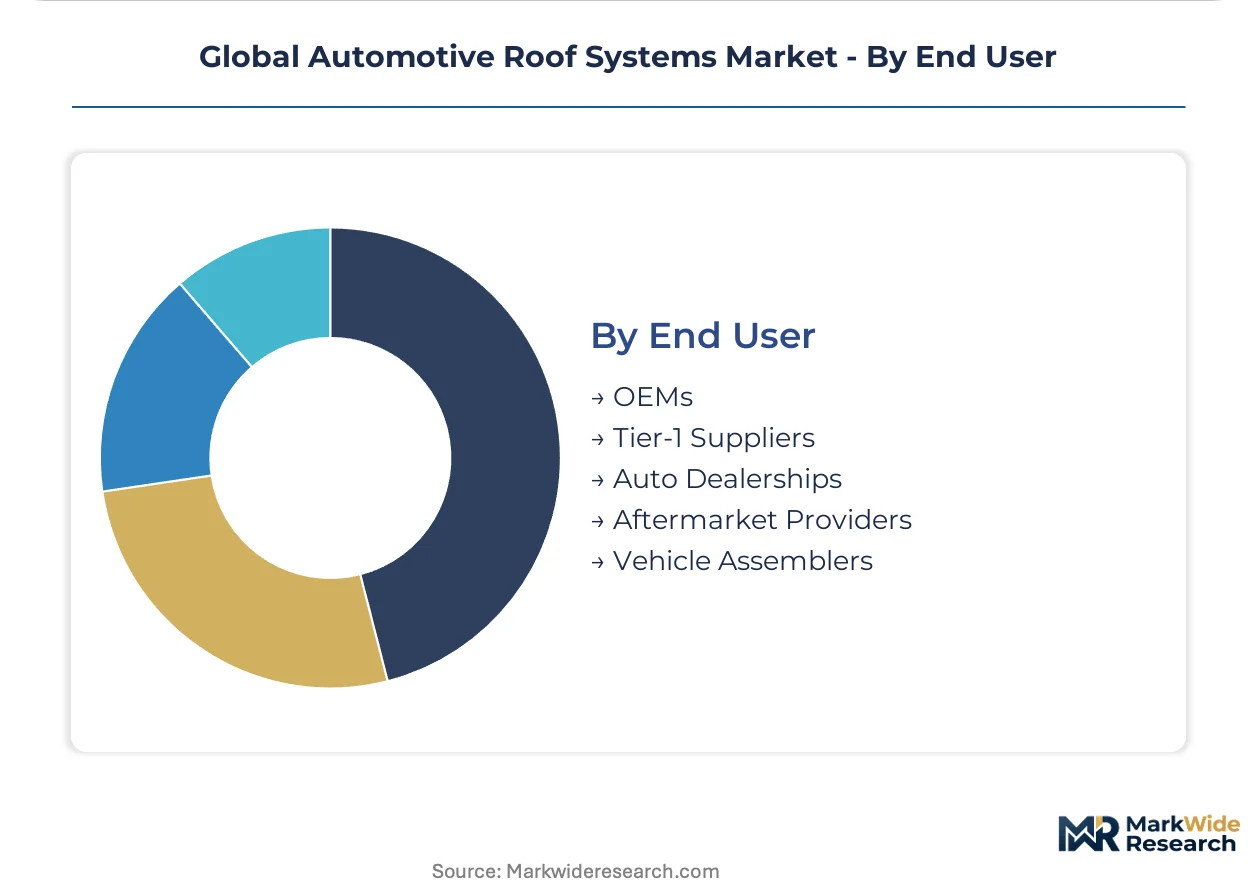
- OEMs:Original Equipment Manufacturers integrate roof systems directly into new vehicle assembly lines as complete modules. Their procurement strategies increasingly favor pre-tested, fully assembled units from Tier 1 suppliers to streamline production.
- Tier-1 Suppliers:These companies design, engineer, and manufacture complete roof modules, often incorporating components from lower-tier suppliers. They manage complex mechatronic integration and material sourcing, delivering ready-to-install systems to automakers.
- Vehicle Assemblers:Companies involved in the final assembly of vehicles, receiving roof systems as part of larger kits for integration.
- Aftermarket Providers:Supply replacement parts and upgrade kits for roof systems, serving repair and customization needs for existing vehicles.
- Auto Dealerships:Sell vehicles equipped with various roof systems and offer limited post-sale accessory installations or repairs.
OEMs represent the largest purchasing entity, while Tier-1 Suppliers drive the majority of innovative product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive manufacturing hubs in the Yangtze River Delta region, particularly around Shanghai, drive significant demand for advanced roof systems. This region benefits from extensive electric vehicle production and a focus on premium vehicle design. Regulatory support from China's dual carbon goals further accelerates innovation in lightweight materials for these systems.
China
Demand for panoramic and large glass roofs in electric vehicles is substantial across China, driven by consumer preference for modern aesthetics. China's dual carbon goals compel automakers to prioritize lightweight materials, including advanced composites, for improved vehicle efficiency. Shanghai's automotive manufacturing cluster, with its numerous EV plants, is a significant center for roof system procurement.
Germany
Premium passenger cars and luxury electric vehicles in Germany consistently specify advanced roof systems, including smart glass technologies. The EU Green Deal regulations push German automakers toward lighter vehicle components, fostering innovation in carbon fiber and composite roof structures. Stuttgart and Munich, key automotive R&D centers, lead development in mechatronic roof systems.
United States
The United States market sees robust demand for panoramic roofs in SUVs and pickup trucks, reflecting consumer preferences for spacious interiors. US NHTSA roof crush resistance standards critically influence the structural design and material selection for all roof systems sold. Detroit's traditional automotive manufacturing base continues to integrate advanced roof modules into new vehicle platforms.
Japan
Japanese automakers increasingly incorporate advanced sunroofs and lightweight roof systems into their diverse vehicle lineups, balancing innovation with practicality. METI's efficiency targets encourage the use of lighter materials and more aerodynamic roof designs across the automotive sector. Toyota City and other industrial clusters drive the adoption of sophisticated roof technologies for both domestic and export models.
India
Rising disposable incomes and evolving consumer preferences in India are increasing the specification of sunroofs and panoramic roofs in mid-range passenger cars. The Indian government's PLI scheme for auto components supports domestic manufacturing and technological upgrades within the automotive supply chain. Chennai's automotive hub, home to major production facilities, is expanding its capacity for advanced roof system integration.
Global Automotive Roof Systems Market Key Industry Players
Capital-heavy producers of complete roof modules compete with more specialized component suppliers in the automotive roof systems market. The market structure is highly concentrated among a few global Tier-1 suppliers providing integrated solutions to OEMs. Strategic archetypes include large-scale integrators, niche technology specialists, and regional manufacturers. These players engage in technology licensing and strategic partnerships to expand their market reach and technological capabilities.
Among leading Tier-1 suppliers, Magna International Inc. exemplifies a broad manufacturing footprint and extensive systems integration capabilities across diverse automotive components, serving as a comprehensive solution provider. Webasto SE represents a long-standing specialization in convertible and sliding roof systems, occupying a position as a global leader in complex mechatronic assemblies and advanced material applications. Inalfa Roof Systems anchors its competitive strategy on innovative large-format glass roof modules for global automakers, demonstrating a focus on advanced design and seamless integration expertise, particularly for premium and electric vehicle segments worldwide.
| Leading Market Players |
|---|
| Aisin Corporation |
| Magna International Inc. |
| Webasto SE |
| Mobitech |
| Yachiyo Industry |
| Inalfa Roof Systems |
| CIE Automotive |
| Valmet Automotive Inc. |
| Inteva Products LLC |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and China's dual carbon goals, compelling automakers to reduce vehicle weight, gate both qualified supply of lightweight materials and premium-tier pricing access for advanced roof systems. This market balances cost-efficiency for high-volume segments with performance-driven pricing for specialized components.
Pricing Analysis
Performance-based pricing anchors the valuation of advanced roof systems, reflecting their contribution to vehicle lightweighting and enhanced user experience. Price differentiation stems from material sophistication, such as carbon fiber composites versus multi-layer glass, and the integration complexity of mechatronic features. Pricing pressure intensifies within the standard sunroof segment due to commoditization and high competition among suppliers. Luxury electric vehicles and premium passenger cars exhibit the least price sensitivity, valuing innovation and integrated features, while commercial vehicles and entry-level passenger cars remain most price-sensitive.
Supply Chain Analysis
Specialized glass and advanced composite material supply rests on a concentrated base of producers, primarily in countries like Germany, Japan, and China. Raw material dependencies include automotive-grade polycarbonate resins, specific carbon fibers, and electrochromic films for smart glass technologies. Single-source vulnerability for these specialized inputs presents a structural supply chain risk for roof system manufacturers. Distribution runs predominantly through Tier-1 suppliers, who deliver complete, pre-tested roof modules directly to Original Equipment Manufacturers for assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players actively pursuing control over advanced material sourcing and software-defined feature development. Strategic moves will differentiate suppliers in a consolidating landscape.
For Market Incumbents:
Acquire niche technology specialists in smart glass or advanced composite materials to secure intellectual property and production capabilities. Invest heavily in mechatronics R&D to integrate complex features like retractable sunshades and switchable glass. This defends against emerging smart glass alternatives and mitigates margin pressure from commoditized components. Certification investment in new roof crush standards for SUVs ensures continued market access.
For New Entrants and Emerging Players:
Technology licensing partnerships with smaller OEMs offer a viable entry point into the cost-effective panoramic roof segment for compact SUVs. Focus on modular component supply for standardized sunroof applications in mid-range passenger cars. This allows new players to gain volume and establish manufacturing expertise without the high capital expenditure required for full module integration. Emphasize innovative, lower-cost material combinations.
For Investors and Strategic Acquirers:
Widespread adoption of Level 3+ autonomous vehicles is the leading indicator that will accelerate demand for enhanced cabin experiences, including advanced roof systems. The market demonstrates long-term viability for integrated, software-defined solutions over the next decade. Acquisition targets should include specialized material providers, mechatronics integrators, and software developers focused on in-cabin experience. Geopolitical stability affecting key material supply chains warrants ongoing watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity and costs for high-volume vehicle segments. |
| Software-Defined Roof Investment | Enhances user experience with adjustable tinting and integrated ambient lighting features. |
| Advanced Material R&D | Enables lightweighting and improved structural integrity to meet stringent regulations. |
| Supply Chain Diversification | Mitigates risks associated with concentrated raw material and component sourcing. |
| Solar Integration Partnership | Provides auxiliary power for onboard systems and contributes to EV range extension. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were then validated through primary interviews with automotive Tier 1 engineering leads, OEM procurement specialists, and material scientists. This approach combined qualitative insights with quantitative data, ensuring a robust foundation for market analysis. The research utilized both bottom-up and top-down triangulation to verify market sizing and growth projections.
Market granularity informed the analytical framework, with dimensions modeled by product type, technology, vehicle type, and regional production clusters across the analysis window. Compound annual growth rates were derived from historical trends, market growth drivers, and expert projections, capturing the dynamic nature of the industry. Industry-specific inputs, such as electric vehicle production forecasts and lightweighting material cost curves, refined the quantitative model.
Caveats apply where geopolitical disruptions affecting material supply, unforeseen changes in safety regulations, or significant shifts in consumer design preferences could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market