
 Car Speaker Market | 2026-2036
Car Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Car Speaker Market Analysis
Acoustic engineering talent scarcity in traditional manufacturing hubs is unwinding as Southeast Asian technical institutes expand electroacoustics programs. Harman International leverages its captive transducer factories in Mexico and Hungary to sustain OEM contract margins. Pioneer competes through deep aftermarket channel control across Latin American distributor networks. Alpine specializes in compact multi-channel amplifiers integrated with its speaker lines, occupying the premium RV and marine crossover segment.
A car speaker is an electromechanical transducer converting amplified electrical signals into audible sound waves, typically employing polypropylene or aramid fiber cones with butyl rubber surrounds to achieve frequency response from 20 Hz to 20 kHz in multi-driver configurations. Its primary commercial purpose is reproducing music, navigation prompts, and hands-free communications within vehicle cabins. Coaxial units dominate volume shipments due to single-point installation efficiency in economy and mid-range vehicles, while component systems capture disproportionate margin pools through separate tweeter and woofer placement. Subwoofers represent the fastest-growing product category as electric vehicle platforms free trunk space previously occupied by exhaust hardware. Bluetooth connectivity is displacing wired installations in aftermarket retrofit jobs, though USB retains relevance in fleet vehicle standardization programs.
The EPA regulates hazardous substance thresholds in speaker adhesives and solder under TSCA, while FCC certification governs wireless connectivity modules embedded in Bluetooth-enabled units. NHTSA distraction guidelines indirectly shape speaker placement and voice-prompt clarity standards for OEM installations. ISO 16750 vibration and temperature testing protocols determine product qualification for tier-one automotive supplier status. Stakeholders must monitor how California's advancing prop 65 enforcement on phthalate content in speaker surrounds may cascade into broader North American material specification changes.
Market Dynamics
Electric vehicle platform architectures are eliminating exhaust-system packaging constraints, liberating trunk and cabin cavities previously unavailable for subwoofer enclosures and multi-channel audio arrays. This spatial dividend is redirecting engineering resources toward acoustic optimization rather than mechanical compromise.
Growth Catalysts
- EU Green Deal material mandates:Lead-free solder requirements and recycled cone material quotas are accelerating supplier qualification programs across German and Hungarian manufacturing clusters.
- Bluetooth module integration:Wireless retrofit protocols are collapsing installation labor costs for aftermarket channel partners serving fleet vehicle operators.
- Thailand technical education expansion:Electroacoustics program graduates from Bangkok-area polytechnics are relieving transducer engineering bottlenecks previously concentrated in Mexican and Eastern European production hubs.
Market Restraints
- Rare-earth magnet price volatility:Neodymium supply concentration in Chinese processing facilities creates margin compression for ferrite-alternative motor designs.
- Butyl rubber import dependency:Surround material sourcing from Southeast Asian petrochemical complexes exposes tier-two suppliers to shipping lane disruptions.
- FCC certification timelines:Bluetooth-enabled unit approvals average fourteen months, freezing product launch windows for wireless-first aftermarket strategies.
Strategic Opportunities
- India two-wheeler audio retrofit:Premium scooter and motorcycle owners in Bangalore and Pune represent an unserved addressable base for compact coaxial weatherproof units.
- ISO 16750 qualification arbitrage:Vibration and temperature testing protocol compliance is creating tier-one supplier status barriers that rewarded early adopters can monetize through OEM contract premiums.
- Voice-prompt clarity mandates:NHTSA distraction guidelines are forcing navigation system integrators to specify wider-dispersion tweeter arrays, opening specification influence channels for component system vendors.
Industry Challenges
- Acoustic simulation software proficiency:Finite element analysis expertise for cone breakup mode prediction remains concentrated among senior engineers at established transducer houses.
- Prop 65 phthalate compliance:California enforcement on surround material composition is forcing dual-specification inventory management for North American versus export production lines.
- Amplifier-speaker impedance matching:OEM infotainment system integration complexity is extending validation cycles for aftermarket component system bundles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Speaker Market |
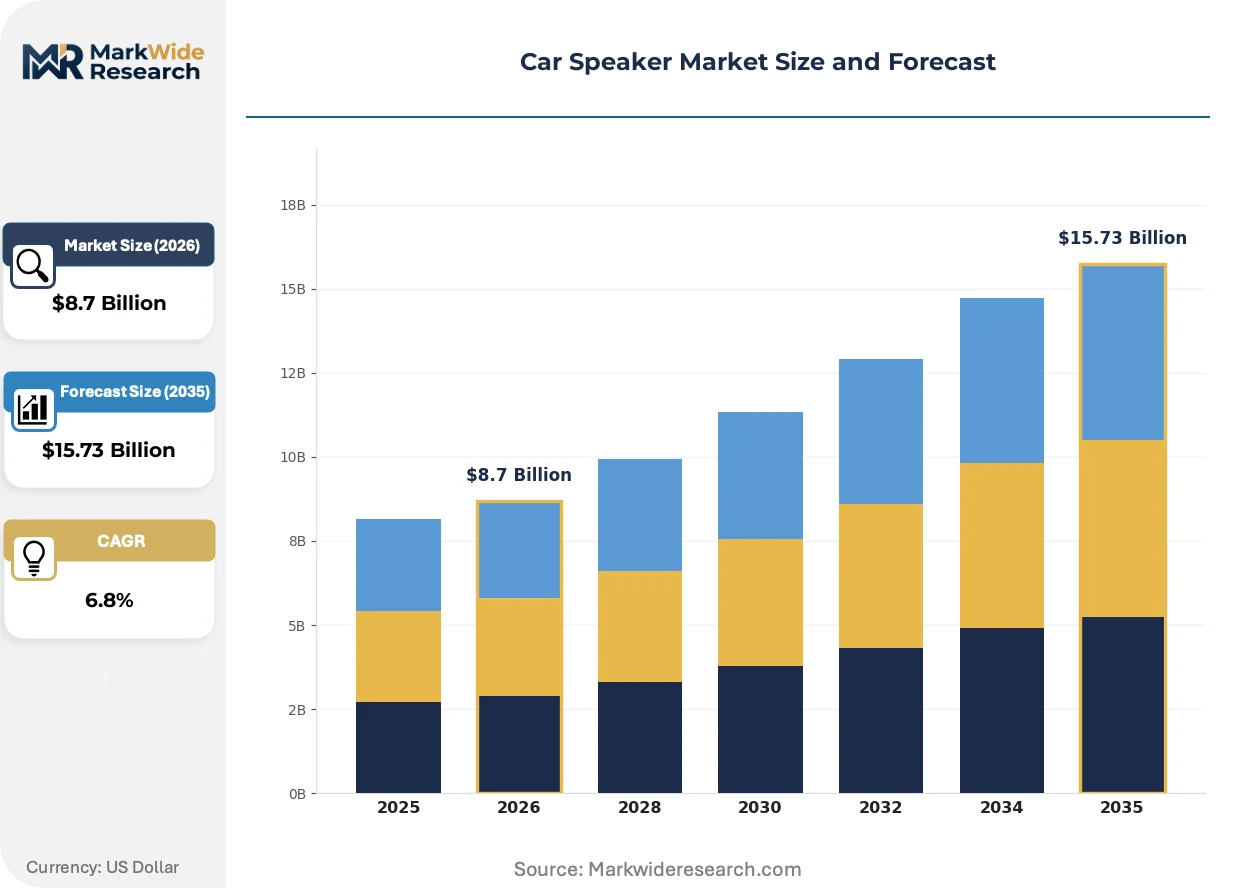
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial, Component, Subwoofer, Tweeter Installation Type: OEM, Aftermarket, Custom, Standard Connectivity: Wired, Bluetooth, Wi-Fi, USB Power Rating: 50W, 100W, 200W, Others |
| Companies Covered | Rockford Fosgate, Focal, Harman International, Hertz, Alpine, Pioneer, JL Audio, Morel, Audiovox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Speaker Market Emerging Trajectories
Audio reproduction architectures are splitting between minimalist cabin-integrated solutions and enthusiast-grade customizable configurations. This divergence is fragmenting supplier R&D roadmaps and reshaping distribution channel specialization.
Subwoofer enclosure designs are bifurcating between sealed acoustic-suspension units favored by German OEM supply chains and ported bass-reflex configurations dominating Latin American aftermarket preferences. Electric vehicle manufacturers specify sealed designs for packaging efficiency, while tuning shops exploit ported architectures for maximum SPL-per-watt performance. The technology split is compressing economies of scale for transducer motor platforms and forcing dual-SKU production strategies at captive factories.
REACH substance restrictions on SVHC candidate list entries are eliminating legacy PVC surround formulations from EU-bound production lines. Compound suppliers in the Netherlands and Belgium are accelerating TPE and silicone alternative qualification. Premium component system manufacturers absorb material cost premiums through OEM contract pricing power, while economy coaxial producers face margin erosion or geographic market withdrawal.
Installation labor models are unbundling from product margin capture across North American specialty retailer networks. Mobile electronics installers in Texas and Florida are transitioning to flat-rate service billing decoupled from equipment markup, compressing traditional distributor financing structures. Fleet vehicle standardization programs retain bundled procurement, creating a two-channel revenue architecture that rewards distinct operational capabilities.
Car Speaker Market Segmentation
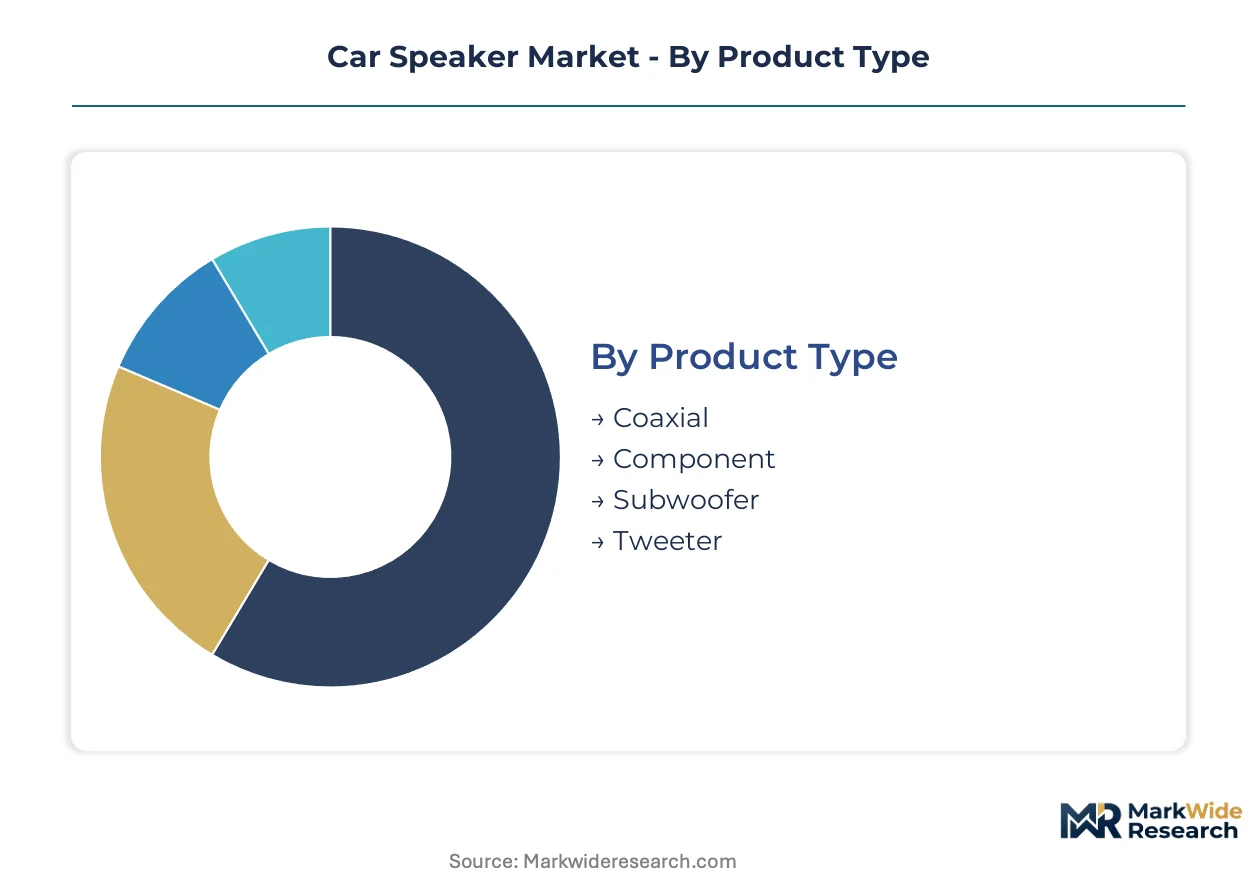
Segmentation in car speakers reveals how acoustic engineering priorities diverge across vehicle platforms and consumer budgets. Product architecture choices directly determine supplier qualification paths and margin capture potential.
Product Type:
Bluetooth-enabled smart speakers and smartphone-integrated audio systems exert substitution pressure on traditional electromechanical transducers, particularly in entry-level vehicle configurations where cabin space is constrained.
- Coaxial:Integrates tweeter and woofer on a single axis with built-in crossover, reducing installation complexity and wiring runs. Economy and mid-range vehicle production in Mexico and Thailand concentrates demand here, driven by single-point mounting efficiency on high-volume assembly lines. Coaxial units anchor the volume base while Subwoofer gains share at the steepest rate.
- Component:Separates tweeter, woofer, and external crossover for optimized placement and imaging. German premium OEM supply chains and Bangalore tuning shops specify these systems, compelled by acoustic performance differentiation in luxury vehicle segments and enthusiast retrofit markets.
- Subwoofer:Dedicated low-frequency transducers exploiting trunk space liberated by electric vehicle platform architectures.
- Tweeter:High-frequency drivers using silk, aluminum, or beryllium domes for extended response.
Component systems command pricing premiums through placement flexibility, though coaxial units dominate fleet procurement volumes.
Installation Type:
Cost tier stratification separates captive OEM supply contracts from fragmented aftermarket service models, with labor billing structures determining margin retention across channels.
- OEM:Factory-installed units specified by vehicle manufacturers and supplied through tier-one automotive contracts. German and Hungarian manufacturing clusters concentrate production here, shaped by ISO 16750 vibration qualification requirements and EU Green Deal material compliance mandates.
- Aftermarket:Retrofit installations replacing or augmenting factory audio systems. Texas and Florida mobile electronics installers drive demand through flat-rate service billing models, pressured by unbundling of labor from equipment markup.
- Custom:Bespoke fabrication for show vehicles and competition audio builds.
- Standard:Basic replacement units matching factory specifications.
Aftermarket channels expand most quickly in electric vehicle retrofit applications, while OEM retains contract stability through platform lifecycle commitments.
Connectivity:
Wireless protocol adoption is compressing installation labor costs and redirecting validation resources toward electromagnetic compliance testing.
- Wired:Traditional copper conductor installations with RCA or speaker-level inputs. Fleet vehicle standardization programs in North America sustain demand here, constrained by procurement protocols favoring proven architectures over emerging wireless standards.
- Bluetooth:Wireless audio streaming with integrated control protocols. Latin American distributor networks and European tuning shops are expanding SKU breadth here, propelled by collapsed installation timelines and consumer preference for smartphone integration.
- Wi-Fi:High-bandwidth wireless for multi-zone audio and lossless streaming.
- USB:Digital audio input with charging and data connectivity.
Wired installations retain fleet procurement dominance as Bluetooth climbs fastest in consumer aftermarket retrofits.
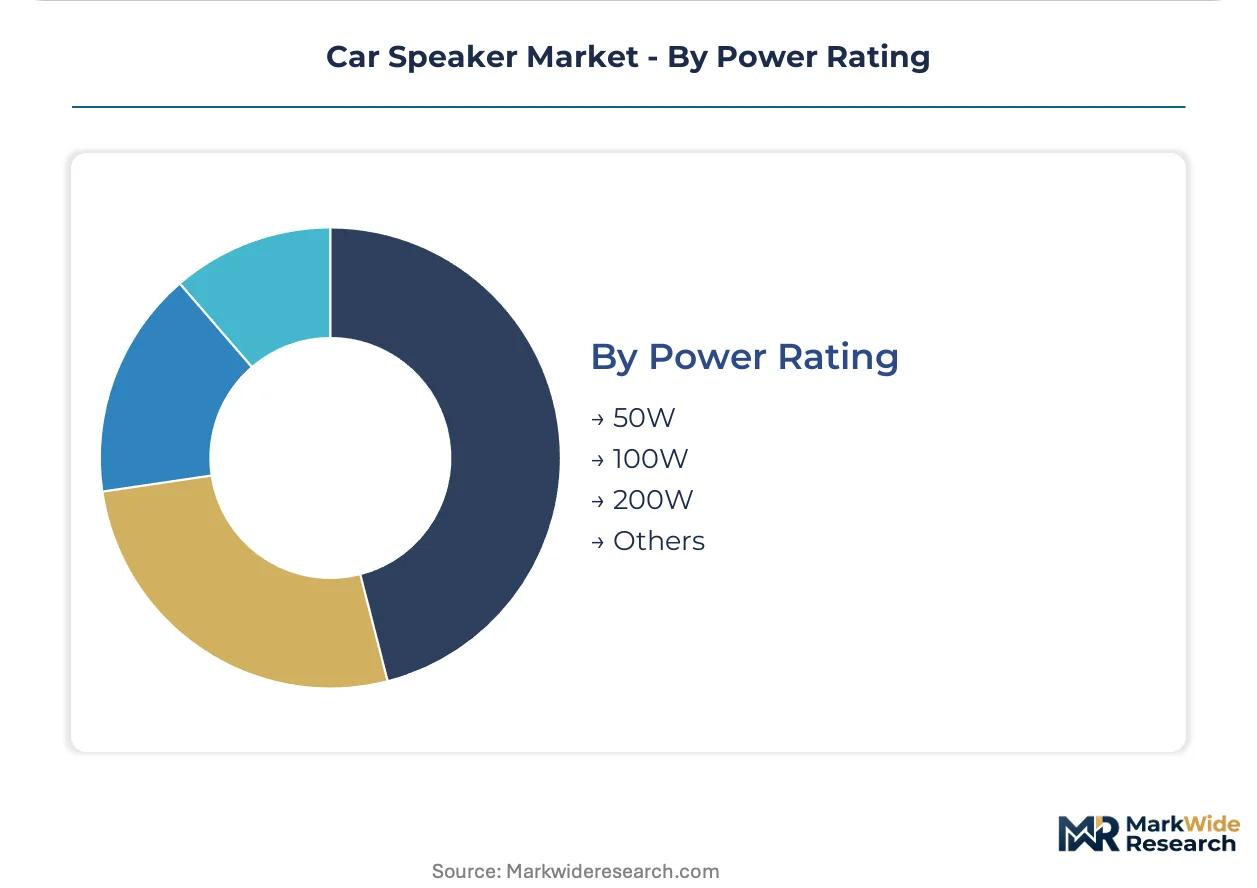
Power Rating:
Amplifier matching requirements segment suppliers by thermal management capability and magnet motor design sophistication.
- 50W:Entry-level units for factory head unit compatibility without external amplification. Economy vehicle production across Indian and Southeast Asian assembly plants concentrates volume here, driven by cost minimization in mass-market segments.
- 100W:Mid-range transducers balancing efficiency and output capability. Premium scooter and motorcycle retrofit markets in Pune and Bangalore specify these ratings, compelled by compact amplifier integration in two-wheeler electrical systems.
- 200W:High-excursion designs for subwoofer and competition applications.
- Others:Specialized ratings for OEM-integrated amplifier systems and pro audio crossover builds.
50W ratings dominate unit volume as 100W specifications expand most quickly in premium two-wheeler retrofit segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German vehicle owners prioritize component speaker upgrades through tuning shops, while Thai and Mexican production clusters feed high-volume coaxial demand into economy vehicle assembly lines. This consumption-mix differential separates premium retrofit markets from captive OEM supply chains.
Germany
Premium OEM supply chains and dense tuning shop networks sustain above-average speaker replacement rates. EU Green Deal material compliance mandates push manufacturers toward lead-free solder and recycled cone materials. Manufacturing clusters in Hungary and Eastern Bavaria concentrate transducer production for tier-one automotive contracts.
United States
Texas and Florida mobile electronics installers drive aftermarket retrofit demand through flat-rate service billing models. EPA hazardous substance thresholds under TSCA regulate speaker adhesives and solder formulations. California Prop 65 enforcement on phthalate content in speaker surrounds forces dual-specification inventory management for North American production lines.
Thailand
Bangkok-area polytechnics expand electroacoustics programs, relieving transducer engineering bottlenecks previously concentrated in Mexican and Eastern European hubs. Domestic technical education expansion feeds workforce supply into regional manufacturing. Assembly plants around Rayong and Chonburi integrate locally sourced coaxial units into economy vehicle exports.
Mexico
Captive transducer factories supply OEM contract volumes to North American vehicle assembly operations. NHTSA distraction guidelines shape speaker placement and voice-prompt clarity standards for factory installations. Manufacturing corridors in Baja California and Guanajuato concentrate production capacity serving US-bound automotive platforms.
India
Premium scooter and motorcycle owners in Bangalore and Pune represent an unserved addressable base for compact coaxial weatherproof units. BIS certification requirements govern electrical safety and electromagnetic compatibility for automotive audio components. Component system retrofit activity concentrates in Karnataka and Maharashtra tuning shops serving enthusiast two-wheeler segments.
Car Speaker Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive manufacturing assets determining contract access to premium OEM supply chains. The upper tier commands tier-one automotive supplier status through ISO 16750 vibration qualification, while mid-scale players compete on aftermarket channel control and installation labor relationships. Two strategic archetypes dominate: vertically integrated transducer houses with captive magnet motor production, and distribution-focused specialists leveraging regional installer networks. Competitive moves concentrate on manufacturing footprint expansion in low-cost technical education clusters and dual-SKU production strategies accommodating sealed versus ported enclosure preferences.
Within the integrated tier, Harman International and Alpine occupy positions defined by captive factory networks and amplifier-speaker bundling capabilities. Pioneer exemplifies the distribution-architecture archetype through Latin American channel control. JL Audio represents the enthusiast-specialist position, with product architectures targeting competition audio and premium retrofit segments.
| Leading Market Players |
|---|
| Rockford Fosgate |
| Focal |
| Harman International |
| Hertz |
| Alpine |
| Pioneer |
| JL Audio |
| Morel |
| Audiovox Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German OEM procurement offices and Hungarian transducer factories lock in neodymium magnet supply visibility while insulating tier-one suppliers from spot-market rare-earth volatility. These contracts bundle ISO 16750 qualification costs into multi-year pricing schedules, compressing margin flexibility for manufacturers serving aftermarket channels.
Pricing Analysis
Project-based pricing dominates OEM contracts, with tier-one suppliers capturing premiums through bundled vibration testing and material compliance documentation. Three-tier pricing structure across premium, standard, and economy levels separates component systems with beryllium tweeters from polypropylene coaxial units. Cost compression in economy coaxial tiers is intensifying because REACH-compliant TPE surround materials carry 15-20% raw material premiums over legacy PVC. Fleet vehicle operators exhibit highest price sensitivity, while German tuning shops absorb markups for placement-optimized component configurations.
Supply Chain Analysis
Strategic stockpiling of butyl rubber surrounds characterizes tier-one supplier inventory strategies, buffering Southeast Asian petrochemical supply disruptions. Magnet motor production concentrates in China, Hungary, and Mexico, with rare-earth processing anchored in Chinese facilities. Ferrite-alternative motor designs rest on cobalt and nickel supply chains from Indonesian and Philippine mining operations. Single-source vulnerability in neodymium separation creates qualification bottlenecks for new supplier entrants. Distribution runs through captive OEM logistics networks for factory installations, while aftermarket channels fragment across Latin American distributor consignment and North American mobile installer direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation labor unbundling from equipment markup represents a service-attach opportunity expanding faster than hardware revenue, as Texas and Florida mobile electronics installers transition to flat-rate diagnostic and tuning billing.
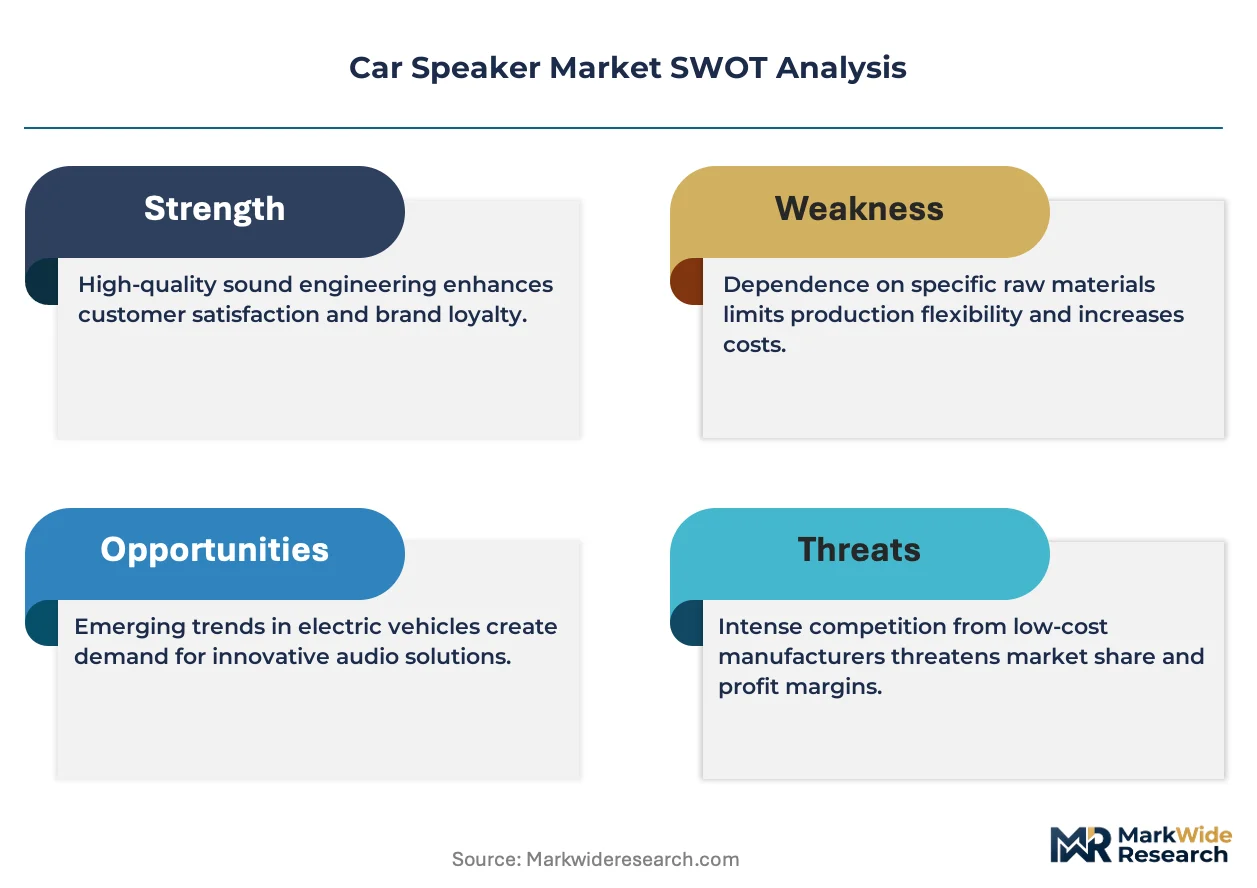
For Market Incumbents: Consolidate backward integration into cone material recycling streams to absorb EU Green Deal compliance premiums without margin erosion. Lock in Bangkok-area polytechnic graduate pipelines before competitor qualification programs mature. Defensive positioning against Bluetooth-enabled wireless retrofit entrants requires accelerating FCC pre-certification investments to collapse fourteen-month approval timelines. For New Entrants and Emerging Players: Aftermarket voice-prompt clarity optimization services present a service-layer gap where incumbents under-serve NHTSA guideline compliance demand. Target Bangalore and Pune two-wheeler tuning shops with compact coaxial weatherproof units rated for monsoon exposure. Pursue ISO 16750 qualification arbitrage by partnering with established testing houses before tier-one supplier status barriers fully crystallize. For Investors and Strategic Acquirers: Regional amplifier-speaker bundling specialists with captive Southeast Asian cone sourcing represent the acquisition target archetype most exposed to margin expansion from EU material mandates. Long-term viability hinges on electric vehicle platform lifecycle commitments extending through mid-next-decade production horizons. Watch NHTSA distraction guideline enforcement intensity as the inflection indicator for wider-dispersion tweeter specification pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Magnet Motor Production | Backward integration into neodymium motor assembly insulates Harman and Alpine from Chinese processing concentration. |
| EU Green Deal Material Compliance | Lead-free solder and recycled cone qualification creates tier-one supplier status barriers rewarded through OEM contract premiums. |
| Bluetooth Module Pre-Certification | FCC fourteen-month approval timeline compression enables faster aftermarket wireless retrofit product launches. |
| Bangkok Technical Education Partnerships | Electroacoustics program graduate pipelines relieve transducer engineering scarcity previously concentrated in Mexican hubs. |
| Dual-SKU Enclosure Strategy | Sealed and ported subwoofer variants accommodate German OEM packaging efficiency and Latin American SPL performance preferences. |
Methodological Framework
Cross-validation between tier-one automotive supplier procurement interviews and vehicle production database analysis anchors the qualitative findings. Primary fieldwork encompassed OEM platform engineers, aftermarket distributor operations heads, mobile electronics installers, and cone material compound suppliers. Secondary sources included EPA TSCA substance filings, FCC equipment authorization databases, EU ECHA SVHC candidate list updates, and IHS Markit vehicle registration data. Bottom-up unit volume estimates triangulated against top-down automotive content-per-vehicle spending analysis.
Sensitivity analysis across rare-earth price volatility scenarios and REACH substance restriction timelines shaped the analytical framework. Segmentation dimensions modeled encompass product architecture, installation channel, connectivity protocol, and power rating tier, with electric vehicle platform penetration as the industry-specific demand driver. CAGRs derived from logistic diffusion curves fitted to historical replacement cycle data and projected EV adoption trajectories. Neodymium magnet cost pass-through rates and butyl rubber shipping lane reliability served as key forecast inputs throughout the projection horizon.
Forecasts assume regulatory continuity in EPA TSCA enforcement and EU Green Deal material mandates; material policy shifts would require re-modeling supplier qualification timelines and cost pass-through assumptions. Revision becomes warranted when rare-earth magnet price volatility exceeds historical bands or California Prop 65 phthalate enforcement cascades into broader North American specification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Steering Roll Connector Market