
 Automotive Over-The-Air (OTA) Updates Market | 2026-2036
Automotive Over-The-Air (OTA) Updates Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Over-The-Air (OTA) Updates Market Analysis
ISO/SAE 21434 cybersecurity certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Robert Bosch GmbH leverages its Tier-1 integration depth to anchor large-scale OTA programs across European OEMs. Tesla sustains end-to-end control over its proprietary update stack, from cloud infrastructure to vehicle execution. Qualcomm Technologies differentiates through chipset-level security enclaves that streamline certification for downstream software vendors.
Automotive Over-The-Air (OTA) updates deliver encrypted software packages to vehicle electronic control units via wireless networks, typically using differential compression to minimize cellular data consumption and verification protocols to ensure firmware integrity before installation. The technology enables remote bug fixes, feature activation, and safety patches without physical service center visits, reducing warranty costs and improving fleet uptime. Public cloud deployment models lead in scalability for mass-market OEMs, while private cloud and hybrid architectures dominate among premium manufacturers seeking data sovereignty. Fleet operators represent the fastest-growing end user category as commercial vehicle operators pursue centralized management of heterogeneous vehicle populations across distributed logistics networks.
UN R155 in Europe, China's GB/T vehicle cybersecurity standards, and the U.S. NHTSA cybersecurity guidance collectively mandate systematic risk management for software updates, forcing suppliers to re-architect delivery pipelines around certified processes. The EU AI Act and GDPR impose additional constraints on AI-infused OTA features such as automated driving function upgrades, creating compliance complexity for cloud-hosted inference models. Stakeholders must monitor divergence between regional certification requirements and assess whether single-stack architectures can satisfy multi-jurisdictional mandates without prohibitive engineering overhead.
Market Dynamics
UN R155 vehicle cybersecurity regulations are forcing OEMs to re-architect software delivery pipelines around certified risk management processes, compressing supplier qualification timelines and elevating architecture security to a competitive differentiator.
Growth Catalysts
- UN R155 Mandate:European OEMs must implement systematic cybersecurity management systems for OTA delivery, creating compliance-driven procurement cycles for certified update platforms.
- Fleet Telematics Expansion:Commercial vehicle operators across Germany, China, and the United States are deploying centralized OTA management to synchronize heterogeneous vehicle populations across distributed logistics networks.
- Differential Compression Algorithms:Advanced delta-update protocols reduce cellular data consumption by transmitting only changed code segments, enabling cost-effective updates for mass-market connected vehicles.
Market Restraints
- Cellular Infrastructure Dependency:Reliable OTA delivery requires consistent 4G/5G coverage, creating service gaps in rural China and remote United States interstate corridors where connectivity remains intermittent.
- Semiconductor Supply Concentration:Secure element chips for hardware-backed verification concentrate among a limited set of foundries, exposing update authentication pipelines to single-source vulnerability.
- ISO/SAE 21434 Certification Burden:The 12-18 month qualification timeline for cybersecurity engineering processes delays supplier market entry and concentrates contract awards among pre-certified incumbents.
Strategic Opportunities
- India Connected Vehicle Deployment:Domestic OEMs and joint ventures are building software-defined vehicle platforms from inception, creating greenfield OTA architecture contracts without legacy integration constraints.
- AI-Infused Feature Activation:The EU AI Act creates a regulated pathway for monetizing automated driving function upgrades through subscription-based OTA delivery, subject to conformity assessment protocols.
- Edge-Cloud Hybrid Architectures:Convergence of vehicle-side container orchestration with centralized fleet management enables tiered update strategies that balance latency, bandwidth, and data sovereignty requirements.
Industry Challenges
- Cybersecurity Engineering Talent Scarcity:Shortage of professionals holding ISO/SAE 21434 auditor credentials extends supplier onboarding timelines and inflates compensation costs for qualified personnel.
- Legacy ECU Integration Complexity:Pre-2020 vehicle architectures lack hardware security modules and sufficient processing headroom, forcing expensive gateway retrofits or exclusion from full-featured OTA programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Over-The-Air (OTA) Updates Market |
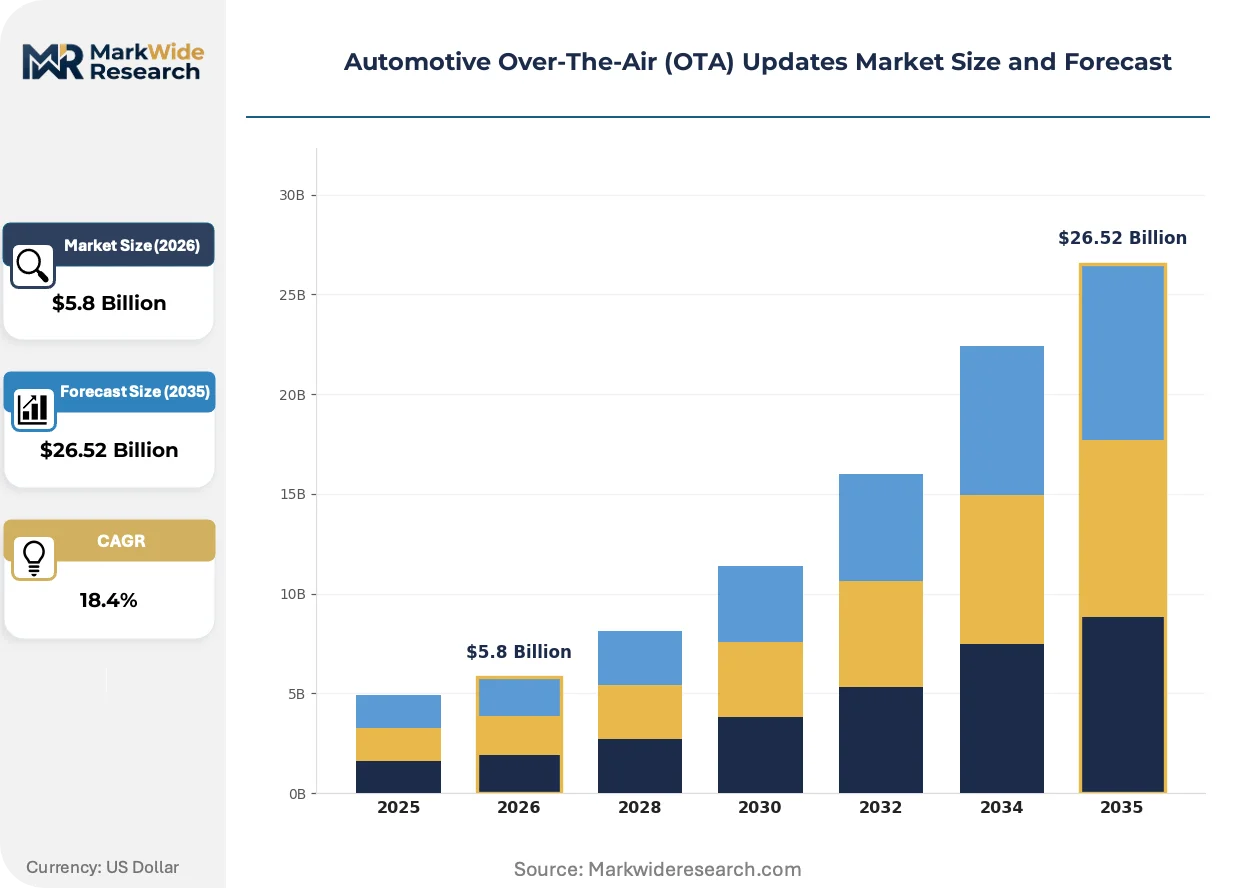
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Providers Technology: Wi-Fi, Cellular, Bluetooth, Satellite Application: Infotainment Systems, Navigation, Safety Features, Performance Enhancements |
| Companies Covered | Tesla, Robert Bosch GmbH, Continental AG, HARMAN International, Aptiv PLC, NXP Semiconductors, Qualcomm Technologies, Denso Corporation, Airbiquity Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Over-The-Air (OTA) Updates Market Emerging Trajectories
Software-defined vehicle platforms are dissolving the boundary between hardware and software release cycles, enabling continuous feature deployment that treats automobiles as perpetually upgradeable compute endpoints rather than static mechanical products.
Containerized software architectures are miniaturizing update payloads through modular packaging that isolates functional domains. Tier-1 suppliers in Germany are deploying micro-OTA protocols that target individual domain controllers rather than full firmware reflashes. This granularity is compressing installation windows and reducing rollback complexity when verification fails.
The EU AI Act is imposing conformity assessment requirements on machine-learning components delivered via OTA channels. Automotive OEMs serving European markets must document training data provenance and algorithmic transparency before deploying automated driving updates. Premium manufacturers are responding by segregating AI inference pipelines into certifiable modules with isolated update tracks.
Fleet procurement departments are consolidating vendor relationships around full-stack OTA providers capable of spanning edge device management through cloud orchestration. Third-party telematics platforms are displacing point-solution suppliers in United States commercial vehicle markets. This concentration is most visible among long-haul trucking operators managing thousand-plus vehicle deployments across North American freight corridors.
Automotive Over-The-Air (OTA) Updates Market Segmentation
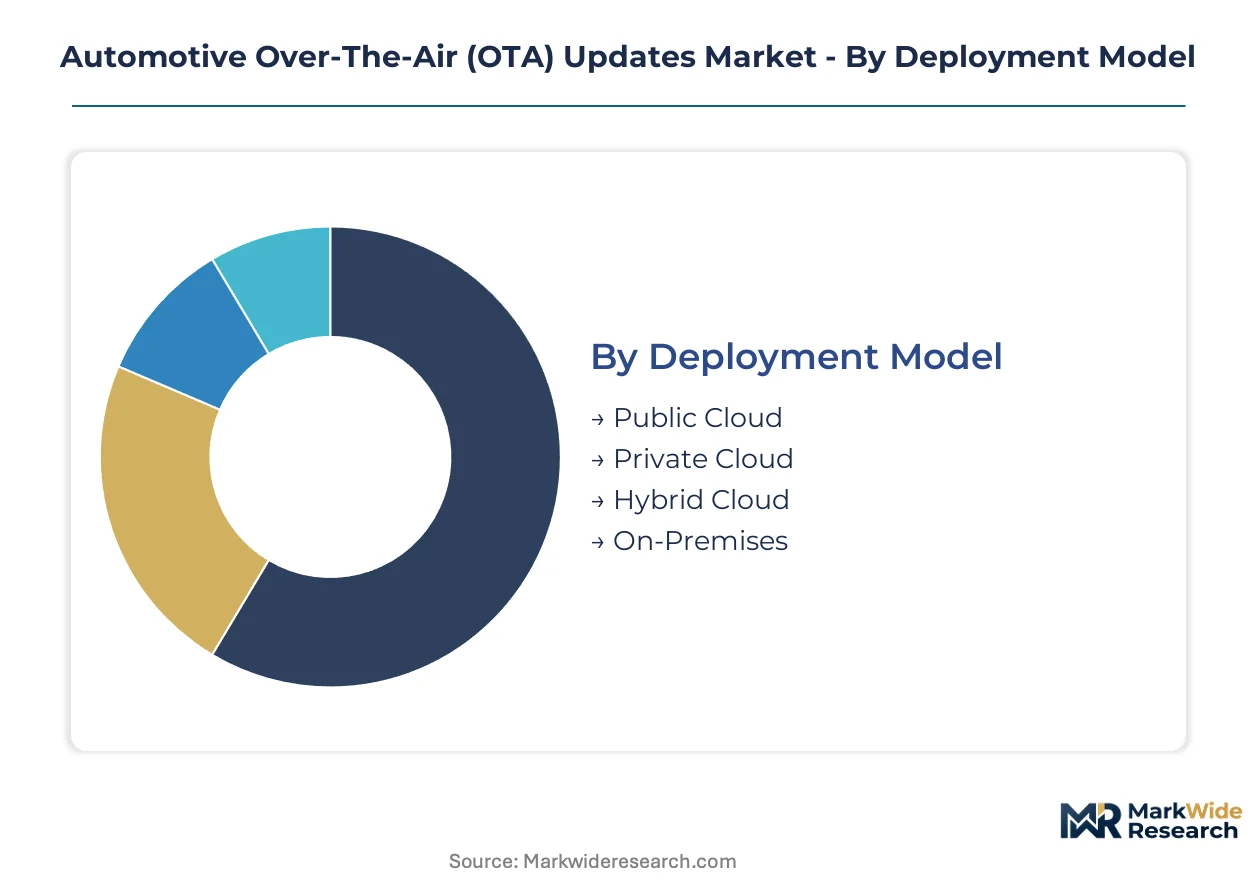
OTA update architectures fragment across four distinct dimensions, each carrying divergent margin profiles and technical certification burdens. Deployment models determine infrastructure ownership economics, while end-user categories separate captive OEM programs from third-party fleet management opportunities.
Deployment Model:
Margin pools concentrate in hybrid configurations that blend public cloud scalability with private infrastructure sovereignty for premium manufacturers.
- Public Cloud:Mass-market OEMs deploy multi-tenant architectures on hyperscaler infrastructure to achieve per-vehicle update costs below private alternatives. German and Chinese volume manufacturers dominate procurement, driven by fleet-scale efficiency targets and reduced capital expenditure requirements.
- Private Cloud:Premium European manufacturers maintain dedicated server farms within regional data centers to satisfy GDPR data residency mandates and ISO/SAE 21434 audit trails. BMW and Mercedes-Benz anchor demand through sovereign update pipelines that isolate firmware repositories from third-party infrastructure.
- Hybrid Cloud:Tiered architectures partition non-critical infotainment updates to public endpoints while reserving safety-critical firmware to private enclaves. United States luxury OEMs favor this model for its compliance flexibility across state-level data privacy variations.
- On-Premises:Air-gapped installations serve defense and specialized commercial vehicle segments with zero external connectivity requirements.
Private cloud holds installed capacity. Hybrid cloud is rotating up the share rankings.
End User:
Procurement authority is shifting from engineering departments to fleet operations centers as commercial vehicle operators consolidate heterogeneous vehicle populations under single management platforms.
- OEMs:Volkswagen, Toyota, and Stellantis operate captive OTA programs spanning 50-plus electronic control units per vehicle architecture. These manufacturers internalize update orchestration to preserve brand-controlled feature monetization and direct customer relationships.
- Fleet Operators:Long-haul trucking conglomerates across United States interstate corridors and German autobahn networks deploy centralized OTA management to synchronize maintenance windows across thousand-plus vehicle deployments. Daimler Truck and Volvo Group anchor this segment through proprietary fleet telematics integration.
- Tier-1 Suppliers:Bosch and Continental supply white-label update infrastructure to mid-size OEMs lacking in-house cybersecurity engineering depth.
- Aftermarket Providers:Third-party telematics platforms retrofit connectivity modules to pre-2020 vehicle populations excluded from factory OTA programs.
OEMs dominate current contract value. Fleet operators are climbing the fastest.
Technology:
Cellular infrastructure investments by telecommunications operators in Germany, China, and the United States are compressing delivery latency and expanding addressable fleet coverage.
- Cellular:4G and 5G networks transmit differential update packages to vehicles in motion, enabling seamless firmware installation without driver intervention. Coverage gaps persist in rural China and remote United States interstate corridors where tower density remains insufficient.
- Wi-Fi:Residential and workplace networks handle large payload downloads during vehicle downtime, reducing cellular data costs for infotainment and navigation map updates.
- Bluetooth:Short-range protocols facilitate smartphone-tethered updates for entry-level vehicles lacking embedded cellular modems.
- Satellite:Geostationary and low-earth-orbit constellations extend coverage to mining, forestry, and maritime applications beyond cellular reach.
Cellular commands the majority of active connections. Satellite is gaining share fastest in specialized commercial segments.
Application:
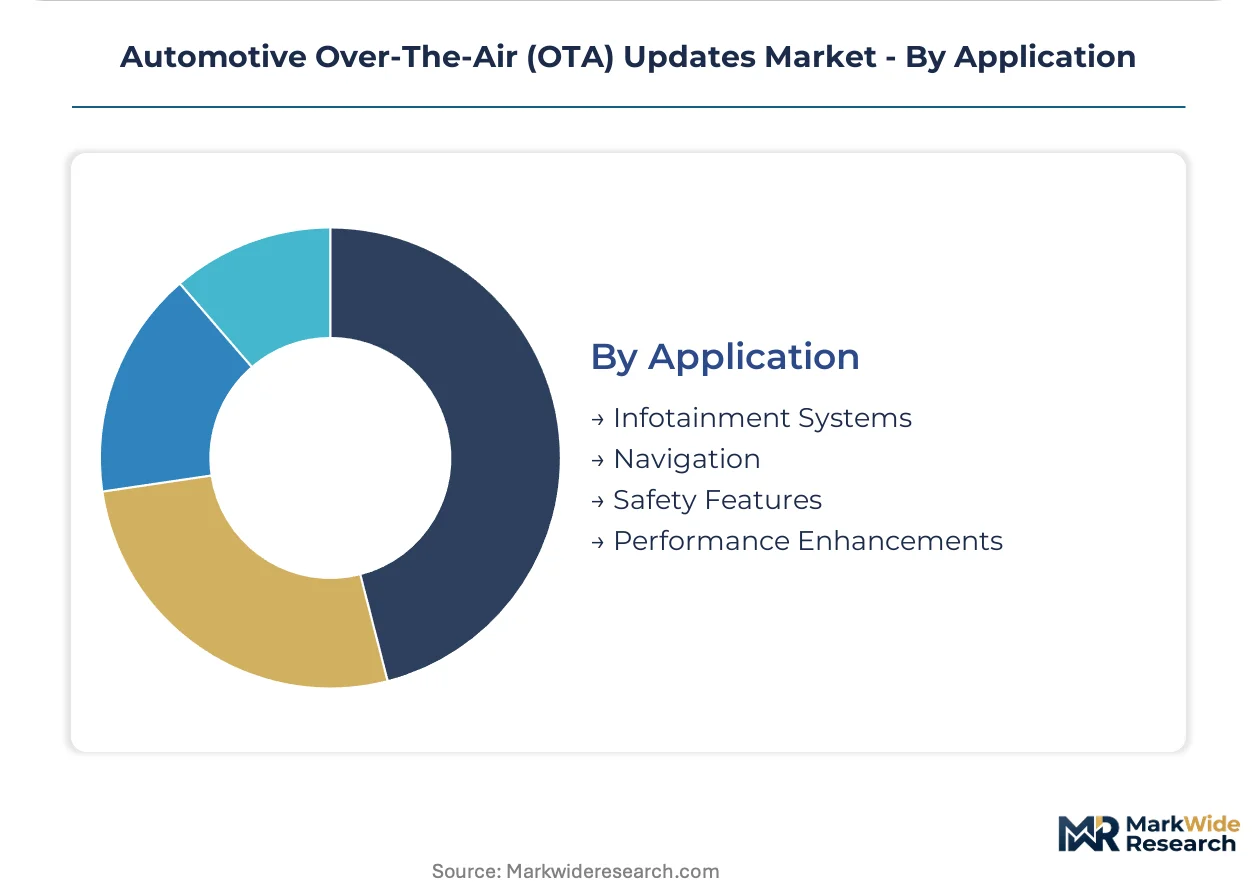
Regulatory pressure from UN R155 and the EU AI Act is elevating safety feature updates to the highest certification tier, separating them from discretionary infotainment deployments.
- Safety Features:Automated emergency braking, lane-keeping assistance, and adaptive cruise control updates require ISO/SAE 21434-certified delivery pipelines with hardware-backed verification. European OEMs face mandatory compliance timelines under UN R155 implementation schedules.
- Infotainment Systems:Over-the-air user interface refreshes and application store expansions generate subscription revenue through premium connectivity packages. Tesla and Mercedes-Benz monetize these updates through recurring billing models.
- Navigation:High-definition map layer updates support automated driving function expansion into new geographic regions.
- Performance Enhancements:Battery management software and powertrain calibration updates unlock range or acceleration improvements through paid activation codes.
Safety features carry the steepest certification overhead. Performance enhancements are rotating up the share rankings as subscription monetization models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UN R155 vehicle cybersecurity regulations are compelling European OEMs to re-architect software delivery pipelines, while China's GB/T standards and United States NHTSA guidance create parallel compliance frameworks that shape procurement across three dominant automotive manufacturing clusters.
United States
Long-haul trucking operators across interstate freight corridors are consolidating thousand-plus vehicle fleets under centralized OTA management platforms. NHTSA cybersecurity guidance mandates systematic risk management for software updates, elevating certification requirements for suppliers serving Detroit-based OEMs. Silicon Valley technology clusters anchor development of edge-cloud hybrid architectures for premium manufacturers seeking data sovereignty compliance.
Germany
Passenger vehicle OEMs in Stuttgart and Munich are expanding OTA adoption to reduce warranty recall costs and satisfy KBA enforcement of UN R155 cybersecurity management systems. ISO/SAE 21434 certification timelines compress supplier qualification windows, concentrating contract awards among pre-certified Tier-1 incumbents. Bavaria-based engineering centers dominate differential compression algorithm development for cellular-efficient delta updates.
China
Domestic OEMs and joint ventures in Shanghai and Guangzhou are building software-defined vehicle platforms from inception, creating greenfield OTA architecture contracts without legacy integration constraints. MIIT GB/T vehicle cybersecurity standards mandate systematic risk management comparable to European frameworks. Yangtze River Delta manufacturing clusters anchor the fastest-scaling connected vehicle fleet deployments globally.
Japan
Automotive electronics suppliers in Nagoya and Tokyo are integrating hardware security modules into next-generation domain controllers to satisfy METI guidance on connected vehicle cybersecurity. Domestic OEMs prioritize differential update protocols that minimize cellular data consumption across archipelago geography with uneven 5G tower density. Kansai-based semiconductor foundries concentrate production of secure element chips for firmware verification pipelines.
India
Domestic OEMs and joint ventures in Pune and Chennai are constructing software-defined vehicle platforms from clean-sheet designs, bypassing legacy ECU retrofit complexity that constrains Western markets. Ministry of Road Transport and Highways notifications on vehicle connectivity standards are accelerating compliance-driven investment in secure update architectures. Tamil Nadu automotive corridors attract Tier-1 supplier engineering centers targeting export qualification for European and Middle Eastern OEM programs.
Automotive Over-The-Air (OTA) Updates Market Vendor Landscape
Player mix skews toward integrated Tier-1 suppliers with captive cybersecurity engineering depth, creating a tiered structure where certification-holding incumbents capture premium contract value. The competitive landscape separates into three strategic archetypes: full-stack platform providers, chipset-level security enablers, and specialized OTA orchestration vendors. Market consolidation proceeds through strategic partnerships between cloud infrastructure providers and automotive electronics specialists, alongside vertical integration moves by OEMs seeking end-to-end control over update pipelines.
Within the integrated Tier-1 tier, Robert Bosch GmbH and Continental AG exemplify suppliers leveraging European engineering depth to anchor multi-OEM OTA programs. Tesla occupies a distinct position through end-to-end control of proprietary update stacks from cloud infrastructure to vehicle execution. Qualcomm Technologies represents the chipset-level security enabler archetype, streamlining certification pathways for downstream software vendors through hardware-backed verification architectures.
| Leading Market Players |
|---|
| Tesla |
| Robert Bosch GmbH |
| Continental AG |
| HARMAN International |
| Aptiv PLC |
| NXP Semiconductors |
| Qualcomm Technologies |
| Denso Corporation |
| Airbiquity Inc. |
| Others |
Supply Flow & Price Mechanics
UN R155 cybersecurity certification gates both supplier qualification and price differentiation simultaneously, concentrating contract awards among pre-certified Tier-1 incumbents who command premium positioning while excluding uncertified competitors from safety-critical procurement cycles. German and Chinese OEMs absorb higher upfront engineering costs to secure ISO/SAE 21434-compliant update pipelines, creating a bifurcated market where certification status outweighs unit economics in vendor selection.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate Tier-1 supplier agreements, insulating margins against secure element chip volatility while passing through foundry cost fluctuations to OEM buyers. Pricing stratifies across ISO/SAE 21434 certification tiers, with fully certified platforms commanding substantial premiums over uncertified alternatives. Cost compression in public cloud deployments is intensifying because hyperscaler volume discounts compress per-vehicle delivery economics for mass-market manufacturers. Fleet operators exhibit the highest price sensitivity due to thousand-plus vehicle scale procurement, while premium European OEMs prioritize data sovereignty over unit cost minimization.
Supply Chain Analysis
Just-in-time inventory strategies prevail for cellular modem modules and gateway controllers, though strategic stockpiling of secure element chips from Taiwan and South Korea has intensified following foundry capacity constraints. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with automotive-grade secure enclaves drawing from TSMC and Samsung foundry output. Single-source vulnerability in hardware security module supply exposes update authentication pipelines to geopolitical disruption. Distribution runs through Tier-1 supplier integration into OEM platform engineering, bypassing independent aftermarket channels for factory-installed OTA architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to automotive production normalization following semiconductor shortage disruption, with connected vehicle platform investment accelerating as OEMs rebuild software-defined vehicle roadmaps deferred during supply-constrained periods.
For Market Incumbents: Secure ISO/SAE 21434 auditor credential pipelines to compress supplier onboarding timelines and defend against cybersecurity engineering talent scarcity threatening service level agreements. Deepen backward integration into secure element chip sourcing to reduce Taiwan foundry concentration risk and stabilize hardware-backed verification supply. Anchor platform engineering relationships with German premium OEMs pursuing data sovereignty compliance to lock out public cloud competitors. For New Entrants and Emerging Players: Anchor in India's greenfield software-defined vehicle deployments where domestic OEMs lack legacy ECU retrofit constraints and seek full-stack OTA architecture without incumbent integration burden. Target aftermarket retrofit opportunities for pre-2020 commercial vehicle fleets excluded from factory OTA programs, leveraging Bluetooth-tethered smartphone gateways as low-cost entry vectors. Pursue white-label partnerships with mid-size OEMs lacking captive cybersecurity engineering depth. For Investors and Strategic Acquirers: UN R155 implementation timelines reshape the acquisition landscape by concentrating contract value among pre-certified suppliers with completed 12-18 month qualification cycles. Long-term viability favors full-stack platform providers spanning edge device management through cloud orchestration, positioned for fleet operator procurement consolidation. The signal to watch is Tier-1 supplier M&A activity targeting container orchestration specialists, indicating vertical integration pressure in edge-cloud hybrid architectures.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/SAE 21434 Certification Investment | UN R155 compliance gates European OEM procurement, concentrating awards among pre-qualified suppliers. |
| Secure Element Chip Supply Agreement | Taiwan and South Korea foundry partnerships anchor hardware-backed verification for safety-critical updates. |
| Edge-Cloud Hybrid Architecture Deployment | Tiered update strategies balance latency, bandwidth, and GDPR data sovereignty for premium manufacturers. |
| Fleet Telematics Platform Integration | Centralized OTA management captures thousand-plus vehicle deployments across North American freight corridors. |
| AI Inference Pipeline Segregation | EU AI Act conformity assessment drives isolated update tracks for machine-learning components. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, fleet telematics operations managers, and cybersecurity engineering leads. Secondary validation drew from UN R155 implementation guidance, KBA enforcement documentation, MIIT GB/T standard publications, NHTSA cybersecurity guidance, and vehicle production registration databases. Bottom-up triangulation across deployment model economics and top-down segmentation by end-user category anchored market sizing.
Across the analysis window, forecasts modeled deployment architecture splits, end-user procurement authority shifts, cellular technology adoption curves, and application certification tiers. CAGRs derived from differential compression algorithm penetration rates, fleet telematics expansion trajectories, and regulatory compliance investment cycles. Industry-specific inputs included semiconductor foundry capacity allocation for automotive secure elements and 5G tower density buildout schedules in Germany, China, and the United States.
Material uncertainties — geopolitical disruption in Taiwan semiconductor supply, UN R155 enforcement variance across European member states, and 5G coverage gaps in rural China — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline normalization and cellular infrastructure continuity. Revision becomes warranted when secure element chip supply concentration or regulatory implementation delays cross thresholds that alter supplier qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market