
 Multimodal Transport Market | 2026-2036
Multimodal Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Multimodal Transport Market Outlook
Last-mile delivery margin pools is fragmenting as carriers absorb fulfillment costs previously borne by retailers. J.B. Hunt Transport Services anchors intermodal rail-road integration across North American corridors. FedEx Corporation extends its air-ground network through controlled hub infrastructure. XPO Logistics specializes in less-than-truckload optimization that bridges regional road networks with national rail spines.
Multimodal transport coordinates the sequential or parallel use of rail, road, air, and sea modes under a single contract, typically governed by FIATA multimodal bills of lading and UNCTAD/ICC rules, with cargo-handling specifications dictating container interoperability across mode transitions. Its primary purpose reduces total logistics cost and transit variance for shippers moving goods across continental distances. Road mode still captures the largest volume share in last-mile and feeder segments, while rail is accelerating fastest on transcontinental lanes where fuel cost differentials against trucking have widened. Cloud Solutions within the Technology segment concentrates margin pools through real-time visibility platforms that reduce detention charges and improve asset turns.
The EU Green Deal and IMO carbon intensity regulations are reshaping carrier fleet composition toward lower-emission rail and short-sea options, while the US EPA heavy-duty truck emissions standards tighten the cost calculus for pure road haulage. India's Dedicated Freight Corridor Corporation and China's MIIT dual carbon goals are accelerating rail electrification projects that expand modal alternatives. Stakeholders must decide whether to build captive intermodal terminals or rely on third-party rail access as port congestion and chassis shortages recur.
Market Dynamics
Carbon intensity regulations are compressing modal economics and forcing asset reallocation across corridors where fuel cost differentials now determine routing decisions.
Growth Catalysts
- EU Green Deal modal mandates:Binding emission reduction targets for freight transport are accelerating rail electrification on corridors connecting Rotterdam, Antwerp, and Hamburg to inland terminals.
- E-commerce fulfillment density:Parcel volume concentration in urban clusters is creating economies of scope for micro-fulfillment centers served by electric last-mile fleets integrated with rail trunk lines.
- Cloud-based visibility platforms:Real-time container tracking across mode transitions is reducing detention charges and improving asset utilization rates for intermodal operators.
Market Restraints
- Chassis pool fragmentation:North American chassis supply remains concentrated among equipment lessors, creating bottleneck risk at peak season port calls.
- Rail terminal access scarcity:Captive terminal infrastructure in Germany and Poland limits third-party carrier entry on China-Europe corridor segments.
- IMO carbon intensity technical limitations:Current vessel engine retrofits cannot achieve CII compliance thresholds without speed reductions that extend transit times.
Strategic Opportunities
- Vietnam-ASEAN port-hinterland networks:Underdeveloped rail connectivity between Cai Mep port and Ho Chi Minh City industrial zones offers greenfield terminal development potential.
- Battery-electric truck-rail convergence:Charging infrastructure co-location at intermodal terminals enables seamless zero-emission handoffs between road and rail modes.
- India Dedicated Freight Corridor expansion:DFCCIL's eastern corridor commissioning creates new scheduled container services between Delhi-Mumbai industrial belts.
Industry Challenges
- Intermodal equipment standardization delays:Incompatible container corner castings and lifting specifications persist between Asian and European rail networks.
- Legacy TMS integration complexity:Shipper ERP systems require costly middleware development to ingest multimodal event data from disparate carrier platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multimodal Transport Market |
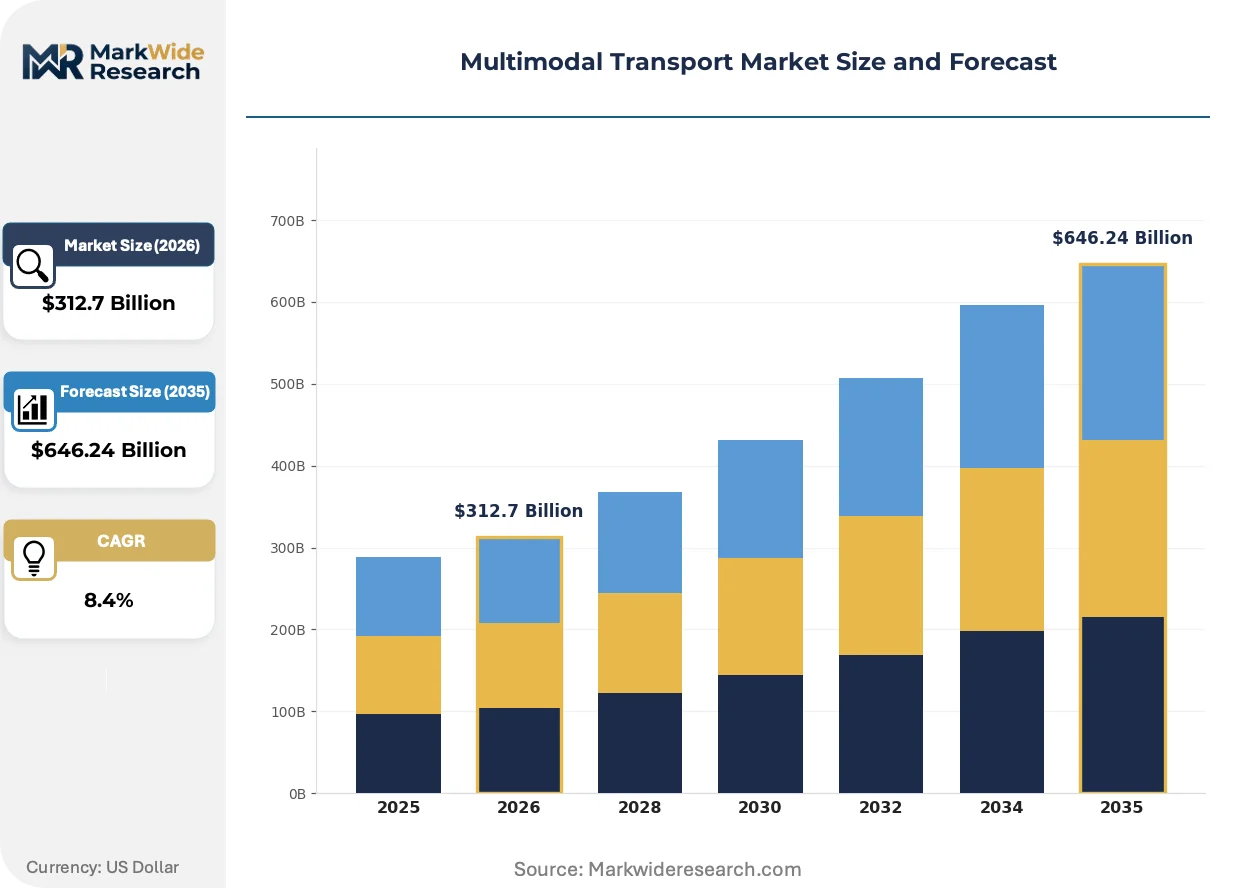
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Rail, Road, Air, Sea Service Type: Logistics, Freight Forwarding, Warehousing, Last-Mile Delivery End User: Manufacturers, Retailers, E-commerce, Government Technology: Tracking Systems, Fleet Management, Cloud Solutions, Automation |
| Companies Covered | Knight-Swift Transportation, TFI International, FedEx Corporation, XPO Logistics, Ryder System Inc., UPS Inc., Schneider National, Old Dominion Freight Line, J.B. Hunt Transport Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multimodal Transport Market Strategic Shifts
Digital freight platforms are compressing procurement cycles while autonomous yard equipment and alternative fuel propulsion systems reconfigure terminal operating models.
Blockchain-enabled smart bills of lading are hybridizing document processing across the China-Europe rail corridor. Deutsche Bahn Cargo and Kazakhstan Temir Zholy are piloting paperless handoffs that reduce customs clearance delays. This convergence of distributed ledger technology with existing FIATA documentation standards is hybridizing liability transfer mechanisms and compressing dispute resolution timelines.
The EU F-Gas Regulation phase-down is accelerating refrigerant conversion in reefer containers moving through Rotterdam and Hamburg. Carrier fleets must retrofit equipment or face operating restrictions in regulated port zones. Cold chain operators on the Mediterranean-Scandinavian short-sea route are responding by consolidating temperature-controlled volumes onto electrified rail spines.
Shippers are unbundling long-term volume commitments from rate contracts and adopting spot-market aggregation platforms for non-core lanes. This procurement fragmentation is displacing traditional annual tender processes in the automotive parts vertical. German and Czech manufacturers now source China-Europe capacity through algorithmic matching rather than direct carrier negotiation.
Multimodal Transport Market Segmentation
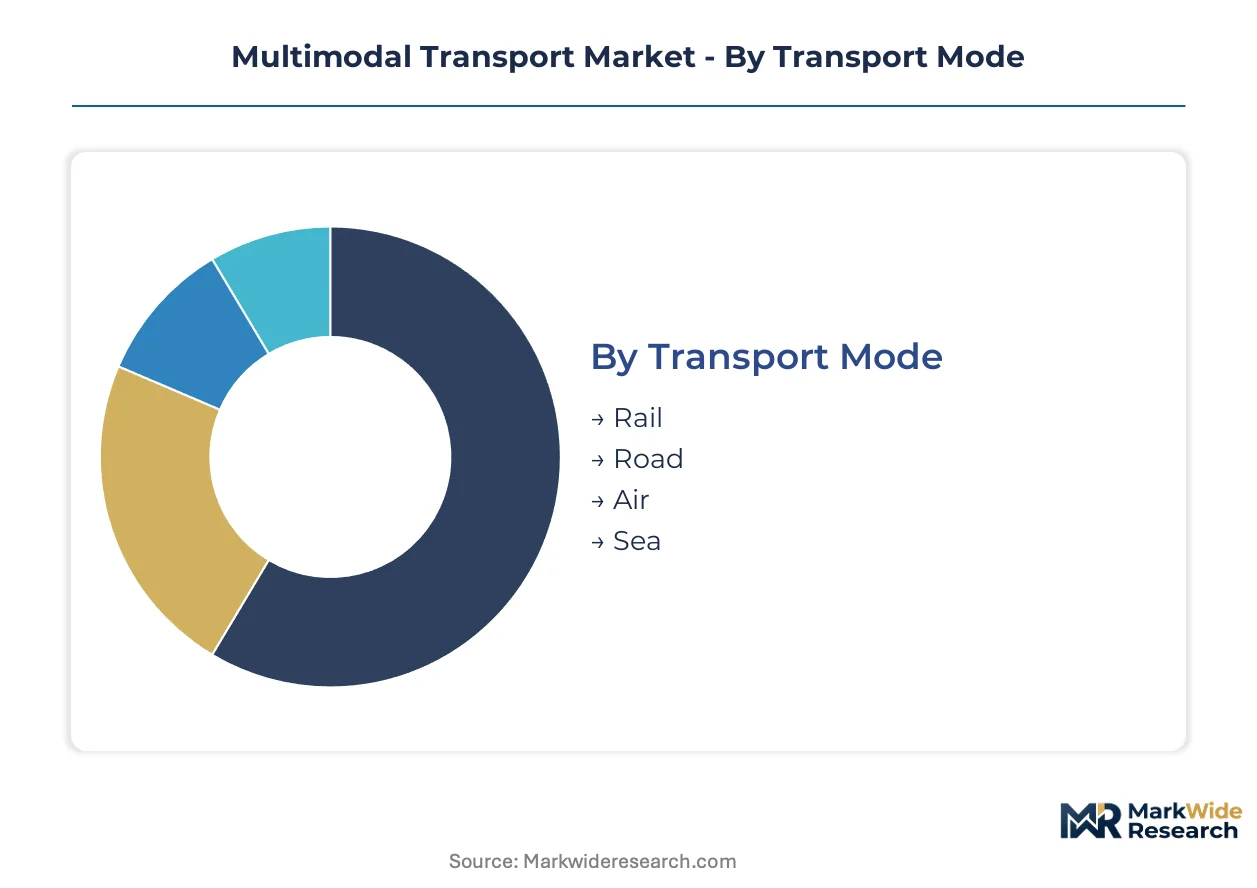
Segmentation in multimodal transport reveals how modal economics and service bundling create distinct margin pools across corridors. Transport mode selection and technology integration determine competitive positioning for operators managing China-Europe rail lanes and Southeast Asian port-hinterland networks.
Transport Mode:
Maturity varies sharply across this spectrum, with road and sea representing established infrastructure while rail electrification projects signal emerging transformation.
- Rail:Electrified trunk corridors dominate transcontinental freight economics, with the China-Europe route absorbing manufacturing relocation from coastal China. The EU Green Deal mandates are accelerating modal shift from road haulage on Rotterdam-Milan and Hamburg-Warsaw lanes.
- Road:Diesel and battery-electric fleets retain indispensable flexibility for first-mile collection and last-mile distribution, though EPA heavy-duty emissions standards and European CO2 regulations compress operating margins on long-haul segments.
- Air:Express cargo networks concentrate on high-value electronics and pharmaceutical cold chain, with hub-and-spoke infrastructure at Memphis and Louisville anchoring intercontinental express services.
- Sea:Containerized deep-sea shipping and short-sea feeder services handle bulk volume across ocean corridors, though IMO carbon intensity regulations force speed reductions that extend transit times on Asia-Europe lanes.
Road retains volume leadership across feeder segments; rail holds the steepest expansion curve on electrified transcontinental corridors.
Service Type:
Cost tier differentiation separates asset-heavy infrastructure plays from asset-light orchestration services, with margin concentration shifting toward technology-enabled coordination layers.
- Logistics:Integrated operators control container terminals, chassis pools, and warehouse networks to guarantee modal handoff reliability, with detention charge reduction becoming a core value proposition.
- Freight Forwarding:FIATA multimodal bill of lading issuance and carrier rate negotiation remain the traditional forwarder function, though digital platforms now disintermediate spot-market procurement on non-core lanes.
- Warehousing:Strategic positioning at inland terminals and port zones enables cross-docking efficiency, with micro-fulfillment centers in urban clusters serving e-commerce density requirements.
- Last-Mile Delivery:Electric van fleets and cargo bike networks address urban congestion charges and zero-emission zones, absorbing fulfillment costs previously borne by retailers.
Freight forwarding retains volume leadership; cloud-enabled logistics holds the steepest expansion curve.
End User:
Application concentration varies by supply chain complexity, with automotive and electronics manufacturers driving scheduled intermodal services while e-commerce demands fragment network design.
- Manufacturers:Automotive and electronics producers require precise scheduling for just-in-sequence delivery, making them anchor customers for dedicated China-Europe rail block trains.
- Retailers:Department store and grocery chains source full-container-load capacity through annual tenders, though inventory-to-shelf velocity requirements are shortening contract durations.
- E-commerce:Parcel volume concentration in urban clusters creates economies of scope for micro-fulfillment integration with electric last-mile fleets and rail trunk lines.
- Government:Defense logistics and disaster relief procurement prioritize resilience over cost, sustaining dedicated capacity reserves on strategic corridors.
Manufacturers retain volume leadership; e-commerce holds the steepest expansion curve.
Technology:
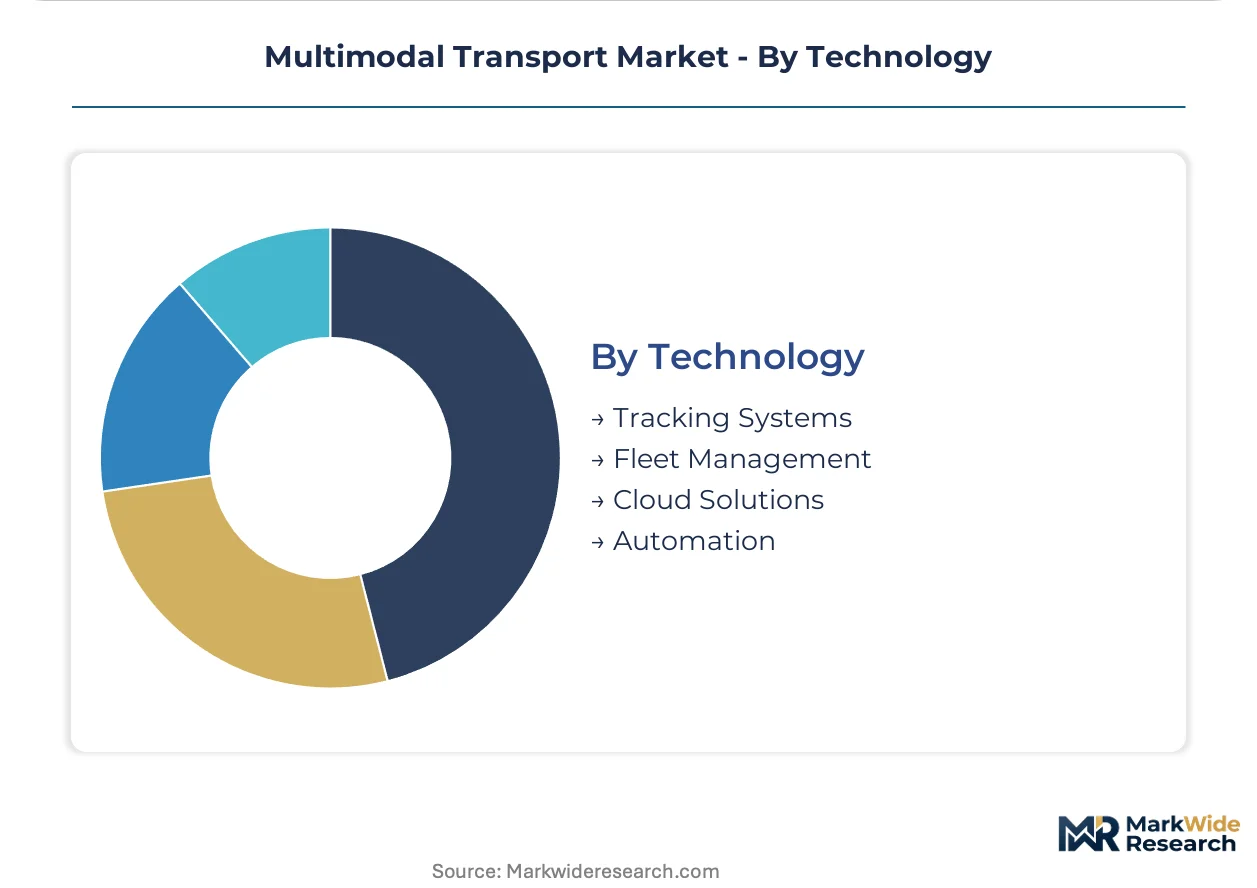
Margin concentration flows toward visibility platforms that reduce detention charges and improve asset turns, while automation addresses labor scarcity at terminal interfaces.
- Tracking Systems:GPS and RFID container monitoring enables real-time location verification across mode transitions, with blockchain pilots on the China-Europe corridor reducing customs documentation delays.
- Fleet Management:Telematics optimization of fuel consumption and route planning addresses carbon intensity compliance, with predictive maintenance reducing unplanned downtime on rail locomotives.
- Cloud Solutions:Real-time visibility platforms aggregate carrier event data to reduce detention charges and improve asset utilization, concentrating margin pools through software subscription models.
- Automation:Autonomous yard equipment and automated gate systems address labor availability constraints at intermodal terminals, with pilot deployments at Rotterdam and Hamburg port zones.
Tracking systems retain volume leadership; cloud solutions hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail electrification dominates corridor economics in Germany while Vietnam pursues greenfield terminal development; the United States concentrates on chassis pool optimization and India accelerates scheduled container services on its eastern freight corridor.
Germany
Rotterdam-Milan and Hamburg-Warsaw lanes absorb modal shift from road haulage under EU Green Deal mandates. Deutsche Bahn Cargo pilots blockchain-enabled documentation with Kazakhstan Temir Zholy. The Rhine-Ruhr industrial cluster anchors electrified intermodal terminals serving automotive and electronics manufacturers.
United States
EPA heavy-duty emissions standards compress pure road haulage margins while intermodal rail-road integration expands. Chassis supply concentration among equipment lessors creates bottleneck risk at peak season port calls. The Chicago rail hub concentrates transcontinental container handoffs between western and eastern Class I networks.
Vietnam
Manufacturing relocation from coastal China drives port-hinterland volume growth through Cai Mep terminal. Underdeveloped rail connectivity to Ho Chi Minh City industrial zones offers greenfield development potential. The southeastern provinces cluster electronics assembly operations demanding integrated multimodal feedering.
India
DFCCIL's eastern corridor commissioning creates scheduled container services between Delhi-Mumbai industrial belts. The Dedicated Freight Corridor Corporation accelerates rail electrification under MIIT-aligned dual carbon goals. Gujarat's Mundra port hinterland concentrates chemical and textile exporters adopting block train services.
China
The China-Europe rail corridor absorbs manufacturing relocation from coastal provinces. MIIT dual carbon goals accelerate locomotive electrification projects expanding modal alternatives. Zhengzhou and Xi'an inland terminals anchor block train consolidation for automotive and electronics exports.
Multimodal Transport Market Competitive Environment
Capability concentration sits with integrated operators controlling terminal infrastructure and chassis pools; scale advantage sits with national LTL networks and parcel carriers with captive air hubs. The vendor base separates into three archetypes: asset-heavy railroads and steamship lines, asset-light forwarders with digital procurement platforms, and hybrid integrators spanning multiple modes. Dominant competitive moves include strategic partnerships for terminal access and technology licensing for visibility platform deployment.
Among North American transport operators, J.B. Hunt Transport Services and Schneider National exemplify the rail-road hybrid archetype, while FedEx Corporation occupies a position as an air-ground integrator with controlled hub infrastructure. Knight-Swift Transportation represents the trucking-scale tier expanding into intermodal brokerage. These three anchors illustrate how capability depth in specific modes combines with network breadth to determine competitive positioning across transcontinental corridors.
| Leading Market Players |
|---|
| Knight-Swift Transportation |
| TFI International |
| FedEx Corporation |
| XPO Logistics |
| Ryder System Inc. |
| UPS Inc. |
| Schneider National |
| Old Dominion Freight Line |
| J.B. Hunt Transport Services |
| Others |
Value Chain & Pricing Dynamics
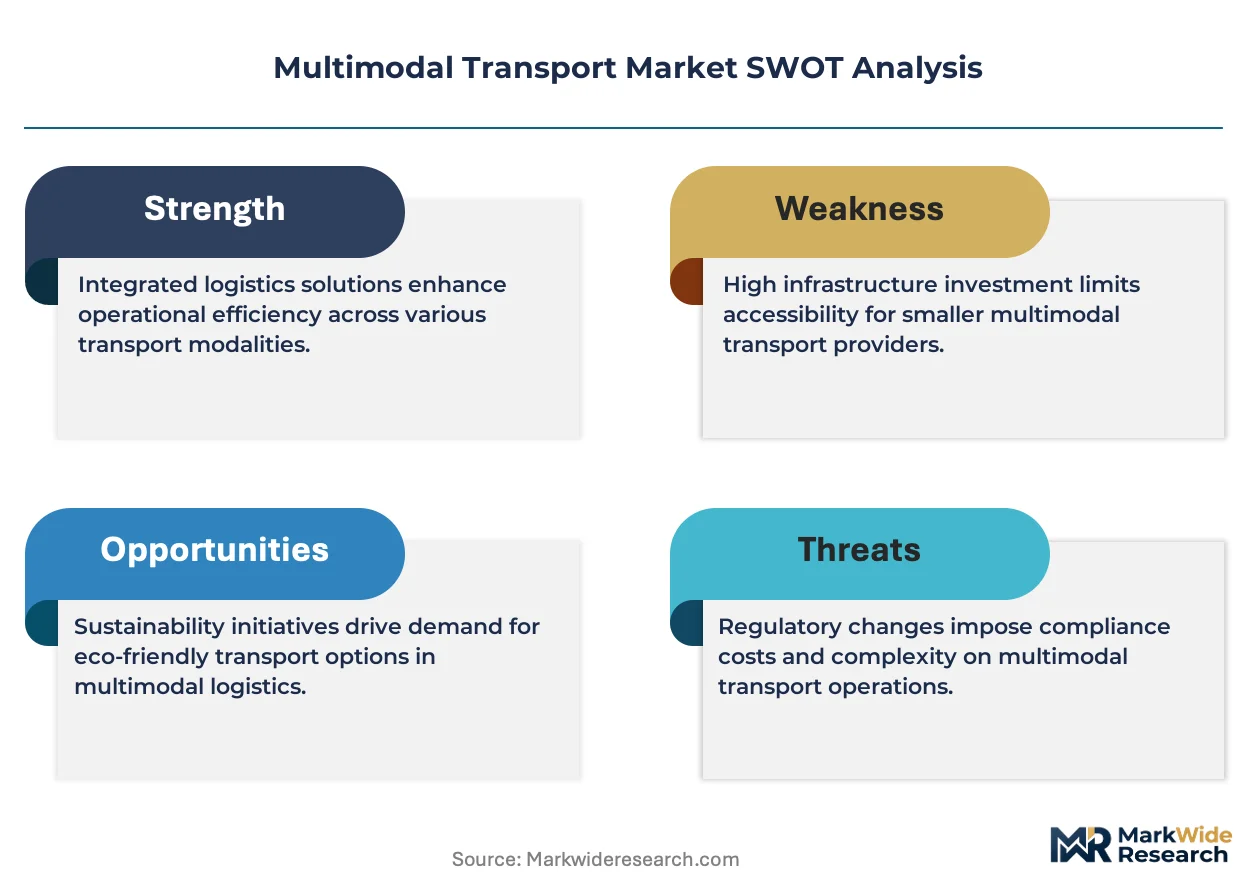
Chassis pool concentration among North American equipment lessors concentrates pricing power at intermodal terminals, pushing margin pools toward carriers with captive container and railcar fleets that can bypass third-party leasing markups.
Pricing Analysis
Long-term offtake contracts dominate China-Europe rail block trains while spot-market platforms fragment procurement on non-core Southeast Asian lanes. Price differentiation hinges on container interoperability certification and volume scale commitments, with automotive manufacturers securing preferential rates through dedicated train services. Cost compression in pure road haulage is intensifying because EPA heavy-duty emissions standards widen fuel cost differentials against electrified rail. E-commerce parcel aggregators exhibit highest price sensitivity; pharmaceutical cold chain operators show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Export-control regimes limiting high-efficiency locomotive technology flows from Germany and Japan constrain rail electrification pace in emerging corridors. Manufacturing concentrates in China, Germany, and the United States for container chassis and intermodal equipment. Critical inputs include high-tensile steel, lithium-ion battery cells for yard tractors, and semiconductor components for telematics systems. Single-source vulnerability sits with European lifting equipment suppliers serving Asia-Europe rail terminals. Distribution runs through port-centric equipment pools and inland terminal chassis depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multimodal transport market is cycling through a recovery phase as e-commerce fulfillment density rebuilds parcel volume concentration in urban clusters following pandemic-era network overexpansion.
For Market Incumbents: Insulate terminal access advantages through captive infrastructure investments at Rotterdam-Milan and Hamburg-Warsaw corridor nodes. Secure long-term railcar supply agreements with Chinese manufacturers before EU carbon border adjustments tighten equipment import costs. Prioritize backward integration into chassis pool ownership to eliminate peak-season lessor bottlenecks at North American port calls. For New Entrants and Emerging Players: Establish a beachhead in Vietnam-ASEAN port-hinterland networks where underdeveloped rail connectivity to Ho Chi Minh City industrial zones offers greenfield terminal development potential. Target battery-electric truck-rail convergence segments with charging infrastructure co-location services at intermodal terminals. Deploy algorithmic freight-matching platforms to disintermediate traditional forwarder rate negotiation on China-Europe spot capacity. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-enabled logistics operators with real-time visibility platform subscriptions that concentrate margin pools through detention charge reduction software. Long-term viability favors hybrid integrators spanning multiple modes with controlled terminal infrastructure rather than asset-light forwarders facing digital disintermediation. Watch for inflection signals in DFCCIL eastern corridor commissioning schedules that would validate scheduled container service expansion across Indian industrial belts.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Infrastructure Expansion | Captive intermodal facilities at Rotterdam and Hamburg port zones guarantee modal handoff reliability under EU Green Deal mandates. |
| Battery-Electric Fleet Conversion | Zero-emission truck deployments at California and New York port complexes align with EPA heavy-duty emissions standards tightening. |
| Blockchain Documentation Pilot | Paperless FIATA bill of lading handoffs between Deutsche Bahn Cargo and Kazakhstan Temir Zholy compress customs clearance delays. |
| Rail Electrification Partnership | Joint locomotive procurement agreements with Chinese manufacturers under MIIT dual carbon goals expand modal alternatives. |
| Cloud Visibility Platform Licensing | Real-time container tracking subscriptions reduce detention charges and improve asset turns for intermodal operators. |
Study Parameters
Initial hypotheses were tested against primary input from intermodal terminal operators, freight forwarder procurement leads, rail network planners, and chassis pool managers and refined through secondary validation against customs trade data, EU transport emission registries, SEC 10-K filings of listed carriers, and DFCCIL project development disclosures. Bottom-up volume modeling across corridor segments triangulated with top-down market sizing from equipment manufacturer shipment records.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by transport mode, service type bundling, end-user vertical, and technology integration tier. CAGRs were derived from corridor-specific volume trajectories and modal shift elasticity assumptions. Forecast inputs incorporated EU Green Deal enforcement timelines, IMO carbon intensity compliance pathways, and e-commerce fulfillment network expansion curves.
Sensitivities concentrate around regulatory enforcement pace of EPA heavy-duty standards and EU carbon border adjustments, chassis pool consolidation outcomes, and rail terminal access licensing decisions. Forecasts reflect documented assumptions on modal shift elasticities and infrastructure commissioning schedules. Material shifts in EU ETS carbon price trajectories or China-Europe rail block train frequency commitments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Transportation Aggregators Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Mexico Customs Brokerage Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market