
 Door Panel Market | 2026-2036
Door Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Door Panel Market Outlook
Buyer concentration among multifamily developers is rebalancing procurement leverage toward volume fabricators. Cendrex leverages its specialty access-panel expertise to sustain premium positioning in commercial infrastructure. Nystrom anchors North American distribution through deep contractor relationships. Activar Construction Products Group competes across multiple building-product categories without overextending its door-panel focus.
Door panels are rigid, planar closures engineered for ingress, egress, privacy, or environmental separation, typically fabricated from wood, steel, aluminum, or composite substrates with specified fire ratings, acoustic damping, or thermal resistance. Their primary purpose is to seal and secure openings in residential, commercial, and transportation structures while meeting structural load and code requirements. Wood material still occupies the largest share of residential replacement demand, though aluminum and composite segments are gaining fastest in coastal and high-humidity zones where moisture resistance commands price premiums. Exterior door applications concentrate margin pools in thermal-break and impact-rated configurations, while interior door demand fragments across price tiers in multifamily new construction.
EPA regulations on formaldehyde emissions from composite wood products shape material selection across US manufacturing, while REACH and CE marking govern chemical content and performance claims in European markets. OSHA workplace safety standards influence industrial door-panel specifications for durability and visibility. Stakeholders must monitor evolving fire-resistance testing protocols and embodied-carbon disclosure requirements as building codes tighten performance benchmarks.
Market Dynamics
Material substitution toward engineered composites is restructuring procurement economics as moisture-resistant substrates command widening price premiums over conventional wood in coastal construction zones.
Growth Catalysts
- REACH chemical compliance:European ECHA enforcement is accelerating certified composite adoption by disqualifying uncertified imports from specification lists.
- Multifamily developer consolidation:Volume fabricators capturing bundled contracts from concentrated buyers are scaling automated production lines for standard interior door configurations.
- Indonesia manufacturing migration:Factory relocation from coastal China is expanding capacity for aluminum thermal-break door systems serving Southeast Asian residential construction.
Market Restraints
- Formaldehyde input volatility:EPA emission caps on composite wood resins are compressing margins for particleboard-dependent fabricators facing reformulation costs.
- Aluminum supply concentration:Smelter capacity limitations in specific geographies are creating lead-time uncertainty for thermal-break exterior door producers.
- Fire-rating technical barriers:Extended testing protocols for multi-hour rated assemblies are elongating new product certification cycles beyond 18 months.
Strategic Opportunities
- Vietnam construction acceleration:Residential building permits in Ho Chi Minh City corridor are outpacing local door-panel supply, creating import substitution openings for certified exporters.
- Embodied-carbon disclosure mandates:California's building performance standards are creating first-mover advantage for manufacturers with verified lifecycle data on composite substrates.
- Direct-to-developer digital platforms:Project-specific specification tools are disintermediating traditional distributor relationships for mid-rise multifamily procurement teams.
Industry Challenges
- Fire-testing facility scarcity:Limited accredited laboratories for large-assembly burn testing are creating certification bottlenecks for innovative core material formulations.
- Legacy ERP integration friction:Custom door fabricators with decades-old production systems face data-migration complexity when adopting automated order-to-cut workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Panel Market |
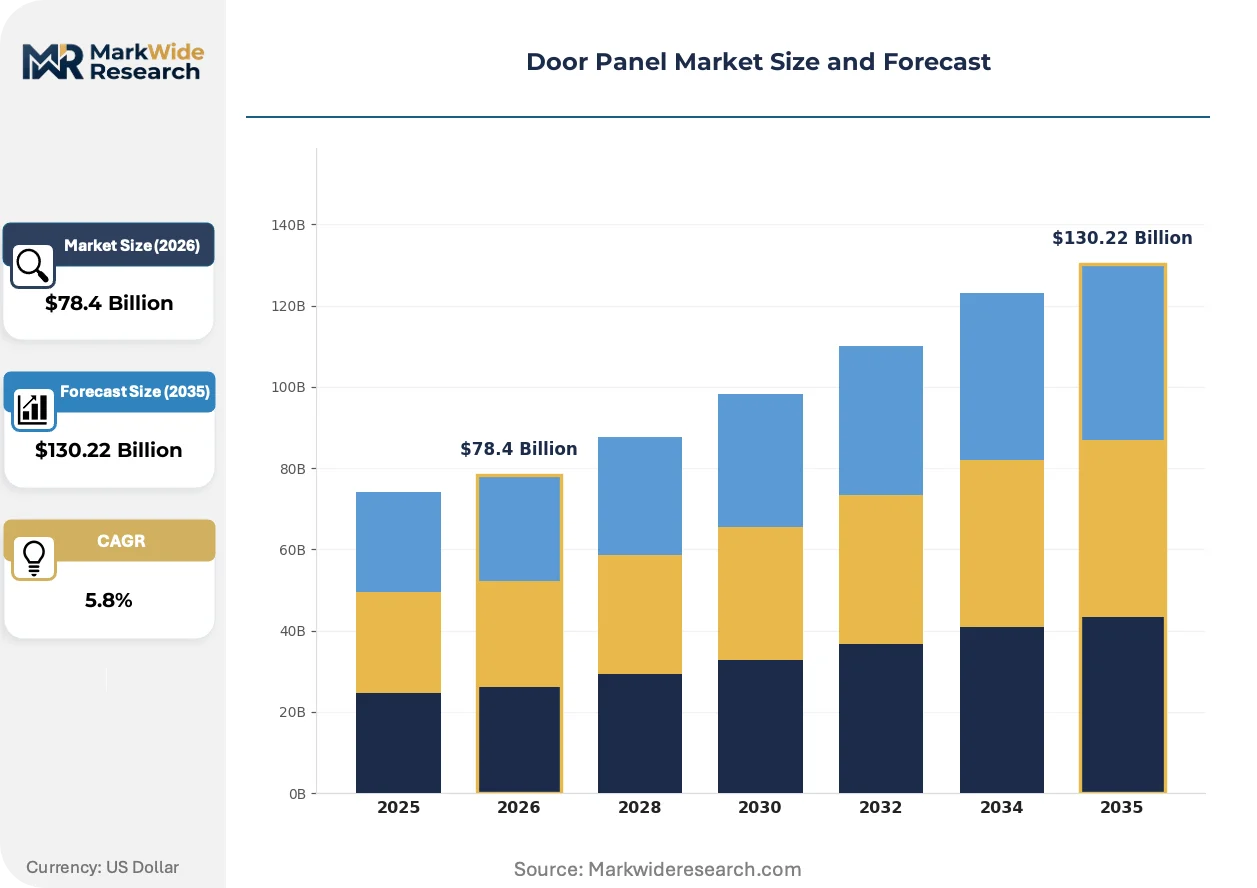
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Door, Exterior Door, Sliding Door, Bi-fold Door Material: Wood, Steel, Aluminum, Composite End User: Residential, Commercial, Automotive, Aerospace Installation Type: Pre-hung, Slab, Pocket, Bi-fold |
| Companies Covered | Cendrex, Nystrom, Activar Construction Products Group, Karp Associates, Williams Brothers Corporation of America, Acudor Products, Babcock-Davis, Access Panel Company, Elmdor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Panel Market Strategic Shifts
Digital specification tools and automated fabrication systems are compressing traditional design-to-delivery timelines while regulatory pressure on material transparency accelerates substitution patterns across substrate categories.
Thermoplastic composite skins bonded to structural foam cores are overtaking conventional fiberglass-reinforced polyester in high-humidity commercial applications. Hotel and healthcare facility maintenance teams are specifying these assemblies for exterior corridor doors based on dent resistance and reduced refinishing cycles. The shift is compressing replacement part inventory requirements for large property management portfolios.
California's updated fire-safety codes for high-rise residential structures are mandating enhanced smoke-seal performance in door-edge configurations. Manufacturers serving the Los Angeles and San Francisco metro corridors are redesigning jamb interfaces to meet the new testing protocols. The regulatory pressure is favoring fabricators with in-house fire-engineering capabilities over those dependent on third-party certification services.
Specification decisions by concentrated multifamily developers are consolidating around performance-based material certifications rather than brand loyalty. Volume buyers in the Phoenix and Atlanta construction markets are unbundling hardware from door slabs to optimize total installed cost through competitive component sourcing. This behavioral shift is compressing traditional package-pricing power held by integrated door system suppliers.
Door Panel Market Segmentation
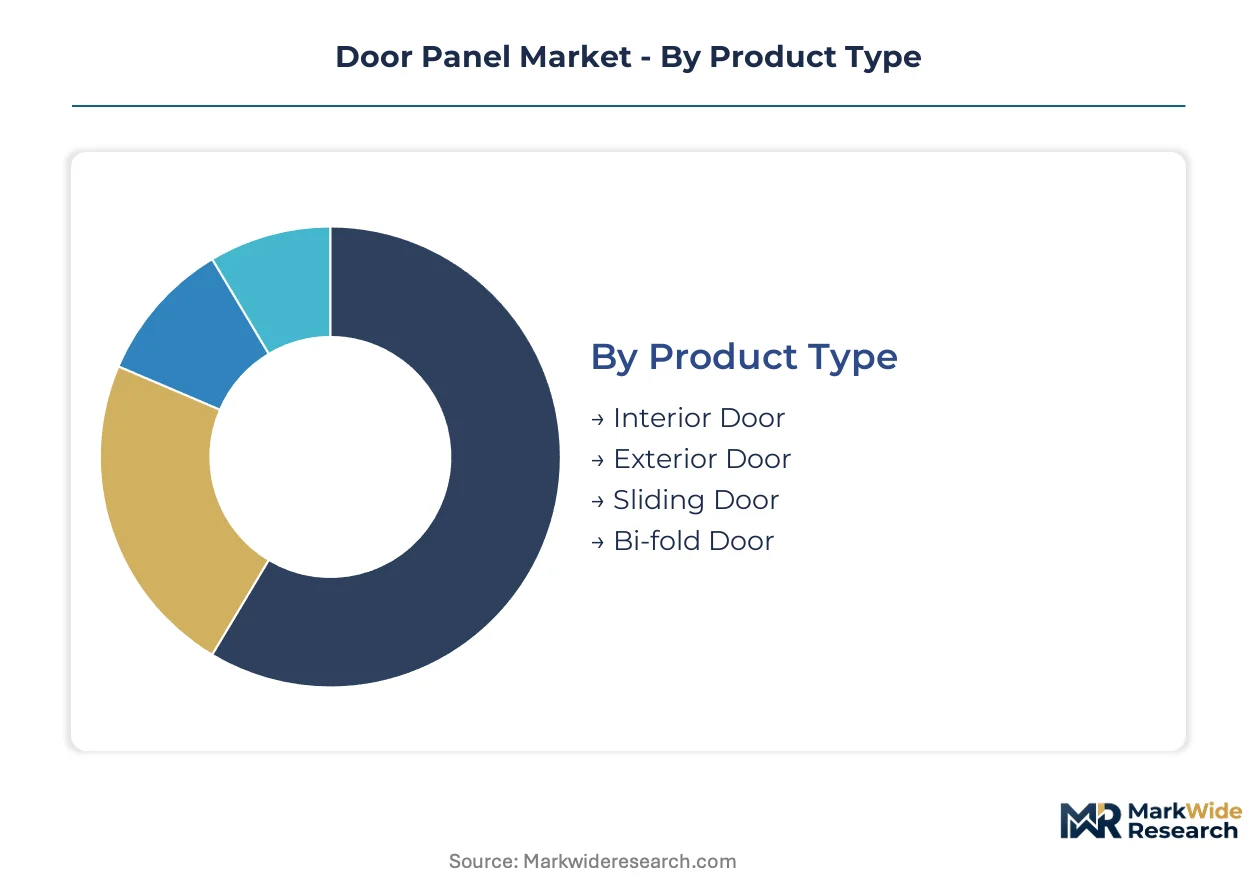
Door panel procurement patterns diverge sharply across application contexts, with replacement cycles in residential stock running 15-20 years against 7-10 year refresh schedules in commercial hospitality and healthcare. Specification teams segment markets by performance tier, material durability, and regulatory compliance burden rather than unit economics alone.
Product Type:
Upgrade cycles vary dramatically by opening configuration, with exterior assemblies demanding earlier replacement due to weather exposure and thermal performance degradation.
- Interior Door:Hollow-core and solid-core configurations dominate multifamily new construction, with specification teams unbundling hardware to optimize total installed cost. Demand concentrates in standard slab dimensions for Phoenix and Atlanta volume developers pursuing component-level procurement strategies.
- Exterior Door:Thermal-break and impact-rated configurations command premium margin pools in coastal zones where moisture resistance and wind-load certification drive selection. Florida and California building codes mandate enhanced performance thresholds that disqualify entry-level products from specification lists.
- Sliding Door:Large-format glass-panel systems serve residential patio and commercial storefront applications with hardware durability as the primary failure mode.
- Bi-fold Door:Folding panel assemblies target high-end residential renovation and hospitality retrofit where spatial flexibility justifies complex track hardware.
Volume placements concentrate in Interior Door; the faster expansion belongs to Exterior Door.
Material:
Cost tier stratification separates specification-grade substrates from commodity alternatives, with certified composites capturing share in humidity-critical applications.
- Wood:Still occupies the largest share of residential replacement demand, though formaldehyde emission caps under EPA regulations are compressing margins for particleboard-dependent fabricators facing reformulation costs. Solid wood and engineered veneer products retain preference in heritage restoration and premium custom residential.
- Steel:Fire-rated commercial assemblies depend on galvanized and stainless substrates for multi-hour certification, with lead times extending due to testing facility scarcity for innovative core formulations.
- Aluminum:Thermal-break exterior systems are gaining fastest in coastal and high-humidity zones where moisture resistance commands price premiums over conventional wood.
- Composite:Thermoplastic skins bonded to structural foam cores are overtaking fiberglass-reinforced polyester in hotel and healthcare exterior corridor applications based on dent resistance.
Wood retains the highest unit placement volumes; composite substrates are climbing the fastest as certified alternatives displace conventional options in regulated markets.
End User:
Customer type determines specification authority structure, with concentrated multifamily developers wielding procurement leverage unavailable to fragmented residential replacement buyers.
- Residential:Multifamily developer consolidation is rebalancing procurement leverage toward volume fabricators capturing bundled contracts for standard interior configurations. Single-family replacement demand fragments across retail channels and custom millwork shops.
- Commercial:Hotel and healthcare facility maintenance teams are specifying thermoplastic composite assemblies for exterior corridor doors based on reduced refinishing cycles and compressed replacement part inventory requirements.
- Automotive:Lightweight panel systems for passenger and commercial vehicles prioritize acoustic damping and crashworthiness certification.
- Aerospace:Honeycomb-core assemblies meet stringent weight and fire-resistance specifications for cabin and cargo compartment applications.
Residential generates the highest absolute unit demand; commercial applications are gaining share fastest as performance-based certification displaces brand loyalty in specification decisions.
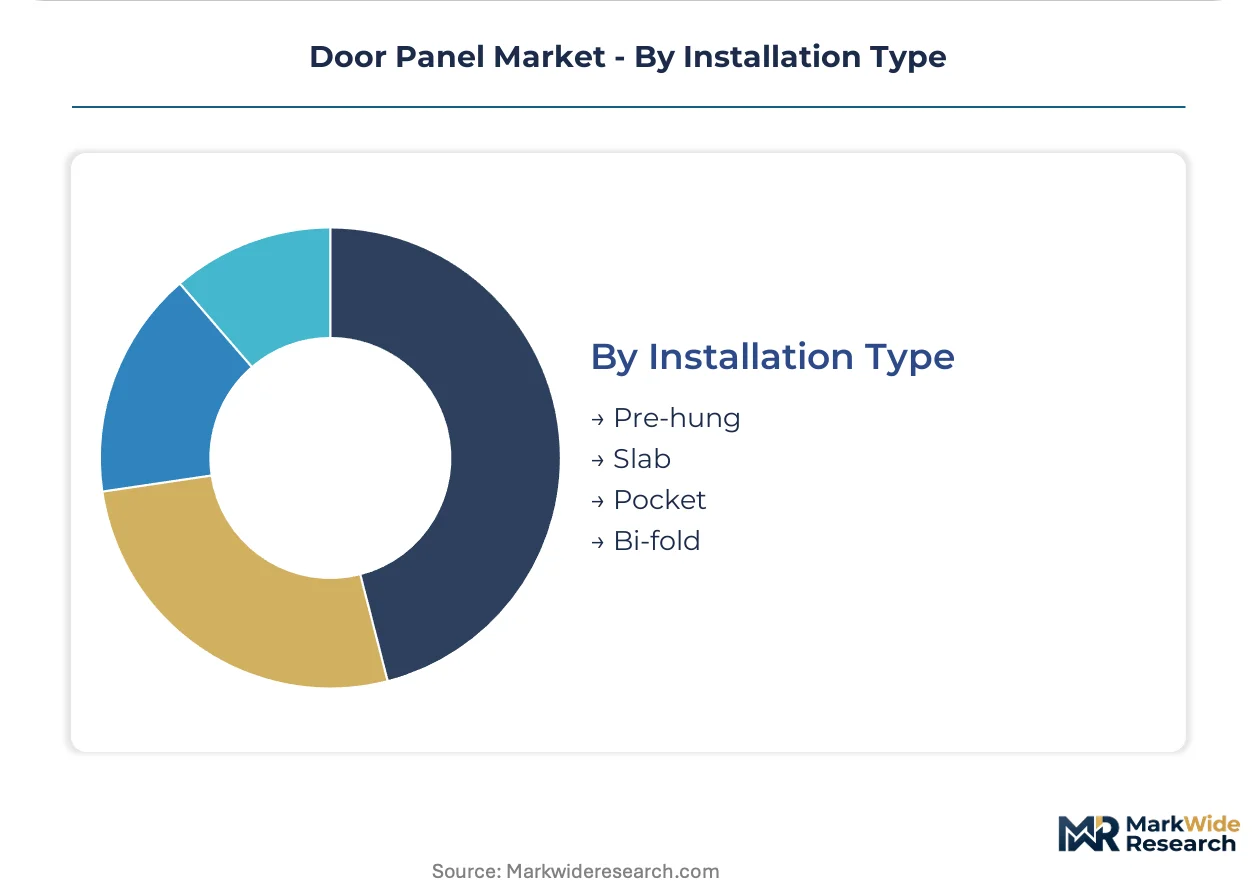
Installation Type:
Supply concentration favors pre-assembled configurations in volume construction while custom fabrication retains position in renovation and specialty commercial.
- Pre-hung:Factory-assembled jamb and hinge systems dominate production homebuilding where field labor scarcity drives preference for ready-to-install units. Automated production lines at volume fabricators compress lead times for standard dimension bundles.
- Slab:Unframed door panels serve renovation contractors and custom millwork shops requiring field-fit flexibility for non-standard openings.
- Pocket:Recessed track hardware configurations target space-constrained residential and hospitality interiors where swing clearance is unavailable.
- Bi-fold:Folding hardware systems serve closet and room-divider applications with specification concentrated in residential renovation and light commercial fit-out.
Pre-hung captures the majority of new construction placements; slab configurations are expanding most quickly in renovation channels where existing frame preservation drives specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multifamily construction clusters in Vietnam and Indonesia are rebalancing procurement patterns across Southeast Asia. Buyers in Ho Chi Minh City and Jakarta corridors concentrate demand for certified composite and aluminum thermal-break systems.
United States
Florida and California coastal zones drive specification for impact-rated and thermal-break exterior configurations. EPA formaldehyde emission caps under the Toxic Substances Control Act compress margins for particleboard-dependent fabricators. Phoenix and Atlanta volume developers unbundle hardware from door slabs to optimize total installed cost.
Germany
Commercial hospitality and healthcare renovation cycles sustain demand for fire-rated steel assemblies. REACH compliance through ECHA enforcement disqualifies uncertified imports from specification lists. Industrial fabricators in North Rhine-Westphalia consolidate automated production lines for standard interior configurations.
China
Manufacturing migration from coastal provinces to inland zones restructures aluminum thermal-break capacity. GB standards for fire resistance and thermal performance govern product certification requirements. Factory relocation to Sichuan-Chongqing and Shandong Peninsula expands output for Southeast Asian export markets.
Vietnam
Residential building permits in the Ho Chi Minh City corridor outpace local door-panel supply. National technical regulations on fire safety and energy efficiency tighten material certification requirements. Manufacturing clusters in Binh Duong and Dong Nai provinces attract component suppliers for aluminum frame systems.
Indonesia
Jakarta and Surabaya metropolitan construction drives demand for moisture-resistant composite substrates. Ministry of Public Works and Housing standards on building safety influence specification authority. Industrial zones in Bekasi and Karawang host expanding fabrication capacity for thermal-break exterior door systems.
Door Panel Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty access-panel and certified fire-rated niches. The vendor base spans integrated building-product conglomerates, regional millwork specialists, and precision metal fabricators. Three archetypes dominate: volume fabricators capturing bundled multifamily contracts, specialty access-panel engineers serving commercial infrastructure, and diversified construction-product groups competing across categories. Consolidation through acquisition of regional distributors and backward integration into aluminum extrusion capacity represent the dominant competitive moves.
Among North American specialists, Cendrex exemplifies the precision-engineered access-panel archetype, while Nystrom occupies a position within the contractor-relationship-driven distribution tier. Activar Construction Products Group represents the diversified construction-product portfolio model, competing across multiple building categories without overextending door-panel focus.
| Leading Market Players |
|---|
| Cendrex |
| Nystrom |
| Activar Construction Products Group |
| Karp Associates |
| Williams Brothers Corporation of America |
| Acudor Products |
| Babcock-Davis |
| Access Panel Company |
| Elmdor |
| Others |
Value Chain & Pricing Dynamics
Multifamily developer unbundling of hardware from door slabs is compressing package-pricing power and forcing fabricators toward component-level cost transparency or volume-scale automation to preserve margin.
Pricing Analysis
Volume placements in standard interior configurations trade margin for throughput while thermal-break exterior systems and certified fire-rated assemblies retain pricing power through technical qualification barriers. Price differentiation hinges on certification grade—UL fire ratings and REACH compliance tiers—and geographic delivery cost to coastal zones with moisture-resistance mandates. Pricing pressure stems from formaldehyde reformulation costs under EPA emission caps squeezing particleboard-dependent fabricators. Single-family replacement buyers show highest price sensitivity; commercial hospitality procurement teams prioritize lifecycle cost over unit price.
Supply Chain Analysis
Dual-sourcing requirements from concentrated multifamily developers are disqualifying single-source fabricators from bundled contract eligibility and elongating supplier qualification timelines. Manufacturing concentrates in Vietnam, Indonesia, and inland China as coastal capacity migrates southeastward. Raw material dependencies center on aluminum billet for thermal-break systems, engineered wood substrates, and fire-resistant core formulations. Single-source vulnerability runs through accredited fire-testing laboratory scarcity, which bottlenecks new product certification. Distribution runs through contractor-relationship-driven distributors and emerging direct-to-developer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Door panel manufacturing is consolidating around volume fabricators with automated production lines, as formaldehyde compliance costs and fire-testing bottlenecks force sub-scale particleboard producers toward exit or acquisition.
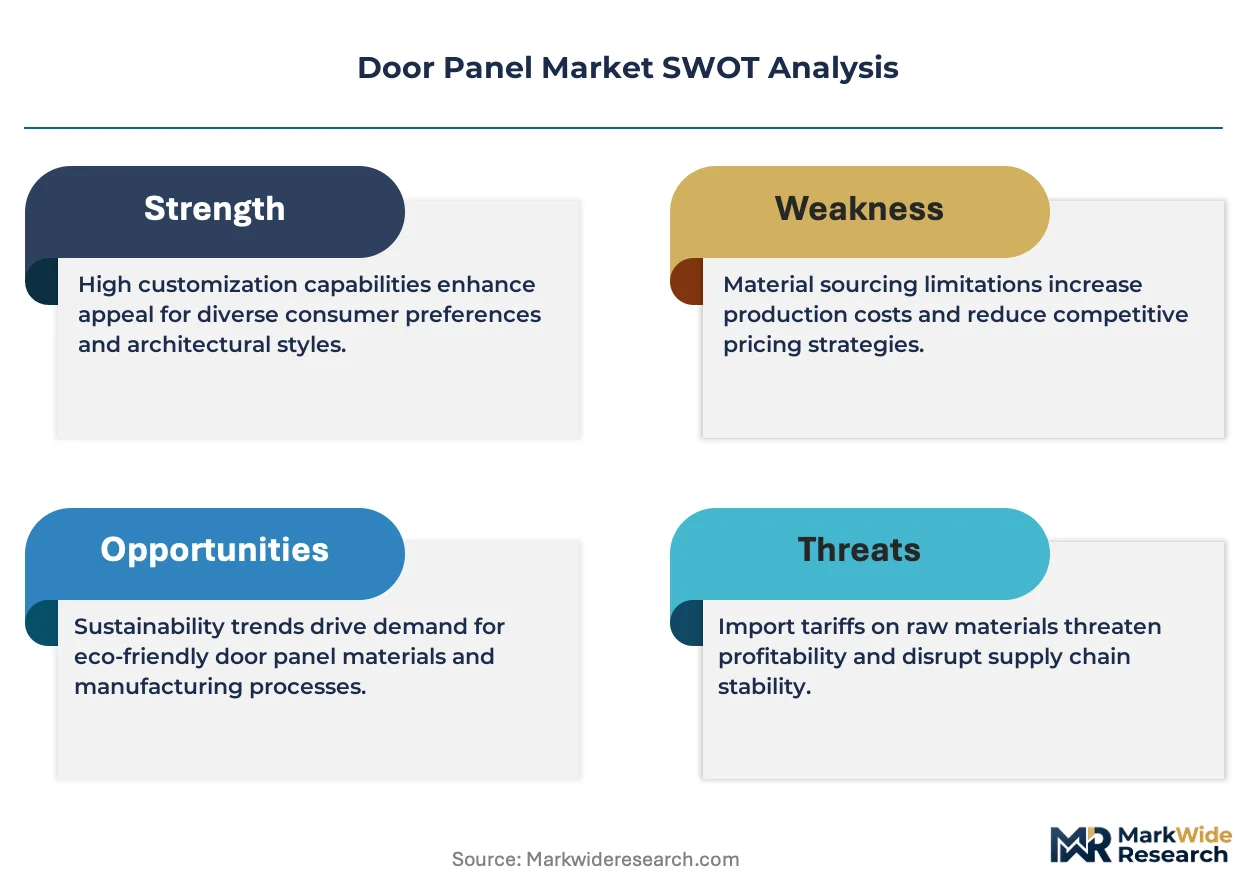
For Market Incumbents: Deploy backward integration into aluminum extrusion capacity to secure thermal-break supply and capture margin pools in coastal exterior applications threatened by smelter concentration. Deepen in-house fire-engineering capabilities to circumvent third-party certification delays and accelerate multi-hour rated assembly launches. Acquire regional distributors in Phoenix and Atlanta corridors to defend channel position against direct-to-developer platform disintermediation. For New Entrants and Emerging Players: The gap between premium certified composites and economy-grade particleboard creates white-space opportunity for mid-tier engineered substrates with verified moisture resistance. Target Vietnam's Ho Chi Minh City corridor where residential permit velocity outstrips local supply and import substitution openings favor certified exporters. Pursue white-label supply partnerships with volume fabricators seeking to unbundle hardware procurement rather than competing for end-user specification directly. For Investors and Strategic Acquirers: The window for entry favors automated volume fabricators with bundled multifamily contracts and specialty access-panel engineers with in-house certification capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch for inflection in California embodied-carbon disclosure enforcement, which would accelerate first-mover advantage for manufacturers with verified lifecycle data.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of thermal-break profiles reduces lead-time uncertainty from smelter concentration in specific geographies. |
| In-House Fire-Engineering Capability Buildout | Internal testing protocols circumvent accredited laboratory scarcity and compress certification cycles below 18-month benchmarks. |
| Direct-to-Developer Digital Platform Launch | Project-specific specification tools disintermediate traditional distributors in Phoenix and Atlanta multifamily procurement. |
| REACH-Compliant Composite Substrate Investment | Certified material qualification preserves European market access as ECHA enforcement disqualifies uncertified imports. |
| Regional Distributor Acquisition | Contractor relationship networks in volume construction corridors defend channel position against platform-based disintermediation. |
Study Parameters
Multi-period observation of residential permit issuance, manufacturing capacity migration patterns, and certification timeline data anchored the trend analysis, supplemented by interviews with plant managers at volume fabricators, procurement leads at multifamily developers, distribution channel partners, and technical R&D directors at composite substrate suppliers. Secondary validation drew from customs and trade data, building code amendment filings in California and Florida, EPA regulatory dockets, and SEC filings of publicly traded building-product conglomerates. Bottom-up unit economics and top-down construction spend estimates were triangulated to constrain forecast variance.
Segment-weighting across product type, material substrate, end-user category, and installation configuration shaped the analytical framework. Modeled dimensions included interior versus exterior application, wood versus engineered composite versus metal substrate, residential multifamily versus commercial hospitality versus replacement demand, and pre-hung versus slab versus specialty hardware systems. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules across the projection horizon. Industry-specific forecast inputs incorporated fire-rating certification pipeline data and aluminum smelter operating rate assumptions.
Inputs from regulatory filing databases and construction permit registries were available through the study window; gaps in real-time inventory positioning at distributor level introduce uncertainty bands around short-term volume estimates. Forecasts reflect documented assumptions regarding code adoption timelines and material substitution elasticities. A model refresh is warranted upon material change in California building performance standard enforcement or REACH amendment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Interior Trims Market