
 Automotive Trunk Lid Panel Market | 2026-2036
Automotive Trunk Lid Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Trunk Lid Panel Market Outlook
Modular trunk lid configurations bundling inner panels, outer skins, and hinge reinforcements into pre-assembled modules is broadening procurement options for vehicle assemblers. Magna International leverages its stamping and assembly integration to sustain large-program contracts with North American OEMs. ThyssenKrupp anchors European supply through its hot-forming expertise in high-strength steel closures. Plastic Omnium differentiates via composite trunk solutions that compete on weight reduction against traditional metal architectures.
An automotive trunk lid panel is a stamped or molded closure component forming the rear cargo access surface of a passenger vehicle, typically manufactured from cold-rolled steel, 5xxx/6xxx series aluminum, or glass-fiber-reinforced polymer composites with nominal thickness ranging from 0.6 mm to 1.2 mm depending on structural grade. Its primary function is to seal the luggage compartment while providing crash energy absorption, aerodynamic continuity, and mounting points for lighting, badging, and actuator hardware. Steel retains dominant share among material types due to cost-efficient stamping infrastructure at OEM scale, though aluminum is displacing incumbent metal in premium electric vehicle platforms where lightweight functionality commands margin premiums. Injection molding of thermoplastic composites represents the fastest-expanding manufacturing process segment as Tier-1 suppliers seek cycle-time reductions for low-volume specialty applications.
NHTSA crashworthiness standards and EPA corporate average fuel economy regulations jointly shape trunk lid panel design specifications in the United States, mandating specific stiffness-to-weight ratios and pedestrian impact performance. ECE R29 and EU pedestrian protection directives enforced by ECHA and national type-approval authorities drive European adoption of aluminum and composite material substitutions. China's MIIT passenger vehicle fuel consumption limits and GB standards for occupant protection create parallel compliance obligations for suppliers serving domestic OEMs. Stakeholders must monitor evolving battery-electric vehicle platform architectures where integrated trunk-hatch designs may merge traditional panel categories with liftgate assemblies.
Market Dynamics
Electric vehicle platform architectures are fragmenting traditional closure panel categories, forcing suppliers to engineer hybrid trunk-hatch assemblies that merge cargo sealing with battery protection functions. This structural shift compresses development cycles and rewards suppliers with multi-material bonding capabilities.
Growth Catalysts
- EU Green Deal material efficiency mandates:Closure panel specifications now prioritize recyclable aluminum and polymer composites, accelerating substitution away from conventional steel stampings in European passenger vehicle programs.
- China MIIT fuel consumption limits:Domestic OEMs source lightweight trunk assemblies to meet fleet-average targets, creating sustained pull for high-strength aluminum grades and thermoplastic solutions.
- Modular pre-assembly integration:Vehicle assemblers now procure complete trunk lid modules bundling inner panels, outer skins, and hinge reinforcements, reducing line-side complexity and inventory overhead.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations compress margins for suppliers locked into annual contracts with premium EV platforms, forcing hedging costs or material substitution clauses.
- Hot-forming capacity concentration:High-strength steel closure production clusters in German and Austrian stamping networks, creating geographic supply risk for programs requiring ultra-high-strength grades.
- Composite recycling infrastructure gaps:Glass-fiber-reinforced polymer trunk panels face end-of-life regulatory friction under EU ECHA waste directives, limiting circular economy claims.
Strategic Opportunities
- India PLI scheme localization:Component suppliers can capture import-substitution incentives by establishing aluminum stamping and composite molding capacity for domestic SUV and sedan platforms.
- Integrated smart surface technology:Convergence of capacitive touch sensors and illuminated badging within trunk lid outer panels enables premium feature differentiation for luxury EV segments.
- Direct-to-OEM digital procurement platforms:Tier-1 suppliers bypass traditional distributor networks through B2B configurators that quote modular trunk assemblies by VIN-specific engineering revision.
Industry Challenges
- Multi-material bonding technician scarcity:Adhesive joining of aluminum-to-composite hybrid structures requires specialized process engineers, with training pipelines lagging platform launch timelines.
- Pedestrian impact certification complexity:ECE R29 head-impact testing protocols demand iterative simulation and physical validation cycles that extend program development by 4-6 months.
- Legacy steel stamping asset obsolescence:Suppliers face stranded equipment risk as OEMs shift volume to aluminum-intensive platforms, requiring capital redeployment or facility repurposing decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Trunk Lid Panel Market |
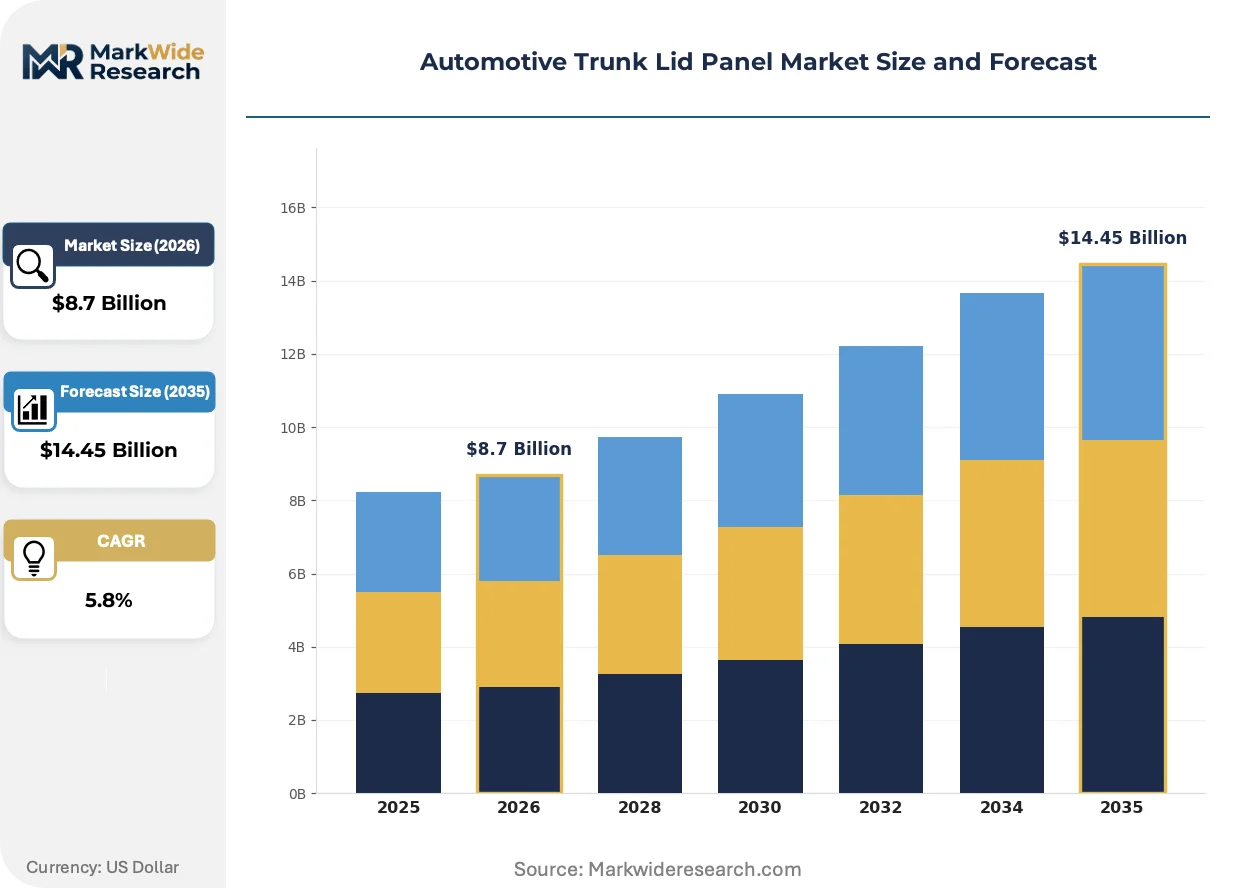
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Composite, Plastic Manufacturing Process: Stamping, Injection Molding, Welding, Thermoforming End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Functionality: Standard, Lightweight, Reinforced, Adaptive |
| Companies Covered | Flex N Gate, Gifu Auto Body Industry, Magna International, Plastic Omnium, ThyssenKrupp, Toyotomi Kiko, UACJ Metal Components, Tata AutoComp Systems, Martinrea International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Trunk Lid Panel Market Strategic Shifts
Active grille shutter integration and aerodynamic optimization are extending into trunk lid design, with engineers treating the rear closure as a controllable airflow surface rather than a static sealing component. This functional expansion demands new sensor and actuator integration capabilities.
Aluminum-intensive trunk lid assemblies are overtaking conventional steel architectures in premium battery-electric vehicle platforms. These structures reduce rear-axle mass to extend driving range. European and Chinese luxury EV OEMs specify 6xxx series extrusions and stampings for outer panels. The technology is overtaking established steel-dominated supply chains by rewarding suppliers with in-house aluminum forming and anodizing capabilities.
EPA corporate average fuel economy standards and NHTSA crashworthiness regulations are tightening in parallel, mandating simultaneous weight reduction and stiffness preservation in closure panels. Suppliers must demonstrate pedestrian head-impact performance while meeting specific torsional rigidity targets. Premium sedan and crossover segments in the United States face the most stringent combined compliance burden, accelerating aluminum and composite material trials.
Fleet procurement centralization among multinational OEMs is consolidating supplier relationships into single-source or dual-source arrangements per platform. Traditional regional sourcing is yielding to global contract structures that demand consistent quality across multiple assembly plants. This concentration is most visible in German and Chinese automotive manufacturing clusters, where platform-sharing agreements amplify purchasing leverage.
Automotive Trunk Lid Panel Market Segmentation
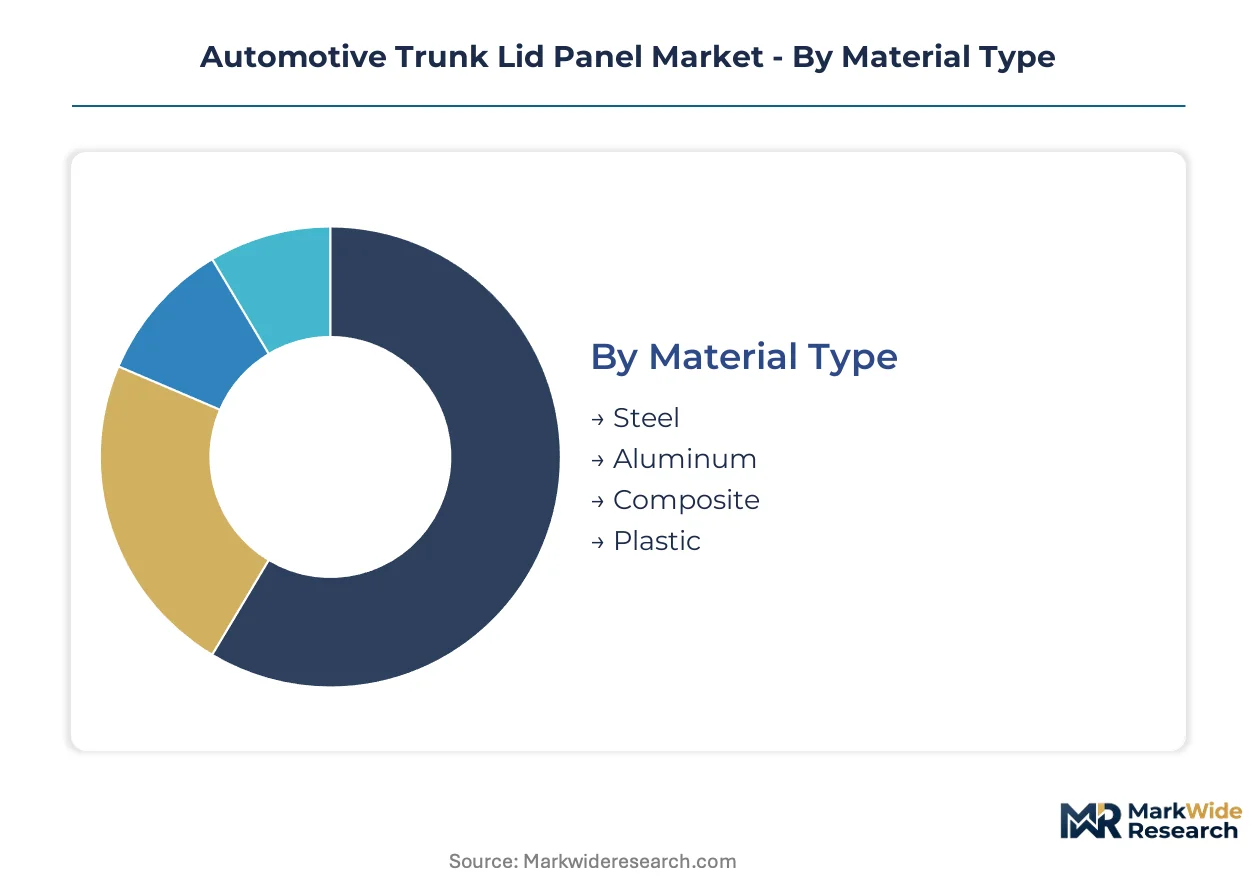
Material selection and manufacturing process choices determine competitive positioning in trunk lid panel procurement. OEM platform strategies fragment demand across cost-optimized steel stampings and premium aluminum-composite hybrids. Segment boundaries blur as electric vehicle architectures merge traditional closure categories with integrated liftgate designs.
Material Type:
Steel dominates mass-market volume while aluminum commands premium EV platforms seeking rear-axle weight reduction.
- Steel:Cold-rolled and hot-formed grades from 0.6 mm to 1.0 mm thickness anchor conventional sedan and SUV programs. German and North American OEMs retain steel-intensive architectures for mid-price segments where stamping infrastructure amortization drives sourcing economics.
- Aluminum:5xxx series stampings and 6xxx series extrusions reduce panel mass by 40-50% versus equivalent steel designs. European luxury EV manufacturers specify aluminum outer skins to meet EU Green Deal fleet efficiency mandates, with Chinese premium brands following MIIT consumption limit trajectories.
- Composite:Glass-fiber-reinforced polymer solutions target low-volume specialty applications and aftermarket lightweight conversions.
- Plastic:Thermoplastic compounds serve cost-sensitive economy segments and integrated spoiler applications where metal forming proves uneconomical.
Today's leader: Steel. Tomorrow's challenger: Aluminum.
Manufacturing Process:
Cycle time and capital intensity separate high-volume stamping from flexible molding alternatives.
- Stamping:Progressive die and transfer press operations process steel and aluminum coils at 60-120 strokes per minute for OEM-scale programs. ThyssenKrupp and Magna International operate concentrated capacity in Germany, Austria, and Michigan serving Detroit Three and premium German OEMs.
- Injection Molding:Thermoplastic composite trunk lids achieve 90-second cycle times versus 15-20 seconds for metal stamping, but eliminate secondary assembly steps for integrated hinge bosses and cable routing channels. Plastic Omnium and Webasto scale this capability for European and Chinese EV platforms.
- Welding:Laser and resistance welding joins inner panel reinforcements to outer skins in modular assembly configurations.
- Thermoforming:Vacuum and pressure forming of thermoplastic sheets serves aftermarket replacement panels and concept vehicle prototyping with minimal tooling investment.
Stamping retains volume dominance. Injection molding climbs fastest on EV platform adoption.
End User:
Procurement centralization concentrates contract leverage among platform-sharing OEM alliances.
- OEMs:Volkswagen Group, Toyota, and Stellantis specify trunk lid modules through global commodity councils that standardize designs across multiple assembly plants. Direct OEM procurement of complete assemblies displaces component-level purchasing in premium electric vehicle programs.
- Tier-1 Suppliers:Magna, Gestamp, and Benteler engineer full-system responsibility for trunk lid modules bundling panels, hinges, actuators, and wiring harnesses. These suppliers amortize development costs across multiple OEM customers sharing common platform architectures.
- Vehicle Assemblers:Contract manufacturers and joint-venture plants in China source pre-assembled trunk modules to minimize line-side complexity and inventory overhead.
- Aftermarket Providers:Independent distributors serve collision repair and restoration markets with certified replacement panels matching OEM corrosion warranties.
OEM direct sourcing expands share. Tier-1 module integration deepens technical barriers.
Functionality:
Regulatory compliance and platform electrification redefine performance specifications beyond basic cargo sealing.
- Standard:Baseline steel stampings with nominal stiffness meet entry-segment cost targets in India, Southeast Asia, and Latin American markets where NHTSA and ECE R29-equivalent regulations permit simpler structures.
- Lightweight:Aluminum-intensive and composite designs address EPA corporate average fuel economy standards and China MIIT consumption limits. BMW and Mercedes-Benz specify lightweight trunk lids for rear-wheel-drive electric sedans where mass reduction extends driving range.
- Reinforced:Ultra-high-strength steel hot-formings and aluminum extrusion reinforcements satisfy NHTSA rear-impact and pedestrian head-impact protocols for US-market crossovers and SUVs.
- Adaptive:Active aerodynamic surfaces with integrated spoiler deployment and capacitive touch activation emerge on luxury EV flagships from Porsche, Lucid, and NIO.
Lightweight functionality captures investment. Adaptive features define next-generation differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive trunk lid panel industry traces its industrial lineage to German cold-rolling innovations and Japanese just-in-time stamping networks established during the 1980s mass-market expansion. These foundational manufacturing clusters continue to influence contemporary supply chain geography despite aluminum and composite material transitions.
Germany
Premium sedan and SUV production from BMW, Mercedes-Benz, and Volkswagen Group sustains demand for aluminum-intensive trunk assemblies. ECE R29 pedestrian protection directives and EU Green Deal material efficiency mandates accelerate substitution away from conventional steel stampings. The Stuttgart and Munich industrial corridors concentrate hot-forming capacity for ultra-high-strength steel closures serving domestic OEMs and export programs.
China
Domestic EV manufacturers including BYD, NIO, and Li Auto specify lightweight trunk modules to extend driving range and satisfy MIIT fleet consumption limits. Dual carbon goals and GB standards for occupant protection create parallel compliance obligations for closure panel suppliers. The Yangtze River Delta and Pearl River Delta manufacturing clusters anchor aluminum stamping and composite molding capacity for both domestic brands and joint-venture platforms.
United States
Detroit Three OEMs and Tesla source trunk lid modules through consolidated procurement structures serving multiple assembly plants. NHTSA crashworthiness standards and EPA corporate average fuel economy regulations jointly shape stiffness-to-weight specifications and pedestrian impact performance. Michigan and Ohio stamping networks retain steel-intensive volume while Kentucky and Texas facilities accommodate aluminum-intensive EV platform ramp-ups.
Japan
Toyota, Honda, and Nissan maintain hybrid trunk-hatch architectures that merge traditional closure categories with integrated liftgate designs. METI energy efficiency guidelines and JIS structural standards influence material selection across kei car and premium export segments. The Aichi and Kanagawa prefectures concentrate Tier-1 supplier engineering centers coordinating multi-material bonding capabilities for next-generation platforms.
India
Maruti Suzuki, Hyundai Motor India, and Tata Motors source cost-optimized steel stampings for entry-segment sedans and compact SUVs. PLI scheme localization incentives attract aluminum stamping and composite molding investments targeting import substitution. The Chennai and Pune automotive clusters host emerging trunk lid module assembly operations serving both domestic consumption and regional export markets.
Automotive Trunk Lid Panel Market Competitive Environment
The competitive structure tilts toward diversified Tier-1 conglomerates with multi-material forming capabilities. Supplier relationships concentrate into single-source or dual-source arrangements per platform as fleet procurement centralization accelerates. Three archetypes dominate: integrated stamping-to-assembly specialists, composite solution innovators, and regional steel-intensive fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for aluminum-intensive EV platform transitions.
Within the diversified Tier-1 tier, Magna International and ThyssenKrupp exemplify integrated stamping-to-assembly capabilities spanning North American and European OEM programs. Plastic Omnium occupies a position among composite solution innovators competing on weight reduction against traditional metal architectures. Tata AutoComp Systems anchors the emerging market specialist archetype with established presence in Indian automotive manufacturing clusters. Flex N Gate represents North American-focused stamping capacity serving Detroit Three volume programs. Gifu Auto Body Industry and Toyotomi Kiko exemplify Japanese precision fabricators with concentrated relationships with domestic OEM keiretsu structures.
| Leading Market Players |
|---|
| Flex N Gate |
| Gifu Auto Body Industry |
| Magna International |
| Plastic Omnium |
| ThyssenKrupp |
| Toyotomi Kiko |
| UACJ Metal Components |
| Tata AutoComp Systems |
| Martinrea International |
| Others |
Value Chain & Pricing Dynamics
Captive aluminum forming capacity at Tier-1 suppliers anchors both supply security and pricing leverage for OEMs sourcing lightweight trunk lid modules. This integration pattern concentrates procurement power among stamping-to-assembly specialists serving premium EV platforms in Germany, China, and the United States.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aluminum-intensive EV modules from steel stampings and thermoplastic economy solutions. Price differentiation rests on certification grade for pedestrian impact performance and volume scale amortizing tooling investment. Cost compression in standard steel tiers is intensifying because legacy stamping asset obsolescence forces capacity consolidation. Fleet procurement centralization renders OEM commodity councils least price-sensitive, while aftermarket distributors face margin pressure from certified replacement panel requirements.
Supply Chain Analysis
Dual-sourcing requirements embedded in OEM platform contracts mandate multi-supplier qualification for aluminum stampings and composite molding capacity. Geographic supply concentration centers on Germany, China, and Mexico for stamping operations, with Austria and Japan anchoring hot-forming expertise. Raw material dependencies draw from LME aluminum contracts, cold-rolled steel coils, and glass-fiber-reinforced polymer resins. Single-source vulnerability concentrates in ultra-high-strength steel grades requiring specialized press capacity. Distribution runs through direct OEM procurement platforms bypassing traditional Tier-2 distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is shifting toward aluminum-intensive trunk assemblies with integrated hinge reinforcement and smart surface capability.
For Market Incumbents: Lock in long-term aluminum supply offtake agreements to hedge LME price volatility threatening margin stability on premium EV contracts. Deepen captive anodizing and multi-material bonding capabilities before technician scarcity widens. Defend against composite substitution by demonstrating end-of-life recyclability under EU ECHA waste directives. For New Entrants and Emerging Players: Launch via direct-to-OEM digital procurement platforms that quote modular trunk assemblies by VIN-specific engineering revision. Target India's PLI scheme localization incentives for aluminum stamping capacity serving Maruti Suzuki and Tata Motors SUV platforms. White-space exists in adaptive aerodynamic surfaces with integrated spoiler deployment for luxury EV flagships. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap stamping specialists with dormant aluminum forming assets because OEM platform consolidation is compressing supplier counts per program. Long-term viability favors suppliers with demonstrated multi-material bonding and modular assembly integration. Watch MIIT consumption limit enforcement trajectories as the inflection signal for aluminum substitution velocity in China.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Bonding Capability Investment | Adhesive joining expertise secures hybrid aluminum-composite contracts from BMW and NIO. |
| Modular Pre-Assembly Integration | Complete trunk lid modules reduce line-side complexity for Volkswagen Group and Stellantis plants. |
| Aluminum Forming Capacity Expansion | Captive 6xxx series extrusion capacity satisfies EU Green Deal material efficiency mandates. |
| Smart Surface Technology Development | Capacitive touch and illuminated badging differentiation commands premium pricing from Lucid. |
| Geographic Manufacturing Footprint | Kentucky and Texas facilities accommodate Detroit Three aluminum-intensive EV platform ramp-ups. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from stamped component suppliers, and EU type-approval authority documentation. Bottom-up program-level volume estimates and top-down market sizing triangulated to segment-weighted outputs.
Segment-weighting across material type, manufacturing process, and vehicle class dimensions structured the analytical framework across the analysis window. CAGRs derived from production volume trajectories, content-per-vehicle trends, and platform electrification schedules. Industry-specific inputs included aluminum price forecasting curves and pedestrian impact certification cycle timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt LME aluminum spikes or accelerated EU ECHA composite recycling mandates. Deviation in China MIIT enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market